
 China Digital Transformation Market | 2026-2036
China Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
China Digital Transformation Market Insights
Smart manufacturing adoption is shifting from pilot programs to full-scale deployment across Chinese industrial bases. Huawei Technologies leverages its 5G infrastructure portfolio to dominate private network installations for factory automation. Alibaba Group anchors cloud-based ERP penetration among mid-market manufacturers through proprietary platforms. Tencent Holdings competes in industrial IoT middleware by integrating WeChat ecosystem connectivity into shop-floor systems.
Digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, and connected sensor networks into enterprise operational technology stacks, typically governed by latency thresholds below 10 milliseconds for real-time process control and data throughput exceeding 10 Gbps in edge computing nodes. Its primary commercial purpose is to replace manual decision layers with algorithmic optimization across production, logistics, and customer interaction workflows. Artificial Intelligence commands the deepest margin pools as semiconductor constraints elevate pricing for training infrastructure, while Hybrid Cloud deployment is expanding fastest as SOEs reconcile data sovereignty mandates with elasticity requirements. Cybersecurity solutions face structural supply pressure from MIIT certification timelines that delay vendor qualification.
MIIT enforces GB standards compliance and dual carbon goals that reshape enterprise IT procurement toward energy-efficient architectures. SAMR scrutinizes cloud pricing transparency and data localization practices, tightening market access for uncertified foreign platforms. NMPA intersects with digital transformation through medical device software validation rules that delay healthcare AI deployment. Stakeholders must monitor regulatory divergence between national standards and municipal implementation timelines in tier-one versus tier-three cities.
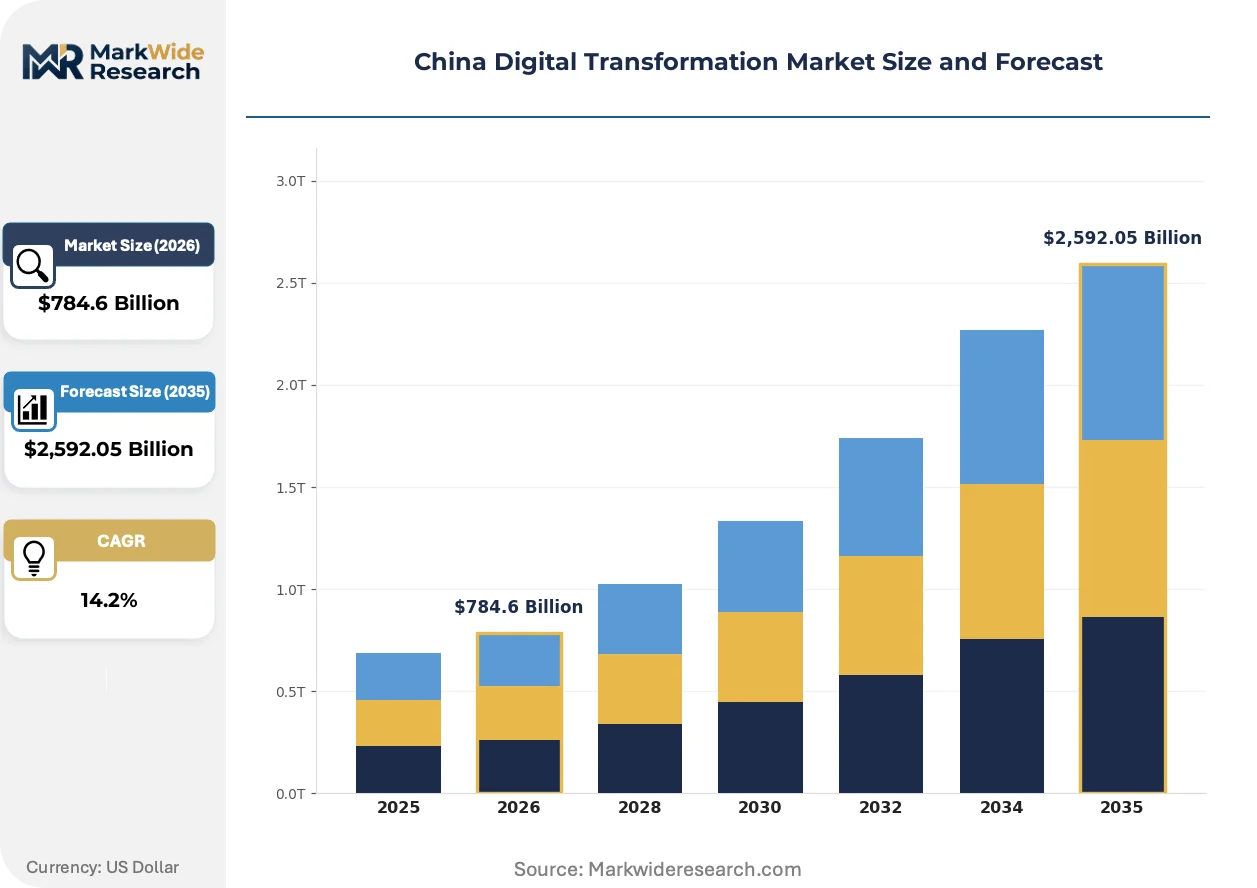
Market Dynamics
MIIT's tightening GB standards compliance and dual carbon mandates are forcing state-owned enterprises to accelerate replacement of legacy operational technology stacks with energy-efficient architectures, compressing procurement cycles and elevating vendor qualification barriers.
Growth Catalysts
- Dual Carbon Policy Framework:National emissions targets mandate SOE facility upgrades, creating captive demand for smart metering and process optimization systems.
- Yangtze River Delta Cluster Concentration:Manufacturing density around Shanghai and Hangzhou generates network effects that lower deployment costs for connected factory infrastructure.
- Edge Computing Latency Thresholds:Sub-10 millisecond process control requirements pull private 5G network investment into automotive and electronics assembly lines.
Market Restraints
- Semiconductor Supply Concentration:Training infrastructure for AI workloads faces input bottlenecks from concentrated advanced chip fabrication capacity.
- MIIT Certification Timelines:Vendor qualification delays for cybersecurity solutions extend sales cycles and freeze procurement decisions.
- Legacy System Technical Debt:Brownfield manufacturing sites require costly protocol translation layers to integrate IIoT sensor networks with existing SCADA investments.
Strategic Opportunities
- Tier-Three City Underpenetration:Interior provinces lack cloud-based ERP adoption among mid-market manufacturers, creating whitespace for platform providers.
- Healthcare AI Regulatory Tailwind:NMPA medical device software validation rules, once cleared, will unlock diagnostic imaging and patient monitoring deployments.
- Hybrid Cloud Convergence:Data sovereignty mandates are converging with elasticity requirements, positioning domestic operators to capture SOE workload migration.
Industry Challenges
- Industrial Data Science Talent Scarcity:Shop-floor algorithm deployment requires scarce cross-trained engineers capable of bridging OT and IT domains.
- Integration Complexity with Proprietary Protocols:Equipment from disparate eras lacks standardized APIs, forcing custom middleware development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Digital Transformation Market |
| Market Size in 2026 | $784.6 Billion |
| Market Size in 2035 | $2,592.05 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, IoT, Artificial Intelligence, Blockchain End User: Retail, Financial Services, Healthcare, Manufacturing Deployment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Solution: Data Analytics, Cybersecurity, ERP Solutions, CRM Software |
| Companies Covered | Huawei Technologies, Alibaba Group, Tencent Holdings, ZTE Corporation, Baidu Inc., Xiaomi Corporation, Lenovo Group, Inspur Group, Digital China Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Digital Transformation Market Trends and Innovations
Digital twin architectures and sovereign cloud infrastructure are actively displacing conventional enterprise software licensing models, while regulatory pressure on carbon disclosure accelerates sensor network deployment across heavy industry.
Digital twin simulation platforms are converging with real-time production data streams to compress commissioning timelines for new manufacturing lines. Automotive and battery producers in the Yangtze Delta are adopting these systems fastest, using virtual commissioning to reduce physical prototype iterations. The technology is converging with predictive maintenance algorithms to shift capital allocation from reactive spare parts inventory toward software subscriptions.
MIIT's GB standards compliance requirements are tightening data localization and cross-border transfer rules for industrial platforms. Cloud service providers must now certify edge node configurations under national encryption protocols before qualifying for SOE procurement. Manufacturing execution system vendors are responding by establishing wholly-owned data center operations in provincial capitals rather than relying on third-party hosting.
State-owned enterprise buyers are consolidating vendor relationships around full-stack platform providers capable of delivering integrated 5G, cloud, and AI capabilities. Discrete software licensing is losing ground to consumption-based pricing tied to connected device counts or data throughput volumes. This pattern is most visible in steel and chemical sectors, where procurement committees now prioritize single-source accountability over best-of-breed component assembly.
China Digital Transformation Market Segmentation
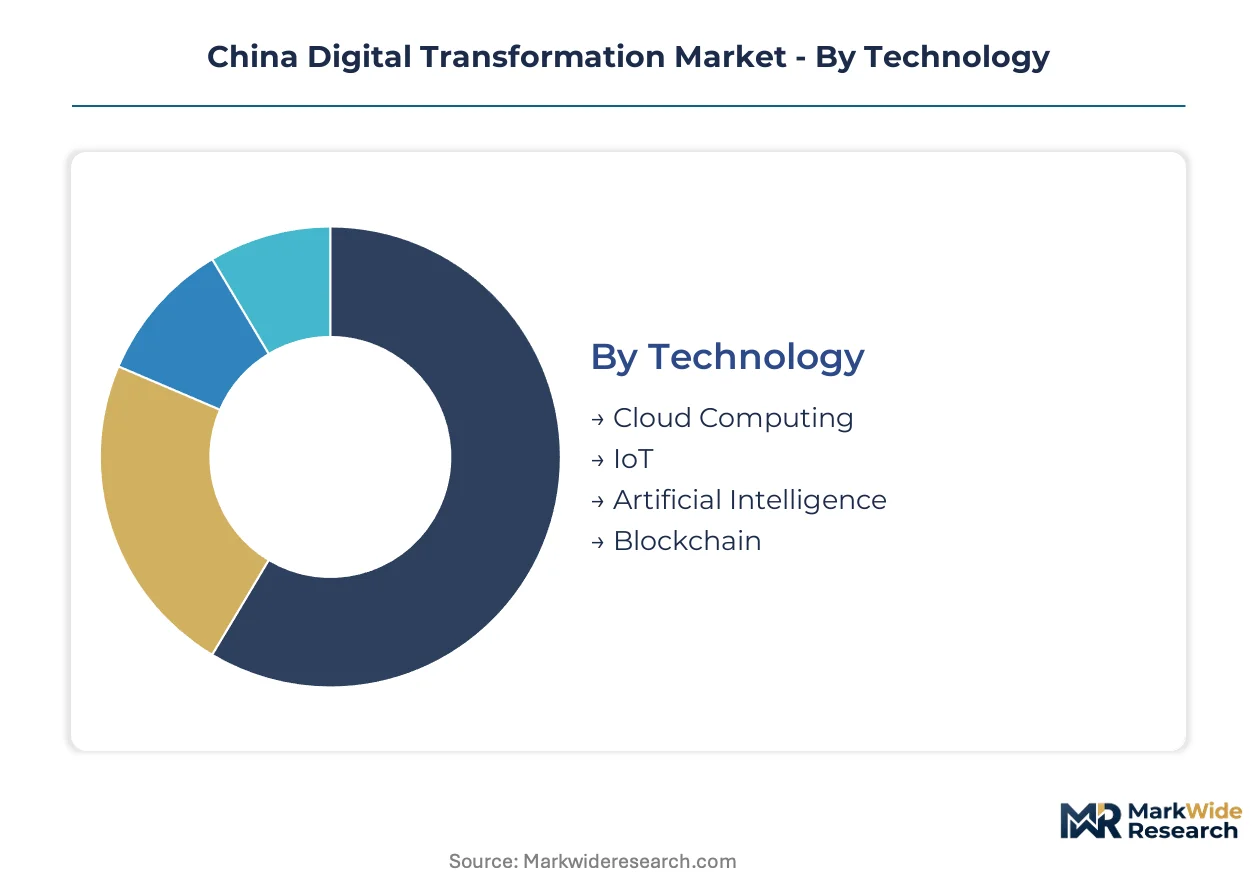
Technology choices in China's digital transformation market cluster around latency requirements and data sovereignty mandates. End-user concentration in state-owned manufacturing and financial services creates procurement patterns that favor full-stack domestic vendors.
Technology:
Cloud infrastructure commands the volume base while AI training infrastructure extracts premium margins from semiconductor-constrained supply.
- Cloud Computing:Elastic compute and storage services form the foundational layer for SOE workload migration. Demand concentrates in Yangtze River Delta financial services and Shanghai-based manufacturing headquarters driven by MIIT data localization mandates.
- Artificial Intelligence:Training clusters and inference accelerators require advanced process node semiconductors facing import restrictions. Deployment concentrates in Beijing and Shenzhen autonomous vehicle R&D centers and NMPA-regulated medical imaging pipelines.
- IoT:Industrial sensor networks and connected device management platforms.
- Blockchain:Supply chain traceability and trade finance verification systems.
Mature deployment sits with Cloud Computing. Newer deployment is concentrated in Artificial Intelligence.
End User:
State-directed capital allocation shapes demand concentration across sectors with diverging regulatory exposure.
- Manufacturing:Smart factory deployments integrate 5G private networks with predictive maintenance algorithms. SOE steel and chemical producers in Hebei and Shandong drive replacement cycles compressed by dual carbon deadlines.
- Financial Services:Core banking modernization and real-time risk analytics require sub-10 millisecond latency. State-owned banks in Shanghai and Beijing prioritize hybrid architectures reconciling PBoC data sovereignty rules with elasticity demands.
- Retail:Omnichannel inventory management and consumer analytics platforms.
- Healthcare:Electronic medical records and diagnostic imaging AI facing NMPA validation delays.
Procurement maturity varies sharply: Manufacturing leads in connected infrastructure deployment. Healthcare AI awaits regulatory clearance for diagnostic algorithms.
Deployment:
Data gravity and compliance requirements fragment workload placement across architectural models.
- Hybrid Cloud:Workload portability between sovereign domestic nodes and burst capacity satisfies SOE governance requirements. Steel and automotive producers in Jiangsu and Zhejiang adopt this model fastest to reconcile MIIT encryption mandates with seasonal demand spikes.
- Private Cloud:Dedicated infrastructure for classified government and defense workloads.
- Public Cloud:Elastic development and testing environments for mid-market software vendors.
- On-Premises:Legacy SCADA integration and air-gapped operational technology systems.
Expansion is steepest in Hybrid Cloud as procurement committees consolidate vendor accountability. On-Premises retention persists in brownfield industrial sites with protocol translation costs.
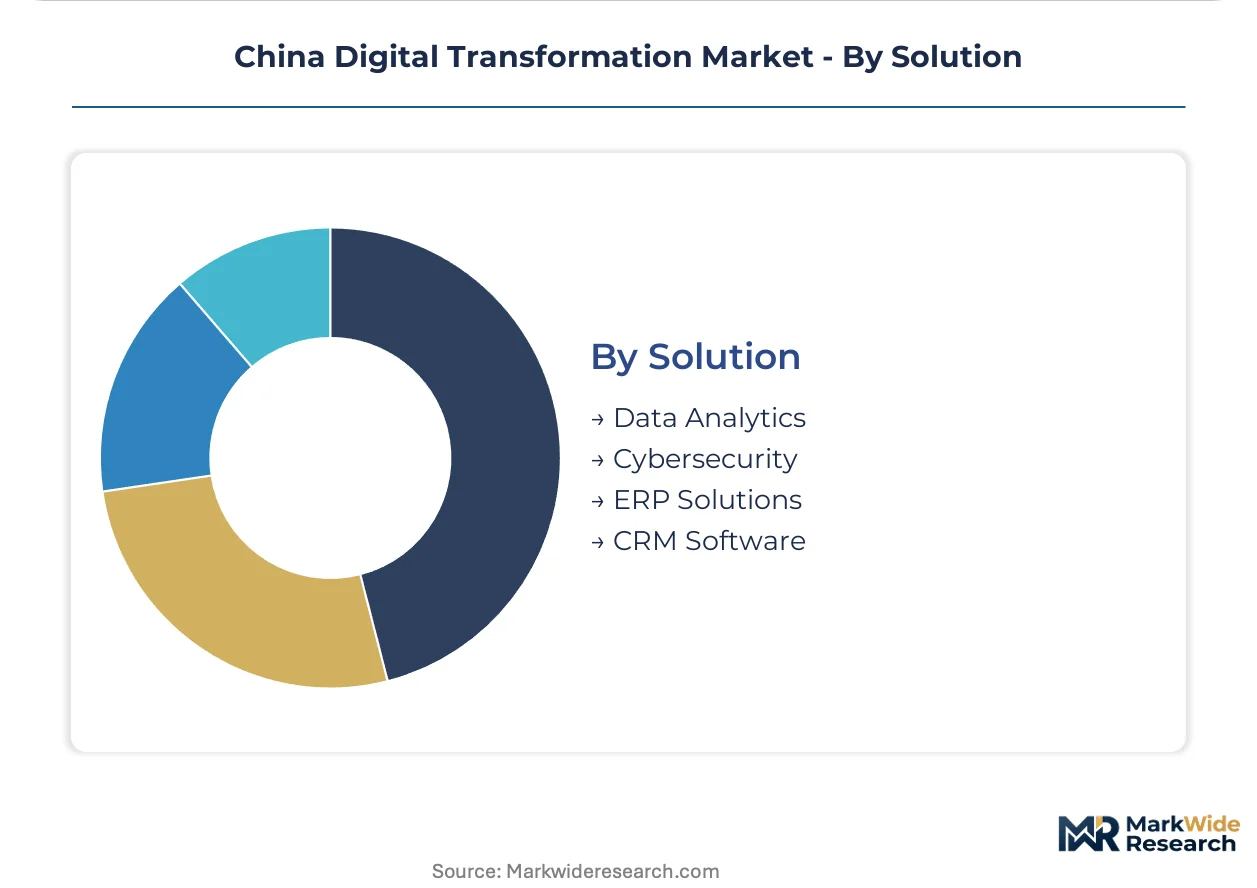
Solution:
Platform consolidation trends favor integrated suites over point solutions in SOE procurement cycles.
- ERP Solutions:Core financial and supply chain modules anchor enterprise software spending. Mid-market manufacturers in tier-three interior provinces present whitespace as cloud-native platforms displace legacy client-server installations.
- Cybersecurity:MIIT certification requirements delay vendor qualification and extend sales cycles.
- Data Analytics:Real-time production optimization and customer intelligence platforms.
- CRM Software:Consumer engagement and loyalty management systems for retail chains.
ERP Solutions retain the deepest incumbent position. Cybersecurity is gaining share fastest as GB standards compliance tightens procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta Economic Zone concentrates digital transformation investment through Shanghai's Lingang Special Area tax incentives and Hangzhou's cross-border data pilot zones.
United States
Federal cloud modernization mandates and CHIPS Act semiconductor subsidies accelerate enterprise AI infrastructure deployment. NIST cybersecurity frameworks tighten procurement criteria for critical infrastructure operators. Silicon Valley and Austin tech corridors anchor hyperscaler data center expansion and autonomous vehicle R&D clusters.
Germany
Industrial Mittelstand export competitiveness demands predictive maintenance and digital twin adoption across automotive supply chains. EU AI Act risk classification rules delay high-stakes manufacturing algorithm deployments. Stuttgart and Munich engineering hubs concentrate Industry 4.0 platform integration for machinery exporters.
Japan
Aging workforce demographics force robotics and process automation substitution in precision manufacturing. METI's Society 5.0 roadmap mandates data interoperability standards across keiretsu supply networks. Nagoya and Osaka industrial zones lead connected factory deployments for automotive and electronics producers.
South Korea
Memory semiconductor dominance funds captive AI training infrastructure for chaebol electronics divisions. K-ISMS certification requirements restrict foreign cloud platform access to financial services. Seoul Capital Area and Busan-Ulsan corridors concentrate private 5G network installations for shipbuilding and display manufacturing.
India
PLI scheme incentives for electronics manufacturing pull ERP and IoT adoption into contract assembly operations. RBI data localization directives fragment cloud architecture choices for fintech and banking workloads. Bengaluru and Hyderabad tech clusters anchor SaaS development and GCC captive centers serving multinational digital transformation programs.
China Digital Transformation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack platform providers capturing SOE procurement consolidation while point-solution vendors defend mid-market niches. The vendor base concentrates around three strategic archetypes: infrastructure-integrated conglomerates, cloud-native software platforms, and vertical-specific system integrators. Dominant competitive moves include strategic partnerships binding 5G equipment to cloud workload commitments and backward integration into sovereign data center operations.
Among China-based technology conglomerates, Huawei Technologies, Alibaba Group, and Tencent Holdings exemplify the infrastructure-integrated archetype. Huawei occupies a position representing private 5G network and edge computing hardware dominance. Alibaba exemplifies cloud-native platform consolidation through ERP and data analytics bundling. Tencent sits within industrial IoT middleware competition, leveraging ecosystem connectivity integration. These three anchors collectively represent the full-stack accountability SOE procurement committees now prioritize over component assembly.
| Leading Market Players |
|---|
| Huawei Technologies |
| Alibaba Group |
| Tencent Holdings |
| ZTE Corporation |
| Baidu Inc. |
| Xiaomi Corporation |
| Lenovo Group |
| Inspur Group |
| Digital China Group |
| Others |
Pricing and Supply Chain Analysis
Industrial data science talent scarcity in the Yangtze River Delta widens pricing-tier spreads between premium algorithm-deployment contracts and commoditized cloud-storage subscriptions. Labor-cost differentials between Shenzhen's AI engineering clusters and tier-three interior provinces compress margins for mid-market ERP implementations while inflating premiums for sovereign-cloud edge deployments.
Pricing Analysis
Short lead-time premiums dominate procurement decisions as MIIT certification delays force SOEs to pay surcharges for pre-qualified cybersecurity vendors. Pricing stratifies across certified-premium, standard-compliance, and economy-tier service levels based on GB standards adherence and data-sovereignty guarantees. Cost compression in economy-tier cloud storage intensifies because hyperscalers sacrifice margin to capture SOE workload migration. Mid-market manufacturers in Hebei and Shandong exhibit highest price sensitivity, while state-owned banks in Shanghai prioritize single-source accountability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for edge-computing hardware refurbishment concentrate in Shenzhen and Dongguan, extending equipment lifecycles for brownfield factory deployments. Advanced-node semiconductor fabrication draws from Taiwan, South Korea, and domestic Yangtze Memory facilities. Supply chain risk centers on single-source vulnerability for AI training accelerators facing export-control restrictions. Distribution runs through provincial-capital data center operators rather than third-party hosting to satisfy MIIT encryption mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
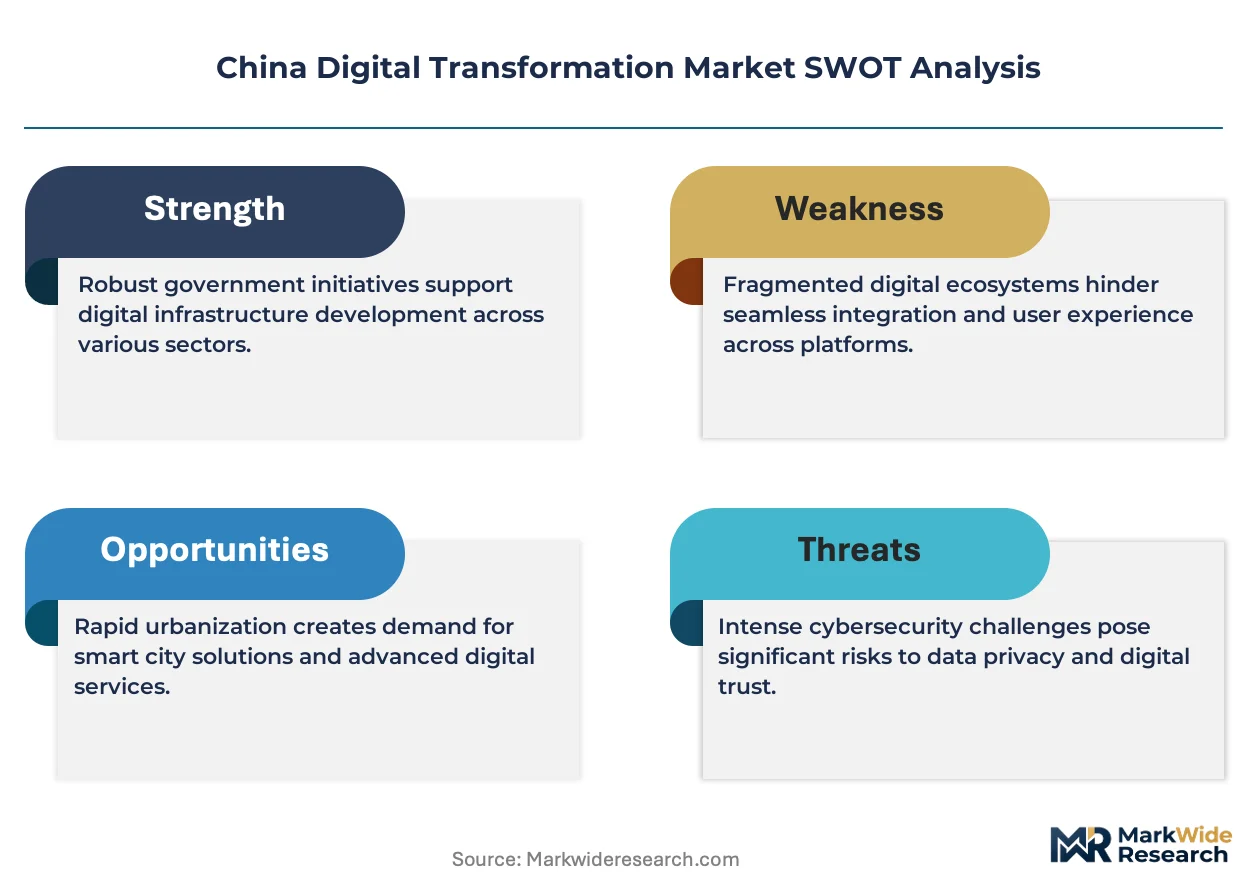
China's digital transformation market reads as a cost-of-compliance story where MIIT's GB standards certification creates a barrier-to-entry moat rewarding vendors with pre-qualified sovereign-cloud infrastructure.
For Market Incumbents: Hedge against margin erosion in commoditized cloud storage by deepening backward integration into proprietary edge-node manufacturing. Capture SOE procurement consolidation by bundling 5G private networks with consumption-based AI training subscriptions, neutralizing emerging threats from vertical-specific system integrators. For New Entrants and Emerging Players: NMPA medical device software validation rules in China open a window for diagnostic-imaging AI specialists to capture healthcare whitespace ahead of incumbent platform bundling. Target tier-three interior provinces lacking cloud-native ERP adoption, penetrating through channel partnerships with provincial SOE procurement committees rather than direct enterprise sales. For Investors and Strategic Acquirers: Re-rating potential sits with full-stack platform providers given SOE vendor-consolidation tailwinds accelerating single-source accountability premiums. Long-term viability favors infrastructure-integrated conglomerates with captive 5G equipment and sovereign data center operations. Monitor MIIT certification timeline compression as inflection indicator for cybersecurity vendor qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Establishment | MIIT encryption mandates require wholly-owned provincial operations rather than third-party hosting. |
| 5G Private Network Integration | Sub-10 millisecond latency requirements pull automotive and electronics assembly line investments. |
| Platform Consolidation Partnership | SOE procurement committees prioritize full-stack accountability over best-of-breed component assembly. |
| Digital Twin Architecture Deployment | Virtual commissioning compresses timelines for Yangtze Delta automotive and battery production lines. |
| Healthcare AI Regulatory Clearance | NMPA validation unlocks diagnostic imaging and patient monitoring algorithm deployment pipelines. |
Research Methodology
Document review covered MIIT policy circulars, SAMR enforcement notices, and NMPA medical device guidance, complemented by interviews with SOE procurement directors, cloud platform engineers, industrial IoT integration specialists, and cybersecurity certification auditors. Secondary validation drew from hyperscaler capex disclosures, provincial SOE annual procurement reports, and GB standards technical documentation. Bottom-up deployment estimates triangulated against top-down digital economy spending projections from national statistical yearbooks.
Segmented outputs across technology, end-user, deployment model, and solution type dimensions fed into elasticity-adjusted growth curves across the projection horizon. CAGRs derived from historical SOE IT spending patterns, MIIT mandate implementation timelines, and semiconductor supply-constraint scenarios. Industry-specific inputs included dual-carbon deadline compression effects on steel and chemical sector replacement cycles, plus private 5G network penetration rates in automotive assembly corridors.
The model assumes a particular technology adoption path; alternative pathways for sovereign-cloud edge computing would alter the outlook if MIIT relaxes data-localization mandates. Forecasts reflect assumptions about GB standards enforcement consistency across provincial implementation timelines. Practitioners should monitor NMPA medical device software validation queue clearance rates and MIIT cybersecurity certification backlog durations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Global Design Thinking Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Canada Digital Transformation Market
Digital Transformation
Retail Digital Transformation Market
Digital Transformation
Digital Transformation in Healthcare Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Digital Transformation in Supply Chain Market
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Australia and New Zealand Digital Transformation Market
Digital Transformation
MENA Digital Transformation Market
Digital Transformation
Indonesia Digital Transformation Market
Digital Transformation
Workspace Transformation Market