
 Automotive Ignition Coil Connector Market | 2026-2036
Automotive Ignition Coil Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ignition Coil Connector Market Analytics
Commercial vehicle electrification is expanding demand for high-voltage-compatible ignition coil connectors in hybrid powertrains. TE Connectivity leverages its sensor-connector integration expertise to anchor positions in European OEM supply chains. Bosch competes through in-house production of ignition system modules that bundle connectors with coil assemblies. Yazaki Corporation dominates Asian sourcing networks for sealed connector variants used in compact engine bays.
An automotive ignition coil connector is an electromechanical interface that transmits high-voltage pulses from the ignition coil to the spark plug, typically engineered with temperature-resistant plastics, conductive metal terminals, and silicone or fluorocarbon rubber seals to withstand thermal cycling above 150°C and exposure to engine fluids. Its primary purpose is ensuring reliable electrical continuity while preventing moisture ingress and electromagnetic interference in combustion engine architectures. Sealed connectors lead material selection trends as EPA Tier 3 and Euro 6 emission standards intensify demands for vacuum integrity and thermal endurance in pressurized engine compartments. Plastic and composite materials represent the fastest-growing material category as manufacturers substitute metal housings to reduce weight and resist galvanic corrosion in start-stop systems.
Federal EPA Tier 3 standards and California Air Resources Board frameworks mandate reduced cold-start emissions, forcing connector redesigns for faster coil saturation and improved spark consistency. NHTSA safety protocols and ISO 8092 road-vehicle electrical standards govern vibration resistance and pin retention forces, shaping qualification requirements for Tier-1 suppliers. Stakeholders must monitor the tension between extended ICE production timelines and electrification commitments when calibrating connector portfolio durability against platform volume forecasts.
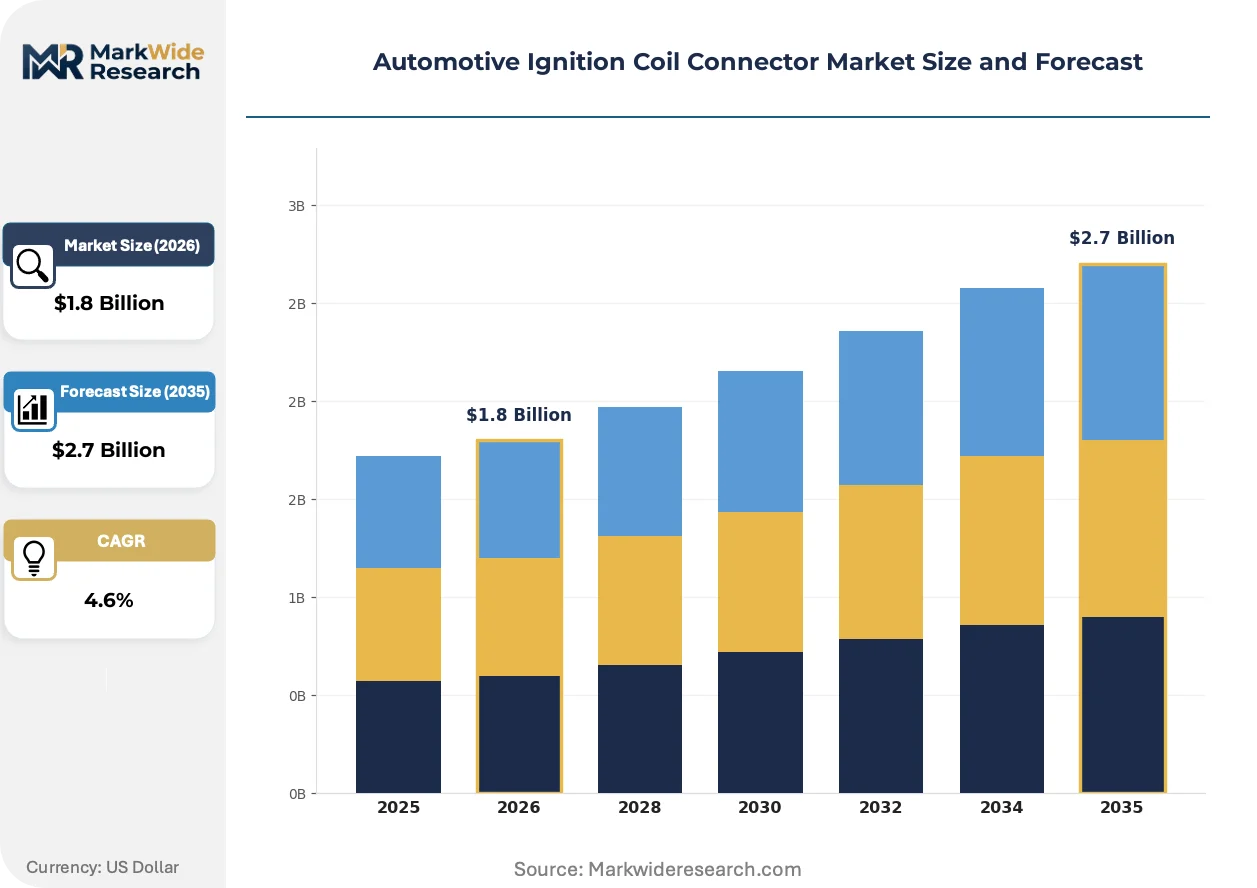
Market Dynamics
EPA Tier 3 and Euro 6 emission mandates are forcing connector redesigns for faster coil saturation, while commercial vehicle electrification creates parallel demand for high-voltage-compatible variants in hybrid architectures.
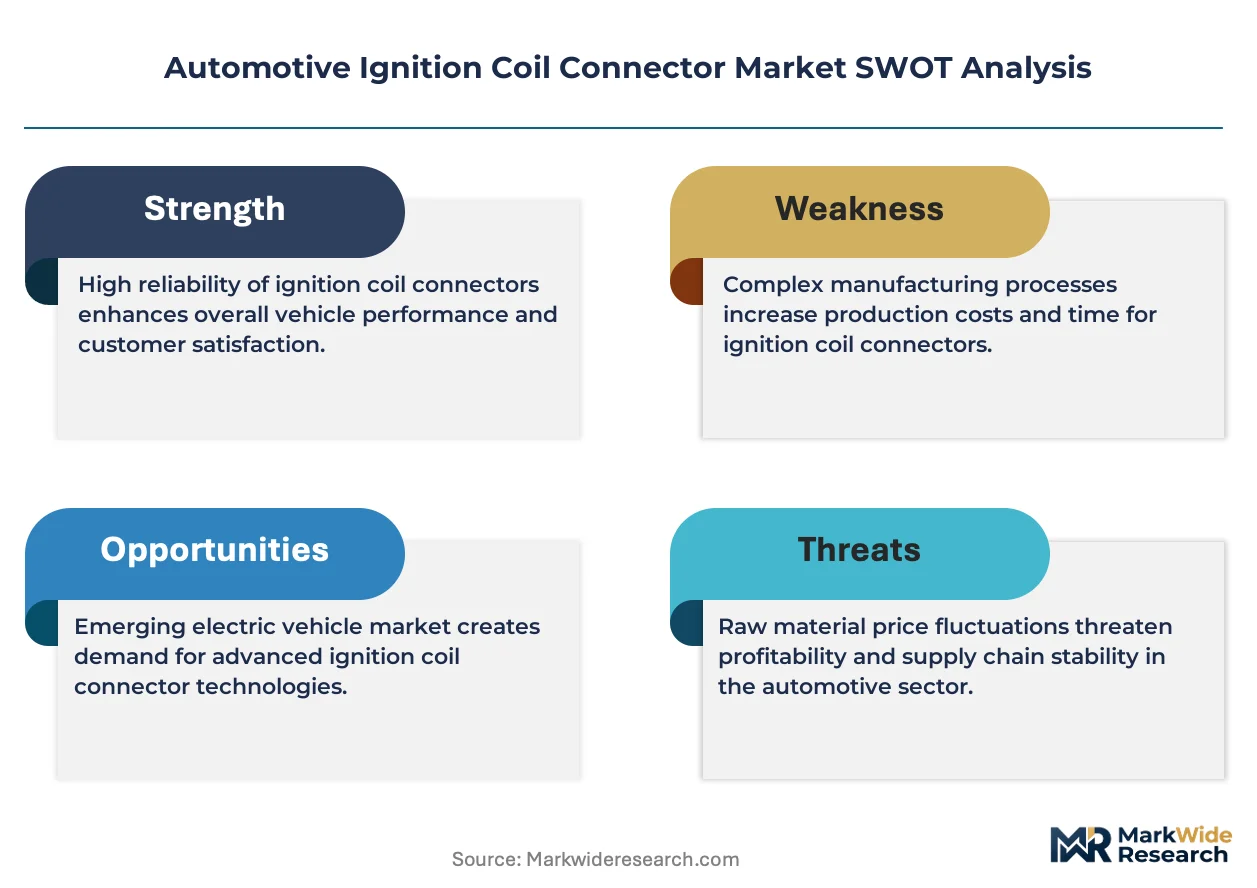
Growth Catalysts
- Commercial Vehicle Electrification:Heavy-duty hybrid powertrains require ignition coil connectors rated for elevated voltage tolerances, expanding addressable demand beyond conventional passenger car applications.
- EPA Tier 3 Compliance:Cold-start emission reduction mandates necessitate sealed connectors with improved thermal cycling performance above 150°C in pressurized engine compartments.
- Stuttgart Supplier Corridor:Germany's concentrated automotive supplier ecosystem accelerates qualification cycles and reduces time-to-market for new connector platforms.
Market Restraints
- Fluorocarbon Rubber Cost Volatility:Specialized sealing materials face price pressure from petrochemical feedstock fluctuations, compressing margin structures for sealed connector variants.
- Asian Sourcing Concentration:Yazaki-dominated supply networks for compact engine bay variants create single-source vulnerability for OEMs seeking geographic diversification.
- ICE Platform Volume Uncertainty:Extended internal combustion engine timelines clash with electrification commitments, complicating long-term capacity planning and tooling amortization.
Strategic Opportunities
- Start-Stop System Penetration:Plastic and composite connector housings gain preference over metal in frequent-cycling applications, opening substitution-driven volume expansion.
- Sensor-Connector Integration:Convergence of ignition timing sensors with coil connectors enables value-added module architectures for European OEM supply chains.
- Aftermarket Channel Digitization:E-commerce platforms for replacement connectors bypass traditional distributor markups in North American independent repair segments.
Industry Challenges
- ISO 8092 Vibration Qualification:Pin retention force testing under multi-axis vibration consumes 18-24 month certification timelines, delaying new product introductions.
- Legacy Harness Compatibility:Electrified powertrain retrofits require adapter interfaces for existing coil connector footprints, adding integration complexity and BOM expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ignition Coil Connector Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Short Connector, Long Connector, Sealed Connector, Unsealed Connector Material: Plastic, Metal, Rubber, Composite Emission Standard: Euro 6, Euro 5, EPA Tier 3, EPA Tier 2 End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | TE Connectivity, Delphi Technologies, Molex LLC, Sumitomo Electric Industries, Yazaki Corporation, Aptiv PLC, Bosch, Denso Corporation, Standard Motor Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ignition Coil Connector Market Evolving Landscape
Material substitution and regulatory tightening are converging to reshape connector architectures, with weight reduction and electromagnetic compatibility emerging as simultaneous design imperatives across combustion and hybrid platforms.
High-temperature thermoplastic housings are displacing metal and conventional plastics in ignition coil connectors. OEMs adopting start-stop systems specify these materials for their resistance to galvanic corrosion and thermal fatigue. This material shift is decentralizing production tooling investments away from traditional metal-stamping supply chains toward injection molding specialists.
California Air Resources Board frameworks now mandate faster catalyst light-off strategies that compress ignition timing tolerances. Connector designs must maintain signal integrity under tighter electromagnetic interference constraints. Heavy-duty diesel applications in the US Southwest face the most acute redesign pressure as fleets retrofit for compliance.
Consolidated procurement of ignition system modules—bundling coils, connectors, and control electronics—is displacing discrete component sourcing. Tier-1 suppliers capture specification authority previously held by connector specialists. This pattern concentrates most visibly in German premium OEM supply chains where module integration reduces assembly line complexity.
Automotive Ignition Coil Connector Market Segmentation
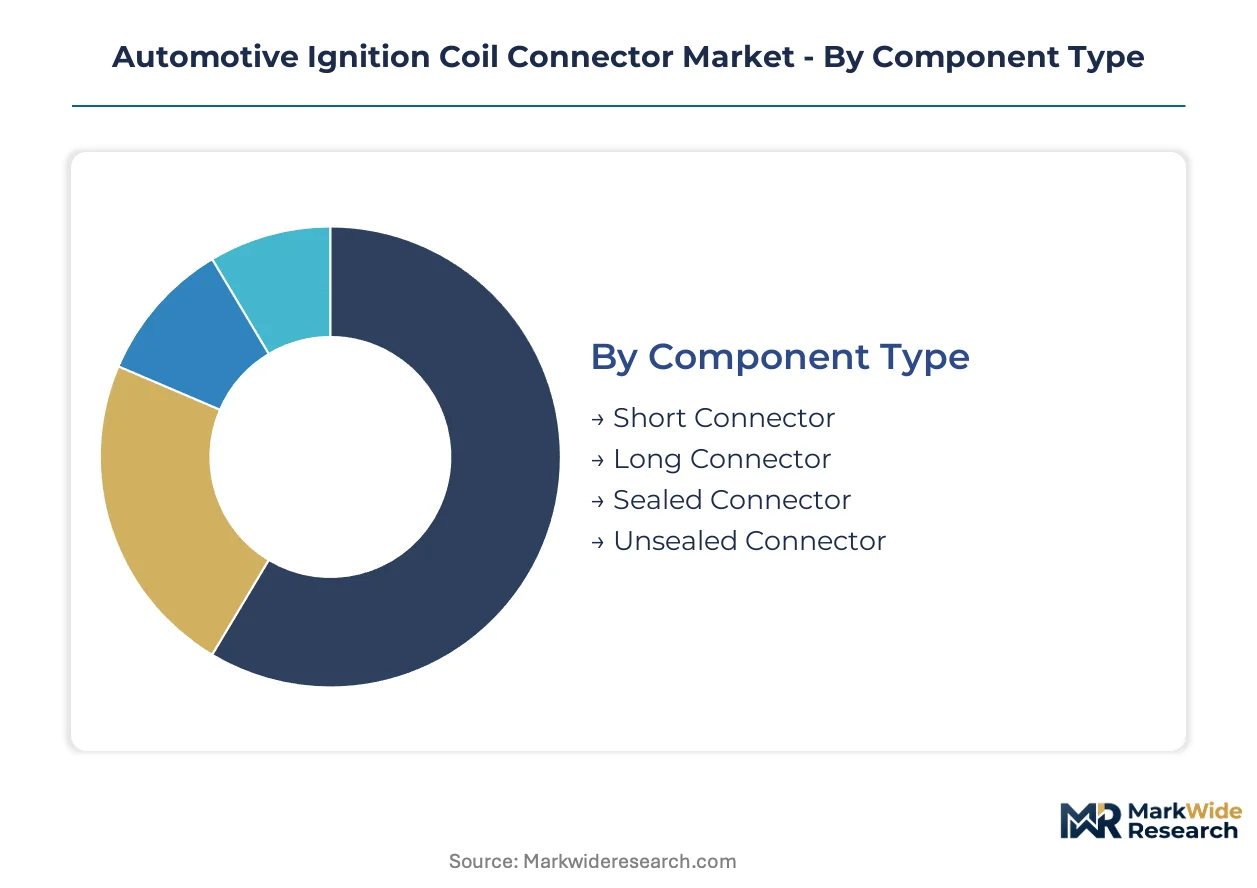
Connector specification diversity reflects the tension between legacy ICE platform maintenance and electrified powertrain retrofit requirements. Upgrade cycles for emission compliance and hybrid integration drive replacement demand across component architectures.
Component Type:
Replacement-cycle timing varies by connector architecture, with sealed variants commanding longer service intervals but higher upfront specification costs.
- Short Connector:Compact terminal housing designed for confined engine bay layouts with reduced wire lead lengths. Passenger car applications in Germany's Stuttgart supplier corridor favor these variants for transverse-mounted powertrains where packaging density limits physical envelope. EPA Tier 3 catalyst light-off strategies accelerate refresh rates as thermal cycling tolerance requirements tighten.
- Sealed Connector:Silicone or fluorocarbon rubber-sealed interface engineered for vacuum integrity above 150°C thermal exposure. Heavy-duty hybrid powertrains in commercial vehicle fleets specify these for pressurized engine compartments where moisture ingress protection is non-negotiable.
- Long Connector:Extended wire lead configuration accommodating longitudinal engine architectures with remote coil mounting.
- Unsealed Connector:Open-terminal design retained in cost-sensitive aftermarket replacement and legacy platform maintenance.
Sealed connectors sit at the top of the volume ranking, with short connectors climbing the fastest.
Material:
Cost tier stratification separates premium thermal-grade compounds from commodity-grade alternatives in procurement specifications.
- Plastic:High-temperature thermoplastic housing injection-molded for start-stop system duty cycles. Germany's automotive supplier ecosystem sources these for galvanic corrosion resistance in frequent-cycling applications where metal fatigue would compromise terminal retention.
- Composite:Glass-fiber reinforced polymer matrix combining structural rigidity with dielectric isolation. Hybrid powertrain retrofits specify these for weight reduction in electrified architectures where every gram impacts range calculations.
- Metal:Stamped aluminum or brass terminal housing retained in heavy-duty diesel applications requiring electromagnetic shielding.
- Rubber:Silicone or fluorocarbon elastomer seals and grommets specified for thermal cycling endurance above 150°C.
Plastic formulations dominate procurement volume, with composites gaining share fastest in electrified platform specifications.
Emission Standard:
Application scope determines connector specification tier, with regulatory stringency mapping directly to thermal and sealing performance requirements.
- EPA Tier 3:Cold-start emission reduction mandate requiring faster coil saturation and improved spark consistency. US Southwest heavy-duty diesel fleets face acute redesign pressure as California Air Resources Board frameworks compress ignition timing tolerances.
- Euro 6:European emission ceiling forcing vacuum integrity specifications in pressurized engine compartments. German OEM supply chains specify sealed connector variants for nitrogen oxide reduction strategies dependent on precise combustion control.
- EPA Tier 2:Legacy US federal standard retained in aftermarket replacement and export-market vehicle production.
- Euro 5:Previous European regulatory tier maintained in budget vehicle segments and developing market exports.
EPA Tier 3 specifications command the highest unit values, with Euro 6 climbing fastest as compliance deadlines approach.
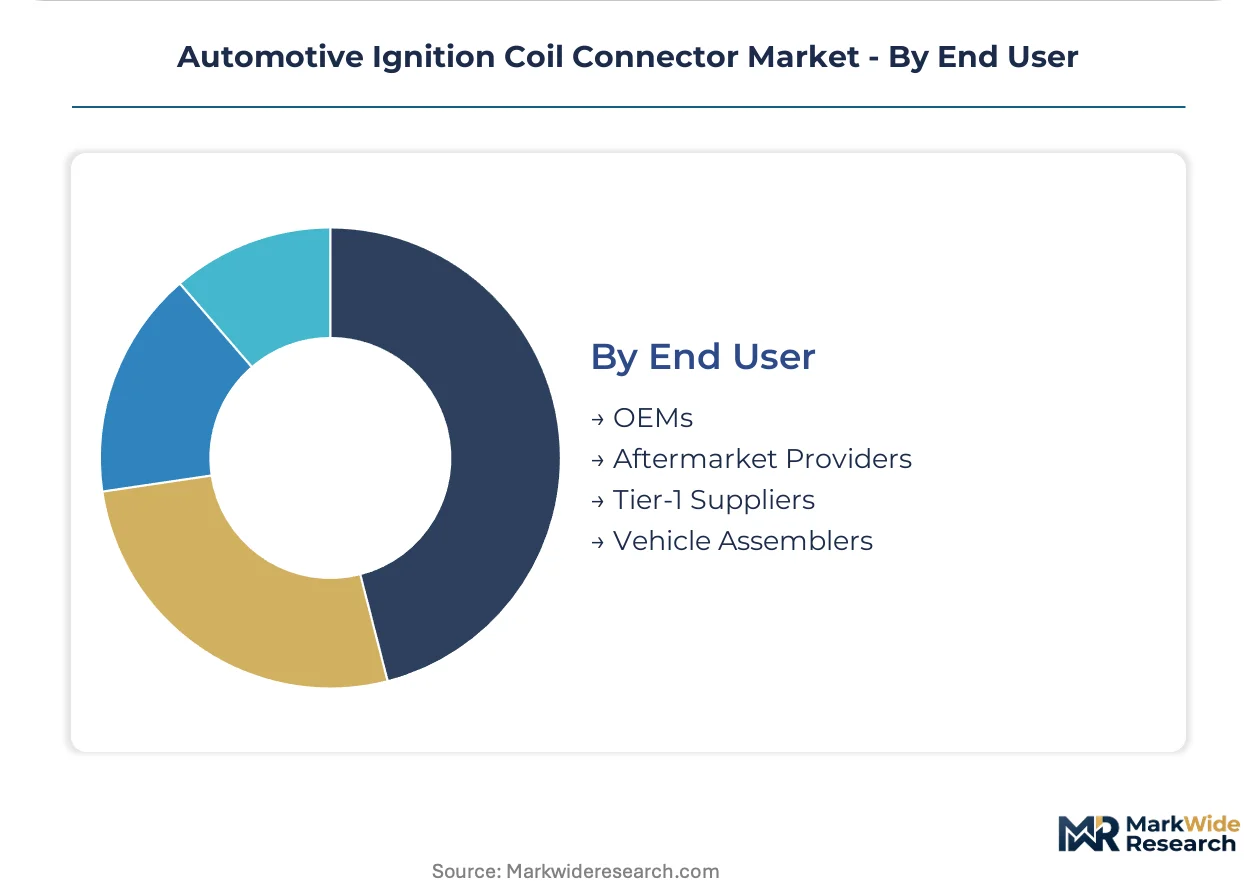
End User:
Customer type dictates procurement pattern, with captive production versus merchant market sourcing creating distinct specification pathways.
- OEMs:Original equipment manufacturers specifying connector architectures at vehicle platform conception. German premium OEMs consolidate procurement through ignition system module bundling that reduces assembly line complexity.
- Tier-1 Suppliers:System integrators capturing specification authority through coil-connector-control electronics consolidation. Stuttgart-based suppliers leverage proximity to accelerate qualification cycles for new platform introductions.
- Aftermarket Providers:Independent replacement channel sourcing discrete connectors for legacy platform maintenance.
- Vehicle Assemblers:Contract manufacturing operations integrating pre-specified connector modules into final assembly.
OEMs sit at the top of the volume ranking, with Tier-1 suppliers climbing fastest as module consolidation concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive supplier corridor anchors European demand for ignition coil connectors, with German OEM procurement patterns rippling through adjacent markets. EPA Tier 3 and Euro 6 compliance deadlines are compressing qualification timelines across manufacturing clusters. Connector specification authority concentrates where module bundling and emission testing infrastructure overlap.
Germany
Baden-Württemberg's supplier ecosystem drives sealed connector specifications for Euro 6 nitrogen oxide reduction strategies. KBA type-approval protocols mandate vacuum integrity testing above 150°C for pressurized engine compartments. Stuttgart-based Tier-1 suppliers capture procurement authority through ignition system module consolidation that reduces assembly line complexity for premium OEMs.
United States
Heavy-duty diesel fleets in the US Southwest generate acute redesign demand for faster catalyst light-off compliance. EPA Tier 3 cold-start emission mandates force connector architectures toward improved spark consistency and thermal cycling tolerance. Michigan's automotive engineering corridor hosts qualification facilities where NHTSA vibration protocols under ISO 8092 govern 18-24 month certification timelines.
China
Domestic OEM electrification roadmaps are expanding demand for high-voltage-compatible connector variants in hybrid powertrains. MIIT new energy vehicle standards accelerate thermal endurance specifications for frequent-cycling start-stop systems. Yangtze River Delta manufacturing clusters concentrate injection molding capacity for plastic and composite housing substitution away from metal-stamping supply chains.
Japan
Compact engine bay architectures in kei-car and subcompact segments favor short connector variants with reduced wire lead lengths. METI carbon neutrality targets for 2050 are compressing ICE platform timelines against electrification commitments. Nagoya's automotive supplier belt maintains legacy harness compatibility expertise for hybrid retrofit adapter interfaces.
South Korea
Hyundai-Kia's integrated supplier networks specify composite connector housings for weight reduction in electrified architectures. MFDS automotive component standards align with ISO 8092 pin retention force requirements for vibration resistance. Seoul Capital Area engineering centers concentrate sensor-connector integration R&D for ignition timing module convergence.
Automotive Ignition Coil Connector Market Competitive Landscape
Module bundling dominates the current landscape as Tier-1 suppliers capture specification authority previously held by connector specialists. The vendor base stratifies across three tiers: diversified electromechanical conglomerates with sensor integration capabilities, dedicated connector manufacturers with sealing expertise, and regional fabricators serving aftermarket channels. Two competitive vectors define positioning: backward integration into coil-connector-control electronics consolidation, and geographic proximity to Stuttgart, Michigan, and Nagoya qualification hubs.
Within the diversified electromechanical tier, TE Connectivity, Bosch, and Yazaki Corporation exemplify contrasting strategic positions. TE Connectivity anchors European OEM supply chains through sensor-connector integration expertise. Bosch represents in-house production of ignition system modules that bundle connectors with coil assemblies. Yazaki Corporation occupies a position within Asian sourcing networks for sealed connector variants in compact engine bay applications. These three entities collectively illustrate how specification authority is migrating toward system integrators with module-level design control.
| Leading Market Players |
|---|
| TE Connectivity |
| Delphi Technologies |
| Molex LLC |
| Sumitomo Electric Industries |
| Yazaki Corporation |
| Aptiv PLC |
| Bosch |
| Denso Corporation |
| Standard Motor Products |
| Others |
Value Network & Pricing Analysis
Injection molding substitution for metal-stamped housings simultaneously compresses unit economics and decentralizes tooling investments away from traditional supply chains toward Yangtze River Delta specialists. This production-method transition concentrates cost advantages with manufacturers mastering high-temperature thermoplastic formulations while fragmenting legacy supplier positions.
Pricing Analysis
Fluorocarbon rubber feedstock volatility passes through directly to sealed connector margins, with petrochemical price swings compressing structures for Tier 3 compliance variants. Three-tier pricing structure across premium thermal-grade, standard injection-molded, and economy unsealed levels differentiates by certification grade and thermal cycling performance. Cost compression in economy tiers intensifies because Asian sourcing networks face single-source vulnerability. Aftermarket providers exhibit highest price sensitivity, while German OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Michigan, and Nagoya operate hub-and-spoke patterns feeding tier-1 module integrators. Manufacturing concentrates in Germany, China, and Japan, with injection molding capacity expanding fastest in the Yangtze River Delta. Supply chains draw from fluorocarbon rubber, high-temperature thermoplastics, and conductive copper alloys. Single-source vulnerability in Asian sealed connector sourcing creates structural risk. Distribution runs through tier-1 system integrators bundling coils, connectors, and control electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through composite housing substitution and sensor-connector integration premiums. Material grade differentiation and module bundling authority concentrate returns with qualification-proximate suppliers.
For Market Incumbents: Lock in sensor-connector integration architectures before module bundling consolidates specification authority with Bosch and TE Connectivity. Deepen backward integration into fluorocarbon rubber compounding to defend margin position against petrochemical volatility. Secure KBA type-approval proximity in Baden-Württemberg to accelerate OEM qualification cycles.
For New Entrants and Emerging Players: Capture aftermarket channel digitization white space in North American independent repair segments bypassing traditional distributor markups. Target plastic and composite housing substitution demand from start-stop system penetration in compact engine bay applications. Lead with e-commerce platform partnerships and legacy harness compatibility expertise.
For Investors and Strategic Acquirers: Valuations sit cheapest among injection molding specialists with thermoplastic formulation capabilities and tier-1 qualification proximity. Long-term viability hinges on positioning for extended ICE production timelines against electrification compression. Monitor EPA Tier 3 compliance deadline acceleration as inflection signal for sealed connector demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Connector Integration | TE Connectivity and Bosch capture specification authority through ignition timing module convergence. |
| Composite Housing Scale-Up | Weight reduction in electrified architectures opens substitution volume for glass-fiber reinforced polymers. |
| Fluorocarbon Rubber Backward Integration | Captive sealing material supply insulates margins from petrochemical feedstock volatility. |
| Aftermarket Channel Digitization | E-commerce platforms bypass distributor markups in North American independent repair segments. |
| Stuttgart Qualification Proximity | KBA type-approval acceleration reduces time-to-market for Euro 6 nitrogen oxide reduction strategies. |
Research Methodology
Direct dialogue with tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and injection molding specialists grounded qualitative assessment. Secondary validation drew from EPA Tier 3 regulatory filings, KBA type-approval databases, MIIT new energy vehicle standards, vehicle production registries, and customs trade records. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Bottom-up modeling aggregated unit assumptions across component type, material grade, emission standard, and end-user category, while top-down analysis triangulated against macro vehicle production forecasts across the analysis window. CAGRs derived from regression analysis of historical qualification cycle compression and platform electrification penetration curves. Industry-specific inputs included start-stop system adoption rates and heavy-duty hybrid powertrain retrofit timelines.
Underlying measurement precision varies by segment; sealed connector and EPA Tier 3 specifications carry tighter precision than economy aftermarket categories due to regulatory filing transparency. Forecasts reflect documented assumptions around ICE platform longevity and electrification commitment credibility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Automotive Throttle Cables Market
Automotive Electronics & Wiring
Passenger Vehicle Dashboard Camera Market
Automotive Electronics & Wiring
Automotive High-Precision Positioning System Market
Automotive Electronics & Wiring
Electric and Autonomous Vehicles Wiring Harness Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Traffic Sign Recognition System Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Automotive Electronics Sensor Aftermarket Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Global Vehicle Camera Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Vehicle Networking Market