
 Latin America Automotive Camera Market | 2026-2036
Latin America Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automotive Camera Market Foresight
Brazil's CONTRAN Resolution 435 is decoupling camera adoption from purely luxury vehicle configurations, compelling OEMs to standardize rear-view and surround-view systems across mid-range passenger and commercial platforms. Continental AG leverages its local manufacturing footprint in Brazil to sustain cost-competitive module assembly for regional OEM programs. Valeo SA anchors its Latin American presence through dedicated thermal camera R&D operations serving both passenger and electric vehicle segments. Bosch Mobility Solutions differentiates via integrated sensor fusion architectures that combine camera data with radar inputs for advanced driver assistance.
Automotive cameras in Latin America comprise sealed electro-optical assemblies housing CMOS image sensors, polycarbonate lens arrays, and signal processing chipsets engineered to operate across temperature ranges from minus forty to eighty-five degrees Celsius; these devices capture real-time visual data to enable parking assistance, lane monitoring, collision avoidance, and cabin occupancy detection for vehicle safety and regulatory compliance. Front cameras and surround view cameras command the dominant share of OEM procurement value given their structural role in advanced driver assistance system architectures, while interior cameras represent the fastest-growing category as ride-hailing operators and fleet managers deploy driver monitoring to mitigate fatigue-related incidents. Night vision technology and infrared sensing attract disproportionate engineering investment due to Latin America's varied terrain and extended rural transport routes where conventional visible-light performance degrades.
ANFAVEA in Brazil, AMA in Mexico, and Argentina's national industrial standards body collectively shape camera specification requirements through regional safety homologation protocols and local content regulations that influence supplier selection and manufacturing location decisions. Compliance with these multi-layered frameworks determines market access for imported modules and dictates the pace of technology transfer to domestic assembly operations. Stakeholders must monitor evolving alignment between national safety mandates and United Nations ECE R79/R158 camera performance standards to anticipate certification burdens and sourcing model adjustments.
Market Dynamics
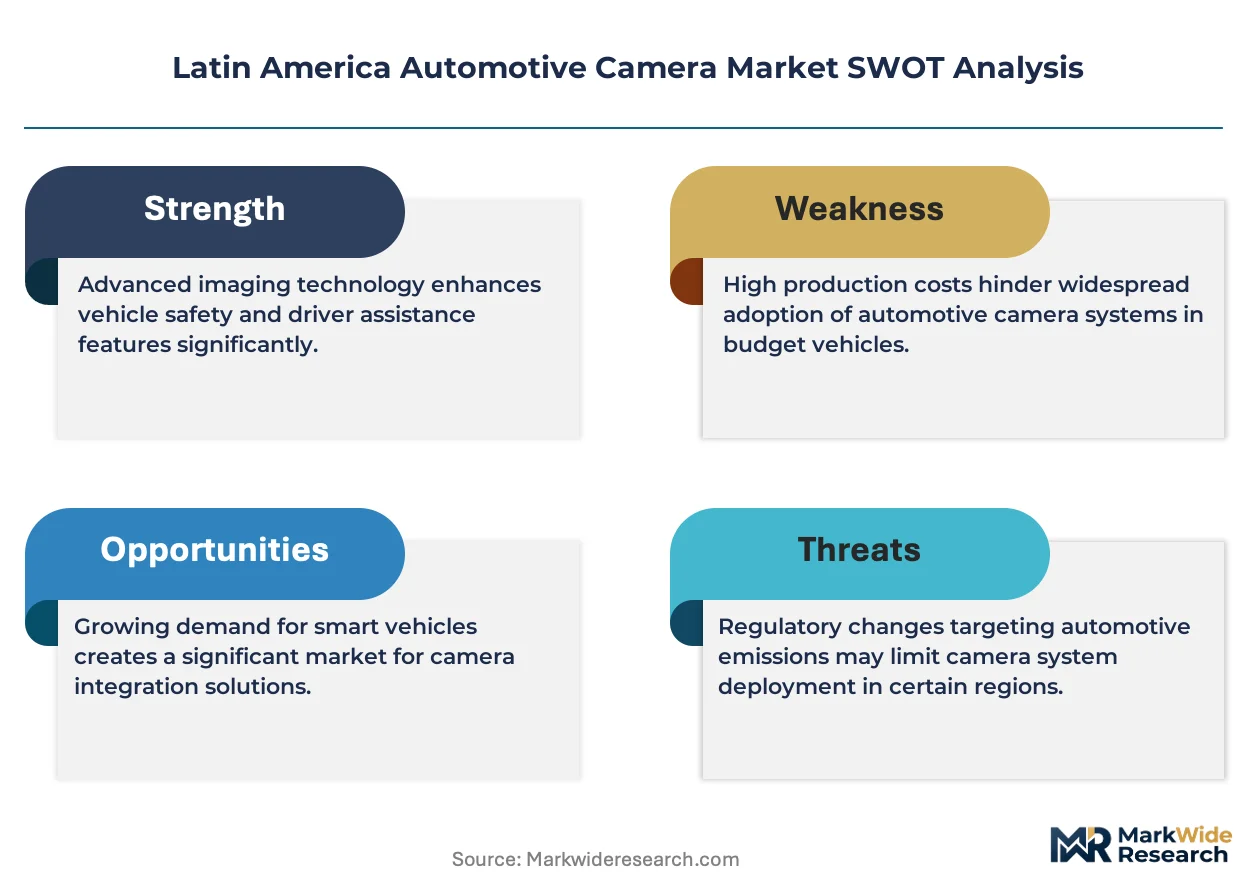
CONTRAN Resolution 435 and Mexico's NOM-194-SCFI standards are forcing OEMs to standardize camera systems across vehicle classes, collapsing the historical luxury-premium segmentation that previously gated advanced driver assistance features to high-end trims.
Growth Catalysts
- Insurer mandates for commercial fleets:Brazilian and Mexican fleet operators face rising liability premiums that camera deployments directly offset, creating procurement pull-through for multi-camera architectures in heavy trucks and buses.
- Rear visibility homologation:Brazil's CONTRAN safety resolutions mandate rear-view camera fitment on new vehicle registrations, eliminating configuration discretion and guaranteeing baseline demand across passenger and commercial segments.
- Driver monitoring for ride-hailing:Fatigue detection algorithms and cabin occupancy verification are accelerating interior camera adoption as Uber and Didi operators seek incident documentation and insurance premium reductions.
Market Restraints
- CMOS sensor import dependency:Latin American assembly operations rely on Asian-sourced image sensors, exposing cost structures to currency volatility and semiconductor allocation priorities from foreign foundries.
- Polycarbonate lens thermal degradation:Extended exposure to equatorial ultraviolet radiation and temperature cycling between minus forty and eighty-five degrees Celsius degrades optical clarity faster than glass alternatives, elevating warranty exposure.
- Local content thresholds:ANFAVEA and AMA homologation protocols impose domestic manufacturing requirements that complicate module sourcing for foreign tier-1 suppliers without established Brazilian or Mexican production footprints.
Strategic Opportunities
- Argentina industrial corridor expansion:Underpenetrated relative to Brazil and Mexico, Argentina's automotive assembly base offers first-mover positioning for camera suppliers establishing local content-compliant manufacturing before regulatory harmonization tightens.
- Thermal imaging for rural transport:Night vision and infrared sensing applications are attracting engineering investment as Latin America's extended rural highway networks expose visible-light camera limitations in unlit conditions.
- Electric vehicle platform integration:Dedicated thermal camera R&D operations are pivoting toward battery thermal runaway detection and pedestrian warning systems for emerging Latin American EV assembly programs.
Industry Challenges
- Multi-layered certification timelines:Alignment between national safety mandates and United Nations ECE R79/R158 camera performance standards creates overlapping homologation burdens that delay product launches and inflate testing expenditure.
- Legacy vehicle retrofit complexity:Aftermarket camera installation in existing commercial fleets requires CAN bus integration and display head-unit compatibility that many aging vehicle platforms lack, constraining addressable market expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automotive Camera Market |
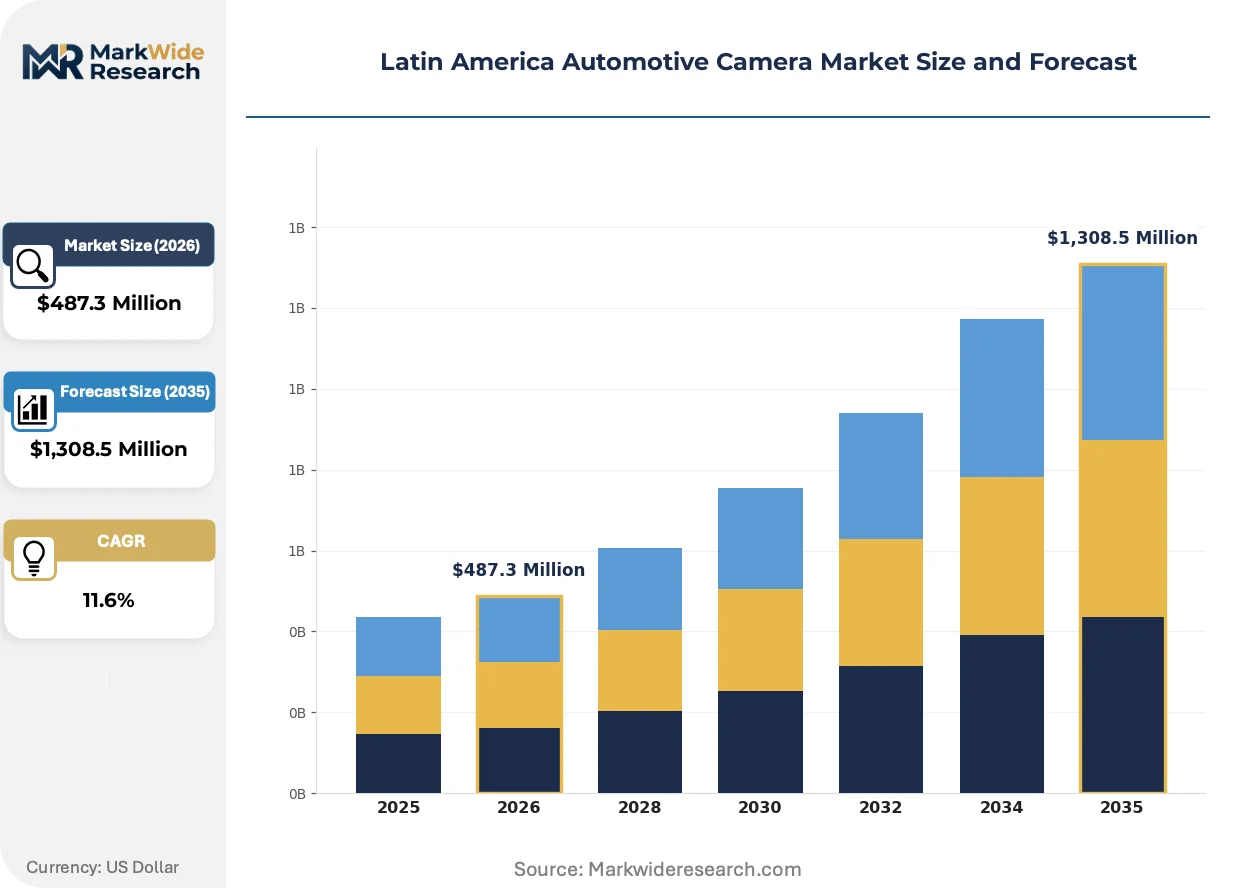
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,308.5 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Cameras, Rear Cameras, Surround View Cameras, Interior Cameras Technology: Image Sensors, Night Vision, 360-Degree View, Infrared End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles Installation Type: OEM Installation, Aftermarket Installation, Integrated Systems, Standalone Units |
| Companies Covered | Magna International Inc, Valeo SA, Continental AG, Gentex Corporation, Garmin Ltd, Bosch Mobility Solutions, Panasonic Corporation, Hella KGaA Hueck & Co, Autoliv Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automotive Camera Market Shifts & Advancements
Camera system architecture is modularizing around software-defined platforms that separate hardware capture from algorithm processing, enabling feature upgrades without physical module replacement. This shift compresses OEM procurement cycles and opens subscription revenue models.
Sensor fusion is modularizing advanced driver assistance architectures by combining CMOS camera streams with radar inputs through integrated chipsets. Tier-1 suppliers in São Paulo's industrial corridor are adopting these consolidated modules to reduce wiring harness complexity and assembly labor. The consolidation is modularizing supplier tiers, compressing margins for standalone camera manufacturers unable to deliver fused perception stacks.
Brazil's CONTRAN Resolution 435 is decoupling camera adoption from luxury vehicle configurations, compelling standardization across mid-range platforms. The regulation eliminates OEM discretion in rear-view system fitment, converting optional equipment to mandatory cost-of-entry. Mid-size passenger vehicle segments and light commercial platforms are absorbing the largest compliance cost shocks as manufacturers reconfigure trim hierarchies.
Fleet procurement patterns are compressing supplier qualification timelines as Brazilian and Mexican logistics operators consolidate camera purchases under master service agreements with integrated telematics providers. Direct OEM channel relationships are losing ground to bundled safety system contracts that combine cameras, connectivity, and cloud analytics. São Paulo-based fleet managers are leading this consolidation, leveraging scale to extract multi-year pricing commitments and dedicated technical support resources.
Latin America Automotive Camera Market Segmentation
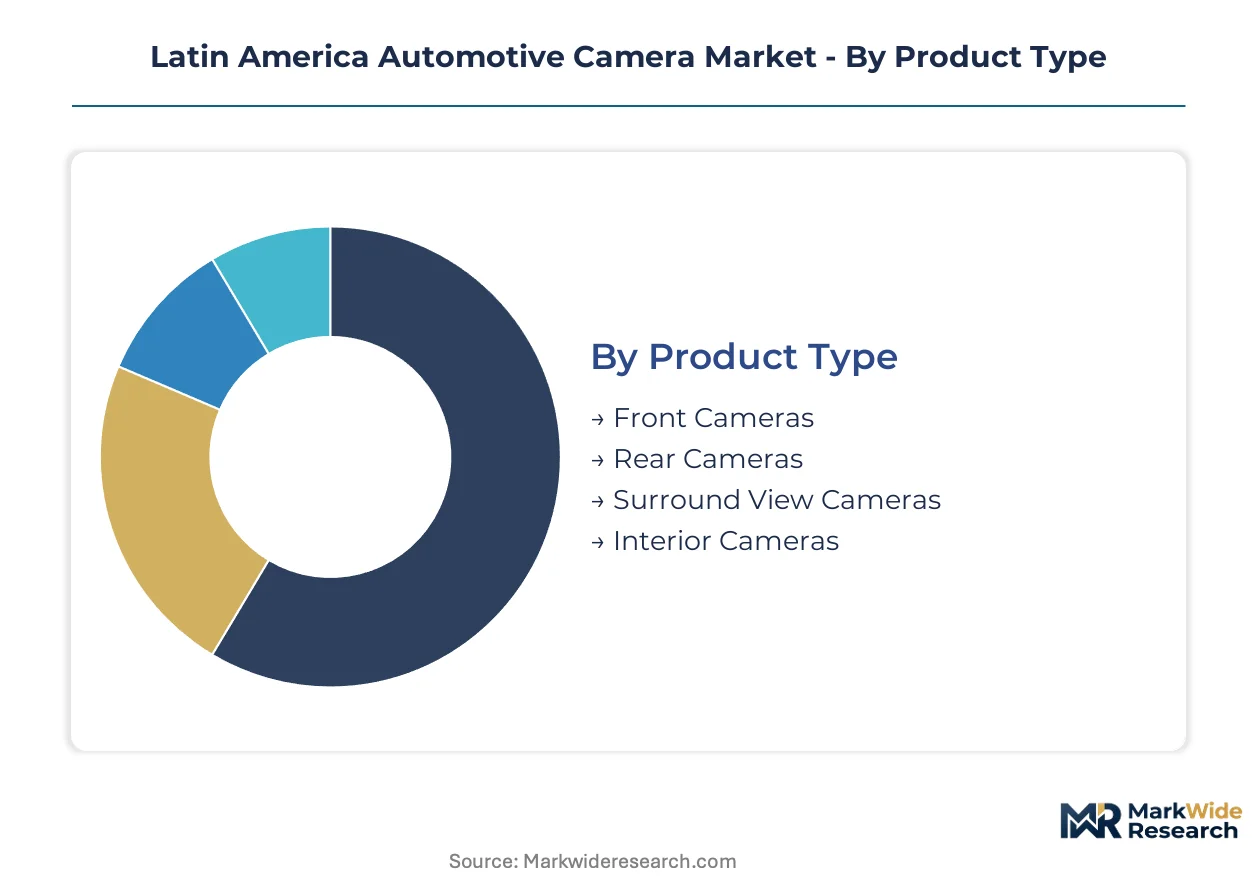
Camera system procurement across Latin America fragments sharply between standardized regulatory-mandated configurations and premium feature differentiation. OEMs optimize platform architectures around these tiered specifications while tier-1 suppliers calibrate manufacturing footprints to serve both compliance-driven volume and technology-upgraded margins.
Product Type:
Customization concentrates in multi-camera surround architectures while standardization dominates single-function rear visibility systems mandated by CONTRAN Resolution 435.
- Front Cameras:CMOS-based forward-facing assemblies integrate lane departure warning and collision avoidance algorithms. Brazilian OEMs in São Paulo's industrial corridor deploy these most intensively in mid-range passenger platforms where ANFAVEA homologation protocols apply.
- Surround View Cameras:Multi-module stitched-imaging systems synthesize four to six camera feeds into unified bird's-eye displays. Mexican assembly plants serving export markets prioritize these configurations for premium SUV and light truck platforms bound for US retail channels.
- Rear Cameras:Single-lens backup visibility modules meeting minimum CONTRAN field-of-view requirements.
- Interior Cameras:Cabin-facing driver monitoring and occupancy detection systems gaining traction fastest among São Paulo ride-hailing fleets.
Leading the category by volume: Rear Cameras. Expanding most quickly: Interior Cameras.
Technology:
Cost tier separation drives procurement patterns from commodity CMOS sensors through premium thermal imaging stacks.
- Image Sensors:Silicon-based CMOS and CCD capture elements constitute the foundational cost layer. Brazilian module assemblers source these predominantly from Asian foundries, exposing landed cost structures to currency volatility against the real.
- Night Vision:Infrared-augmented low-light detection systems extend operational range beyond visible-spectrum limitations. Extended rural transport routes across Brazil's interior and Mexico's northern highway corridors create concentrated demand from long-haul commercial operators.
- 360-Degree View:Multi-sensor fusion processing for comprehensive vehicle perimeter imaging.
- Infrared:Thermal radiation detection for pedestrian and wildlife identification in unlit conditions.
Dominating procurement value: Image Sensors. Steepest expansion trajectory: Night Vision.
End User:
Application maturity separates established passenger vehicle fitment from emerging electric platform integration.
- Passenger Vehicles:Light-duty consumer automobiles absorb the majority of OEM camera procurement by unit volume. São Paulo-based assembly operations for both domestic Brazilian consumption and regional export concentrate rear-view and surround-view deployments here.
- Electric Vehicles:Battery-electric platforms require specialized thermal monitoring and pedestrian warning systems. Emerging Latin American EV assembly programs in Mexico and Brazil are catalyzing dedicated camera R&D investment from tier-1 suppliers establishing local content-compliant production.
- Commercial Vehicles:Heavy truck and bus platforms subject to fleet insurer mandates.
- Autonomous Vehicles:Test fleet and limited deployment platforms requiring redundant perception stacks.
Highest unit volume: Passenger Vehicles. Gaining share fastest: Electric Vehicles.
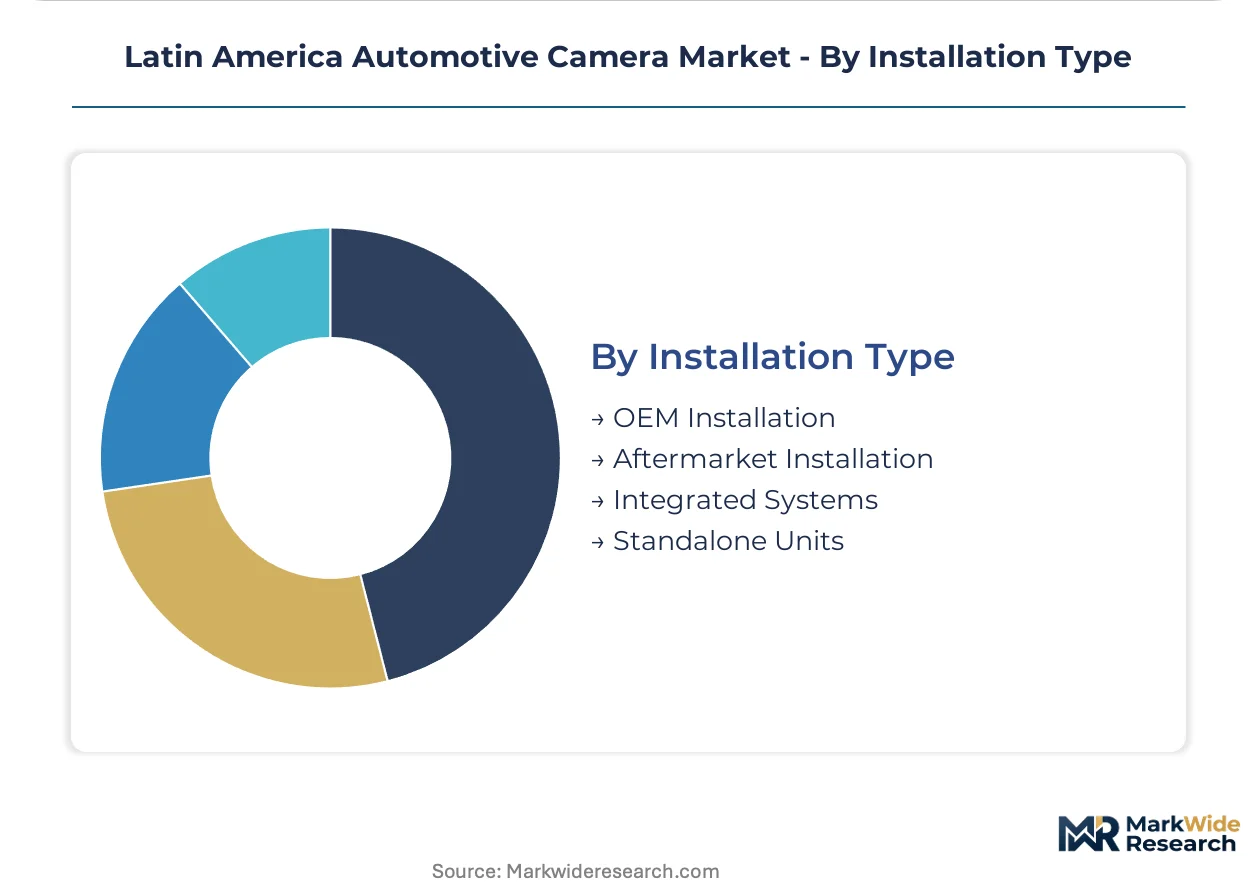
Installation Type:
Customer type bifurcates between factory-integrated OEM channels and retrofit aftermarket complexity.
- OEM Installation:Factory-integrated camera modules installed during vehicle assembly. CONTRAN and NOM-194-SCFI mandates guarantee this channel baseline demand across all new vehicle registrations in Brazil and Mexico.
- Aftermarket Installation:Retrofit camera systems for legacy vehicle fleets. São Paulo logistics operators consolidate these purchases under telematics-bundled contracts, compressing standalone supplier margins.
- Integrated Systems:Multi-sensor fusion architectures combining camera, radar, and LiDAR inputs.
- Standalone Units:Single-function camera modules without sensor fusion or connectivity features.
Capturing dominant channel share: OEM Installation. Growing fastest: Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil manufactures the majority of Latin America's automotive camera modules while Mexico serves as the primary export assembly hub; Argentina and Chile absorb smaller volumes through domestic fleet retrofit channels. Production capacity concentrates in São Paulo's industrial corridor and Mexico's Bajío Region, with regulatory mandates in Brazil and Mexico driving baseline demand across all vehicle classes.
Brazil
Fleet insurer mandates and CONTRAN Resolution 435 rear visibility requirements dominate procurement volume. ANFAVEA homologation protocols enforce local content thresholds that shape supplier qualification. São Paulo's industrial corridor hosts Continental AG's module assembly operations serving domestic OEM programs.
Mexico
NOM-194-SCFI standards mandate camera fitment for new vehicle registrations while export-oriented assembly plants supply US retail channels. The Bajío Region and Nuevo León concentrate tier-1 supplier manufacturing for integrated sensor fusion architectures. Mexico City Metro fleet operators consolidate multi-camera purchases under telematics-bundled contracts.
Argentina
Underpenetrated commercial vehicle fleets create retrofit demand as national industrial standards bodies draft camera specification requirements. The country's automotive assembly base offers first-mover positioning for suppliers establishing local content-compliant manufacturing. Córdoba and Buenos Aires provinces concentrate logistics operator procurement for heavy truck visibility systems.
Chile
Mining fleet operators deploy thermal imaging for extended rural transport routes where visible-light performance degrades. The national transport regulator advances safety homologation alignment with United Nations ECE standards. Santiago-based logistics companies pilot driver monitoring systems for long-haul copper corridor operations.
Colombia
Ride-hailing platform operators accelerate interior camera adoption for fatigue detection and incident documentation. The national automotive standards body develops camera performance protocols for emerging electric vehicle assembly programs. Bogotá's urban fleet managers negotiate consolidated safety system contracts combining cameras with cloud analytics.
Latin America Automotive Camera Market Competitive Landscape
The competitive structure tilts toward multinational tier-1 suppliers with established local manufacturing footprints. Module assembly concentrates among electro-optical specialists capable of CMOS integration and thermal management engineering. Two strategic archetypes dominate: integrated sensor fusion providers combining camera and radar inputs, and standalone visibility module manufacturers serving regulatory-mandated rear-view fitments. Capacity expansion and strategic partnerships constitute the primary competitive moves as suppliers secure OEM program allocations.
Within the multinational tier-1 tier, Continental AG leverages its Brazilian manufacturing presence to serve regional OEM programs with cost-competitive module assembly. Valeo SA anchors its Latin American position through thermal camera operations addressing both passenger and electric vehicle segments. Bosch Mobility Solutions exemplifies the integrated sensor fusion archetype, combining camera data with radar inputs for advanced driver assistance architectures. These three entities represent the dominant competitive anchors as local content regulations and CONTRAN mandates reshape procurement patterns.
| Leading Market Players |
|---|
| Magna International Inc |
| Valeo SA |
| Continental AG |
| Gentex Corporation |
| Garmin Ltd |
| Bosch Mobility Solutions |
| Panasonic Corporation |
| Hella KGaA Hueck & Co |
| Autoliv Inc |
| Others |
Supply & Pricing Matrix
CMOS sensor integration specialists concentrated in São Paulo's industrial corridor anchor module assembly labor-cost differentials that widen pricing-tier spreads between regulatory-compliant rear-view systems and premium surround-view architectures. Brazilian foundry wages against Asian-sourced image sensor landed costs create structural margin compression that OEMs pass through trim hierarchies.
Pricing Analysis
Margin tightening in mid-range passenger platforms traces to CONTRAN Resolution 435 compliance mandates that eliminate configuration discretion. Three-tier pricing structure across premium surround-view, standard front-camera, and economy rear-visibility levels separates ANFAVEA-certified modules from import-only alternatives. Price differentiation hinges on local content thresholds and thermal management engineering. Fleet procurement through telematics-bundled contracts exhibits highest price sensitivity; export-platform OEMs absorbing compliance costs show lowest.
Supply Chain Analysis
Ocean freight cost volatility from Asian semiconductor foundries to Brazilian port terminals elevates landed CMOS sensor expenses and compresses module assembler margins. Supply concentrates in Taiwan, South Korea, and China for image sensors; Germany and Japan for polycarbonate lens arrays; Mexico for integrated sensor fusion chipsets. Raw material dependencies span silicon wafers, optical-grade polymers, and signal processing ASICs. Single-source vulnerability from TSMC allocation priorities threatens Brazilian assembly continuity. Distribution runs through São Paulo-based tier-1 suppliers to domestic OEM programs and Bajío Region export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's automotive camera market operates as a cost-of-compliance arena where Brazil's CONTRAN Resolution 435 erects regulatory moats that reward pre-certified incumbents with guaranteed procurement volume and marginalize non-compliant import alternatives.
For Market Incumbents: Anticipate sensor fusion consolidation by deepening backward integration into thermal management engineering and securing dedicated CMOS allocation agreements with Taiwanese foundries. Defend against integrated radar-camera module displacement by accelerating software-defined platform development that decouples hardware from algorithm refresh cycles.
For New Entrants and Emerging Players: Enter via Argentina's underpenetrated commercial vehicle retrofit channel before national industrial standards bodies finalize camera specification requirements and tighten local content thresholds. Target Córdoba and Buenos Aires logistics operators with CAN bus-compatible aftermarket systems bundled with cloud analytics subscriptions.
For Investors and Strategic Acquirers: Re-rating potential sits with thermal camera specialists possessing ANFAVEA homologation and electric vehicle platform qualifications given accelerating battery thermal runaway detection demand. Monitor alignment between Argentina's draft camera standards and United Nations ECE R79/R158 protocols as inflection signal for regional regulatory harmonization timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Content Manufacturing Footprint | ANFAVEA homologation compliance secures OEM program allocation against import-dependent competitors. |
| Sensor Fusion Architecture Investment | Integrated radar-camera modules reduce wiring harness complexity for São Paulo assembly operations. |
| Thermal Camera R&D Expansion | Battery thermal runaway detection addresses emerging Latin American electric vehicle assembly requirements. |
| Software-Defined Platform Development | Feature upgrade subscriptions decouple hardware procurement from algorithm refresh revenue cycles. |
| Telematics Provider Partnership | Fleet bundled contracts consolidate procurement power for São Paulo logistics operators. |
Research Methodology
Multi-period observation of CONTRAN regulatory implementation timelines and NOM-194-SCFI compliance trajectories anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and ANFAVEA homologation officials. Secondary validation drew from vehicle production databases, customs import records for CMOS sensors, IHS Markit registration data, and SEC filings of multinational automotive component suppliers. Bottom-up module assembly capacity estimates triangulated against top-down OEM program allocation forecasts.
Input-output matrices mapped camera content per vehicle across passenger, commercial, and electric propulsion architectures, with segmentation by technology tier, installation channel, and regional production cluster. CAGRs derived from regression analysis of historical fitment rates against regulatory mandate effective dates, incorporating semiconductor supply elasticity and currency volatility assumptions. Forecast inputs included fleet insurer mandate expansion schedules and thermal imaging R&D expenditure patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged Asian foundry allocation constraints or accelerated Argentina regulatory harmonization. Forecasts reflect documented assumptions regarding CONTRAN enforcement consistency and CMOS sensor import cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Aircraft Engine Electrical Wiring Harnesses and Cable Assembly Market
Automotive Electronics & Wiring
Construction Machinery Wiring Harness Market
Automotive Electronics & Wiring
Brake Cables Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Automotive Connectivity Market
Automotive Electronics & Wiring
Automotive Display Units Market
Automotive Electronics & Wiring
North America Electric Vehicle Sensor Market
Automotive Electronics & Wiring
Global Automotive Active Window Display Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Africa and Middle East Automotive Camera Market
Automotive Electronics & Wiring
Brake-By-Wire System Market
Automotive Electronics & Wiring
In-Vehicle Connectivity Market
Automotive Electronics & Wiring
Automotive Auxiliary Lamps Market
Automotive Electronics & Wiring
Automotive HMI Market
Automotive Electronics & Wiring
Automotive HV Junction Box Busbar Insulator Market