
 Russia Automotive Camera Market | 2026-2036
Russia Automotive Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Camera Market Analytics
UN ECE R79/R158 homologation is collapsing the supplier field to Tier-1s with certified testing infrastructure. Continental AG leverages its Kaluga electronics plant to sustain local ADAS camera assembly. Robert Bosch GmbH anchors the forward-view segment through its domestic engineering center. Valeo SA competes on surround-view integration with St. Petersburg-based OEM programs.
Russia automotive cameras are electro-optical imaging devices with CMOS or infrared sensors, lens assemblies, and IP-rated housings engineered for vibration resistance between -40°C and 85°C; they capture real-time visual data for parking assistance, lane-keeping, and collision avoidance systems. Vision sensors dominate technology procurement due to cost scalability across L2 autonomy architectures, while time-of-flight modules represent the fastest-growing technology tier as OEMs add depth perception for urban pilot functions. OEM installation channels capture the dominant value pool because factory-integrated calibration preserves warranty compliance, whereas aftermarket standalone units occupy the price-sensitive replacement segment.
Russia's Technical Regulation of the Customs Union (TR CU 018/2011) mandates emergency braking and lane departure warnings on new vehicle categories, directly expanding ADAS camera fitment rates. GOST R certification and Rosstandart type-approval procedures shape product design rules for electromagnetic compatibility and climatic durability. The country's national automotive regulator continues tightening localization requirements for electronic components. Stakeholders must monitor how parallel import channels and domestic semiconductor substitution programs reshape component sourcing economics.
Market Dynamics
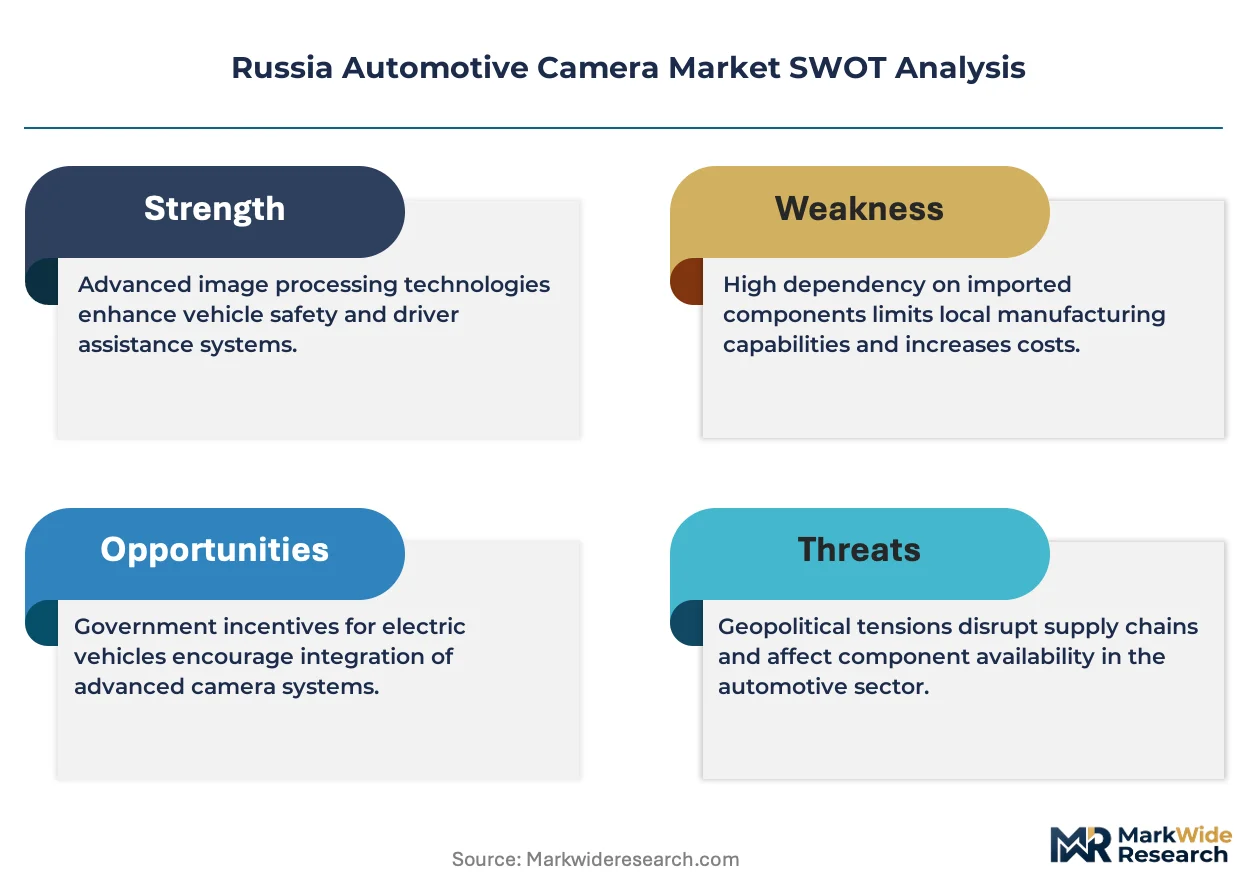
TR CU 018/2011 mandates are compressing supplier lead times as OEMs scramble to certify camera systems before enforcement deadlines tighten. This regulatory compression is redrawing competitive boundaries between domestic assemblers and import-dependent distributors.
Growth Catalysts
- Emergency Braking Mandates:TR CU 018/2011 requires AEB systems on new passenger vehicles, forcing camera fitment rates upward across Moscow and Tatarstan production lines.
- CMOS Sensor Migration:Domestic electronics clusters are absorbing semiconductor substitution programs, lowering import dependency for image processing components.
- Kaluga Manufacturing Concentration:Tier-1 suppliers have anchored localized PCB assembly and lens calibration operations, reducing logistics friction for OEM just-in-time delivery.
Market Restraints
- Semiconductor Input Volatility:CMOS wafer and FPGA availability remains hostage to parallel import channel disruptions, inflating safety stock requirements.
- Rosstandart Certification Friction:Electromagnetic compatibility testing bottlenecks at accredited laboratories extend product launch timelines by 4-6 months.
- Infrared Module Substitution:Thermal imaging alternatives for low-light operation threaten vision sensor dominance in premium vehicle segments.
Strategic Opportunities
- Surround-View Penetration:St. Petersburg-based luxury OEM programs remain underpenetrated for 360-degree camera integration, creating white space for multi-sensor fusion suppliers.
- GOST R Localization Incentives:Domestic content thresholds for electronic components are opening procurement slots for Tatarstan-based housing and connector manufacturers.
- Time-of-Flight Convergence:Depth perception modules combining structured light with CMOS arrays are enabling urban pilot functions beyond basic L2 autonomy.
Industry Challenges
- Calibration Technician Scarcity:Factory-integrated ADAS systems require specialized optical alignment expertise that vocational pipelines in Moscow Oblast have failed to scale.
- Legacy CAN Bus Integration:Older vehicle architectures lack bandwidth for multi-camera data streams, forcing expensive gateway module retrofits.
- IP Licensing Complexity:Image signal processing algorithms from foreign semiconductor vendors face royalty renegotiation under sanctions-driven contract restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Camera Market |
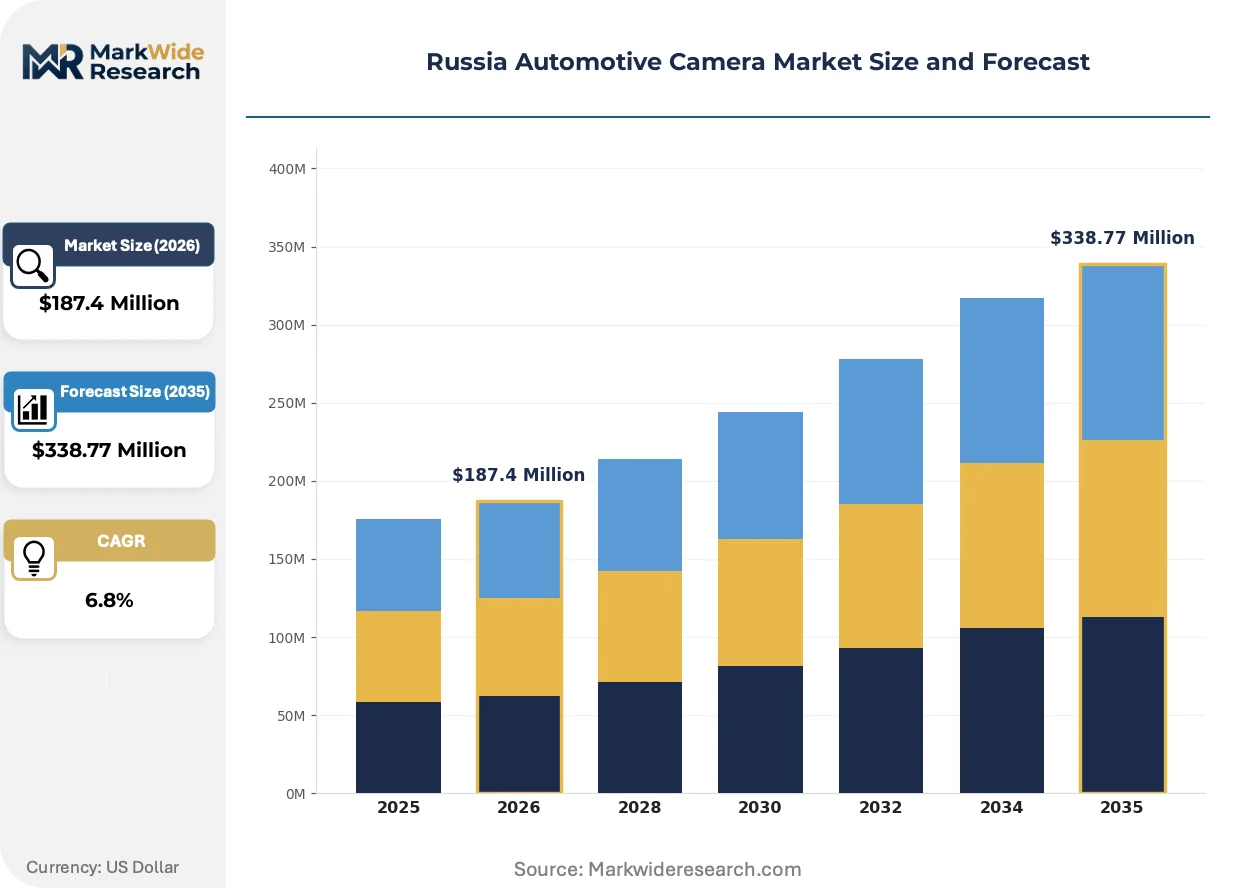
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rear-View Cameras, Surround-View Systems, Advanced Driver Assistance Cameras, Forward-View Cameras Technology: Vision Sensors, Infared Imaging, Time-of-Flight, CMOS Technology Installation: OEM, Aftermarket, Integrated Systems, Standalone Units Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Autonomous Vehicles |
| Companies Covered | Continental AG, Denso Corporation, Robert Bosch GmbH, Garmin Ltd, Magna International Inc, ZF Friedrichshafen AG, Panasonic Corporation, Valeo SA, Autoliv Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Camera Market Evolving Landscape
Camera system architectures are fragmenting into modular subassemblies as OEMs seek supply chain flexibility. This decomposition is accelerating sensor-lens-electronics unbundling.
Time-of-flight depth sensing is decomposing traditional stereo camera architectures in urban pilot applications. Domestic OEMs in the Moscow cluster are adopting single-sensor depth modules for parking assistance. This compression is collapsing the supplier field toward vendors with in-house VCSEL and SPAD fabrication partnerships.
Rosstandart has tightened electromagnetic compatibility testing protocols under updated GOST R 51317 series standards. Camera module manufacturers must now demonstrate immunity to 100V/m radiated fields across extended temperature ranges. Tier-1 suppliers with captive Kaluga testing chambers are absorbing certification demand that smaller competitors cannot service.
Fleet operators are consolidating procurement through direct Tier-1 contracts rather than aftermarket distributors. Commercial vehicle buyers in Tatarstan now specify camera durability requirements directly with Continental and Bosch engineering centers. This disintermediation is compressing margin pools for independent installers and regional parts wholesalers.
Russia Automotive Camera Market Segmentation
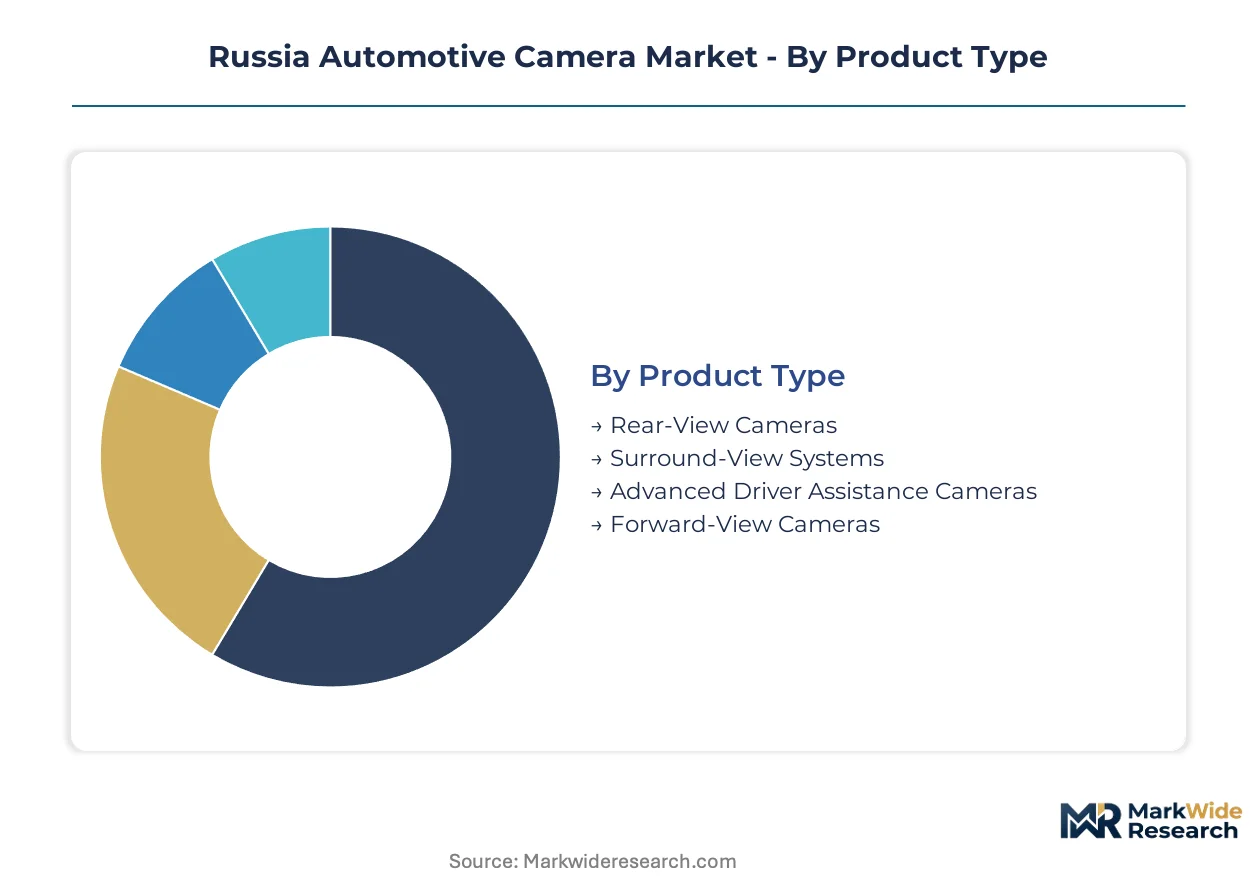
Camera system fragmentation across Russia reflects divergent OEM procurement strategies and regulatory compliance pathways. Understanding where value concentrates within each dimension enables suppliers to align R&D spend with enforceable demand pockets.
Product Type:
Margin pools concentrate in factory-integrated systems where calibration complexity creates switching costs for OEMs.
- Advanced Driver Assistance Cameras:These units combine multi-layer CMOS arrays with embedded image signal processors for lane-keeping and collision avoidance. Moscow-based passenger vehicle lines are absorbing the bulk of procurement as TR CU 018/2011 mandates tighten AEB fitment requirements. Calibration technician scarcity at Kaluga assembly plants is compressing supplier margins despite volume concentration.
- Surround-View Systems:Multi-camera fusion architectures synthesize four to six imaging feeds into unified 360-degree displays. St. Petersburg luxury OEM programs drive specification intensity, though integration complexity with legacy CAN bus architectures delays deployment timelines. Tatarstan commercial vehicle assemblers are piloting simplified dual-camera variants for parking assistance.
- Rear-View Cameras:Single-sensor units with IP69K housings dominate entry-segment fitment.
- Forward-View Cameras:Windshield-mounted mono and stereo configurations serve adaptive cruise control systems.
Advanced Driver Assistance Cameras hold installed capacity. Surround-View Systems is rotating up the share rankings.
Technology:
Cost tier stratification separates commoditized sensor platforms from premium depth-perception modules.
- Time-of-Flight:Structured-light depth modules employing VCSEL emitters and SPAD detector arrays enable real-time 3D scene reconstruction. Urban pilot function deployments in Moscow clusters are absorbing initial volumes as OEMs seek L2+ autonomy differentiation. Domestic semiconductor substitution programs have yet to localize SPAD fabrication, maintaining import dependency for critical components.
- Vision Sensors:Standard CMOS-based imaging dominates volume procurement across Kaluga and Tatarstan production lines. Cost scalability supports fitment rate expansion mandated by emergency braking regulations. Rosstandart electromagnetic compatibility testing bottlenecks are extending certification cycles for new sensor introductions.
- CMOS Technology:Backside-illuminated and stacked-die architectures improve low-light performance.
- Infared Imaging:Thermal sensor modules for pedestrian detection in adverse visibility conditions.
Vision Sensors holds installed capacity. Time-of-Flight is climbing the fastest among depth-sensing alternatives.
Installation:
Channel economics diverge sharply between warranty-integrated factory fitment and price-driven replacement demand.
- OEM:Factory-integrated camera systems with embedded calibration profiles preserve warranty compliance and optimize ADAS performance. Moscow Oblast passenger vehicle manufacturers specify direct Tier-1 contracts with Continental and Bosch engineering centers, disintermediating regional distributors. Lead time compression under regulatory deadlines is favoring suppliers with captive Kaluga assembly capacity.
- Integrated Systems:Multi-sensor fusion architectures bundled with central domain controllers command premium positioning. Tatarstan commercial fleet operators are consolidating procurement through direct Tier-1 relationships, bypassing aftermarket intermediaries.
- Aftermarket:Standalone replacement units serve collision repair and retrofit demand.
- Standalone Units:Single-function dashcams and parking cameras for price-sensitive consumers.
OEM holds installed capacity. Integrated Systems is gaining share fastest as domain controller architectures proliferate.
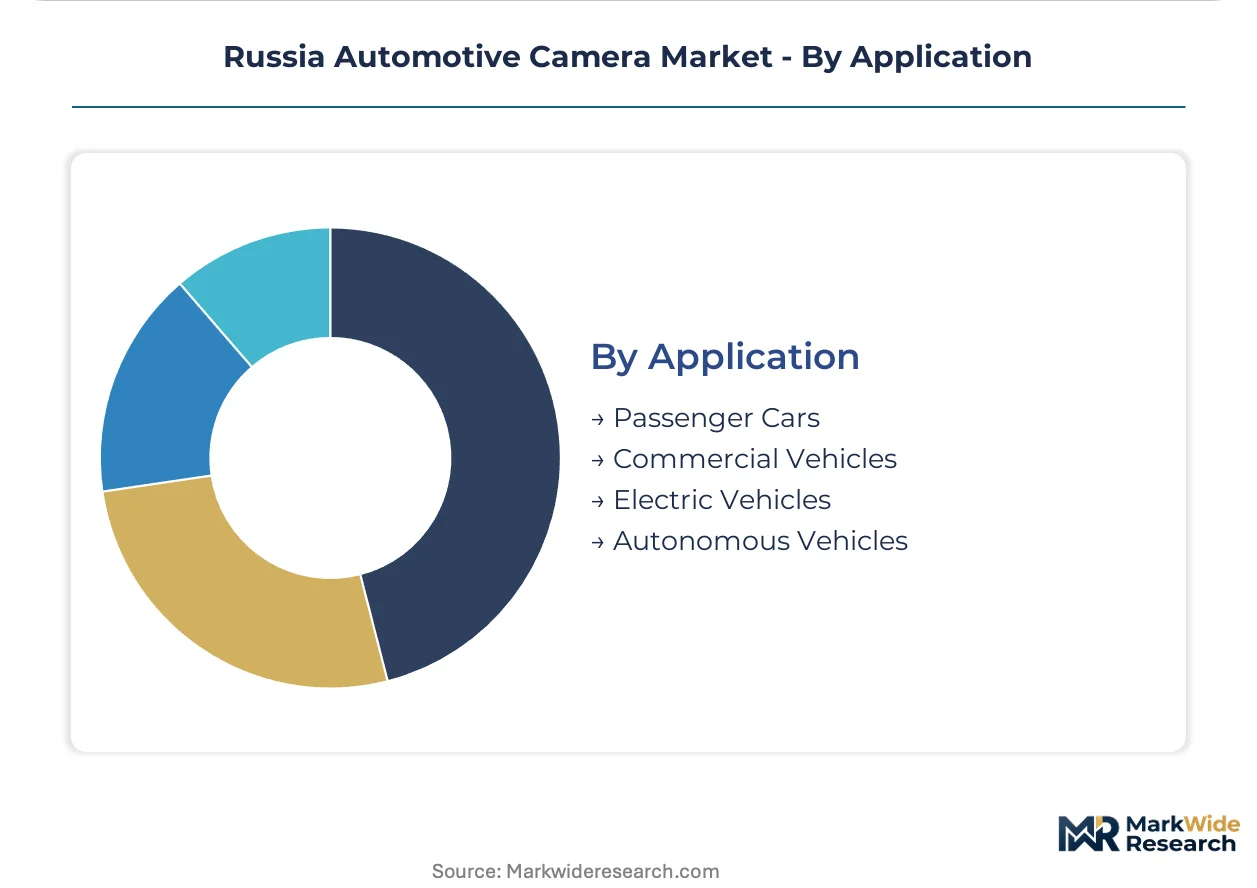
Application:
End-use segmentation tracks divergent durability specifications and autonomy readiness across vehicle categories.
- Passenger Cars:Light-duty vehicles with L2 autonomy architectures drive volume demand for forward-view and surround-view cameras. Moscow and St. Petersburg production lines are absorbing the majority of ADAS camera procurement as safety mandates tighten fitment rates. Electromagnetic compatibility testing at Rosstandart-accredited laboratories creates certification backlogs for new model introductions.
- Electric Vehicles:Battery-electric platforms with centralized electrical architectures enable higher-resolution camera data streams. Kaluga-based OEM programs are specifying multi-sensor fusion systems for automated parking and urban pilot functions.
- Commercial Vehicles:Heavy-duty applications prioritize vibration resistance and extended temperature operation.
- Autonomous Vehicles:L4-ready prototypes require redundant camera arrays with functional safety certification.
Passenger Cars holds installed capacity. Electric Vehicles is rotating up the share rankings as platform electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger vehicle OEMs concentrate procurement authority in Moscow and Tatarstan production clusters, while commercial fleet operators in St. Petersburg drive specification intensity for surround-view systems. Regional divergence reflects uneven regulatory enforcement timelines and localization incentive gradients.
Central Federal District
Moscow Oblast passenger vehicle manufacturers absorb the majority of ADAS camera procurement as TR CU 018/2011 mandates tighten emergency braking fitment requirements. Rosstandart electromagnetic compatibility testing bottlenecks at accredited laboratories extend certification cycles for new sensor introductions. Kaluga electronics plants anchor localized PCB assembly and lens calibration operations for Tier-1 suppliers.
Volga Federal District
Tatarstan commercial vehicle assemblers pilot simplified dual-camera variants for parking assistance while consolidating procurement through direct Tier-1 relationships. Domestic content thresholds for electronic components under GOST R certification open procurement slots for local housing and connector manufacturers. Naberezhnye Chelny truck assembly lines specify vibration-resistant camera modules for extended temperature operation.
Northwestern Federal District
St. Petersburg luxury OEM programs drive specification intensity for multi-camera fusion architectures despite integration complexity with legacy CAN bus architectures. Surround-view penetration remains underdeveloped, creating white space for multi-sensor fusion suppliers targeting 360-degree display integration. Local engineering centers coordinate directly with Continental and Bosch on domain controller architectures.
Southern Federal District
Rostov Oblast aftermarket distributors serve collision repair demand for standalone replacement units as factory-integrated systems dominate new vehicle fitment. Price-sensitive consumers in regional markets prioritize single-function dashcams over multi-sensor ADAS packages. Parallel import channels for CMOS wafers and FPGA components inflate safety stock requirements for regional installers.
Ural Federal District
Yekaterinburg-based electronics assemblers absorb semiconductor substitution programs for backside-illuminated CMOS architectures, lowering import dependency for image processing components. Vocational training pipelines struggle to scale calibration technician expertise required for factory-integrated optical alignment. Regional OEM programs specify time-of-flight depth modules for urban pilot function differentiation.
Russia Automotive Camera Market Competitive Landscape
Player mix skews toward multinational Tier-1 electronics suppliers with captive Russian assembly infrastructure. The supplier field compresses around entities with UN ECE R79/R158 homologation certification and Rosstandart-accredited testing chambers. Two archetypes dominate: integrated automotive electronics conglomerates with domain controller capabilities, and specialized vision system houses with multi-sensor fusion expertise. Competitive moves concentrate on Kaluga manufacturing capacity expansion and strategic partnerships for VCSEL emitter sourcing.
Within the integrated electronics tier, Continental AG and Robert Bosch GmbH anchor forward-view and surround-view segments through domestic engineering centers and localized assembly operations. Valeo SA occupies a position in multi-camera fusion architectures, while Denso Corporation and ZF Friedrichshafen AG exemplify Tier-1 suppliers navigating certification friction through captive testing infrastructure. These entities represent the consolidation pressure collapsing margins for smaller competitors without accredited electromagnetic compatibility laboratories.
| Leading Market Players |
|---|
| Continental AG |
| Denso Corporation |
| Robert Bosch GmbH |
| Garmin Ltd |
| Magna International Inc |
| ZF Friedrichshafen AG |
| Panasonic Corporation |
| Valeo SA |
| Autoliv Inc |
| Others |
Value Network & Pricing Analysis
TR CU 018/2011 homologation gates both supplier qualification and price differentiation simultaneously, compressing the vendor field toward Tier-1s with captive testing infrastructure while stratifying procurement costs across certified and uncertified tiers. Moscow-based OEMs pay premiums for Rosstandart-accredited camera modules that preserve warranty compliance, whereas parallel import channels feed price-sensitive aftermarket segments with unbundled components.
Pricing Analysis
Cost-plus contracts with CMOS wafer indexation dominate OEM procurement, linking module pricing to semiconductor spot market movements. Three-tier pricing structure across premium, standard, and economy levels separates UN ECE R79-certified forward-view systems from basic rear-view units and unbranded aftermarket alternatives. Pricing pressure stems from FPGA input volatility forcing safety stock inflation. Commercial fleet operators in Tatarstan exhibit highest price sensitivity, while St. Petersburg luxury OEMs absorb premiums for surround-view integration.
Supply Chain Analysis
Strait of Hormuz transit underwrites CMOS wafer and VCSEL emitter flows into Russian assembly plants, exposing Tier-1s to maritime logistics disruption. Manufacturing concentrates in Germany, South Korea, and domestic Kaluga electronics clusters. Raw material dependencies span silicon wafers, optical glass, and rare-earth phosphors. Single-source vulnerability for SPAD detector arrays threatens time-of-flight module scaling. Distribution runs through OEM direct contracts disintermediating regional wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers, technology architectures, and regional production clusters creates niche entry points for specialized suppliers. Urban pilot function deployments and commercial fleet digitization are spawning demand pockets outside incumbent dominance.
For Market Incumbents: Consolidate Kaluga manufacturing capacity to absorb Rosstandart certification demand that smaller competitors cannot service. Deepen backward integration into VCSEL emitter sourcing to offset SPAD fabrication import dependency. Infrared module substitution in premium segments threatens vision sensor margins; preempt with multi-sensor fusion R&D investment. For New Entrants and Emerging Players: Lead with simplified dual-camera parking assistance variants targeting Tatarstan commercial vehicle assemblers underserved by complex surround-view architectures. Naberezhnye Chelny truck lines offer lowest competitive density among volume OEM programs. Direct Tier-1 engineering relationships bypass aftermarket margin compression. For Investors and Strategic Acquirers: TR CU 018/2011 enforcement timeline reshapes the acquisition landscape toward targets with captive electromagnetic compatibility testing infrastructure. Five-to-ten-year viability hinges on localization compliance rather than import arbitrage. Prioritize Tatarstan-based housing and connector manufacturers with GOST R certification pathways. Monitor Rosstandart laboratory queue lengths as inflection indicator for certification bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Domain Controller Integration | Multi-sensor fusion architectures bundled with central compute units command premium positioning in Kaluga OEM programs. |
| VCSEL Supply Partnership | Structured-light depth module scaling rests on emitter fabrication partnerships beyond current import channels. |
| Kaluga Testing Chamber Expansion | Rosstandart-accredited electromagnetic compatibility facilities absorb certification demand collapsing competitor margins. |
| Calibration Technician Pipeline | Vocational training partnerships with Moscow Oblast technical institutes address optical alignment expertise scarcity. |
| Surround-View St. Petersburg Penetration | Luxury OEM 360-degree display integration remains underdeveloped relative to forward-view saturation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, encompassing OEM platform engineers at Moscow and St. Petersburg vehicle manufacturers, Tier-1 procurement leads at Continental and Bosch engineering centers, aftermarket distributors in Rostov Oblast, and calibration technicians at Kaluga assembly plants. Secondary validation drew from vehicle production databases, Rosstandart type-approval registries, TR CU regulatory filings, and customs import records for CMOS wafer and FPGA components. Bottom-up unit economics triangulated against top-down market sizing across technology and installation segments.
Across the analysis window, volume and value outputs reflect segmented modeling by product type, technology architecture, installation channel, and vehicle application, with regional disaggregation across Central, Volga, Northwestern, Southern, and Ural Federal Districts. CAGRs were derived from fitted growth curves incorporating regulatory mandate enforcement schedules, OEM platform refresh cycles, and semiconductor substitution program progress. Industry-specific forecast inputs included ADAS camera fitment rate trajectories tied to TR CU 018/2011 phase-in timelines and time-of-flight module adoption curves for urban pilot functions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement, intact parallel import channels, or stable OEM production volumes would require recalibration. Forecasts reflect documented assumptions about certification timeline elasticity and component localization thresholds. Practitioners should keep alternative scenarios live as Rosstandart laboratory capacity and semiconductor substitution program effectiveness evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Camera-Based Side Mirrors Market
Automotive Electronics & Wiring
Smart Dash Cameras Market
Automotive Electronics & Wiring
Automotive Switch Market
Automotive Electronics & Wiring
In-Vehicle Ethernet System Market
Automotive Electronics & Wiring
Automotive Ultrasonic Sensors Market
Automotive Electronics & Wiring
Virtual Reality in Automotive Market
Automotive Electronics & Wiring
Japan Automotive Smart Keys Market
Automotive Electronics & Wiring
Digital Tachographs Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive Ultrasonic Technologies Market
Automotive Electronics & Wiring
Digital Tachograph System Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Automotive Steer-By-Wire System (Sbw) Market
Automotive Electronics & Wiring
Rear-Seat Entertainment Display Platforms for SUVs Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market