
 Reverse Tuck Cartons Market | 2026-2036
Reverse Tuck Cartons Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Tuck Cartons Market Analytics
Skilled die-cutting and gluing technician shortages across Midwestern United States converting plants is unwinding near-term capacity expansion plans for several producers. WestRock sustains broad North American mill and converting integration that buffers fiber cost swings. Smurfit Kappa Group anchors European supply through its recycled containerboard network and regional sheet-feeding operations. Mondi Group differentiates via lightweight kraftliner grades that reduce basis weight without sacrificing box compression strength.
Reverse tuck cartons are paperboard folding cartons with opposing tuck flaps on the top and bottom panels, typically manufactured through rotary die-cutting, scoring, and adhesive or locking-tab assembly to create rectangular rigid containers for retail shelf display and product protection. The structure permits hand-loading or automated filling at speeds exceeding 200 units per minute on standard cartoning equipment. Food and beverage applications dominate volume consumption across the material split, with paperboard grades holding the largest share due to direct food contact approval breadth and printability for brand graphics. E-commerce application demand is expanding fastest as unboxing experience requirements and return-loop durability specifications tighten beyond traditional retail performance standards.
FDA cGMP and EU MDR traceability mandates are elevating serialization-ready carton specifications, particularly for pharmaceutical end-uses requiring tamper-evident closure integration. EPA and REACH frameworks restrict certain coating chemistries and recycled fiber contaminants, pushing converters toward water-based barrier treatments and controlled-substance-compliant ink systems. Stakeholders must monitor evolving extended producer responsibility fee structures and material recovery facility sorting compatibility standards that will determine viable substrate choices across regional supply footprints.
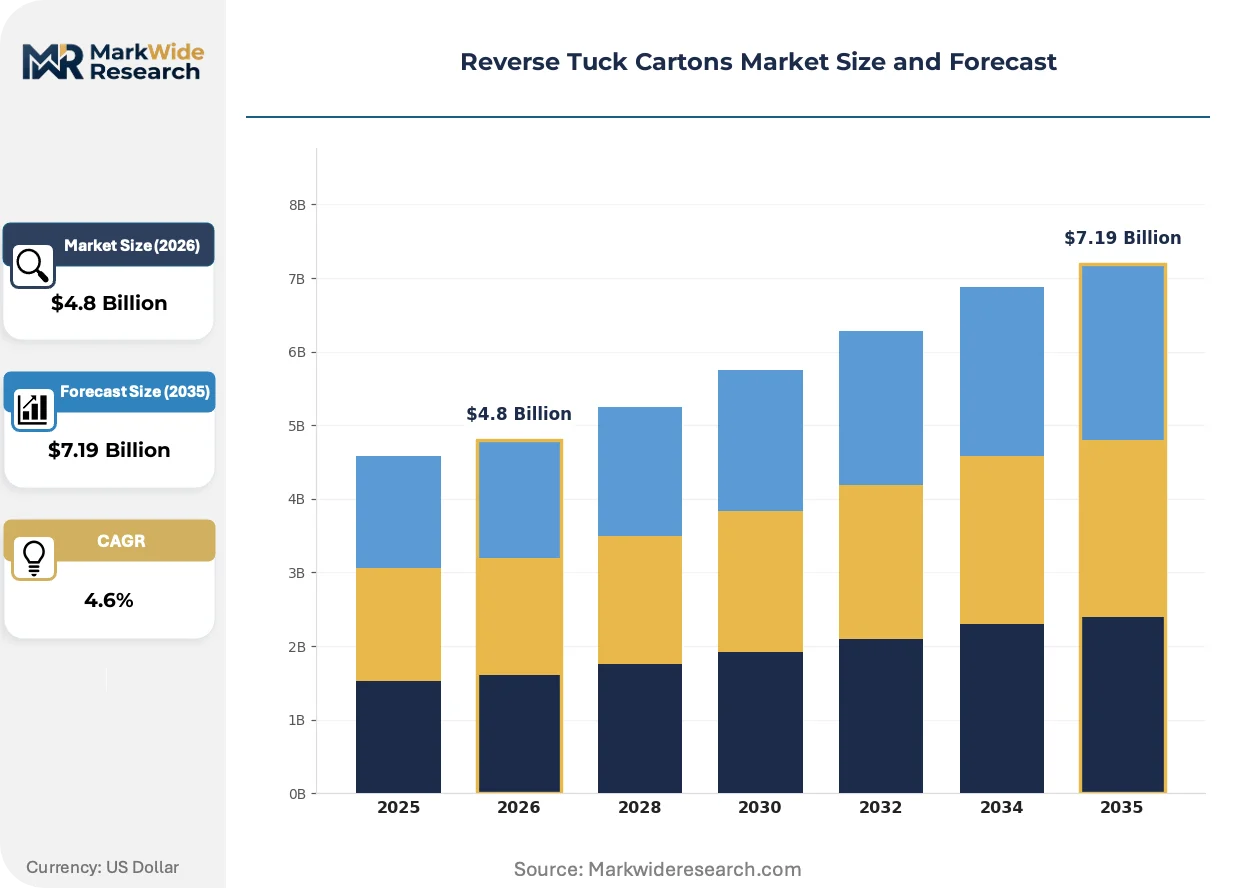
Market Dynamics
Pharmaceutical serialization mandates and e-commerce unboxing specifications are compressing traditional carton lead times while expanding performance requirements beyond historical retail benchmarks. Contract packers now specify dual-purpose structures that satisfy both automated filling lines and direct-to-consumer durability standards.
Growth Catalysts
- EU MDR Traceability Mandates:Medical device manufacturers must integrate tamper-evident closures with unique device identification serialization, expanding demand for certified carton formats across European packaging converters.
- India's Western Pharmaceutical Corridor:Manufacturing clusters from Mumbai to Ahmedabad are attracting contract packaging investment, driving localized carton procurement for export-oriented generic drug production.
- Water-Based Barrier Coatings:Food contact approval breadth for aqueous treatments is expanding direct-to-food applications without fluorochemical migration concerns.
Market Restraints
- Recycled Fiber Contaminant Thresholds:EPA and REACH frameworks restrict post-consumer content in pharmaceutical-grade board, elevating virgin fiber dependency and input cost exposure.
- Midwest Technician Shortages:Skilled die-cutting and gluing operator scarcity across United States converting plants is constraining near-term capacity expansion feasibility.
- Flexible Pouch Substitution:Stand-up pouches with resealable fitments are capturing shelf-stable food volume previously held by rigid paperboard formats.
Strategic Opportunities
- Child-Resistant Certification Gap:Pharmaceutical contract packers in Germany and the United States are expanding orders for certified formats, creating premium positioning for qualified converters.
- Return-Loop Durability Specifications:E-commerce merchants are specifying compression-tested structures that survive multiple handling cycles, opening technical differentiation beyond commodity board grades.
- Extended Producer Responsibility Fee Structures:Evolving material recovery facility sorting compatibility standards will reward substrate choices with established recycling pathways.
Industry Challenges
- cGMP Compliance Timeline Compression:FDA 21 CFR Part 210/211 validation requirements for pharmaceutical cartons are extending qualification periods for new supplier onboarding.
- Legacy Equipment Integration:Automated cartoning lines running at 200-plus units per minute require precise dimensional tolerances that challenge converters with mixed vintage machinery parks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Tuck Cartons Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverage, Cosmetics, Pharmaceuticals Material: Paperboard, Corrugated Board, Plastic, Metal Application: Retail Packaging, Industrial Packaging, E-commerce, Gift Packaging Size: Small, Medium, Large, Custom |
| Companies Covered | International Paper, WestRock, Smurfit Kappa Group, Mondi Group, Georgia-Pacific, DS Smith, Oji Holdings, Sonoco Products Company, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Tuck Cartons Market Evolving Landscape
Material lightweighting and digital print integration are restructuring competitive differentiation away from scale economies toward technical specification compliance and short-run responsiveness.
Lightweight kraftliner grades are supplanting traditional board weights in pharmaceutical and food applications. Brand owners specify basis weight reductions of 10-15% without sacrificing box compression strength. This shift compresses fiber consumption per thousand units while enabling freight cost savings.
REACH restrictions on certain coating chemistries are redirecting converter capital toward water-based barrier treatments and controlled-substance-compliant ink systems. The industrial consequence is elevated capital intensity for coating line retrofits. Pharmaceutical end-uses are responding with accelerated supplier qualification audits to secure compliant supply ahead of enforcement phase-ins.
Consolidated buying desks at major pharmaceutical contract packers are compressing supplier rosters and extending quality agreement terms. Regional sheet-feeding operations are displacing merchant distributor intermediaries in procurement channels. This concentration is most visible in Germany and the United States where child-resistant certification requirements filter qualified suppliers.
Reverse Tuck Cartons Market Segmentation
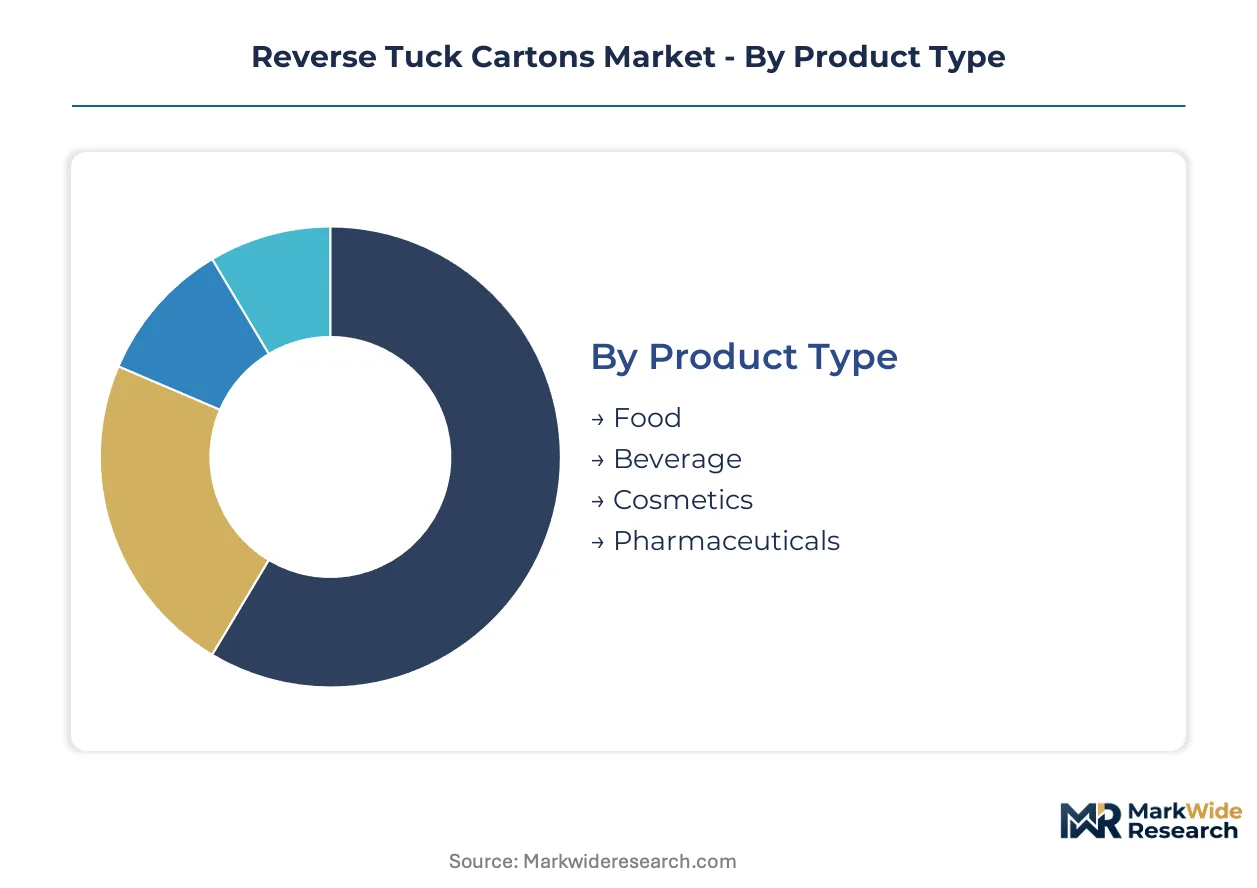
Reverse tuck carton segmentation reflects divergent compliance burdens across end-uses. FDA cGMP and EU MDR traceability mandates create tiered specification requirements that reshape material selection and print technology choices by application.
Product Type:
Regulatory stringency separates pharmaceutical requirements from consumer segments.
- Pharmaceuticals:Child-resistant certification and tamper-evident closure integration dominate specifications. German and United States contract packers are expanding orders for certified formats that satisfy FDA 21 CFR Part 210/211 and EU MDR serialization mandates.
- Food:Direct food contact approval breadth drives paperboard grade selection. Water-based barrier coatings are expanding applications without fluorochemical migration concerns under EPA and REACH frameworks.
- Beverage:Moisture resistance specifications favor coated board treatments for shelf-stable liquid containment.
- Cosmetics:Premium print surfaces and rigid structure support brand differentiation at retail shelf.
Established volume favors Food; emerging adoption favors Pharmaceuticals.
Material:
Cost tier positioning determines fiber sourcing and coating capital intensity.
- Paperboard:Lightweight kraftliner grades enable 10-15% basis weight reduction without sacrificing box compression strength. Mondi Group and WestRock sustain integrated supply that buffers fiber cost swings.
- Corrugated Board:Return-loop durability specifications from e-commerce merchants favor compression-tested structures surviving multiple handling cycles.
- Plastic:Barrier performance exceeds fiber-based alternatives for moisture-sensitive contents.
- Metal:Premium positioning supports gift and collectible applications requiring rigid protection.
Cost efficiency concentrates in Paperboard; technical differentiation concentrates in Corrugated Board.
Application:
Customer type separates automated filling line requirements from direct-to-consumer durability standards.
- E-commerce:Unboxing experience requirements and return-loop durability specifications exceed traditional retail benchmarks. Dual-purpose structures now satisfy both automated filling and direct-to-consumer handling.
- Retail Packaging:Rotary die-cutting precision enables 200-plus units per minute on standard cartoning equipment.
- Industrial Packaging:Bulk containment specifications prioritize structural integrity over print quality.
- Gift Packaging:Premium substrates and finishing treatments support seasonal demand concentration.
Volume scale anchors Retail Packaging; specification intensity anchors E-commerce.
Size:
Volume throughput separates standardized formats from customized production economics.
- Custom:Digital print integration enables short-run responsiveness for pharmaceutical serialization and regional brand variants. Skilled die-cutting technician shortages constrain near-term capacity expansion for complex formats.
- Small:Unit dose and sample applications concentrate in pharmaceutical and cosmetics segments.
- Medium:Standard retail shelf dimensions dominate food and beverage procurement.
- Large:Multi-unit retail and industrial applications require enhanced compression strength specifications.
Procurement scale favors Medium; margin expansion favors Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP standards anchor United States demand, while EU MDR traceability mandates reshape European procurement. India's western pharmaceutical corridor and China's e-commerce logistics networks concentrate emerging volume.
United States
Pharmaceutical contract packers in New Jersey and North Carolina are expanding orders for child-resistant certified formats. FDA 21 CFR Part 210/211 validation requirements extend qualification periods for new supplier onboarding. Midwestern converting plants face skilled die-cutting technician shortages that unwind near-term capacity expansion plans.
Germany
Medical device manufacturers must integrate tamper-evident closures with unique device identification serialization under EU MDR. ECHA REACH frameworks restrict certain coating chemistries, pushing converters toward water-based barrier treatments. The Rhine-Ruhr industrial region anchors European supply through recycled containerboard networks and regional sheet-feeding operations.
India
Manufacturing clusters from Mumbai to Ahmedabad attract contract packaging investment for export-oriented generic drug production. CDSCO traceability mandates align with international serialization standards. The western pharmaceutical corridor drives localized carton procurement as pharmaceutical contract packers expand facility footprints.
China
E-commerce merchants specify compression-tested structures surviving multiple handling cycles for return-loop durability. SAMR packaging standards and GB quality frameworks regulate material traceability. The Yangtze River Delta concentrates converting capacity serving domestic e-commerce logistics and cross-border retail fulfillment.
Japan
PMDA pharmaceutical serialization requirements elevate specifications for tamper-evident closure integration. METI sustainability guidelines promote lightweight kraftliner adoption to reduce fiber consumption per thousand units. The Kanto region around Tokyo maintains precision converting operations for high-specification pharmaceutical and cosmetics applications.
Reverse Tuck Cartons Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the reverse tuck cartons market. Integrated mill-converting operations buffer fiber cost swings through captive supply chains, while specialized sheet-feeders compete on short-run responsiveness and regional logistics. Three archetypes dominate: North American integrated giants with broad mill networks, European recycled fiber specialists with circular economy positioning, and lightweight material innovators reducing basis weight without sacrificing compression strength. Competitive moves concentrate on coating line retrofits for regulatory compliance and strategic partnerships with pharmaceutical contract packers seeking child-resistant certification.
Among North American integrated players, WestRock and Georgia-Pacific exemplify the scale-driven archetype with broad mill and converting integration. Mondi Group occupies a position within the lightweight innovation tier, representing technical differentiation through kraftliner grades that enable freight cost savings. These three anchors illustrate how competitive positioning separates fiber cost buffers, regulatory compliance enablers, and specification-driven premium positioning across the market structure.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Smurfit Kappa Group |
| Mondi Group |
| Georgia-Pacific |
| DS Smith |
| Oji Holdings |
| Sonoco Products Company |
| Packaging Corporation of America |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between pharmaceutical contract packers and certified converters lock in both virgin fiber supply access and price visibility across the 4.60% CAGR expansion window. These structures insulate qualified suppliers from spot market volatility while binding buyers to minimum volume commitments that justify coating line retrofits for FDA cGMP and EU MDR compliance.
Pricing Analysis
Price spreads between German and United States pharmaceutical-grade cartons exceed those for food-contact formats due to child-resistant certification scarcity and EU MDR serialization requirements. Three-tier pricing structure across premium certified, standard compliant, and economy non-pharmaceutical levels separates qualified converters from commodity board suppliers. Cost compression in economy tiers is intensifying because flexible pouch substitution captures shelf-stable food volume. Pharmaceutical contract packers show least price sensitivity given regulatory qualification barriers, while food brand owners negotiate aggressively on virgin fiber pass-through.
Supply Chain Analysis
Strait of Malacca transit routes underpin Asia-Pacific containerboard flows to India's western pharmaceutical corridor from Mumbai to Ahmedabad. Geographic supply concentration centers on United States integrated mill networks, German recycled containerboard operations, and Chinese kraftliner capacity. Raw material dependencies draw from bleached virgin pulp, water-based barrier coating chemistries, and child-resistant closure hardware. Single-source vulnerability runs through Midwestern United States die-cutting technician shortages that constrain near-term capacity expansion. Distribution runs through regional sheet-feeding operations displacing merchant distributor intermediaries in procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment defensive moat where FDA 21 CFR Part 210/211 and EU MDR qualification periods create switching costs that lock in incumbent supplier relationships. Certification scarcity functions as the structural barrier protecting margin pools.
For Market Incumbents: Fortify position by accelerating child-resistant certification investments ahead of EU MDR enforcement phase-ins and securing captive virgin fiber supply through backward integration into bleached pulp sourcing. Flexible pouch substitution in shelf-stable food segments threatens volume retention, making pharmaceutical contract packer relationship depth the priority defensive lever. For New Entrants and Emerging Players: Differentiate on short-run digital print responsiveness for pharmaceutical serialization and regional brand variants where skilled die-cutting technician shortages constrain incumbent capacity expansion. India's western pharmaceutical corridor from Mumbai to Ahmedabad represents the most penetrable geography given localized procurement trends and CDSCO traceability alignment with international standards. Target e-commerce return-loop durability specifications as the go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated mill-converting operations with captive fiber supply and established pharmaceutical qualification portfolios. Long-term viability over the mid-decade window favors converters with coating line retrofit completion and water-based barrier treatment approval breadth. Acquisition target archetype: regional sheet-feeders with EU MDR certification progress and proximity to German medical device manufacturers. Watch FDA cGMP validation timeline compression as the inflection indicator for supplier roster consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Child-Resistant Certification Investment | EU MDR and FDA mandates expand addressable market for qualified converters. |
| Water-Based Barrier Coating Retrofit | ECHA REACH restrictions redirect capital toward compliant treatment systems. |
| Regional Sheet-Feeding Expansion | Proximity to India's western pharmaceutical corridor reduces logistics exposure. |
| Lightweight Kraftliner Adoption | Mondi Group and WestRock integration models demonstrate freight cost savings. |
| Digital Print Integration | Short-run responsiveness captures pharmaceutical serialization and brand variant demand. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with pharmaceutical contract packers, die-cutting technicians, coating line operators, and procurement directors at German medical device manufacturers; and secondary validation through FDA 21 CFR filings, EMA MDR guidance documents, CDSCO traceability circulars, and customs trade data on containerboard flows. Bottom-up volume estimates from converting capacity utilization and top-down demand segmentation from end-use procurement patterns were triangulated for cross-verification.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, material grade, application channel, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of pharmaceutical serialization mandate implementation schedules and e-commerce logistics network expansion. Industry-specific forecast inputs incorporated virgin fiber price indices and water-based coating approval timelines under EPA and REACH frameworks.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity and stable Midwestern United States labor availability would require recalibration. Forecasts reflect documented assumptions regarding child-resistant certification adoption curves and flexible pouch substitution rates in food applications. Practitioners should keep alternative scenarios live as CDSCO traceability mandate alignment and SAMR packaging standard evolution reshape procurement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Mailers Market
Cartons
Microwaveable Carton Market
Cartons
Global Hand Carton Sealers Market
Cartons
Beverage Cartons Market
Cartons
Luxury Folding Carton Market
Cartons
Global Crash Lock Bottom Cartons Market
Cartons
Twist Opening Cartons Market
Cartons
XXL Packaging Market
Cartons
Cupcake Box Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Carton Sealer Machine Market
Cartons
Carton Form Fill Seal Machine Market
Cartons
Metallized Folding Cartons Market
Cartons
Carton Bottle Market
Cartons
Cardboard Crates Market