
 Dye-Sublimation Printing Machines Market | 2026-2036
Dye-Sublimation Printing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Dye-Sublimation Printing Machines Market Foresight
Skilled technician availability is unwinding across the dye-sublimation service sector, forcing print shops to favor automated large-format systems over labor-intensive setups. Epson leverages its piezoelectric printhead ecosystem to sustain margins in high-volume textile operations. Mimaki dominates the Japanese and Southeast Asian markets through precision color management and dedicated dye-sub ink chemistries.
Dye-sublimation printing machines transfer solid dye particles onto polyester-based substrates through controlled heat and pressure, typically operating at 350-400°F to achieve permanent, photorealistic color bonding without liquid ink residue. Large format systems anchor the installed base for soft-signage and home-textile production, while direct-to-fabric technology is displacing transfer-paper workflows in apparel hubs seeking to cut per-unit material waste. Desktop units occupy the entry-tier for promotional products and small-batch customization, though margin pools concentrate in industrial-class machines serving sportswear customization lines.
EPA chemical safety standards and REACH registration requirements in Europe are restricting volatile organic compound content in sublimation inks, pushing OEMs toward water-based and bio-derived formulations. FDA indirect food-contact rules in the US also constrain promotional-product applications involving kitchen textiles and serving accessories. Stakeholders must monitor how dual carbon goals in China and evolving ESG disclosure frameworks in the EU reshape capital allocation toward low-energy curing systems and closed-loop ink supply models.
Market Dynamics
Skilled technician scarcity across textile printing hubs is compressing equipment selection criteria toward automated large-format systems that reduce manual calibration demands and shift labor requirements from machine operation to file preparation workflows.
Growth Catalysts
- Sportswear Customization:Team-uniform suppliers and apparel decorators in China's Zhejiang corridor are expanding installed capacity to capture on-demand production contracts from professional leagues and amateur athletic associations.
- REACH Compliance Evolution:ECHA registration requirements for volatile organic compounds in sublimation inks are accelerating water-based formulation adoption among European OEMs seeking sustained market access.
- Direct-to-Fabric Migration:Heat-transfer paper elimination through direct-to-fabric dye-sub technology is cutting per-unit material waste by half in high-volume polyester textile operations.
Market Restraints
- Piezoelectric Printhead Supply Concentration:Precision MEMS fabrication capacity clusters in Japanese and German supplier networks, creating single-source vulnerability for industrial-class machine OEMs.
- EPA Chemical Safety Friction:Evolving EPA standards for per- and polyfluoroalkyl substances in ink chemistries are forcing reformulation cycles that extend product certification timelines.
- Latex and UV-Curable Substitution:Wide-format latex printers are capturing soft-signage applications previously served by dye-sub systems through broader substrate compatibility and room-temperature operation.
Strategic Opportunities
- Dual Carbon Alignment in China:MEE enforcement of provincial energy-intensity targets is creating preferential financing for low-curing-temperature dye-sub systems in Jiangsu and Guangdong manufacturing zones.
- Home Textile Direct Production:Curtain and upholstery fabricators are bypassing wholesale converters by installing mid-format dye-sub units for made-to-measure consumer channels.
- ESG Disclosure Tailwinds:EU CSRD reporting requirements on Scope 3 emissions are pushing brand owners toward closed-loop ink supply contracts with documented recycling rates.
Industry Challenges
- Color Profile Engineering Talent Gap:ICC profile development for multi-head array calibration requires specialized expertise that print shops struggle to recruit outside major metropolitan design centers.
- Legacy RIP Software Integration:Raster image processor upgrades for variable-data printing are creating workflow friction for decorators operating mixed-vintage equipment fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dye-Sublimation Printing Machines Market |
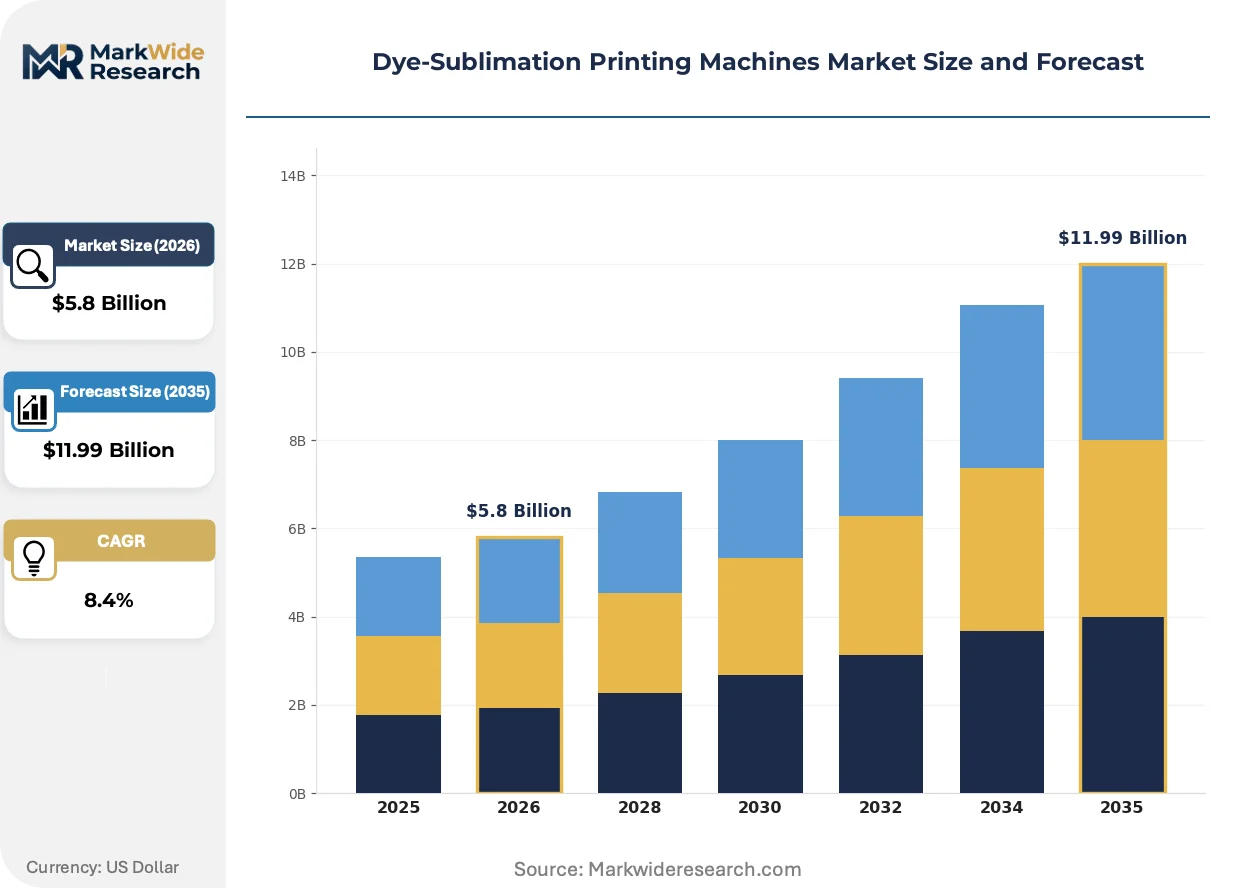
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Large Format, Desktop, Industrial, Mini End User: Apparel, Home Textiles, Promotional Products, Signage Technology: Inkjet, Thermal, Dye-Transfer, Direct-to-Fabric Application: Textile Printing, Artwork Reproduction, Sportswear Customization, Interior Décor |
| Companies Covered | Epson, Mimaki, Roland, Sawgrass, HP, Brother, Canon, Winnerjet, Disen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dye-Sublimation Printing Machines Market Shifts & Advancements
Equipment architecture is pivoting toward modularity and energy efficiency as regulatory pressure and labor constraints simultaneously reshape capital expenditure priorities across the installed base.
Single-pass printhead arrays with fixed nozzle positioning are miniaturizing the physical footprint of industrial dye-sub systems while maintaining throughput parity with multi-pass gantries. Soft-signage producers in Turkey and Mexico are adopting these compact configurations to sidestep facility expansion costs. The form-factor reduction is enabling distributed production nodes closer to end consumers, compressing logistics lead times for time-sensitive promotional campaigns.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon refrigerants are indirectly pressuring heat-press manufacturers to develop alternative thermal management systems for calender units. Industrial laundries and textile finishers operating integrated dye-sub lines face retrofit decisions as service refrigerant costs escalate. German and Italian equipment suppliers are responding with closed-loop oil-based heating circuits that eliminate vapor-compression cooling entirely.
Brand-owner sustainability scorecards are reconfiguring supplier qualification criteria toward documented carbon intensity per square meter printed. Polyester fabricators serving European fashion houses must now submit lifecycle assessments alongside sample submissions. Procurement teams in Amsterdam and Milan are prioritizing dye-sub decorators with renewable energy certificates and water-based ink portfolios, marginalizing conventional solvent-dependent operations regardless of unit pricing.
Dye-Sublimation Printing Machines Market Segmentation
Segmentation reveals how substitution threats from latex and UV-curable systems concentrate against specific machine classes and end-use configurations. Procurement patterns diverge sharply between high-volume textile converters seeking direct-to-fabric efficiency and promotional decorators prioritizing desktop flexibility.
Product Type:
Substitution pressure from wide-format latex printers hits desktop and mini segments hardest, while industrial-class dye-sub systems defend position through speed advantages on polyester substrates.
- Large Format:These systems deploy multi-head piezoelectric arrays across 1.6-3.2 meter print widths, serving soft-signage producers and home-textile converters. China's Zhejiang corridor concentrates installed capacity for curtain and upholstery fabricators supplying European retail chains. EPA chemical safety standards on per- and polyfluoroalkyl substances extend certification timelines for ink formulations used in these machines.
- Industrial:Single-pass fixed-nozzle architectures achieve throughput parity with multi-pass gantries at reduced physical footprint. Sportswear customization lines in Jiangsu manufacturing zones favor these configurations for on-demand team uniform production. MEE enforcement of provincial energy-intensity targets creates preferential financing for low-curing-temperature variants.
- Desktop:Entry-tier units occupy promotional products and small-batch customization workflows. Margin compression from Chinese OEMs intensifies price competition in this tier.
- Mini:Compact systems target hobbyist decorators and micro-businesses. REACH compliance costs for ink chemistry documentation disadvantage smaller operators in this segment.
Large Format anchors the volume base while Industrial gains share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive textile converters from asset-light promotional decorators with divergent equipment financing profiles.
- Apparel:Direct-to-fabric technology eliminates transfer paper waste in polyester garment production. Zhejiang-based team-uniform suppliers expand capacity to capture professional league contracts. ESG disclosure requirements from EU brand owners push decorators toward closed-loop ink supply models.
- Signage:Soft-signage applications face encroachment from latex printers with broader substrate compatibility. Turkish and Mexican producers adopt compact single-pass configurations to avoid facility expansion costs.
- Home Textiles:Curtain and upholstery fabricators install mid-format units for made-to-measure consumer channels, bypassing wholesale converters.
- Promotional Products:Desktop dye-sub systems serve kitchen textiles and serving accessories under FDA indirect food-contact constraints. Reformulation cycles for compliant inks extend product development timelines.
Apparel commands the highest equipment investment intensity while Home Textiles expands most quickly through distributed production nodes.
Technology:
Application maturity separates established inkjet workflows from emerging direct-to-fabric architectures with divergent skill requirements.
- Inkjet:Piezoelectric printhead ecosystems dominate installed base economics. Japanese and German MEMS fabrication networks create supply concentration vulnerability for industrial-class OEMs. Water-based formulation adoption accelerates under ECHA registration requirements.
- Direct-to-Fabric:Heat-transfer paper elimination cuts per-unit material waste by half in high-volume operations. Color profile engineering talent scarcity constrains adoption outside major metropolitan design centers.
- Thermal:Sublimation ribbon systems occupy niche applications with lower capital barriers. Limited throughput constrains deployment in production-scale environments.
- Dye-Transfer:Traditional calender-based workflows persist in legacy installations. EU F-Gas Regulation phase-down schedules pressure retrofit decisions for refrigerant-dependent thermal management.
Inkjet retains the broadest installed base while Direct-to-Fabric climbs the fastest as waste reduction targets harden.
Application:
Customer type divergence separates specification-driven B2B procurement from price-sensitive promotional workflows with distinct margin structures.
- Textile Printing:Polyester fabricators serving European fashion houses submit lifecycle assessments alongside sample submissions. Procurement teams in Amsterdam and Milan prioritize renewable energy certificates and water-based ink portfolios.
- Sportswear Customization:On-demand production contracts from amateur athletic associations drive capacity expansion. Skilled technician scarcity compresses selection criteria toward automated calibration systems.
- Interior Décor:Wall covering and furnishing applications demand precision color matching for design-specified palettes. ICC profile development expertise concentrates in major metropolitan centers.
- Artwork Reproduction:Photorealistic color bonding requirements favor dye-sub permanence over aqueous alternatives. Limited volume constrains dedicated equipment investment.
Textile Printing anchors revenue concentration while Sportswear Customization shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes dye-sublimation equipment primarily for high-volume textile conversion, while the United States and Germany emphasize regulatory-compliant promotional and industrial applications with stricter chemical safety protocols.
China
Zhejiang province's textile manufacturing corridor drives industrial-class machine demand for sportswear customization and home textile production. MEE enforcement of provincial dual carbon goals creates preferential financing for low-curing-temperature systems in Jiangsu and Guangdong zones. Hangzhou-based decorators expand direct-to-fabric capacity to serve European fashion house contracts.
United States
Team-uniform suppliers and promotional product decorators anchor equipment demand across the Southeast and Midwest manufacturing belts. EPA chemical safety standards on per- and polyfluoroalkyl substances extend ink reformulation certification timelines. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate mid-format system installations for on-demand athletic apparel production.
Germany
Industrial laundries and textile finishers drive demand for closed-loop thermal management systems amid EU F-Gas Regulation phase-down schedules. ECHA REACH registration requirements accelerate water-based ink formulation adoption among OEMs. Bavaria and North Rhine-Westphalia host precision MEMS fabrication networks supplying piezoelectric printhead components.
Japan
Precision color management requirements from soft-signage exporters sustain demand for dedicated dye-sub ink chemistries and automated calibration systems. METI industrial efficiency standards favor single-pass fixed-nozzle architectures with reduced energy intensity. Nagoya and Osaka metropolitan areas concentrate technical service infrastructure for Southeast Asian export markets.
Turkey
Soft-signage producers adopt compact single-pass configurations to serve European retail chains without facility expansion costs. The country's national environmental regulator enforces volatile organic compound limits in textile finishing operations. Istanbul and Izmir industrial zones concentrate mid-format installations for curtain and upholstery fabricators.
Dye-Sublimation Printing Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the dye-sublimation printing machines market. Japanese and German OEMs control precision MEMS printhead supply chains, while Chinese fabricators compete on equipment cost at the desktop and mini segments. Strategic archetypes divide between piezoelectric ecosystem integrators, direct-to-fabric technology specialists, and regional cost-optimized assemblers. Competitive moves center on vertical integration into ink formulation supply and geographic expansion through localized technical service networks.
Within the integrated leader tier, Epson and Mimaki exemplify piezoelectric ecosystem dominance through captive printhead technology and dedicated ink chemistries. Roland occupies a position among precision wide-format specialists serving soft-signage and promotional workflows. These three Japanese-origin companies anchor the premium equipment segment where margin pools concentrate in industrial-class configurations.
| Leading Market Players |
|---|
| Epson |
| Mimaki |
| Roland |
| Sawgrass |
| HP |
| Brother |
| Canon |
| Winnerjet |
| Disen |
| Others |
Supply & Pricing Matrix
Long-term ink supply contracts with take-or-pay provisions dominate procurement between European apparel decorators and Japanese OEMs, locking in price visibility for piezoelectric printhead arrays while insulating buyers from ECHA REACH registration cost spikes. These arrangements concentrate margin protection among industrial-class machine operators in Germany and Italy who face volatile organic compound compliance deadlines.
Pricing Analysis
Contract-based long-term offtake structures govern industrial-class equipment transactions, while spot purchasing persists for desktop tier consumables. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in the desktop segment is intensifying because Chinese OEMs expand manufacturing scale in Zhejiang. Promotional product decorators show highest price sensitivity, whereas team-uniform suppliers prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Port congestion on transpacific lanes from Yokohama to Long Beach elevates inbound logistics costs for MEMS printhead components destined for US assembly plants. Precision fabrication capacity clusters in Japan and Germany, with secondary sourcing from Taiwan. Raw material dependencies span silicon wafers, piezoelectric ceramics, and specialized polyester substrates. Single-source vulnerability concentrates in Japanese MEMS foundries serving Epson and Mimaki ecosystems. Distribution runs through authorized dealer networks with technical certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a post-pandemic equipment replacement cycle that favors capital deployment toward automated direct-to-fabric systems. Sportswear customization demand from amateur athletic associations provides cyclical justification for capacity expansion.
For Market Incumbents: Secure captive supply agreements for piezoelectric printhead arrays before MEMS fabrication capacity tightens further. Invest in water-based ink formulation R&D to preempt EPA per- and polyfluoroalkyl substance restrictions. Vertical integration into closed-loop ink recycling services defends margin pools against emerging Chinese cost competitors. For New Entrants and Emerging Players: Anchor in the mini segment serving hobbyist decorators and micro-businesses where REACH compliance documentation costs disadvantage smaller operators. Target Turkey and Mexico soft-signage producers seeking compact single-pass configurations without facility expansion. Pursue private-label partnerships with Zhejiang textile equipment distributors for rapid channel access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision color management specialists with proprietary ICC profile libraries. Five-to-ten year viability hinges on regulatory adaptation speed rather than pure manufacturing scale. Acquisition candidates should demonstrate documented closed-loop ink supply contracts with European fashion houses. Watch EPA chemical safety standard evolution as the primary inflection signal for reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Formulation | ECHA REACH compliance accelerates water-based chemistry investment among German OEMs. |
| Single-Pass Fixed-Nozzle Architecture Deployment | MEE dual carbon enforcement in Jiangsu creates preferential financing for low-energy systems. |
| Closed-Loop Ink Supply Contract Expansion | EU CSRD Scope 3 disclosure requirements push Amsterdam procurement teams toward documented recycling rates. |
| Compact Configuration Product Line Extension | Turkish soft-signage producers adopt reduced-footprint systems to sidestep facility expansion costs. |
| Technical Service Network Localization | Southeast Asian export markets from Nagoya demand calibrated support infrastructure for precision color management. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with textile print shop owners, OEM product managers, ink formulation chemists, and aftermarket service technicians. Secondary validation drew from EPA chemical safety filings, ECHA REACH registration databases, customs trade records for MEMS components, and SEC equipment manufacturer disclosures. Bottom-up installed base estimates and top-down market sizing were triangulated against production capacity announcements from Zhejiang and Guangdong manufacturing zones.
Across the analysis window, volume and value outputs reflect segmentation modeling by product type, end-use application, technology architecture, and regional regulatory cluster. CAGRs were derived from trend extrapolation of sportswear customization contract flows and direct-to-fabric adoption curves. Forecast inputs incorporated MEE provincial energy-intensity targets and EU F-Gas Regulation phase-down schedules for thermal management systems.
Underlying assumptions cover sustained polyester substrate demand, stable piezoelectric printhead supply from Japanese MEMS networks, and incremental EPA chemical safety enforcement without abrupt formulation bans, with deviation risk concentrated in trade policy shifts affecting China-US equipment flows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Card Printer Ribbons Market
Printing Technology
Digital Graphic Printing Market
Printing Technology
Variable Data Printing Market
Printing Technology
Global Wireless Printers Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Digital Production Printer Market
Printing Technology
Printing Machinery Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Large Format Printer Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Commercial Printer Market