
 Large Character Printers Market | 2026-2036
Large Character Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Large Character Printers Market Foresight
The distributor-to-end-user channel is narrowing as direct OEM engagement replaces traditional equipment resellers. Videojet Technologies leverages its captive service network to sustain aftermarket revenue streams. Domino Printing Sciences anchors European market presence through localized manufacturing. Markem-Imaje differentiates with integrated software-to-hardware traceability systems.
Large character printers are industrial marking systems that produce alphanumeric codes, barcodes, and graphics at character heights typically exceeding 12 millimeters on porous and non-porous substrates. These systems employ piezoelectric or valve-based inkjet architectures to deliver solvent-based, water-based, or UV-curable inks for compliance labeling, batch coding, and logistics identification across high-speed production environments. Inkjet systems occupy the dominant share of product type revenue due to substrate versatility and lower total cost of ownership. High-speed printing technology commands premium positioning among technology segments, while the logistics end user category is expanding fastest as e-commerce fulfillment centers mandate real-time carton marking.
REACH chemical restrictions in Europe and FDA food contact material regulations in the United States constrain ink formulation choices and drive reformulation costs. OSHA workplace exposure limits and EPA volatile organic compound emissions standards further shape equipment design and facility compliance requirements. Stakeholders must monitor evolving chemical substance restrictions and assess regional certification gaps before committing to platform investments.
Market Dynamics
Food and beverage packaging lines are expanding printer deployments as traceability mandates tighten, while REACH chemical restrictions in Europe are pushing solvent-free ink formulations that reconfigure equipment specifications and supplier relationships.
Growth Catalysts
- E-commerce fulfillment mandates:Logistics operators in Germany's industrial corridor require real-time carton marking for automated sortation systems, driving hardware refresh cycles.
- REACH chemical restrictions:ECHA's evolving substance restrictions force ink reformulation toward water-based and UV-curable alternatives, creating replacement demand for compatible printheads.
- Piezoelectric inkjet architectures:These systems enable substrate versatility across porous and non-porous materials, reducing total cost of ownership for multi-product manufacturing lines.
Market Restraints
- Raw material concentration:Specialized piezoelectric ceramics and precision valve components concentrate among Japanese and German suppliers, exposing buyers to single-source fragility.
- Reformulation cost burden:FDA food contact material regulations and EPA volatile organic compound emissions standards impose recurring compliance expenditures that compress margins for mid-tier equipment vendors.
- Technical speed ceilings:Valve-based systems face throughput limitations above 300 meters per minute on non-porous substrates, constraining adoption in high-velocity beverage canning operations.
Strategic Opportunities
- Underpenetrated pharmaceutical serialization:India's CDSCO track-and-trace requirements for exported medicines create demand for large-character secondary packaging codes that integrate with aggregation systems.
- UV-curable ink convergence:Combination of LED curing arrays with inkjet deposition enables instant adhesion on recycled corrugated board, opening sustainable packaging applications.
- Direct OEM channel expansion:Equipment manufacturers bypass traditional distributors to capture aftermarket service revenue through captive technician networks.
Industry Challenges
- Specialized technician scarcity:Maintenance of piezoelectric printhead arrays requires expertise in fluid dynamics and electronics diagnostics that outpaces vocational training pipeline output.
- Legacy system integration friction:Brownfield manufacturing facilities face protocol mismatches between new inkjet controllers and existing SCADA architectures, extending deployment timelines.
- Certification timeline compression:OSHA workplace exposure assessments and EPA emissions permitting for solvent-based installations now average 14-18 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Character Printers Market |
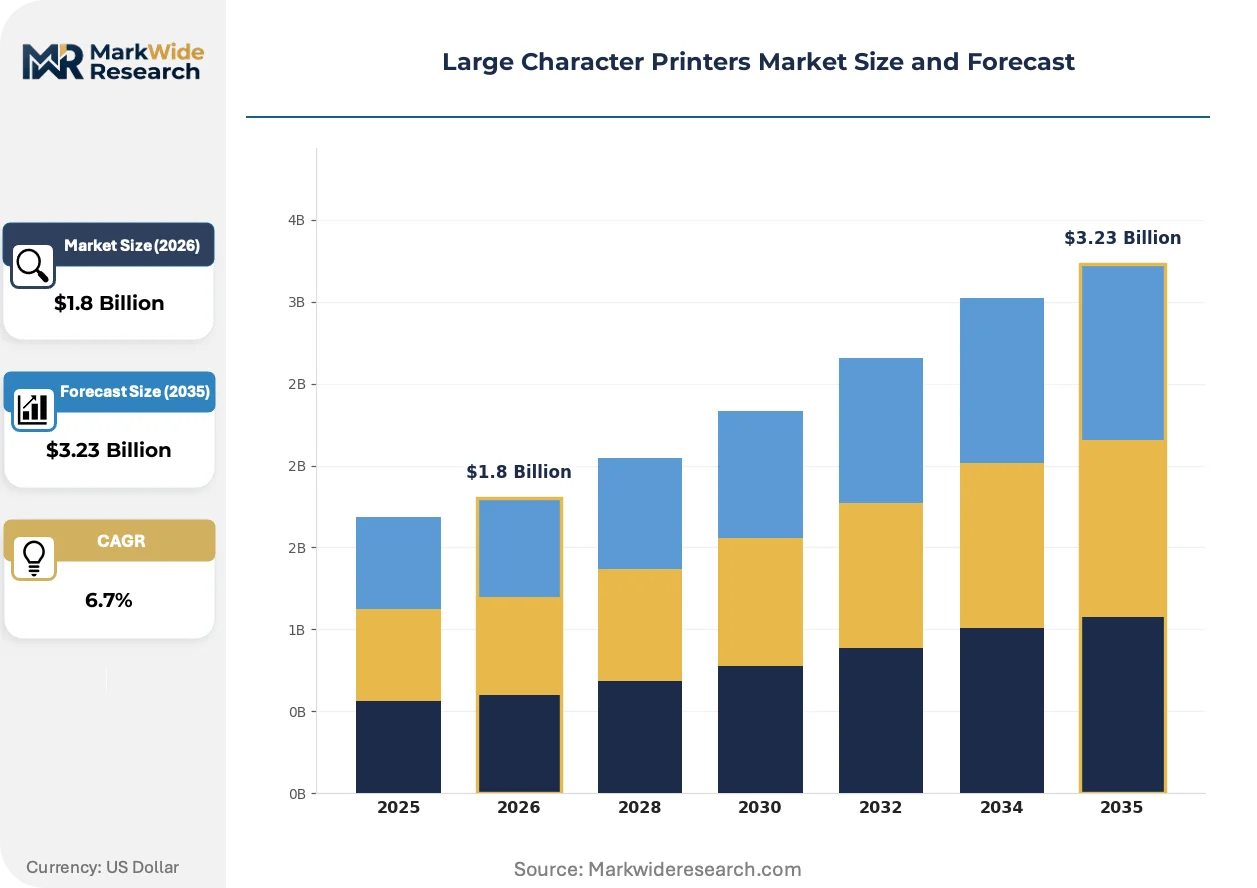
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet, Laser, Thermal, Dot Matrix Application: Packaging, Labeling, Signage, Advertising End User: Manufacturing, Retail, Transportation, Logistics Technology: Continuous Ink Supply, High-Speed Printing, Eco-Friendly, NFC Enabled |
| Companies Covered | Videojet Technologies, Domino Printing Sciences, Markem-Imaje, Hitachi Industrial Equipment Systems, Linx Printing Technologies, ITW Diagraph, Matthews International Corporation, Control Print, Macsa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Character Printers Market Shifts & Advancements
Software-to-hardware integration is redefining competitive differentiation as traceability requirements extend beyond simple marking into full supply chain visibility systems that synchronize with enterprise resource planning platforms.
UV-LED curing technology is collapsing the distinction between porous and non-porous substrate handling by enabling instant polymerization without thermal damage. Pharmaceutical contract packagers in Switzerland and Germany are adopting these systems at accelerated rates to meet EU Falsified Medicines Directive serialization deadlines. The technology is collapsing legacy thermal transfer and hot-stamp methods in applications requiring variable data and high-resolution graphics.
REACH authorization procedures under ECHA jurisdiction are constraining solvent-based ink chemistries containing N-methyl-2-pyrrolidone and other restricted substances. Industrial compounders must submit substitution plans or seek time-limited authorizations, elevating water-based and bio-derived formulation R&D budgets. German chemical formulators are most affected, with reformulated product portfolios now representing the majority of new registrations.
Buyer concentration among multinational consumer packaged goods corporations is compressing equipment vendor negotiation cycles and unbundling after-sales service contracts from hardware procurement. Third-party maintenance providers in the United States are capturing calibration and spare parts revenue previously retained by original manufacturers. This pattern is most visible in California and Illinois food processing corridors where facility engineering teams maintain multi-brand print fleets.
Large Character Printers Market Segmentation
Large character printer procurement varies sharply by operational environment. Substrate compatibility, line speed requirements, and regulatory exposure drive divergent technology choices across packaging, logistics, and manufacturing verticals.
Product Type:
Industrial marking demands span porous corrugated board, non-porous plastics, and coated metals, creating divergent hardware specifications.
- Inkjet:Piezoelectric and valve-based architectures deposit solvent-based, water-based, or UV-curable inks at character heights exceeding 12 millimeters. Food and beverage packaging lines in Germany's industrial corridor favor these systems for substrate versatility and lower total cost of ownership across multi-product manufacturing.
- Laser:Fiber and CO2 systems ablate or discolor substrates without consumables, eliminating ink compliance burdens. Pharmaceutical manufacturers in Switzerland adopt laser marking for permanent serialization codes under EU Falsified Medicines Directive requirements.
- Thermal:Direct thermal and thermal transfer methods apply heat-sensitive ribbons or coatings for variable data on labels and tags. Retail distribution centers deploy these for short-run carton identification with minimal setup time.
- Dot Matrix:Impact-based pin arrays strike ink ribbons onto porous surfaces, surviving dusty manufacturing environments where inkjet nozzles clog. Heavy industrial facilities in legacy steel and automotive plants maintain these for extreme durability.
Established volume favors Inkjet; emerging adoption favors Laser.
Application:
Functional requirements split between compliance-driven marking and visual communication objectives.
- Packaging:Batch codes, expiration dates, and barcodes on primary and secondary packaging must withstand supply chain abrasion. REACH chemical restrictions force reformulation toward water-based inks that reconfigure printhead specifications.
- Labeling:Variable data printing on adhesive labels integrates with automated applicators for pallet and case identification. Logistics operators in Germany require real-time carton marking synchronized with automated sortation systems.
- Signage:Large-format alphanumeric and graphic production for industrial safety and wayfinding demands UV-curable outputs for weather resistance. Construction and chemical processing facilities drive replacement cycles.
- Advertising:Point-of-sale and promotional displays utilize wide-format character printing for temporary campaign materials. Retail chains compress procurement cycles for seasonal promotional windows.
Compliance mandates concentrate investment in Packaging; e-commerce fulfillment is expanding most quickly in Labeling.
End User:
Operational scale and integration complexity create distinct procurement patterns across buyer categories.
- Manufacturing:Continuous production lines demand 24/7 reliability with minimal downtime for maintenance. FDA food contact material regulations and EPA volatile organic compound emissions standards shape equipment selection for US-based food processors.
- Retail:Distribution centers and fulfillment warehouses prioritize rapid deployment and multi-shift operability without specialized technician support. California and Illinois food processing corridors maintain multi-brand print fleets with third-party maintenance contracts.
- Transportation:Fleet marking and cargo identification require portable or fixed installations in harsh environmental conditions. Rail and intermodal operators specify equipment for temperature extremes and vibration exposure.
- Logistics:E-commerce fulfillment centers mandate real-time carton marking for automated sortation and track-and-trace visibility. Germany's industrial corridor anchors European demand as parcel volumes strain existing infrastructure.
Installed base concentration sits with Manufacturing; steepest expansion trajectory belongs to Logistics.
Technology:
Hardware architecture choices determine consumable economics, regulatory exposure, and integration complexity.
- Continuous Ink Supply:Bulk ink delivery systems reduce per-print cost and minimize operator intervention for high-volume operations. beverage canning lines above 300 meters per minute specify these configurations.
- High-Speed Printing:Piezoelectric printhead arrays achieve throughput rates that valve-based systems cannot match on non-porous substrates. Premium positioning reflects technical performance thresholds.
- Eco-Friendly:Water-based and bio-derived formulations respond to ECHA substance restrictions and EPA emissions standards. German chemical formulators allocate majority R&D budgets to reformulated portfolios.
- NFC Enabled:Near-field communication tags embedded in printed outputs enable smartphone-based verification and authentication. Pharmaceutical contract packagers adopt these for patient engagement and anti-counterfeiting layers.
Current procurement favors High-Speed Printing; regulatory pressure is accelerating fastest in Eco-Friendly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while procurement costs compress in India's emerging pharmaceutical packaging belt. This asymmetry reflects divergent regulatory stringency and supply chain maturity across manufacturing geographies.
Germany
REACH authorization procedures under ECHA jurisdiction constrain solvent-based ink formulations containing N-methyl-2-pyrrolidone. Food and beverage packaging lines in Bavaria and North Rhine-Westphalia are expanding piezoelectric inkjet deployments for multi-product manufacturing flexibility.
United States
FDA food contact material regulations and EPA volatile organic compound emissions standards shape equipment selection for food processors. California and Illinois food processing corridors maintain multi-brand print fleets with third-party maintenance contracts capturing aftermarket revenue.
India
CDSCO track-and-trace requirements for exported medicines create demand for large-character secondary packaging codes. Pharmaceutical contract packagers in Maharashtra and Gujarat are integrating serialization systems with aggregation infrastructure for EU market access.
Switzerland
EU Falsified Medicines Directive serialization deadlines drive accelerated adoption of UV-LED curing systems. Pharmaceutical manufacturers in Basel and Zurich are displacing legacy thermal transfer methods with inkjet deposition for variable data applications.
China
NMPA pharmaceutical serialization mandates and SAMR product traceability regulations expand compliance labeling requirements. E-commerce fulfillment centers in the Yangtze River Delta are mandating real-time carton marking for automated sortation systems.
Large Character Printers Market Competitive Landscape
Integrated systems specialists and component-focused fabricators split the market along the software-to-hardware integration frontier. The vendor base concentrates among established industrial marking conglomerates with captive service networks and regional specialists with localized manufacturing footprints. Three archetypes dominate: full-stack traceability providers, inkjet hardware pure-plays, and laser marking specialists diversifying into complementary deposition technologies. Competitive moves center on direct OEM channel expansion to capture aftermarket revenue and strategic partnerships for UV-curable ink formulation access.
Among US-based industrial conglomerates, Videojet Technologies and Matthews International Corporation exemplify the integrated systems archetype with extensive service infrastructure. Domino Printing Sciences anchors European market presence through localized manufacturing capabilities. These three occupy positions spanning the premium-to-mid-tier equipment spectrum, with differentiation converging on software-to-hardware traceability integration rather than pure deposition speed metrics.
| Leading Market Players |
|---|
| Videojet Technologies |
| Domino Printing Sciences |
| Markem-Imaje |
| Hitachi Industrial Equipment Systems |
| Linx Printing Technologies |
| ITW Diagraph |
| Matthews International Corporation |
| Control Print |
| Macsa |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese inkjet printhead manufacturing is compressing component costs while tightening margins for European system integrators, forcing pricing discipline that rewards captive service networks over hardware margins.
Pricing Analysis
The customization-premium spread between configured-to-order piezoelectric systems and standard valve-based configurations spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade (CE marking for EU pharmaceutical compliance vs industrial-grade alternatives) and after-sales service bundling. Cost compression in mid-tier equipment is intensifying because third-party maintenance providers capture calibration revenue previously retained by OEMs. Retail distribution centers exhibit highest price sensitivity due to multi-brand fleet standardization pressures, while pharmaceutical contract packagers show lowest sensitivity given serialization compliance deadlines.
Supply Chain Analysis
Extended payment terms from Japanese piezoelectric ceramic suppliers are straining working capital for European equipment assemblers, accelerating supply-chain finance facility adoption among mid-tier vendors. Geographic supply concentration draws from Japan (specialized ceramics), Germany (precision valve components), and China (printhead electronics). Raw material dependencies center on lead zirconate titanate ceramics, stainless steel valve bodies, and UV-LED curing arrays. Single-source vulnerability in Japanese ceramic feedstock exposes buyers to disruption. Distribution runs through direct OEM channels bypassing traditional equipment resellers, with captive technician networks capturing aftermarket revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as e-commerce fulfillment infrastructure investment rebounds from pandemic-era overbuild, with parcel volume growth in Germany's industrial corridor serving as the confirming demand signal.
For Market Incumbents: Insulate aftermarket revenue streams by deepening captive technician networks before third-party maintenance providers consolidate calibration and spare parts markets. Prioritize backward integration into UV-curable ink formulation to offset margin compression from REACH-driven solvent-based ink phase-outs. Lock in long-term supply agreements with Japanese ceramic suppliers to hedge single-source fragility.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical contract packaging belt where CDSCO track-and-trace requirements for exported medicines create demand for large-character secondary packaging codes with lower incumbent saturation. Target logistics operators in Germany's industrial corridor with hardware-as-a-service pricing to bypass capital expenditure approval cycles. Lead with software-to-hardware traceability integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across UV-LED curing system manufacturing as LED array costs decline and pharmaceutical adoption accelerates. Long-term viability favors full-stack traceability providers with captive service infrastructure over component-focused fabricators. Monitor ECHA authorization timeline compression for N-methyl-2-pyrrolidone as the inflection signal for ink formulation substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ink Formulation | German chemical formulators capture margin from REACH-driven solvent reformulation mandates. |
| Direct OEM Channel Expansion | Videojet Technologies and Domino Printing Sciences bypass distributors to retain aftermarket service revenue. |
| UV-LED Curing Technology Adoption | Swiss pharmaceutical manufacturers displace thermal transfer methods under EU Falsified Medicines Directive deadlines. |
| Software-to-Hardware Traceability Integration | Markem-Imaje differentiates through ERP-synchronized supply chain visibility systems. |
| Captive Technician Network Buildout | Equipment vendors address specialized maintenance scarcity outpacing vocational training pipeline output. |
Research Methodology
A spread of perspectives from plant engineers at food and beverage packaging lines, procurement leads at pharmaceutical contract packagers, aftermarket service heads at equipment OEMs, and regulatory affairs specialists at chemical formulators converged on the working assumptions. Primary interviews combined with secondary validation from ECHA substance restriction databases, FDA food contact material guidance documents, SEC filings of industrial conglomerates, and customs trade data for piezoelectric component flows. Bottom-up equipment shipment analysis triangulated against top-down end-use industry capital expenditure patterns.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled across product type (inkjet, laser, thermal, dot matrix), application (packaging, labeling, signage, advertising), end user (manufacturing, retail, transportation, logistics), and technology (continuous ink supply, high-speed printing, eco-friendly, NFC enabled). CAGRs were derived from regression analysis of historical shipment volumes against macroeconomic indicators and regulatory timeline assumptions. Industry-specific forecast inputs included REACH authorization procedure schedules and e-commerce fulfillment center buildout pipelines.
Stress conditions across raw material price volatility, regulatory timeline delays, and technician training pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about substitution elasticity for solvent-based inks and pharmaceutical serialization mandate enforcement intensity. Macroeconomic contraction, ECHA substance restriction acceleration, or breakthrough laser marking cost reductions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Large Format Printer Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Industrial Printer Market
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Variable Data Printing Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Automated Document Inserter (ADI) Market
Printing Technology
Global Microprinting Market
Printing Technology
Digital Production Printer Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Photo Printing Market
Printing Technology
ID Card Printers Market
Printing Technology
Card Printers Market
Printing Technology
Commercial Printer Market