
 Digital Notepad Market | 2026-2036
Digital Notepad Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Notepad Market Insights
Low-power reflective display technology is rewriting the fundamental architecture of digital notepads, replacing backlit LCD panels with bi-stable e-ink and cholesteric liquid crystal layers that draw power only during image updates. reMarkable AS anchors the premium segment through proprietary CANVAS display technology and vertical control over its Oslo-based hardware-software stack. Onyx International Inc. competes across multiple price tiers with Android-based tablets that support third-party annotation apps. Wacom Co., Ltd. leverages decades of electromagnetic resonance pen technology to dominate professional creative workflows where pressure sensitivity precision defines purchasing decisions.
A digital notepad is an electronic device or application that captures handwritten input through stylus or finger interaction, stores content in digital format, and synchronizes across platforms, typically employing display technologies with sub-30-millisecond refresh rates and pressure levels exceeding 4,096 distinct gradations for natural ink emulation. Smart Pens and Digital Paper categories lead current revenue generation by serving users who retain physical writing rituals while demanding cloud backup and searchable archives. Tablets represent the fastest-expanding structural segment as full-color LCD and OLED variants encroach on tasks previously reserved for dedicated e-ink devices. Software Apps command disproportionate margin attention from vendors seeking recurring subscription revenue rather than single hardware transactions.
FCC electromagnetic emissions standards in the United States, CE marking requirements under EU MDR and RoHS directives, and China's GB standards for electronic display devices collectively shape product certification costs and market access timelines for manufacturers. Japan's METI energy efficiency guidelines further constrain power budgets for devices targeting corporate procurement channels. Stakeholders must monitor how right-to-repair legislation across multiple jurisdictions forces redesigns of sealed-unit architectures into modular, serviceable form factors that alter both cost structures and brand loyalty dynamics.
Market Dynamics
Low-power reflective display technology is compressing refresh-rate performance gaps between e-ink and LCD architectures, forcing manufacturers to reposition around stylus latency and outdoor readability rather than panel type alone.
Growth Catalysts
- EU Green Deal right-to-repair mandates:Modular hardware designs extend device lifecycles and unlock upgrade revenue streams for manufacturers serving enterprise procurement channels.
- Hospital system digitization:Clinical documentation workflows in acute care settings demand paper-like writing surfaces that integrate with electronic health record systems.
- Cholesteric liquid crystal layers:Bi-stable display variants eliminate backlighting requirements entirely, slashing power budgets for field-deployed engineering teams.
Market Restraints
- E-ink display supply concentration:Single-source dependency on Taiwan-based panel fabrication creates vulnerability to geopolitical trade friction and capacity allocation decisions.
- Raw material cost volatility:Indium tin oxide prices fluctuate with semiconductor foundry demand, pressuring electromagnetic digitizer production economics.
- RoHS substance restrictions:Lead-free solder requirements complicate flexible PCB assembly for foldable form factors, extending qualification timelines.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract assembly investment for export-oriented mid-tier devices targeting price-sensitive professional segments.
- Convergence of e-ink with front-lighting arrays:Hybrid architectures enable dark-environment usability without sacrificing daylight readability, opening maritime and underground mining applications.
- Direct-to-enterprise subscription bundles:Hardware-plus-software recurring contracts bypass retail channel fragmentation and capture lifetime value from institutional buyers.
Industry Challenges
- Electromagnetic resonance calibration expertise:Scarce engineering talent for pressure-level tuning across temperature ranges limits in-house R&D scaling for new entrants.
- FCC Part 15 certification timelines:Electromagnetic emissions testing for stylus transceivers adds months to product launch schedules, compressing competitive windows.
- Legacy EMR protocol fragmentation:Wacom's proprietary digitizer standards create integration friction for third-party stylus vendors seeking cross-device compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Notepad Market |
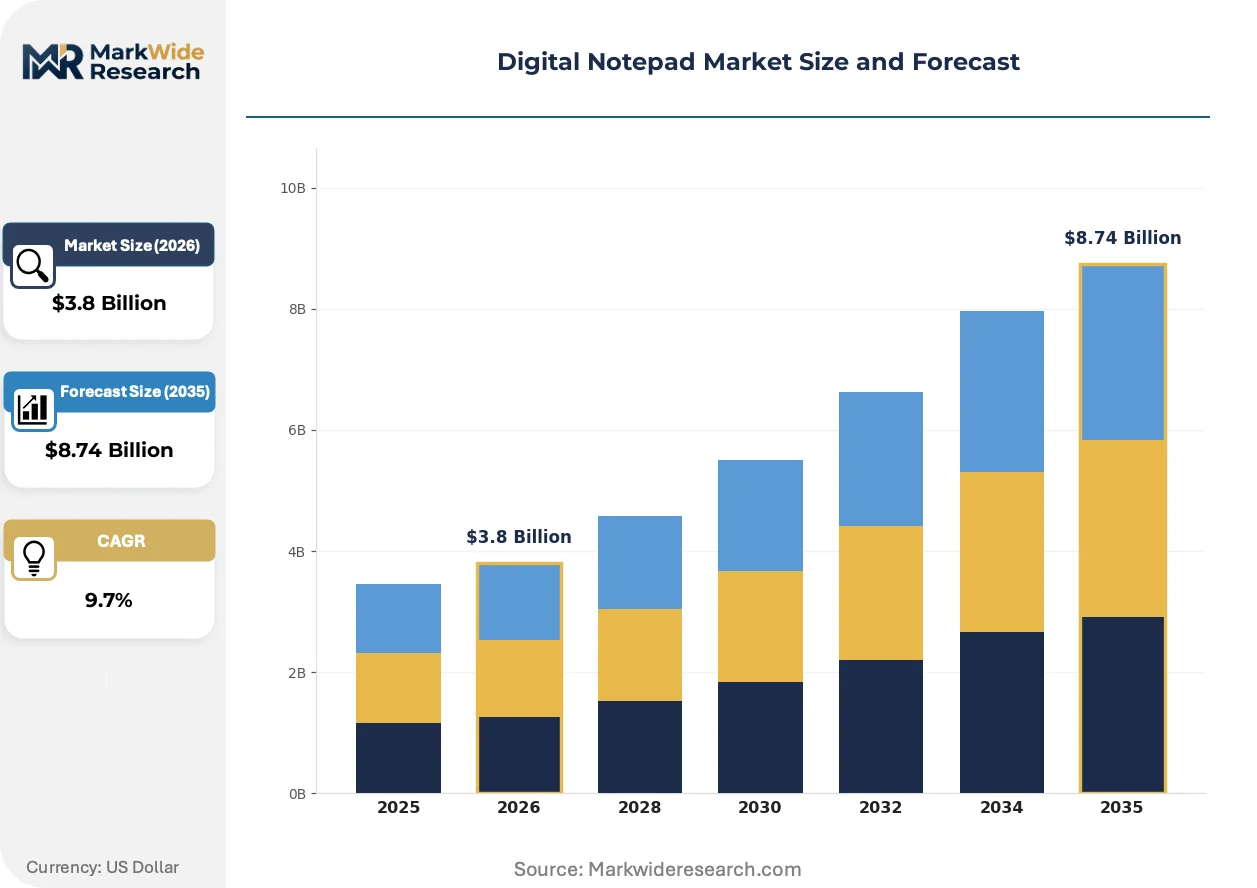
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Pens, Tablets, Digital Paper, Software Apps End User: Students, Professionals, Artists, Businesses Technology: Touchscreen, Pressure-sensitive, Audio Recording, Cloud Integration Price Tier: Premium, Mid-range, Budget, Educational |
| Companies Covered | reMarkable AS, Onyx International Inc., Sony Group Corporation, Wacom Co., Ltd., Livescribe Inc., NeoLAB Convergence Inc., Kent Displays Incorporated, Moleskine Srl, Rocketbook, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Notepad Market Trends and Innovations
Reflective display architectures are converging with advanced stylus protocols to redefine input precision benchmarks, while regulatory pressure on hardware serviceability accelerates design philosophy shifts across manufacturing tiers.
E-ink Carta 1300 and comparable cholesteric liquid crystal technologies are hybridizing static image retention with partial-refresh animation capabilities. Engineering firms in Germany now specify sub-20-millisecond latency thresholds for technical sketching workflows. This convergence is compressing the performance premium previously commanded by dedicated creative tablets, forcing vendors to differentiate through software ecosystems rather than raw hardware specifications.
REACH substance-of-very-high-concern listings now restrict certain flame retardants in flexible electronics enclosures sold across EU member states. Manufacturers must reformulate housing materials or face market exclusion, with certification costs disproportionately burdening smaller hardware specialists. German engineering procurement channels have responded by embedding RoHS and REACH compliance verification into supplier scorecards, elevating documentation overhead to competitive differentiator status.
Enterprise buyers in healthcare and construction sectors now unbundle hardware acquisition from software licensing, treating digital notepads as commodity endpoints for cloud-based annotation platforms. This pattern concentrates purchasing authority within IT procurement functions rather than departmental end-users, compressing vendor margins through volume aggregation. The shift is most visible in US hospital systems consolidating device standards under centralized capital planning committees.
Digital Notepad Market Segmentation
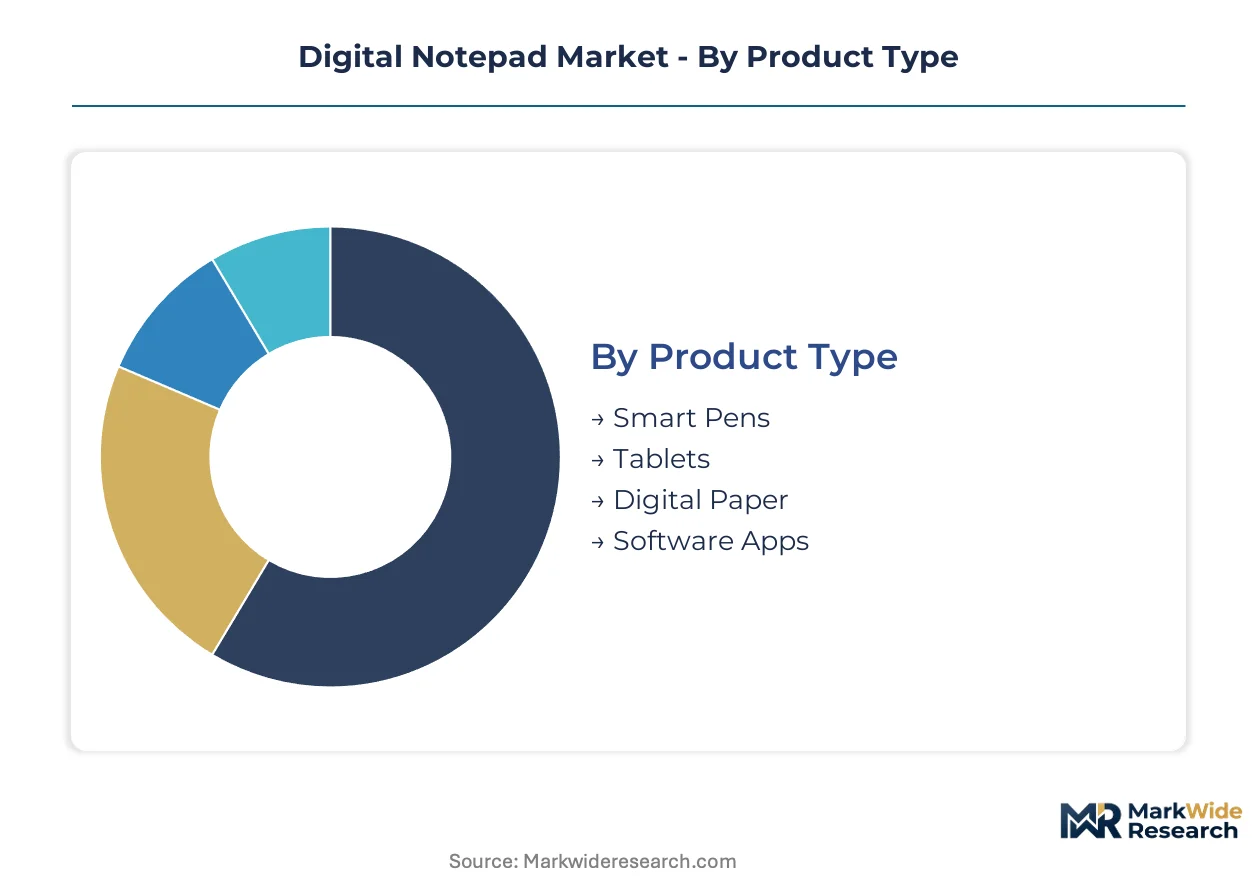
Segmentation in the digital notepad market reveals how hardware specialization, user workflow requirements, and procurement economics create distinct competitive arenas. Vendors must align product architectures with specific pressure-sensitivity thresholds, display technologies, and institutional purchasing protocols to capture value.
Product Type:
Mature dedicated hardware segments coexist with emerging software-centric delivery models that reshape margin structures.
- Smart Pens:Electromagnetic resonance stylus systems capture handwriting on physical paper while streaming digital copies to cloud archives. Healthcare systems in Germany deploy these for patient rounds requiring HIPAA-compliant documentation without screen-based distraction.
- Tablets:Full-color LCD and OLED variants with sub-20-millisecond latency now encroach on tasks previously reserved for reflective displays. Engineering firms specify these for technical sketching workflows demanding real-time color annotation.
- Digital Paper:Bi-stable e-ink surfaces retain images without power, serving field-deployed teams in construction and maritime sectors where battery weight constraints dominate.
- Software Apps:Cloud-native annotation platforms decouple functionality from hardware, capturing recurring subscription revenue from enterprise buyers treating notepads as commodity endpoints.
Smart Pens and Digital Paper handle the majority of throughput; Software Apps are expanding most quickly on share.
End User:
Cost tier differentiation separates institutional procurement from individual purchasing decisions across user categories.
- Students:Price-sensitive demand concentrates in budget-tier devices with cloud synchronization for lecture note archives. India's PLI scheme for electronics manufacturing attracts assembly investment targeting this volume segment.
- Professionals:Corporate buyers prioritize EMR stylus precision and EHR integration. US hospital systems consolidate device standards under centralized capital planning committees, aggregating purchasing power.
- Artists:Pressure-level granularity exceeding 4,096 distinct gradations defines purchasing decisions for creative workflows.
- Businesses:Enterprise procurement channels unbundle hardware acquisition from software licensing, compressing vendor margins through volume aggregation.
Businesses command the largest procurement volumes; Students represent the steepest expansion trajectory as educational digitization accelerates.
Technology:
Application-specific requirements determine which input protocols dominate within each deployment context.
- Touchscreen:Capacitive multi-touch layers enable finger-based navigation and gesture control. Construction sector field teams in Germany specify these for blueprint markup in variable weather conditions.
- Pressure-sensitive:Electromagnetic resonance digitizers with temperature-calibrated pressure curves serve professional creative and technical documentation workflows.
- Audio Recording:Synchronized voice capture with handwritten timestamps supports legal and medical transcription requirements.
- Cloud Integration:Real-time synchronization protocols enable cross-platform access and enterprise content management integration.
Pressure-sensitive technology anchors professional-grade revenue; Cloud Integration is gaining share fastest as enterprise IT departments centralize endpoint management.
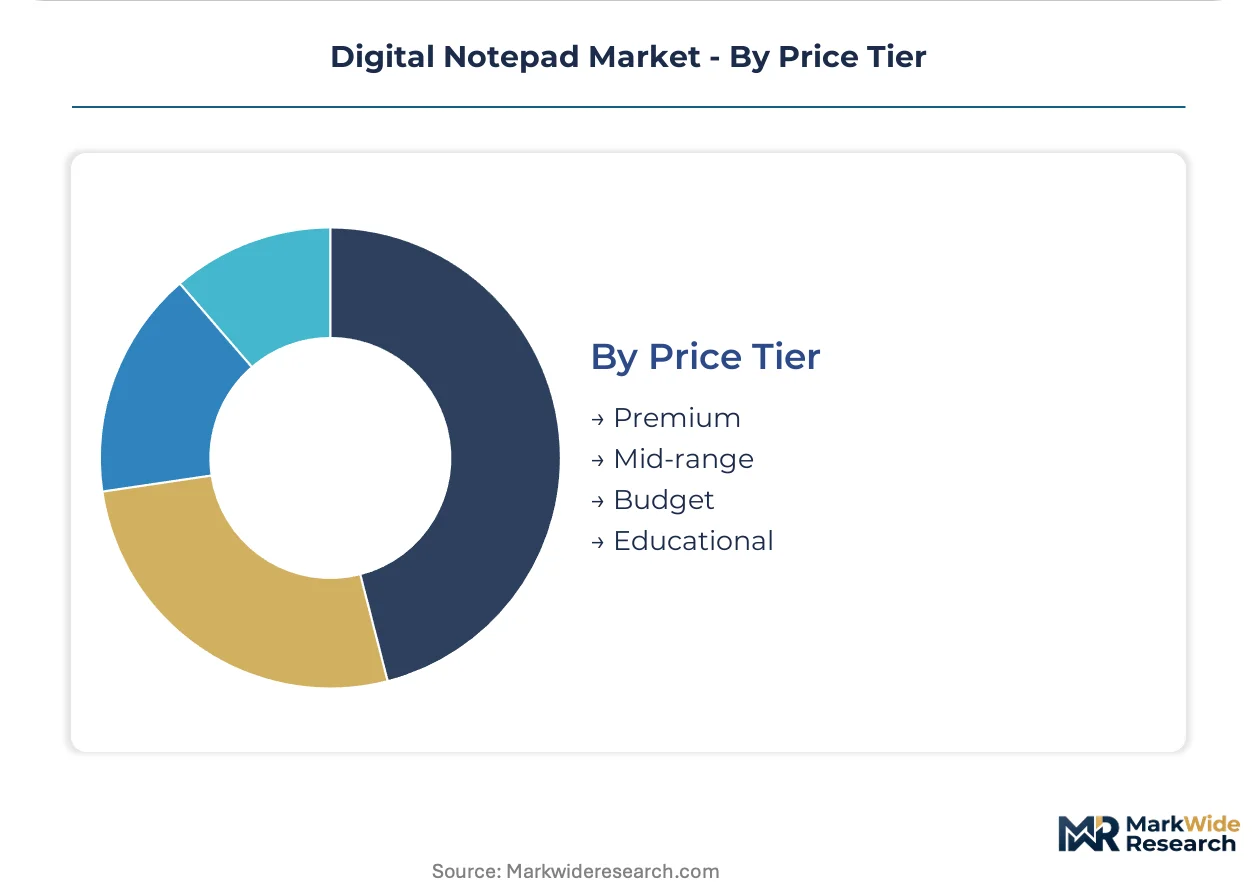
Price Tier:
Supply concentration in display panel fabrication shapes margin distribution across pricing strata.
- Premium:Proprietary display technologies and vertical hardware-software integration command sustained margin premiums. Oslo-based manufacturing clusters serve this tier with CANVAS display architectures.
- Mid-range:Android-based tablets with third-party annotation app support compete on specification breadth rather than proprietary ecosystem lock-in.
- Budget:Cost-optimized e-ink variants target price-sensitive professional segments in export-oriented manufacturing hubs.
- Educational:Volume procurement contracts with institutional buyers drive assembly scale in India under production-linked incentive frameworks.
Premium tier captures disproportionate margin attention; Educational pricing is climbing the fastest as public sector digitization budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oslo-based reMarkable AS ships CANVAS-equipped devices to engineering procurement channels across Germany and the Nordic bloc, while Shenzhen-anchored assembly lines feed mid-range Android tablets into India's educational digitization programs.
Germany
Technical documentation workflows in Stuttgart and Munich engineering clusters specify sub-20-millisecond stylus latency for CAD markup applications. EU Green Deal right-to-repair mandates under ECHA enforcement push device manufacturers toward modular chassis designs. The Karlsruhe region hosts compliance testing laboratories where REACH substance verification has become a supplier qualification gate.
United States
Hospital systems in the Boston and Houston metro areas consolidate digital notepad procurement under centralized IT capital committees. FCC Part 15 electromagnetic emissions certification creates months-long launch delays for stylus transceiver designs. Austin-based hardware startups partner with Dallas-Fort Worth medical networks for HIPAA-compliant clinical documentation pilots.
India
Production-linked incentive schemes under the Ministry of Electronics and Information Technology attract assembly investment targeting student-volume price tiers. CDSCO medical device regulations shape documentation requirements for healthcare-adjacent notepad deployments. Bengaluru and Hyderabad host software development centers building cloud-native annotation platforms for export markets.
Japan
METI energy efficiency guidelines constrain power budgets for corporate procurement channels in Tokyo and Osaka. PMDA quality system regulations extend to digital notepads used in pharmaceutical manufacturing documentation. Nagoya-based precision engineering firms demand pressure-sensitivity calibration exceeding 4,096 gradations for technical sketching workflows.
China
GB standards for electronic display devices mandate specific luminance and refresh-rate disclosures for domestic market access. MIIT industrial policy directs investment toward reflective display panel fabrication capacity in the Yangtze River Delta. Shenzhen hardware ecosystems supply electromagnetic resonance digitizer components to mid-tier global brands.
Digital Notepad Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement landscapes. The vendor base separates into three strategic archetypes: proprietary ecosystem builders with captive display technologies, Android-based specification competitors, and component-technology licensors. Competitive moves concentrate on backward integration into panel supply and direct-to-enterprise subscription bundling that bypasses retail fragmentation.
Within the proprietary ecosystem tier, reMarkable AS exemplifies vertical hardware-software integration through Oslo-based manufacturing clusters. Wacom Co., Ltd. anchors the electromagnetic resonance technology licensing position that shapes stylus compatibility standards across professional creative workflows. Onyx International Inc. occupies the Android-based specification-breadth position, competing across multiple price tiers through third-party application support rather than captive ecosystem lock-in.
| Leading Market Players |
|---|
| reMarkable AS |
| Onyx International Inc. |
| Sony Group Corporation |
| Wacom Co., Ltd. |
| Livescribe Inc. |
| NeoLAB Convergence Inc. |
| Kent Displays Incorporated |
| Moleskine Srl |
| Rocketbook |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta-to-Rotterdam maritime corridor carries reflective display panels and electromagnetic digitizer assemblies, with freight cost volatility compressing margins for mid-range tablet assemblers while premium vendors in Oslo exploit captive supply chains to sustain three-tier price separation across enterprise procurement channels.
Pricing Analysis
E-ink Carta 1200 versus Carta 1300 versus experimental cholesteric liquid crystal architectures anchor distinct price bands. Three-tier pricing structure across premium, standard, and economy levels reflects pressure-sensitivity calibration grade and REACH compliance certification tier. Cost compression in budget-tier educational devices is intensifying because India's PLI scheme attracts volume assembly investment. Students exhibit highest price sensitivity; German engineering procurement channels show lowest sensitivity due to EHR integration requirements.
Supply Chain Analysis
Extended payment terms from Taiwan-based panel fabricators to Shenzhen assembly ecosystems reveal working capital stress propagating upstream. Supply concentrates in Taiwan for e-ink substrates, China for electromagnetic resonance digitizers, and Norway for proprietary CANVAS display modules. Indium tin oxide and flexible PCB substrates constitute critical input dependencies. Single-source vulnerability in reflective display fabrication creates tariff exposure. Distribution runs through enterprise IT procurement committees and educational volume contracts rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as enterprise buyers unbundle hardware from cloud-native annotation software, with Wacom's proprietary EMR protocol fragmentation versus Android's open stylus standards representing the decisive interoperability inflection.
For Market Incumbents: Entrench proprietary ecosystem lock-in through backward integration into cholesteric liquid crystal panel supply and captive certification laboratories for FCC Part 15 pre-testing. EMR protocol standardization pressure from Android competitors threatens stylus compatibility premiums. Channel control through direct-to-hospital subscription bundling defends margin position. For New Entrants and Emerging Players: Mid-market engineering firms in India's industrial corridors represent the most penetrable entry point for Android-based specification competitors lacking legacy EMR licensing costs. Construction sector field teams in Germany seeking REACH-compliant ruggedized devices offer secondary white-space. Go-to-market through CDSCO-registered medical device distributors bypasses retail fragmentation. For Investors and Strategic Acquirers: Component-technology licensors with captive electromagnetic resonance calibration expertise and established FDA 510(k) predicate pathways offer superior long-term viability within a five-to-ten-year holding window. Monitor EU Green Deal right-to-repair enforcement timelines as inflection signal for modular hardware redesign capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reflective Display Supply | Captive cholesteric liquid crystal capacity insulates against Taiwan panel fabrication bottlenecks. |
| Direct-to-Enterprise Subscription Bundling | Recurring revenue contracts with US hospital systems bypass retail margin compression. |
| REACH Compliance Certification Investment | Karlsruhe laboratory pre-qualification unlocks German engineering procurement channels. |
| Android Open Stylus Protocol Adoption | Third-party app ecosystem breadth challenges proprietary EMR ecosystem lock-in. |
| Modular Hardware Architecture Redesign | EU ECHA right-to-repair mandates force serviceable chassis designs extending device lifecycles. |
Research Methodology
Initial hypotheses were tested against primary input from hospital IT procurement directors, electromagnetic resonance hardware engineers, educational technology coordinators, and REACH compliance consultants, and refined through secondary validation against FDA 510(k) databases, ECHA substance restriction listings, FCC equipment authorization records, and import-export customs data. Bottom-up assembly cost modeling triangulated with top-down enterprise spending surveys.
Demand-supply-balance framing across the analysis window segmented volume and value outputs by product type, end-user workflow, pressure-sensitivity technology tier, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and educational digitization budget trajectories. Cholesteric liquid crystal yield rates and EMR stylus latency benchmarks constituted industry-specific forecast inputs.
Practitioners should monitor EU Green Deal enforcement acceleration, Taiwan Strait trade friction indicators, and India's PLI scheme revision triggers for early signals of forecast deviation. Macroeconomic contraction in enterprise IT capital expenditure, regulatory restriction expansion under REACH SVHC listings, or breakthrough full-color reflective display commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Thin Client Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
Plant Asset Management (PAM) Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Load Balancer Market
Digital Solutions
Utility Bill Management System Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Online Voting System Market
Digital Solutions
Email Marketing Market
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
Correspondence Management Solution Market
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Social Networking App Market
Digital Solutions
Supply Side Platform (SSP) Market