
 RFID Printer Market | 2026-2036
RFID Printer Market Size, Share, and Industry Trends Forecast 2026-2036
RFID Printer Market Analysis
China is tilting toward expanded RFID printer production capacity as domestic electronics manufacturing clusters scale output for regional export markets. Zebra Technologies Corp. leverages its North American channel density to sustain service-led contracts with Fortune 500 logistics operators. SATO Holdings Corporation anchors its competitive position through specialized thermal transfer engineering for high-tolerance industrial environments. Toshiba Tec Corporation competes aggressively on print-head durability, extending equipment lifecycle metrics that reduce total cost of ownership for Japanese automotive suppliers.
An RFID printer encodes data onto radio-frequency identification tags and simultaneously prints human-readable graphics, typically operating at UHF frequencies between 860 and 960 MHz for supply-chain applications. The device integrates an RF encoder module with a thermal or inkjet print engine to produce adhesive labels containing both printed barcodes and embedded antennae for wireless inventory tracking. Industrial printers dominate capital deployment due to 24/7 operational requirements in automated distribution centers, while mobile printers represent the fastest-growing product configuration as field-service technicians adopt Bluetooth-connected units for on-site asset tagging. Thermal transfer technology leads technology segmentation because resin ribbons withstand chemical exposure in pharmaceutical cold chains, though direct thermal formats occupy the economy tier for short-lifecycle retail apparel labels.
FCC equipment authorization rules govern UHF transmitter power levels in the United States, constraining printer-encoder combinations that exceed 4-watt effective isotropic radiated power. ETSI EN 302 208 standards across Europe mandate listen-before-talk protocols that reduce tag-collision errors in dense retail environments, directly shaping product firmware requirements for multi-region OEMs. ISO/IEC 18000-63 compliance for item-level tagging is forcing healthcare providers to validate printer-encoder accuracy against FDA drug pedigree regulations. Stakeholders must monitor whether emerging GS1 Digital Link standards will displace legacy EPC Gen2 encoding, as this transition would obsolete substantial installed printer bases and trigger replacement cycles across logistics networks.
Market Dynamics
Retail inventory management is accelerating adoption as retailers replace barcode systems with RFID-enabled item-level tracking, compressing replacement cycles and reshaping vendor relationships across supply chains.
Growth Catalysts
- FDA pharmaceutical traceability mandates:Healthcare providers validate printer-encoder accuracy against drug pedigree regulations, forcing deployment across hospital networks and pharmaceutical distributors.
- EU Green Deal circular economy requirements:Manufacturers pivot toward energy-efficient thermal transfer technologies to meet binding sustainability thresholds for production equipment.
- Warehouse automation investments:United States distribution centers deploy industrial printers for 24/7 operational requirements in automated fulfillment networks.
Market Restraints
- Print-head replacement costs:Thermal transfer print heads degrade under continuous industrial use, creating recurring opex burdens that extend total cost of ownership calculations.
- Resin ribbon supply concentration:Specialty ribbon manufacturing clusters in East Asia expose buyers to freight volatility and currency fluctuation risks.
- FCC power constraints:Four-watt effective isotropic radiated power limits constrain encoder performance in dense tag environments, forcing firmware workarounds.
Strategic Opportunities
- Indian pharmaceutical cold chains:CDSCO traceability requirements and expanding domestic vaccine production create demand for chemical-resistant resin ribbon encoding systems.
- Bluetooth-connected mobile units:Field-service technicians in utilities and telecommunications adopt portable printers for on-site asset tagging outside fixed infrastructure.
- GS1 Digital Link transition:Emerging standards for web-enabled identifiers threaten legacy EPC Gen2 encoding, positioning vendors to capture replacement cycles across logistics networks.
Industry Challenges
- RF engineer talent scarcity:UHF antenna design and firmware optimization require specialized expertise that outpaces vocational training pipeline output.
- Multi-regional certification timelines:Simultaneous FCC, ETSI EN 302 208, and ISO/IEC 18000-63 validation extends product launch windows by 8-14 months.
- Legacy WMS integration friction:Enterprise warehouse management systems require custom middleware development to consume RFID data streams alongside existing barcode workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RFID Printer Market |
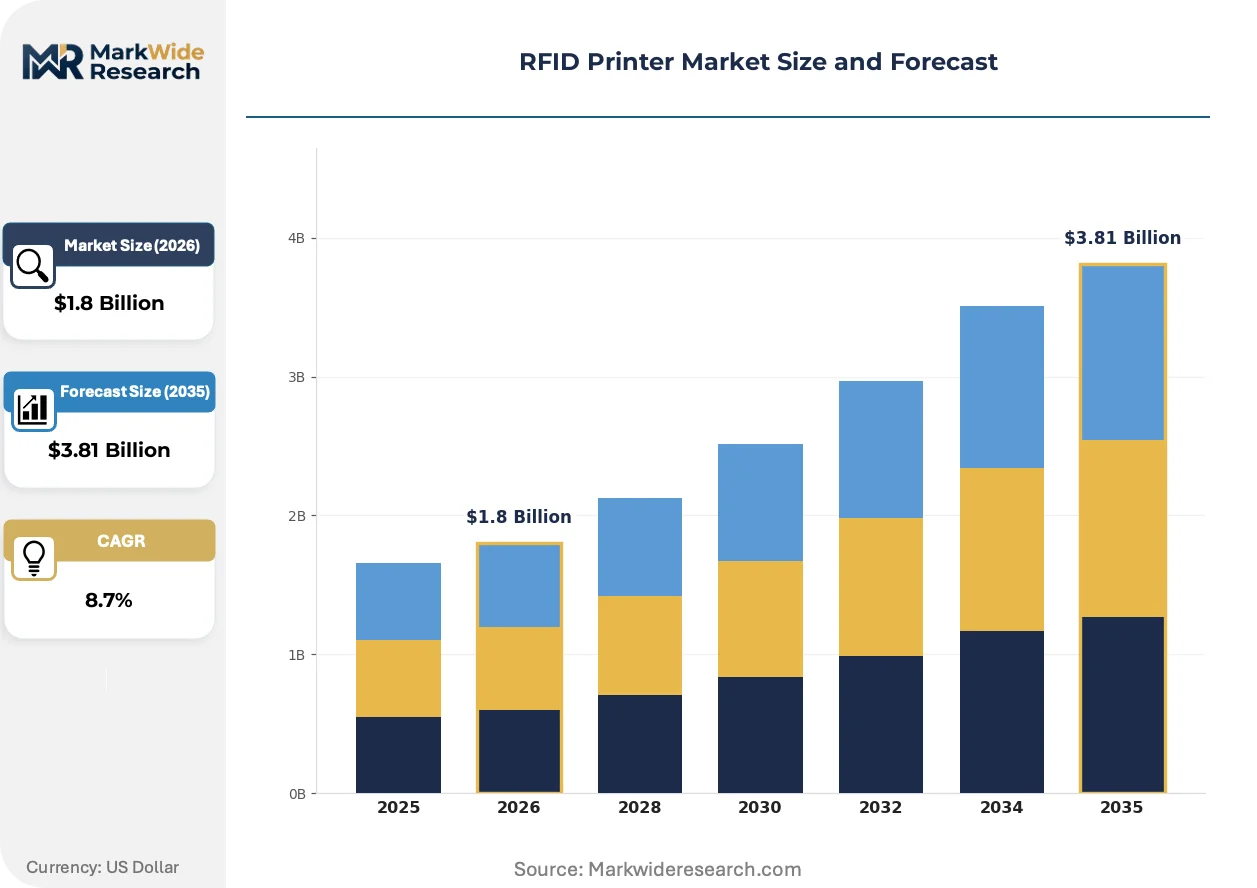
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Printers, Desktop Printers, Mobile Printers, Printer Bundles Technology: Thermal Transfer, Direct Thermal, Inkjet, Laser End User: Retail, Healthcare, Logistics, Manufacturing Application: Inventory Management, Asset Tracking, Shipping Labels, Event Management |
| Companies Covered | Seiko Epson Corp., Toshiba Tec Corporation, Zebra Technologies Corp., Printronix, BIXOLON, SATO Holdings Corporation, AVERY DENNISON CORPORATION, GoDEX International, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RFID Printer Market Emerging Trajectories
Hardware vendors are converging encoding accuracy with cloud-native fleet management, enabling remote diagnostics and predictive maintenance that reconfigures service revenue models.
Precision thermal transfer engineering with ceramic-coated print heads is digitizing asset identification workflows in pharmaceutical cold chains. Biologics manufacturers deploying these systems achieve 99.9% encode-first-pass rates at temperatures below negative twenty degrees Celsius. The technology is digitizing compliance documentation by embedding temperature excursion data directly into tag memory, eliminating manual chain-of-custody logging.
ETSI EN 302 208 listen-before-talk protocols are mandating firmware architectures that reduce tag-collision errors in dense European retail environments. Multi-region OEMs must engineer dual-mode radios that switch between FCC and ETSI power profiles without hardware swaps. German automotive suppliers face the steepest compliance burden, as just-in-sequence parts tracking requires sub-100-millisecond encode-verify-print cycles under these constraints.
Third-party logistics providers are unbundling printer hardware from managed print services, shifting capex-heavy ownership models toward per-label operational expenditures. Pharmaceutical 3PLs in the United States now demand service-level agreements guaranteeing 99.5% uptime with four-hour technician dispatch. This restructuring concentrates vendor selection around geographic service density rather than equipment specifications alone.
RFID Printer Market Segmentation
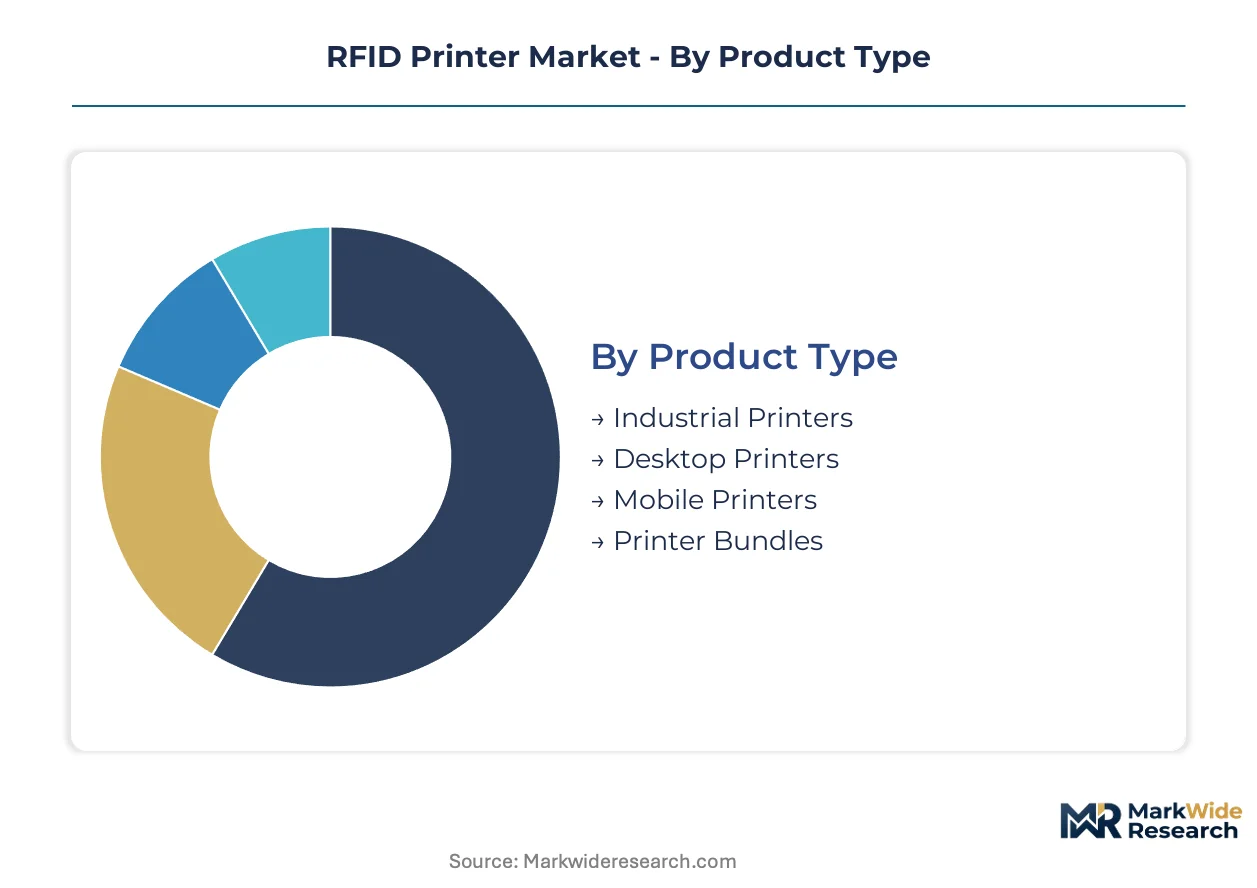
RFID printer segmentation reveals distinct operational requirements across fixed infrastructure, portable field deployment, and bundled service models. Each configuration demands specific encoder precision, connectivity protocols, and environmental tolerance that reshape procurement criteria and vendor selection.
Product Type:
Use-case spectrum spans high-throughput distribution centers to lone field technicians requiring Bluetooth mobility.
- Industrial Printers:Ruggedized metal chassis house 600-dpi thermal transfer engines rated for continuous 24/7 operation in automated fulfillment networks. United States warehouse operators validate these units against four-hour SLA response windows for pharmaceutical 3PL contracts.
- Mobile Printers:Battery-powered units weighing under two kilograms connect via Bluetooth 5.0 to enterprise handhelds for on-site asset tagging outside fixed infrastructure. Utilities and telecommunications field crews in Germany adopt these for substation equipment labeling where wired power is unavailable.
- Desktop Printers:Compact footprint units serve mid-volume retail backrooms and hospital pharmacy satellite locations with 4-6 hour daily duty cycles.
- Printer Bundles:Pre-configured hardware-ribbon-software packages reduce deployment friction for first-time RFID adopters in mid-market logistics.
The dominant share belongs to Industrial Printers, while Mobile Printers are gaining share fastest as field-service digitization accelerates.
Technology:
Cost tier separation tracks ribbon economics against print durability requirements.
- Thermal Transfer:Resin and wax-resin ribbons bond polymer ink to synthetic label substrates, achieving chemical resistance mandatory for pharmaceutical cold chains below negative twenty degrees Celsius. EU Green Deal energy-efficiency thresholds favor modern thermal transfer engines with ceramic-coated print heads.
- Direct Thermal:Heat-sensitive paper eliminates ribbon replacement but produces labels with 6-12 month legibility lifespans suited to fast-fashion apparel with short selling seasons. Japanese retailers favor this format for cost-sensitive seasonal turnover.
- Inkjet:Piezoelectric drop-on-demand systems enable full-color branding on RFID labels for luxury goods authentication.
- Laser:Toner-based imaging delivers archival-grade durability for aerospace component traceability exceeding ten-year retention mandates.
Thermal Transfer commands the installed base, though Direct Thermal climbs fastest in retail apparel replacement cycles.
End User:
Application maturity varies sharply across compliance-driven healthcare and efficiency-focused logistics.
- Retail:Item-level tagging mandates from major apparel chains compress replacement cycles as barcode systems phase out. Dense store environments in France require ETSI EN 302 208 listen-before-talk firmware to reduce tag collisions.
- Healthcare:FDA drug pedigree regulations force hospital networks and pharmaceutical distributors to validate printer-encoder accuracy against ISO/IEC 18000-63 compliance. Biologics manufacturers embed temperature excursion data directly into tag memory.
- Logistics:Third-party providers unbundle hardware ownership in favor of per-label operational expenditures with 99.5% uptime guarantees.
- Manufacturing:Automotive just-in-sequence parts tracking demands sub-100-millisecond encode-verify-print cycles under German supplier quality protocols.
Retail holds the largest deployment volume, while Healthcare shows the steepest expansion trajectory on regulatory compulsion.
Application:
Customer type differentiation separates enterprise warehouse management integration from standalone event deployment.
- Inventory Management:Real-time stock visibility systems replace cycle-count labor with automated RFID tunnel readers, requiring printers that synchronize encode data with WMS middleware. United States distribution centers lead capital deployment here.
- Asset Tracking:Fixed and mobile infrastructure labels track IT equipment, medical devices, and tooling across dispersed corporate campuses and hospital networks.
- Shipping Labels:Hybrid barcode-RFID formats bridge legacy scanner infrastructure during multi-year carrier compliance transitions.
- Event Management:Short-duration badge printing for conferences and exhibitions favors rental fleet models with minimal integration requirements.
Inventory Management dominates current revenue, while Asset Tracking expands most quickly as enterprise digitization broadens beyond supply chain cores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian electronics manufacturing clusters control the bulk of RFID printer component fabrication, while end-use demand concentrates in North American and European distribution networks subject to pharmaceutical traceability mandates.
United States
Warehouse automation investments and FDA pharmaceutical traceability mandates drive printer deployment across healthcare and logistics networks. FCC equipment authorization rules constrain UHF transmitter power levels to four-watt effective isotropic radiated power, shaping firmware architectures for domestic OEMs. The Midwest distribution corridor spanning Illinois and Ohio anchors automated fulfillment center installations serving pharmaceutical 3PL contracts.
Germany
Automotive just-in-sequence parts tracking demands sub-100-millisecond encode-verify-print cycles under stringent supplier quality protocols. ETSI EN 302 208 standards mandate listen-before-talk firmware that reduces tag-collision errors in dense retail environments. The Baden-Württemberg industrial cluster around Stuttgart concentrates thermal transfer engineering expertise for high-tolerance manufacturing applications.
China
Domestic electronics manufacturing clusters scale output for regional export markets, expanding production capacity to serve Southeast Asian logistics networks. MIIT radio frequency regulations govern 920-925 MHz UHF allocations for supply-chain applications, diverging from FCC and ETSI spectrum bands. The Yangtze River Delta manufacturing belt around Shanghai hosts ribbon substrate and print-head component suppliers.
Japan
Automotive suppliers prioritize print-head durability metrics that reduce total cost of ownership across extended equipment lifecycles. METI industrial standards emphasize energy-efficiency thresholds aligned with circular economy objectives. The Chubu region around Nagoya anchors precision thermal engineering clusters serving biologics manufacturers with cold-chain encoding requirements.
India
CDSCO traceability requirements and expanding domestic vaccine production create demand for chemical-resistant resin ribbon encoding systems. BIS certification timelines for imported printing equipment extend product launch windows by six to nine months versus domestic assembly. The Maharashtra pharmaceutical manufacturing corridor around Mumbai and Pune drives cold-chain infrastructure investment.
RFID Printer Market Vendor Landscape
Specialized thermal transfer engineers and diversified industrial automation conglomerates split the market between precision niche positioning and scale-driven service density. The vendor base organizes into three strategic archetypes: North American channel-heavy integrators, East Asian precision component specialists, and European industrial automation conglomerates. Dominant competitive moves center on geographic service density expansion and managed print service unbundling that shifts hardware ownership toward per-label operational expenditure models.
Among diversified industrial technology providers, Zebra Technologies Corp. and Honeywell International exemplify the channel-density archetype, anchoring competitive positioning through North American service-led contract structures. Toshiba Tec Corporation and SATO Holdings Corporation represent the precision-engineering tier, occupying positions defined by thermal transfer durability metrics and high-tolerance industrial specifications. Seiko Epson Corp. sits within the diversified electronics conglomerate category, leveraging vertical integration into print-head component fabrication.
| Leading Market Players |
|---|
| Seiko Epson Corp. |
| Toshiba Tec Corporation |
| Zebra Technologies Corp. |
| Printronix |
| BIXOLON |
| SATO Holdings Corporation |
| AVERY DENNISON CORPORATION |
| GoDEX International |
| Honeywell International |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing belt around Shanghai controls ribbon substrate and print-head component fabrication, concentrating upstream capacity in a corridor that grants East Asian suppliers substantial leverage over equipment pricing for Western OEMs. This geographic clustering amplifies cost volatility when freight rates fluctuate or currency positions shift, forcing distributors to absorb margin compression or pass through increases to end-users in pharmaceutical and logistics verticals.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across the RFID printer landscape, with energy-efficiency certification thresholds separating premium ceramic-coated thermal transfer engines from standard metal-housed units and economy direct thermal configurations. Price differentiation rests on ISO/IEC 18000-63 compliance grade and after-sales service bundling, with pharmaceutical 3PLs paying premiums for four-hour SLA guarantees while retail apparel buyers prioritize capital minimization. Cost compression in the economy tier is intensifying because Japanese retailers are consolidating direct thermal procurement for fast-fashion seasonal turnover. Field-service technicians in utilities represent the most price-sensitive segment, while biologics manufacturers demonstrate minimal sensitivity due to cold-chain validation requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now anchor supplier relationships as ribbon manufacturers in China, Japan, and South Korea stretch receivables to secure volume commitments from equipment OEMs. Raw material dependencies center on ceramic print-head substrates, resin ribbon polymer coatings, and UHF antenna copper etching feedstock. Single-source vulnerability concentrates in specialty resin formulation, where three East Asian chemical suppliers control pharmaceutical-grade cold-chain ribbon chemistry. Distribution runs through authorized industrial automation distributors in North America and direct OEM relationships in European automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RFID printer market fragmentation creates acquisition opportunities as regulatory mandates splinter demand across pharmaceutical traceability, automotive just-in-sequence tracking, and retail item-level tagging niches with divergent technical specifications.
For Market Incumbents: Harden service density in the Midwest distribution corridor to defend against third-party logistics providers unbundling hardware ownership into per-label operational expenditure models. Expand backward integration into ceramic print-head substrate production to reduce exposure to Yangtze River Delta supply concentration and capture margin from pharmaceutical cold-chain premium tiers. For New Entrants and Emerging Players: Pursue Bluetooth-connected mobile printer white space in German utilities and telecommunications field crews, where wired power unavailability creates untapped demand outside fixed infrastructure. Target Indian pharmaceutical cold chains as the most penetrable geography, leveraging CDSCO traceability requirements and domestic vaccine production expansion to establish resin ribbon encoding system credentials without incumbent service network entrenchment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision thermal transfer engineering specialists with captive ceramic coating capabilities and established FDA validation pathways. Long-term viability hinges on GS1 Digital Link transition readiness, as web-enabled identifier standards threaten legacy EPC Gen2 encoding installed bases. Watch firmware architecture flexibility as the inflection signal distinguishing replacement-cycle capture from obsolescence exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Print Service Unbundling | Shifts pharmaceutical 3PL contracts from capex ownership to per-label operational expenditure with 99.5% uptime SLAs. |
| Ceramic Print-Head Backward Integration | Captures margin from cold-chain premium tiers while reducing exposure to East Asian substrate supply volatility. |
| Dual-Mode Radio Firmware Development | Enables single hardware platforms to switch between FCC and ETSI power profiles without regional SKU proliferation. |
| Cloud-Native Fleet Management Platform | Reconfigures service revenue models through remote diagnostics and predictive maintenance capabilities. |
| Resin Ribbon Regional Manufacturing | Mitigates freight volatility risks by establishing chemical-resistant formulation capacity near Indian pharmaceutical corridors. |
Methodological Framework
Desk research of SEC 10-K filings, ETSI equipment authorization databases, and pharmaceutical cold-chain compliance documentation preceded structured interviews with thermal transfer R&D directors, pharmaceutical 3PL operations managers, automotive supplier quality engineers, and retail inventory systems integrators. Primary fieldwork with hospital biomedical engineering departments and distribution center automation specialists validated secondary data on encode-first-pass rate benchmarks and SLA response requirements. Bottom-up equipment deployment estimates triangulated against top-down addressable market calculations across the analysis window.
Assumptions held regulatory mandate timelines and warehouse automation capital expenditure trajectories fixed while varying RFID tag cost decline curves and GS1 Digital Link adoption velocity across sensitivity scenarios. Segmentation modeling incorporated product type, technology format, end-user vertical, and application workflow dimensions alongside regional regulatory cluster differentiation. CAGRs derived from logistic growth curve fitting to historical deployment data, with pharmaceutical traceability compliance deadlines and automotive just-in-sequence quality protocols serving as industry-specific demand anchors throughout the projection horizon.
Sensitivities concentrate around ETSI EN 302 208 firmware certification delays, resin ribbon supply disruptions, and GS1 Digital Link standard displacement of EPC Gen2 encoding. Forecasts reflect documented assumptions on regulatory enforcement intensity and warehouse automation investment continuity. Macroeconomic contraction, trade restriction expansion, or alternative auto-ID technology breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Industrial Printer Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Print on Demand Software Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
ID Card Printers Market
Printing Technology
Large Character Printers Market
Printing Technology
Digital Pattern Generator Market
Printing Technology
Global Wireless Printers Market