
 Global Digital Printing Services Market | 2026-2036
Global Digital Printing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Printing Services Market Foresight
East Asian equipment makers is restructuring the competitive map for digital printing services as Chinese and Japanese producers expand high-speed inkjet foundry capacity. HP Inc. leverages its PageWide technology leadership to anchor enterprise print contracts across North America and Western Europe. Canon Inc. sustains dominance in commercial photo production through proprietary dye-sublimation systems. Durst Group AG specializes in UV-curing large-format systems for industrial signage applications.
Digital printing services encompass variable-data reproduction workflows that deposit pigmented fluids or toners onto substrates without fixed image carriers, typically operating at resolutions from 300 to 2400 dpi with run lengths below five thousand impressions. These systems serve commercial and industrial clients requiring time-compressed, customized visual communication. Inkjet printing leads service revenue due to its substrate versatility and declining per-page economics, while label printing represents the fastest-expanding category as beverage and pharmaceutical brands adopt serialized packaging. On-demand printing occupies mature margin pools in transactional document segments where laser electrophotography still controls cost curves for monochrome volumes.
The EPA regulates volatile organic compound emissions from commercial print facilities, pushing solvent-based operations toward water-based or UV-curing inkjet alternatives. ECHA REACH restrictions on hazardous pigment classifications reshape formulation sourcing across European service providers. ISO 12647 color management standards govern cross-border contract proofing acceptability. Stakeholders must monitor regulatory chemistry timelines and press retrofit capital cycles to align capacity commitments with compliant ink supply chains.
Market Dynamics
SKU proliferation across consumer packaged goods is compressing run lengths and forcing packaging converters toward hybrid digital-conventional production lines that balance flexibility against unit economics.
Growth Catalysts
- REACH pigment restrictions:ECHA classifications on hazardous colorants are accelerating service provider migration to compliant water-based inkjet formulations, creating replacement demand for aging solvent fleets.
- Pharmaceutical serialization mandates:Track-and-trace regulations in the United States and European Union require variable-data printing on every drug package, pulling label converters toward digital infrastructure.
- High-speed inkjet foundry expansion:Japanese and Chinese equipment producers are scaling production capacity, reducing hardware delivery cycles and lowering entry barriers for mid-tier commercial printers.
Market Restraints
- Pigment supply concentration:Specialty colorant production clusters in China and India, exposing European and North American ink formulators to freight volatility and tariff exposure.
- Substrate compatibility gaps:Uncoated corrugated and flexible films remain technically challenging for aqueous inkjet, limiting addressable share in food packaging segments.
- EPA VOC enforcement timelines:Solvent-based operations face accelerated compliance deadlines without guaranteed retrofit financing, freezing capacity decisions at marginal facilities.
Strategic Opportunities
- India commercial print modernization:Fragmented offset capacity and rising brand localization campaigns create white space for on-demand digital service models in Mumbai and Delhi clusters.
- UV-LED curing convergence:Integration of instant-curing chemistry with single-pass inkjet architectures enables direct-to-object decoration on three-dimensional packaging formats.
- Brazil beverage label demand:Craft brewing and premium spirits proliferation is compressing label order quantities below rotary flexo minimums, opening digital penetration in São Paulo state.
Industry Challenges
- Color management certification backlog:ISO 12647-7 proofing accreditation queues extend six to nine months, delaying contract eligibility for commercial printers pursuing brand-direct relationships.
- Prepress workflow integration:Legacy MIS systems lack native JDF connectivity to digital front ends, forcing manual job ticketing and inflating make-ready labor at hybrid facilities.
- Specialized technician scarcity:Electrophotography-trained press operators require eighteen-month retraining curves for inkjet maintenance protocols, constraining fleet expansion at family-owned print shops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Printing Services Market |
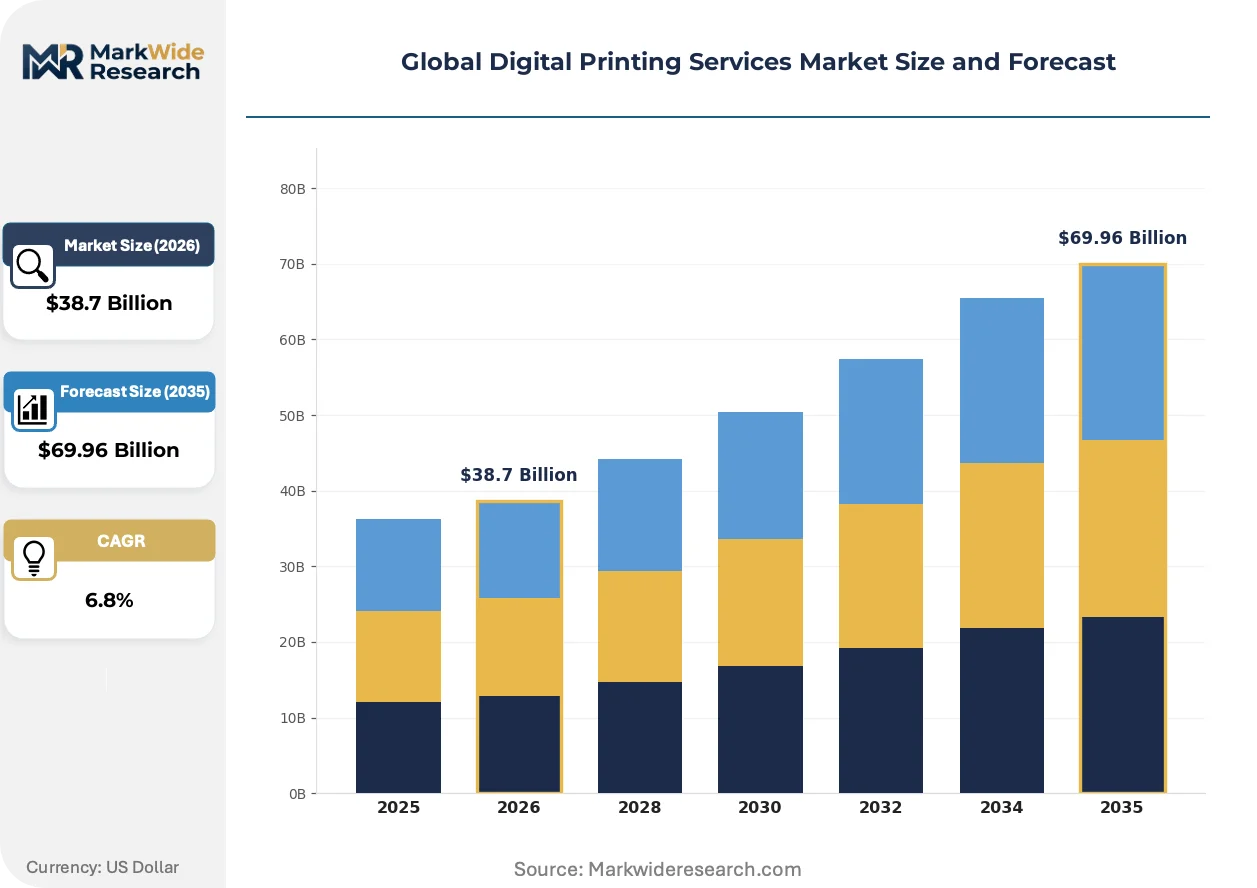
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-demand Printing, Large Format Printing, Label Printing, Textile Printing, 3D Printing, Photo Printing Application: Marketing Materials, Packaging, Personalized Products, Commercial Publications, Signage, Promotional Items Technology: Inkjet Printing, Laser Printing, Electrophotography, Dye Sublimation, UV Curing, Thermal Printing End User: Advertising Agencies, Publishing Houses, Textile Manufacturers, Event Management Firms, Packaging Companies, Graphic Designers |
| Companies Covered | HP Inc., Canon Inc., Xerox Corporation, Ricoh Company Ltd., Seiko Epson Corporation, Konica Minolta Inc., Mimaki Engineering Co., Ltd., Roland DG Corporation, Durst Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Printing Services Market Shifts & Advancements
Single-pass inkjet architectures are collapsing the speed gap with offset lithography while retaining variable-data capabilities, redrawing competitive boundaries between digital service providers and conventional converters.
Water-based inkjet formulations with nanoscale pigment dispersion are rewriting substrate economics for folding carton applications. Major beverage brands in Germany and Japan have validated direct-to-board printing on uncoated stock, eliminating lamination steps. This chemistry shift is compressing total applied cost curves and enabling digital penetration into volume packaging segments previously reserved for flexographic conversion.
EPA New Source Performance Standards for printing facilities are tightening volatile organic compound thresholds, pushing solvent-based operations toward UV-curing or water-based alternatives. Commercial printers in California and Texas face retrofit capital decisions against uncertain payback periods. The regulatory pressure is concentrating compliant capacity among larger service providers with balance sheet capacity for emission control infrastructure.
Brand procurement teams are unbundling print specification from fulfillment logistics, creating direct relationships with digital converters that bypass traditional broker networks. This disintermediation is most visible in North American direct-to-consumer apparel packaging, where Shopify-integrated merchants require sub-48-hour turnaround on variable inserts. Service providers capturing these flows are building captive design-to-door workflows that absorb margin previously captured by intermediaries.
Global Digital Printing Services Market Segmentation
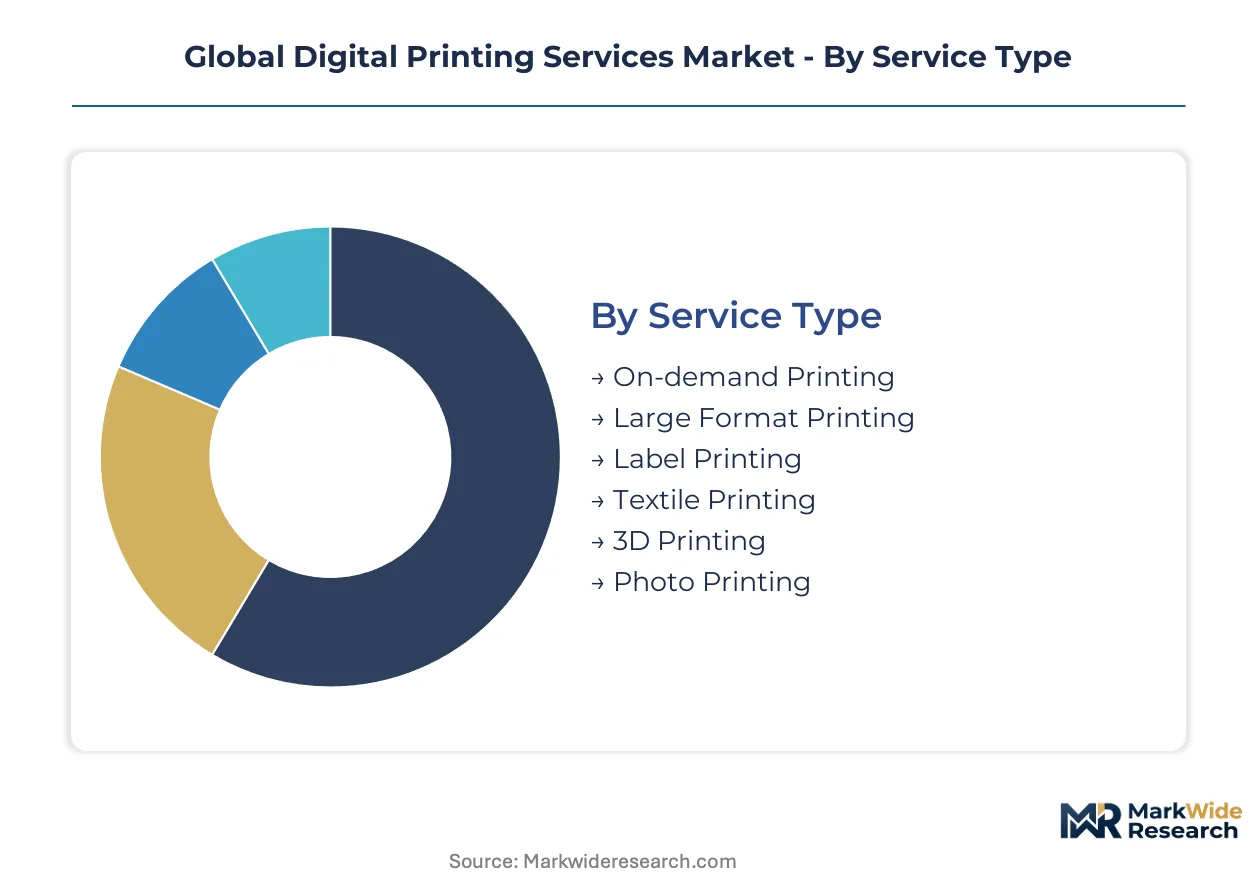
Digital printing services fragment across six distinct technology categories, each commanding different capital intensity and margin profiles. Upgrade cycles vary dramatically—inkjet fleets refresh every five to seven years while electrophotography extends to nine—creating asynchronous replacement demand across service provider balance sheets.
Service Type:
Replacement urgency concentrates in segments where substrate versatility gaps limit customer retention, driving faster depreciation schedules and earlier capital redeployment.
- On-demand Printing:Transactional document workflows for variable-data statements and short-run corporate collateral. Demand clusters in United States financial services and German insurance verticals where compliance archiving mandates compress turnaround windows.
- Label Printing:Serialized packaging reproduction for pharmaceutical track-and-trace and beverage SKU proliferation. Pharmaceutical serialization mandates in the United States and European Union pull converters toward digital infrastructure with 48-hour changeover capabilities.
- Large Format Printing:Architectural renderings and retail point-of-sale graphics at widths exceeding 1.5 meters.
- Textile Printing:Direct-to-garment and roll-to-roll fabric decoration for fast fashion and custom apparel.
- 3D Printing:Additive manufacturing services for prototyping and short-run production parts.
- Photo Printing:Consumer and commercial photographic reproduction through dye-sublimation and inkjet systems.
On-demand printing sits at the top of the volume ranking, with label printing climbing the fastest.
Application:
Cost tier stratification separates high-mix, low-volume brand work from commodity replication contracts with divergent equipment utilization economics.
- Marketing Materials:Variable-data direct mail, catalogs, and corporate brochures requiring frequent content refresh. United States direct-to-consumer merchants in California and Texas demand sub-48-hour fulfillment cycles that bypass traditional broker networks.
- Packaging:Folding cartons, flexible pouches, and corrugated displays for consumer packaged goods. German beverage brands and Japanese electronics manufacturers validate direct-to-board printing on uncoated stock, eliminating lamination steps.
- Personalized Products:Custom apparel, promotional merchandise, and individualized gift items.
- Commercial Publications:Books, magazines, and periodicals with print-on-demand distribution models.
- Signage:Indoor and outdoor display graphics for retail and construction site applications.
- Promotional Items:Branded merchandise and event-specific materials with short lead times.
Marketing materials commands the largest installed base, though packaging gains share fastest as SKU proliferation compresses run lengths below rotary flexo minimums.
Technology:
Volume throughput requirements separate single-pass architectures from scanning systems with order-of-magnitude speed differentials.
- Inkjet Printing:Piezoelectric and thermal drop-on-demand systems depositing aqueous, solvent, or UV-curable fluids. Japanese and Chinese equipment producers scale high-speed foundry capacity, reducing hardware delivery cycles for mid-tier commercial printers.
- Laser Printing:Electrophotographic toner fusion for monochrome transactional documents. United States healthcare and financial services retain laser dominance where cost-per-page economics still favor toner for volumes exceeding five thousand impressions.
- Electrophotography:Digital press systems using photoconductive drums and dry toner transfer.
- Dye Sublimation:Heat-activated dye transfer for photographic and textile applications with continuous tone output.
- UV Curing:Instant polymerization chemistry enabling direct-to-object decoration on non-porous substrates.
- Thermal Printing:Direct thermal and thermal transfer systems for labels and receipts in logistics applications.
Inkjet printing leads absolute unit shipments, with UV curing expanding most quickly as EPA VOC enforcement accelerates solvent fleet replacement.
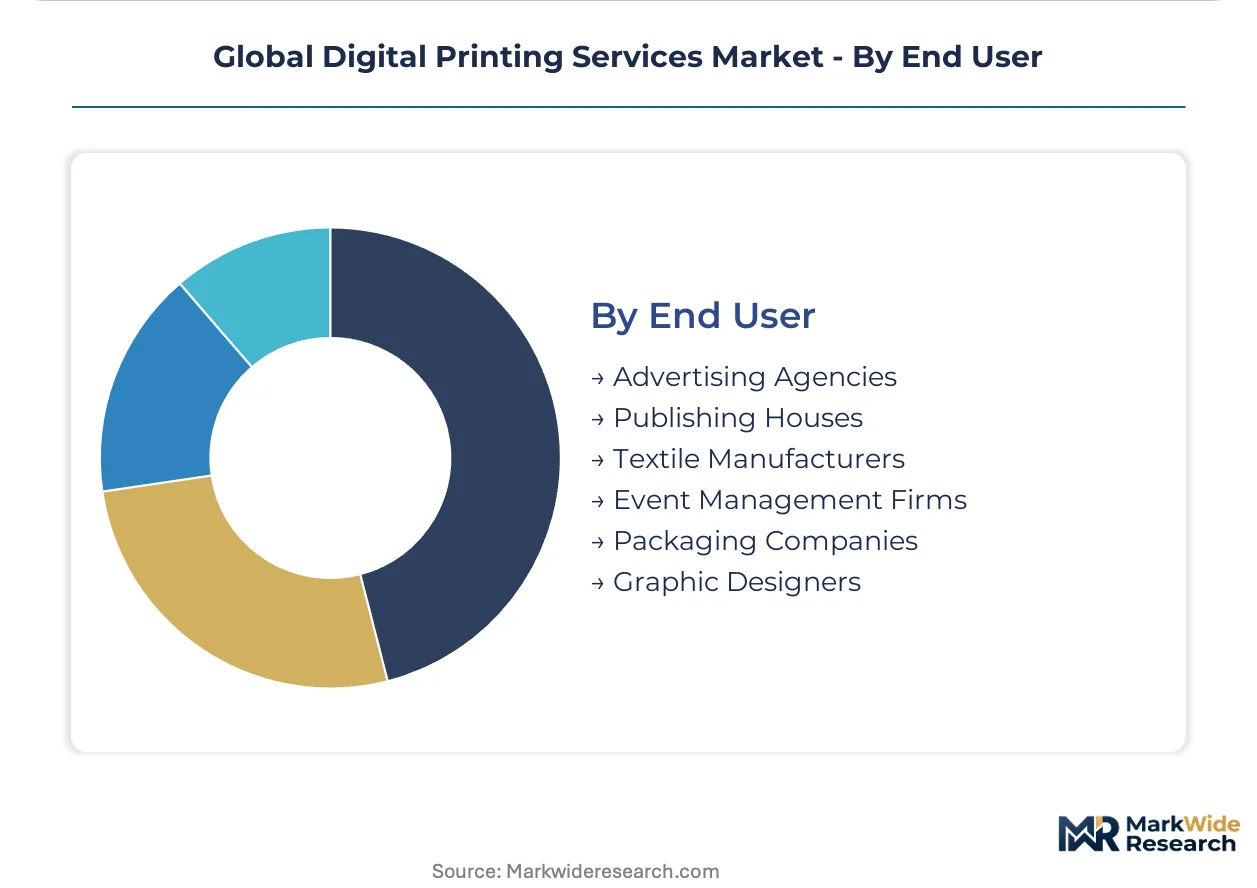
End User:
Customer sophistication tiers separate specification-fluent brand owners from price-sensitive intermediaries with divergent service level requirements.
- Advertising Agencies:Creative services firms managing brand visual identity and campaign execution. Mumbai and Delhi clusters in India show rising digital service penetration as brand localization campaigns fragment offset capacity.
- Packaging Companies:Converters serving food, beverage, and pharmaceutical brands with hybrid digital-conventional production lines. São Paulo state in Brazil sees craft brewing and premium spirits proliferation compressing label order quantities below rotary flexo thresholds.
- Publishing Houses:Book and periodical producers adopting print-on-demand distribution models.
- Textile Manufacturers:Fabric mills and garment decorators integrating digital decoration into supply chains.
- Event Management Firms:Corporate and entertainment producers requiring rapid-turn signage and promotional materials.
- Graphic Designers:Independent creative professionals and small studios sourcing production services.
Advertising agencies represent the deepest existing penetration, while packaging companies show the steepest expansion trajectory as converters consolidate capacity around hybrid production lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production geography as compliance-cost differentials push digital printing investment toward jurisdictions with stable chemistry standards and accessible emission-control financing.
United States
Pharmaceutical serialization mandates and SKU proliferation in beverage packaging drive converter investment in digital label capacity. EPA New Source Performance Standards tighten VOC thresholds for commercial print facilities, accelerating solvent-to-UV migration timelines. California and Texas host the densest clustering of hybrid digital-conventional packaging lines serving direct-to-consumer merchants.
Germany
Beverage brands validate direct-to-board printing on uncoated folding cartons, eliminating lamination steps and compressing applied costs. ECHA REACH pigment restrictions reshape ink formulation sourcing across European service providers. The Rhine-Ruhr and Baden-Württemberg industrial corridors concentrate high-speed inkjet foundry capacity for export-oriented converters.
Japan
Electronics manufacturers demand serialized packaging with 48-hour changeover capabilities for component distribution. METI industrial standards govern color management certification for cross-border contract proofing acceptability. The Kanto and Kansai metropolitan areas anchor domestic production of piezoelectric printhead systems and aqueous inkjet chemistry.
China
Domestic equipment producers scale high-speed inkjet foundry capacity, reducing hardware delivery cycles for mid-tier commercial printers. MEE emission guidelines tighten solvent-based operation permits in coastal manufacturing zones. The Yangtze River Delta and Pearl River Delta clusters integrate digital front ends with existing offset capacity for export packaging.
India
Fragmented offset capacity and rising brand localization campaigns create white space for on-demand digital service models. BIS standards for ink chemistry remain less stringent than REACH equivalents, attracting formulation testing and pilot production. Mumbai and Delhi-NCR clusters see fastest penetration of variable-data commercial print for financial services and retail.
Global Digital Printing Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue UV-curing specialization and textile sublimation niches. The vendor base stratifies across three maturity tiers: diversified technology conglomerates with full-stack hardware and consumables portfolios; mid-scale regional equipment fabricators competing on delivery speed and retrofit compatibility; and application-specific specialists dominating narrow verticals like photographic reproduction or industrial signage. Consolidation pressure concentrates among solvent-based equipment holders facing accelerated EPA compliance deadlines. Dominant competitive moves include capacity expansion in high-speed inkjet foundries and strategic partnerships between press manufacturers and compliant ink formulators.
Within the diversified technology tier, HP Inc., Canon Inc., and Durst Group AG exemplify contrasting archetypes. HP Inc. anchors enterprise print contracts through integrated hardware-subscription models. Canon Inc. occupies a position in commercial photo production anchored by proprietary imaging systems. Durst Group AG represents UV-curing specialization for industrial-scale signage applications. These three entities collectively illustrate the competitive spectrum from volume-driven consumables economics to premium-tier application engineering.
| Leading Market Players |
|---|
| HP Inc. |
| Canon Inc. |
| Xerox Corporation |
| Ricoh Company Ltd. |
| Seiko Epson Corporation |
| Konica Minolta Inc. |
| Mimaki Engineering Co., Ltd. |
| Roland DG Corporation |
| Durst Group AG |
| Others |
Supply & Pricing Matrix
EPA New Source Performance Standards for VOC emissions gate qualified ink supply access and premium-tier service pricing, forcing converters to absorb retrofit costs or cede high-margin pharmaceutical serialization contracts to compliant competitors. This environmental mandate concentrates pricing power among balance-sheet-strong incumbents while squeezing solvent-dependent mid-tier operators toward commodity positioning.
Pricing Analysis
Distributor margin layers dominate downstream economics, with authorized equipment resellers capturing 15-25 point markups on Japanese and Chinese inkjet hardware before value-added service bundling. Pricing stratifies across ISO 12647-7 certified premium tiers, compliant standard tiers, and uncertified economy tiers, with certification backlog queues extending six to nine months. Cost compression in the economy tier intensifies as Chinese equipment producers reduce hardware delivery cycles and compress entry capital requirements. Brand-direct pharmaceutical and beverage packaging converters show lowest price sensitivity, while transactional document resellers face acute margin pressure from cloud-based alternatives.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's MEE emission guidelines are reshaping sourcing patterns for ink formulation and printhead assembly. Specialty pigment production clusters in China and India, with piezoelectric printhead manufacturing anchored in Japan and high-speed inkjet foundry capacity scaling across the Yangtze River Delta. Supply chain vulnerability centers on single-source dependency for nanoscale pigment dispersions critical to water-based folding carton applications. Distribution runs through authorized dealer networks for hardware and direct bulk contracts for consumables, with regional formulators maintaining captive supply relationships to hedge tariff exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where pharmaceutical serialization mandates and EPA VOC enforcement timelines create replacement demand cycles independent of macro print volume trends.
For Market Incumbents: Lock in compliant capacity advantages by accelerating UV-LED curing retrofit programs ahead of EPA enforcement timelines, while securing multi-year ink formulation supply agreements with REACH-certified European suppliers. Consolidation pressure from solvent-based equipment holders facing accelerated compliance deadlines creates acquisition opportunities for balance-sheet-strong operators seeking geographic density in California and Texas packaging clusters.
For New Entrants and Emerging Players: Capture white space in India's fragmented commercial print modernization, where Mumbai and Delhi-NCR clusters show rising brand localization demand without established digital service infrastructure. UV-curing specialization for three-dimensional packaging formats offers the most penetrable application wedge, with direct-to-object decoration on beverage and cosmetic containers commanding premium positioning absent from flatbed commodity segments.
For Investors and Strategic Acquirers: Roll-up economics work for hybrid digital-conventional packaging converters because SKU proliferation across consumer packaged goods compresses run lengths below rotary flexo minimums faster than organic capacity expansion. Target family-owned print shops with electrophotography-trained operator bases requiring eighteen-month retraining curves, creating captive technician scarcity moats. Watch ISO 12647-7 proofing accreditation queue lengths as the signal for contract eligibility inflection and brand-direct relationship access.
| Strategic Initiative | Industry Significance |
|---|---|
| UV-LED Curing Retrofit Program | EPA New Source Performance Standards compliance secures pharmaceutical serialization contract eligibility. |
| High-Speed Inkjet Foundry Partnership | Japanese and Chinese equipment producers reduce hardware delivery cycles for mid-tier commercial printers. |
| REACH-Compliant Ink Formulation Supply Agreement | ECHA pigment restrictions reshape sourcing security for European service provider networks. |
| ISO 12647-7 Proofing Accreditation Investment | Six-to-nine month queue delays create first-mover advantage for brand-direct relationship capture. |
| Hybrid Production Line Consolidation | SKU proliferation in beverage packaging compresses run lengths below rotary flexo economic thresholds. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market cluster combining interviews with packaging converter operations directors, commercial print procurement managers, ink formulation technical leads, and digital press OEM channel partners. Secondary validation draws from EPA enforcement guidance documents, ECHA REACH substance restriction updates, ISO 12647 color management standards, and customs data on printing machinery trade flows. Bottom-up equipment shipment tracking triangulates against top-down service revenue estimates across technology and application segments.
Rate-of-change decomposition separates volume effects from mix-shift and pricing components across the projection horizon. Segmentation dimensions modeled include service type, application, technology, and end-user sophistication tier, with additional granularity on regulatory compliance status. CAGRs derive from fitted trend extrapolation adjusted for replacement cycle timing and capital expenditure intention surveys. Industry-specific forecast inputs incorporate pharmaceutical serialization mandate implementation schedules and EPA VOC threshold enforcement timelines.
Tariff escalation on Chinese pigment imports, accelerated EPA compliance deadlines without retrofit financing availability, and single-pass inkjet reliability failures in corrugated substrates are the dominant revision risks that could compress or extend replacement demand timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Global RFID and Barcode Printer Market
Printing Technology
Print on Demand Software Market
Printing Technology
Book Printing Service Market
Printing Technology
Cloud Print Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Industrial Printer Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Photo Printing Market
Printing Technology
Web to Print Market
Printing Technology
Large Format Printer Market
Printing Technology
Professional Printers Market
Printing Technology
Roll to Roll Printing Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Photo Printing and Merchandise Market