
 Photo Printing Market | 2026-2036
Photo Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Photo Printing Market Intelligence
Market Context
Professional photographers and commercial studios is unwinding the historical dominance of casual consumer printing as the primary revenue anchor. Shutterfly leverages its vertical integration across software, fulfillment, and direct-to-consumer logistics to sustain repeat purchase rates in the personal use segment. Nations Photo Lab differentiates through specialized fine-art and gallery-wrap offerings that command premium positioning among professional photographers. WHCC anchors its competitive stance by controlling regional production facilities that shorten delivery windows for event and portrait workflows.
Technical Definition and Segment Structure
Photo printing encompasses the physical reproduction of digital image files onto substrates including photographic paper, canvas, metal, and acrylic through processes such as inkjet droplet deposition, dye sublimation thermal transfer, and silver-halide chemical development, yielding outputs ranging from wallet-sized portraits to large-format exhibition displays. The professional photography application commands the highest margin pools due to substrate specialization and color calibration requirements, while digital presses represent the fastest-expanding product type as print service providers adopt short-run, on-demand production models. Online retailers now dominate distribution channel growth by collapsing the traditional multi-step wholesale pipeline between production assets and end buyers.
Regulatory Environment and Outlook
FDA guidelines on ink and toner chemical composition influence consumable sourcing decisions for equipment manufacturers serving the North American market, while REACH compliance in Europe restricts certain dye formulations and drives reformulation investments across the supply base. ISO 3664 viewing condition standards and color management protocols shape product certification requirements that professional end users demand before equipment procurement. Stakeholders must monitor how evolving chemical safety frameworks in multiple jurisdictions interact with sustainability claims now embedded in corporate and institutional procurement criteria.
Market Dynamics
On-demand production platforms are compressing traditional wholesale distribution layers, forcing equipment manufacturers and print service providers to reconfigure fulfillment architectures around direct-to-consumer workflows and micro-factory networks.
Growth Catalysts
- Dye Sublimation Thermal Transfer:Commercial studios in Japan and Germany adopt this process for its continuous-tone output and archival stability, displacing silver-halide workflows in high-margin portrait and fine-art segments.
- Event Photography Workflows:Wedding and corporate event photographers drive consumable throughput through same-day printing demands, creating predictable recurring revenue streams for equipment lessors.
- REACH Compliance Reformulation:European chemical safety mandates accelerate investment in water-based ink alternatives, opening procurement channels for compliant consumable suppliers.
Market Restraints
- Pigment and Dye Input Volatility:Petroleum-derived colorant costs fluctuate with energy markets, compressing margin pools for mid-volume print service operators in North America.
- Silver-Halide Chemistry Dependency:Declining raw silver availability and environmental discharge restrictions constrain traditional photochemical processing capacity in legacy facilities.
- Smart Display Substitution:Digital photo frames and high-resolution screens displace physical print demand in casual consumer gifting applications.
Strategic Opportunities
- India E-Commerce Fulfillment:Underdeveloped professional photography infrastructure and expanding middle-class celebration culture create whitespace for on-demand platform entry.
- ISO 3664 Certification Services:Color management audit and calibration offerings address professional photographer procurement criteria, generating recurring service revenue adjacent to hardware sales.
- Metal Substrate Convergence:UV-curable inkjet bonding with aluminum panel fabrication opens architectural and commercial interior applications beyond traditional photographic markets.
Industry Challenges
- Color Science Talent Scarcity:ICC profile engineering and spectrophotometry expertise concentrate in aging workforce cohorts, constraining quality assurance scaling for growing print networks.
- Legacy RIP Software Integration:Raster image processor upgrades encounter compatibility friction with existing workflow management systems, delaying production efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photo Printing Market |
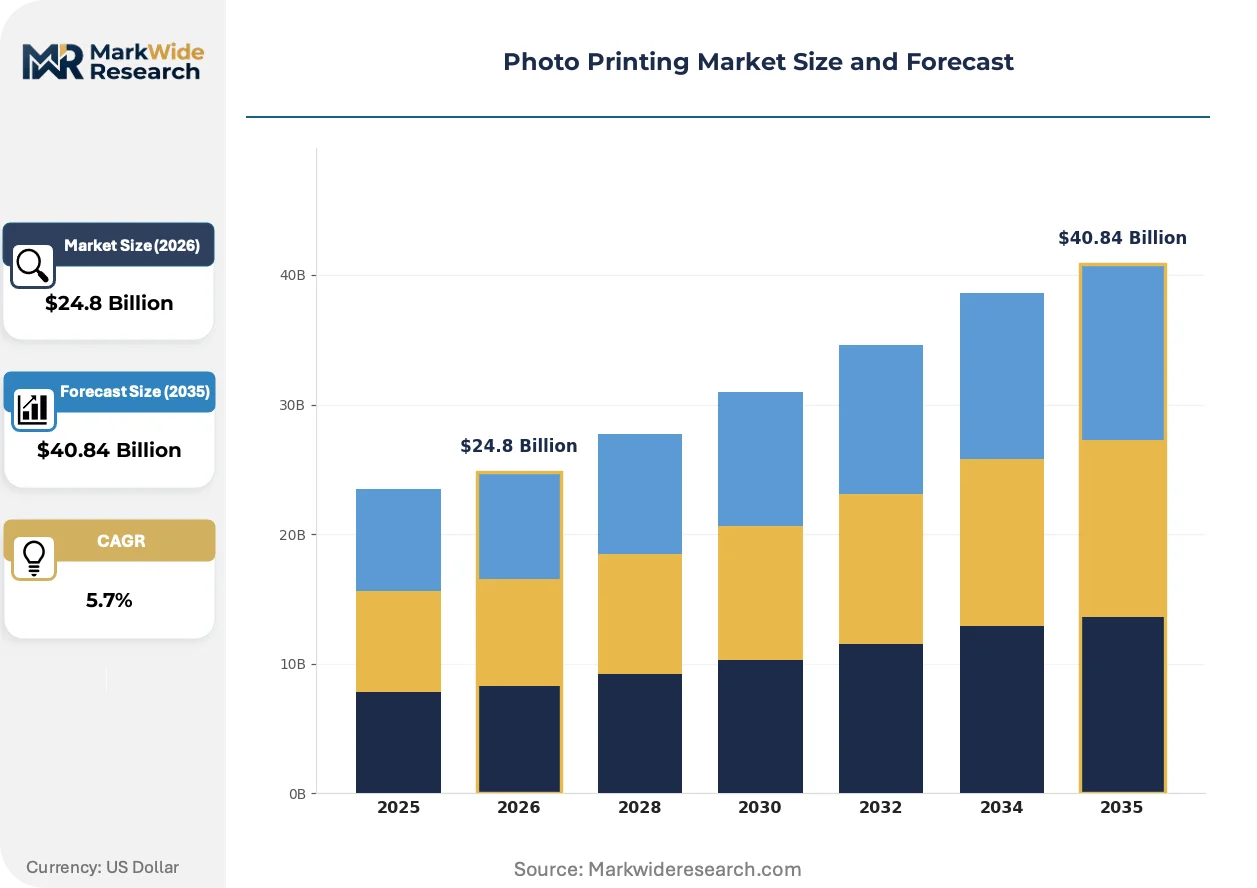
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Dye Sublimation Printers, Thermal Printers, Laser Printers, Digital Presses Application: Personal Use, Professional Photography, Commercial Advertising, Event Photography, ID & Passport Printing End User: Photo Studios, Printing Shops, Corporate Offices, Educational Institutions, Freelancers Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesale Distributors, Authorized Dealers |
| Companies Covered | Nations Photo Lab, WHCC, Printique, Snapfish, Shutterfly, Mpix, Whitewall, Xpozer, Bay Photo Lab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photo Printing Market Strategic Shifts & Innovations
Production technology, chemical regulation, and procurement architecture are simultaneously restructuring how print services acquire equipment, formulate consumables, and reach end buyers.
Industrial inkjet printheads are bifurcating the equipment installed base. High-speed single-pass arrays capture volume-driven photofinishing operations in the United States, while precision multi-pass systems retain position in proofing and gallery-print studios. This technological split is compressing the addressable market for mid-speed continuous-feed alternatives.
REACH authorization requirements for certain azo dye formulations are forcing consumable manufacturers to accelerate bio-based pigment development. European formulators face reformulation timelines that compress product certification cycles. Professional photography labs in Germany and France are responding by consolidating supplier relationships around compliant pre-certified chemical portfolios.
Direct-to-consumer platform purchasing is displacing wholesale distributor relationships. Millennial and Gen-Z buyers in Japan and the United States now expect design-to-delivery interfaces with real-time production tracking. This channel compression rewards operators with captive fulfillment networks and penalizes those dependent on third-party logistics coordination.
Photo Printing Market Segmentation
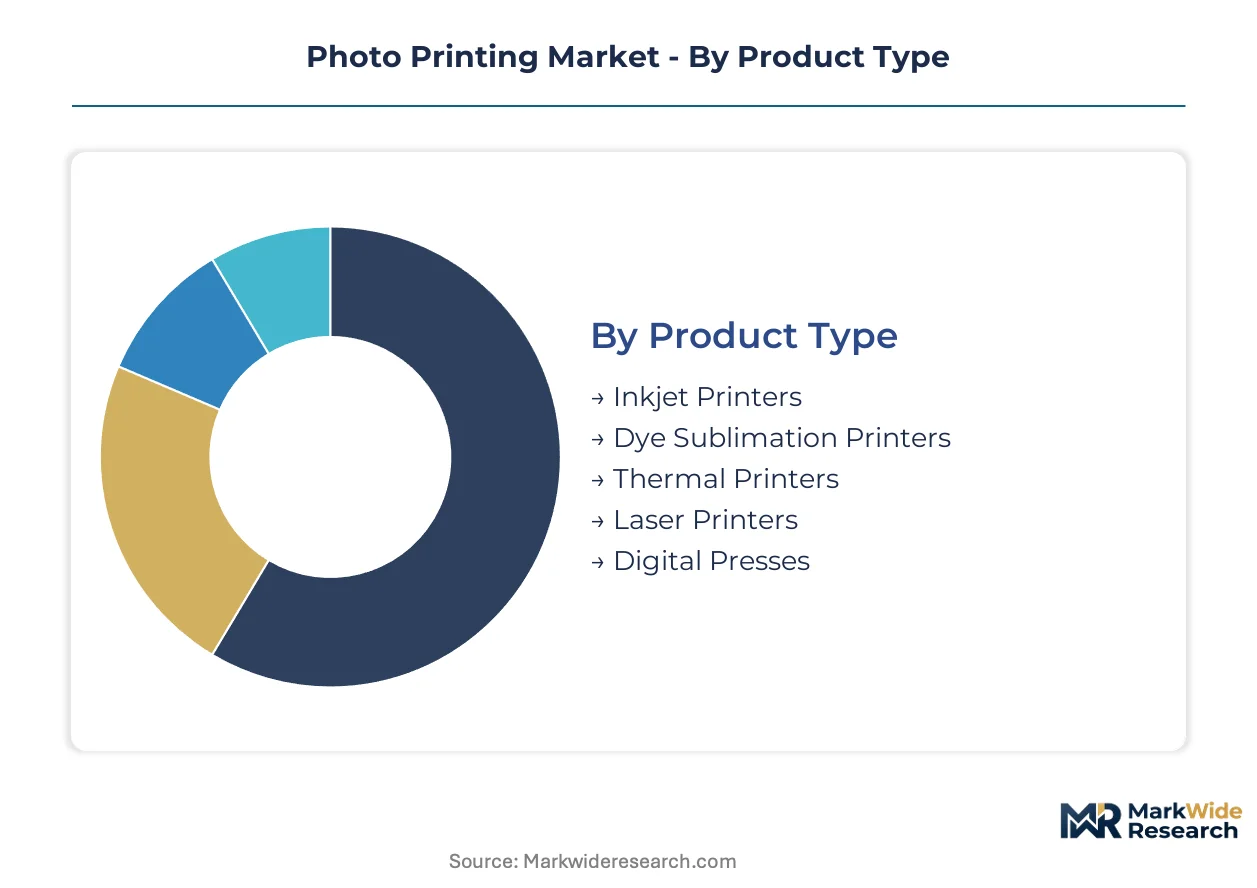
Segment boundaries in photo printing equipment and services reflect divergent vulnerability to digital substitution, chemical regulation, and workflow automation. Understanding these fault lines clarifies where hardware investments concentrate versus where service revenue models dominate.
Product Type:
Dye sublimation and thermal technologies face the most acute substitution pressure from smartphone-first sharing habits, while digital presses and inkjet systems find shelter in professional and commercial segments where physical output retains irreplaceable value.
- Inkjet Printers:Piezoelectric and thermal inkjet heads deposit aqueous or solvent-based pigments onto porous substrates with droplet precision measured in picoliters. Demand clusters in United States proofing studios and German fine-art reproduction houses where ICC profile flexibility outweighs speed requirements.
- Dye Sublimation Printers:Solid dye panels undergo thermal transfer to polymer-coated paper, producing continuous-tone gradations without visible dot patterns. Japanese portrait studios and German event photographers specify these systems for same-day delivery workflows where archival stability commands premium positioning.
- Thermal Printers:Direct thermal and thermal transfer mechanisms serve high-frequency, low-margin outputs through wax-resin ribbon or heat-sensitive paper chemistry.
- Laser Printers:Electrophotographic toner fusion delivers speed advantages in corporate document-photograph hybrid environments where monochrome efficiency dominates.
- Digital Presses:Sheet-fed and web-fed inkjet or toner systems enable variable-data short runs with inline finishing. Print service providers in the United States adopt these for on-demand photo merchandise production.
Inkjet printers retain volume leadership across installed base counts; digital presses hold the steepest expansion curve as service providers retool for batch-size-one economics.
Application:
Margin concentration follows the technical sophistication ladder, with segments requiring color calibration and substrate specialization capturing value that casual use cases cannot replicate.
- Personal Use:Consumer-grade output for home albums and informal gifting faces relentless compression from social media sharing and smart display substitution. Volume persists in Japan's aging demographic cohorts where physical photograph rituals remain culturally embedded.
- Professional Photography:Fine-art, portrait, and commercial studios demand spectrophotometric color matching and museum-grade substrate options. German and United States photographers drive specification intensity here, with gallery-wrap canvas and aluminum dibond mounting commanding sustained premium pricing.
- Commercial Advertising:Point-of-sale and retail environment graphics require weather-resistant UV-curable output on rigid substrates.
- Event Photography:Wedding and corporate event workflows generate same-day print demands with tight turnaround windows.
- ID & Passport Printing:Government-specified durability and security features constrain equipment selection to certified thermal or dye-sub systems.
Personal use retains volume leadership in unit terms; professional photography holds the steepest expansion curve as casual consumers abandon physical printing.
End User:
Procurement authority distributes across organizational scales, with independent operators prioritizing equipment leasing flexibility against institutional buyers emphasizing total cost of ownership and compliance documentation.
- Photo Studios:Independent and chain portrait businesses in Japan and Germany specify color-calibrated workflows with captive finishing capabilities. These operators concentrate equipment investment in dye sublimation and precision inkjet systems for client-facing same-day service.
- Printing Shops:Generalist commercial printers adding photo services face margin pressure from specialized competitors but capture walk-in convenience demand.
- Corporate Offices:Marketing and HR departments source photo output for identification, events, and promotional materials through managed print service contracts.
- Educational Institutions:University photography programs and K-12 yearbook production drive seasonal demand spikes for mid-volume equipment.
- Freelancers:Independent event and portrait photographers prioritize portable dye-sub units and cloud-integrated ordering platforms.
Photo studios retain volume leadership in specialized equipment procurement; freelancers are gaining share fastest as platform economics lower entry barriers.
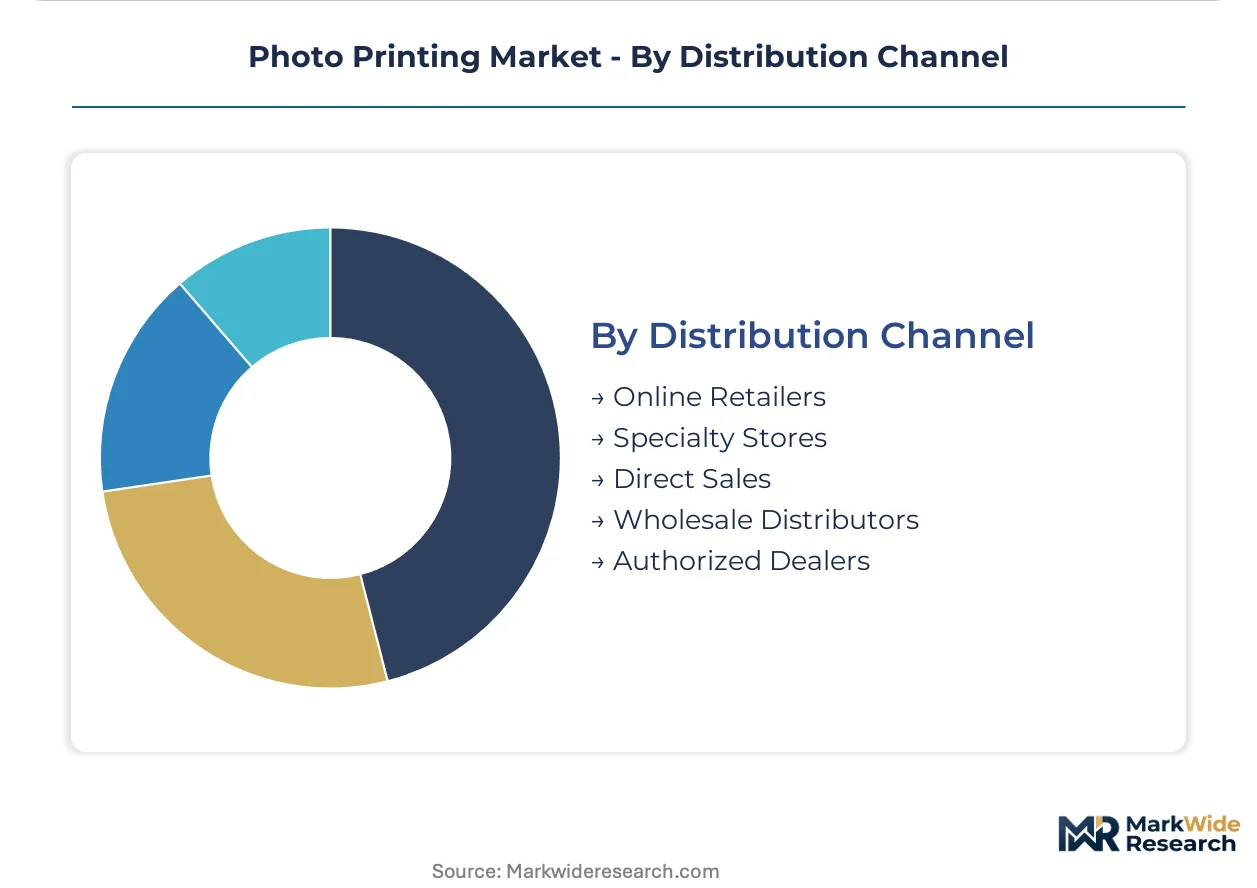
Distribution Channel:
Channel structure reflects the collapse of traditional wholesale layers, with direct digital interfaces capturing growth at the expense of inventory-carrying intermediaries.
- Online Retailers:Design-to-delivery platforms with real-time production tracking dominate millennial and Gen-Z purchasing in the United States and Japan. These channels compress delivery windows and eliminate geographic constraints on supplier selection.
- Specialty Stores:Photography-focused retailers in Germany and Japan provide hands-on equipment evaluation and color management consultation that professional buyers demand before capital commitments.
- Direct Sales:Manufacturer-owned account teams serve high-volume commercial and government purchasers with customized service agreements.
- Wholesale Distributors:Regional inventory buffers persist for consumables and entry-level hardware where immediate availability outweighs price optimization.
- Authorized Dealers:Certified service networks support enterprise and institutional installations with maintenance contracts and training programs.
Online retailers retain volume leadership in consumer and small-business segments; direct sales channels are expanding most quickly in enterprise and government procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional photographers and commercial studios in the United States, Germany, and Japan generate the highest equipment procurement intensity, with each market shaped by distinct regulatory frameworks and production network configurations.
United States
Event photography workflows and personalized gifting platforms drive consumable throughput across Texas, California, and New York Metro clusters. FDA guidelines on ink chemical composition shape consumable sourcing decisions for equipment manufacturers serving North American print service providers. The Pacific Northwest corridor hosts specialized fine-art reproduction houses where spectrophotometric color matching commands premium positioning.
Germany
Fine-art and gallery-wrap offerings from professional photographers sustain demand for dye sublimation systems with archival stability specifications. ECHA REACH compliance mandates accelerate reformulation investments across the consumable supply base, restricting certain azo dye formulations. Bavaria and North Rhine-Westphalia concentrate precision inkjet installations serving museum-grade substrate workflows.
Japan
Portrait studios and aging demographic cohorts maintain physical photograph rituals through same-day delivery service expectations. METI industrial standards and JIS certification protocols influence equipment procurement criteria for commercial photography operations. The Kanto region around Tokyo anchors dye-sub system deployment for client-facing event photography workflows.
India
Expanding middle-class celebration culture and underdeveloped professional photography infrastructure create whitespace for on-demand platform entry. Central Electricity Authority grid reliability standards influence production facility location decisions for commercial print operations. Maharashtra and Karnataka host emerging e-commerce fulfillment networks targeting wedding and corporate event segments.
United Kingdom
Corporate marketing departments and educational institutions sustain mid-volume equipment demand through seasonal procurement cycles. GDPR data handling requirements shape cloud-integrated ordering platform architectures for photography service providers. London and the Southeast corridor concentrate specialty retail channels providing hands-on equipment evaluation for professional buyers.
Photo Printing Market Key Industry Players
Player mix skews toward vertically integrated direct-to-consumer platforms and specialized fine-art service providers, creating a bifurcated structure with limited mid-tier consolidation. Equipment manufacturers and consumable suppliers occupy distinct competitive layers from print fulfillment operators. Two strategic archetypes dominate: captive logistics networks with software-fulfillment integration, and premium substrate specialists with color science capabilities. Competitive moves center on regional production facility expansion and ISO 3664 certification service adjacencies.
Within the premium-tier vector, Nations Photo Lab and WHCC exemplify divergent geographic concentration strategies, while Shutterfly anchors the vertically integrated direct-to-consumer archetype. These three occupy positions that reflect the market's structural split between specialized professional service and mass-market platform economics.
| Leading Market Players |
|---|
| Nations Photo Lab |
| WHCC |
| Printique |
| Snapfish |
| Shutterfly |
| Mpix |
| Whitewall |
| Xpozer |
| Bay Photo Lab |
| Others |
Cost & Logistics Intelligence
Dye sublimation ribbon stock displacing silver-halide chemistry in German and Japanese professional labs simultaneously concentrates procurement leverage among three specialty chemical suppliers and compresses margin pools for mid-volume print service operators facing petroleum-derived pigment cost volatility.
Pricing Analysis
Cost-plus contracts with petroleum indexation dominate consumable supply agreements between Japanese dye-panel manufacturers and North American print service providers. Pricing stratifies across archival-grade, professional-calibrated, and consumer-economy tiers, with ISO 3664 certification commanding substantial premiums. Cost compression in the consumer tier is intensifying because smartphone sharing habits erode volume leverage. Freelance photographers exhibit highest price sensitivity, while museum-grade fine-art studios demonstrate inelastic demand.
Supply Chain Analysis
Fujifilm's Kanagawa dye-substrate facility underwrites global archival ribbon availability, creating single-source vulnerability for European formulators awaiting REACH-compliant reformulations. Manufacturing concentrates in Japan, Germany, and the United States, with raw silver availability constraints and azo dye regulatory restrictions feeding input volatility. Distribution runs through direct-to-consumer platforms collapsing traditional wholesale layers, rewarding operators with captive fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
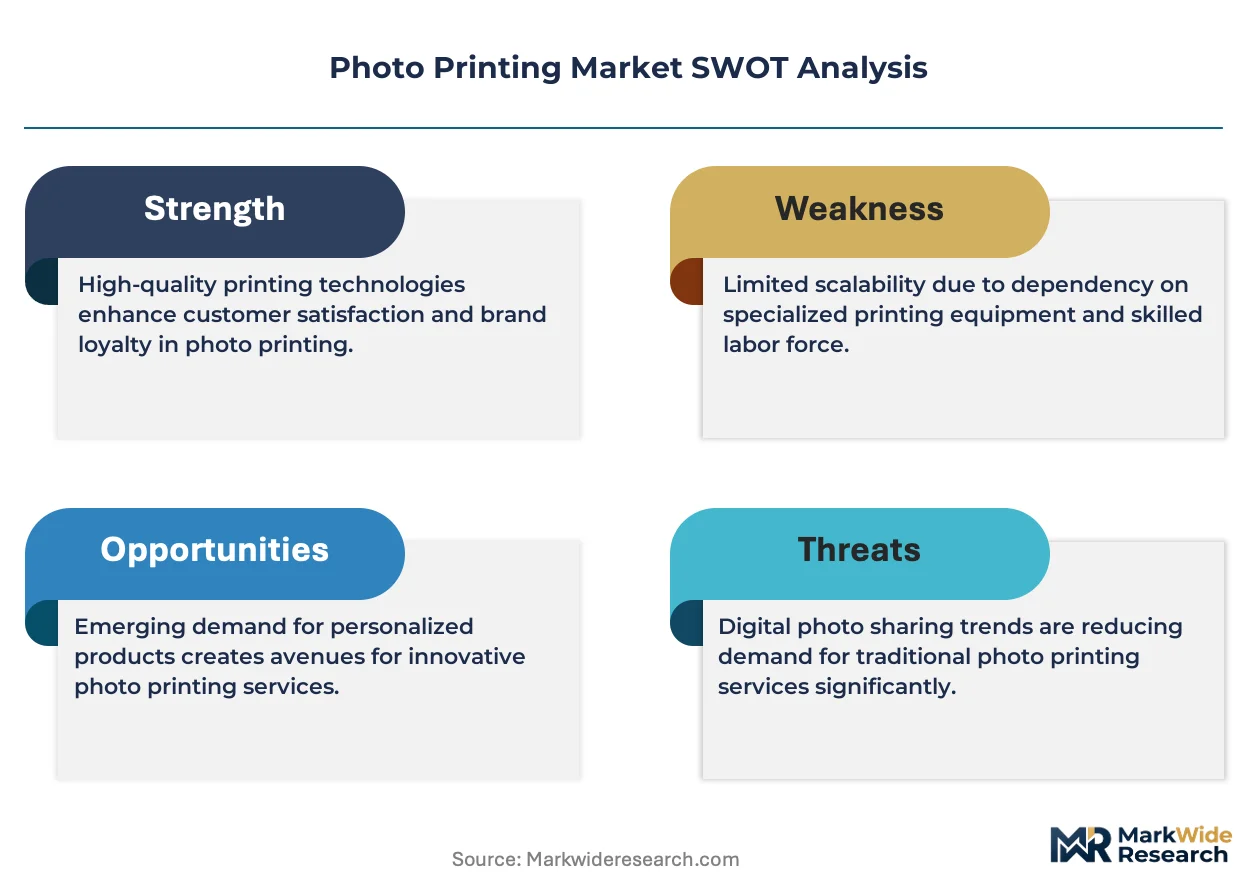
Physical photo printing operates as a substitution defense against smart display and digital frame encroachment, with incumbents navigating smartphone-first sharing habits that erode casual consumer volume while professional segments retain irreplaceable substrate value.
For Market Incumbents: Secure captive dye-sublimation ribbon supply through backward integration into polymer-coated substrate manufacturing, insulating margin pools from petroleum cost volatility. Deepen ISO 3664 certification service adjacencies to lock in professional photographer switching costs against emerging platform competitors.
For New Entrants and Emerging Players: REACH fast-track compliance for water-based ink formulations opens procurement channels with German and French professional labs consolidating supplier relationships. Target India's underdeveloped event photography infrastructure with cloud-integrated same-day delivery platforms, leveraging expanding middle-class celebration culture and underpenetrated e-commerce fulfillment networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer platforms possessing captive logistics networks but limited color science depth. Long-term viability hinges on professional segment retention against digital substitution; monitor dye-sublimation equipment utilization rates as inflection indicator for physical print demand durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Micro-Factory Expansion | Shortens delivery windows for Texas and California event photography clusters. |
| REACH-Compliant Reformulation Partnership | Secures German and French lab procurement against azo dye restrictions. |
| ISO 3664 Certification Service Launch | Generates recurring revenue adjacent to dye-sub hardware sales. |
| Cloud-Integrated Design Platform | Captures millennial and Gen-Z buyers expecting real-time production tracking. |
| Metal Substrate UV Bonding Development | Opens architectural applications beyond traditional photographic markets. |
Research Approach
Two parallel data streams informed the analysis: structured conversations with equipment procurement managers at commercial print operations, color science directors at fine-art reproduction houses, and consumable sourcing leads at dye-sub manufacturers; and secondary validation against METI industrial standards filings, ECHA REACH authorization databases, FDA chemical composition guidelines, and trade flow records for silver-halide and dye-substrate inputs. Bottom-up equipment shipment tallies and top-down print service revenue estimates underwent cross-triangulation.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning print technology type, application sophistication tier, end-user organizational scale, and distribution channel architecture. CAGRs derived from equipment replacement cycle analysis, consumable throughput per installed base unit, and platform order volume trajectories. Industry-specific inputs incorporated professional photographer population counts, event photography workflow frequency patterns, and e-commerce fulfillment network density metrics.
Decision-makers should treat outputs as directional under assumptions of sustained professional photography demand and stable regulatory compliance timelines; material deviation in digital substitution velocity or chemical safety framework stringency would warrant model refresh. Practitioners should keep alternative scenarios live as smart display resolution improvements and cloud-based image sharing platform feature evolution reshape casual consumer preferences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Printing Machinery Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Digital Franking Machine Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
Point of Sale (Pos) Printers Market
Printing Technology
Digital Paper System Market
Printing Technology
Photo Printing and Merchandise Market
Printing Technology
Nordic Commercial Printing Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
US Print on Demand Market
Printing Technology
ID Card Printers Market
Printing Technology
Managed Print Services Market
Printing Technology
Retail Printers Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Digital Graphic Printing Market