
 Card Printer Ribbons Market | 2026-2036
Card Printer Ribbons Market Size, Share, and Industry Trends Forecast 2026-2036
Card Printer Ribbons Market Analysis
High-durability resin ribbons is bifurcating the Card Printer Ribbons landscape into premium-specification and cost-optimized procurement tiers. Zebra Technologies Corporation leverages its North American channel density to sustain aftermarket ribbon attach rates alongside hardware placements. HID Global Corporation anchors enterprise security contracts through integrated card-and-supply bundling. Evolis S.A. competes in the European small-batch segment with specialized wax-resin formulations for short-run personalization.
Card printer ribbons are thermal transfer consumables composed of wax, resin, or hybrid ink coatings deposited onto polyester or PET film substrates, engineered to transfer precise dye patterns onto PVC or composite card bodies at temperatures between 150°C and 200°C. Color ribbons and half-panel ribbons lead procurement volumes in corporate and education end-user segments where full-bleed photographic quality is unnecessary, while full-panel resin ribbons command margin pools in government and healthcare applications demanding ten-year archival durability. Polyester and PET material grades dominate technical specifications due to thermal stability and tensile strength during high-speed print cycles.
ISO standards for card dimensional tolerances, REACH chemical compliance for substrate coatings in Europe, and FDA unique device identification mandates for healthcare credentials collectively shape product formulation and market access requirements across major economies. The EU AI Act and associated biometric data governance frameworks are extending compliance burdens to card issuance systems handling facial-image credentials. Stakeholders must monitor regulatory divergence between data-localization regimes and chemical-substance restrictions when configuring regional supply and certification strategies.
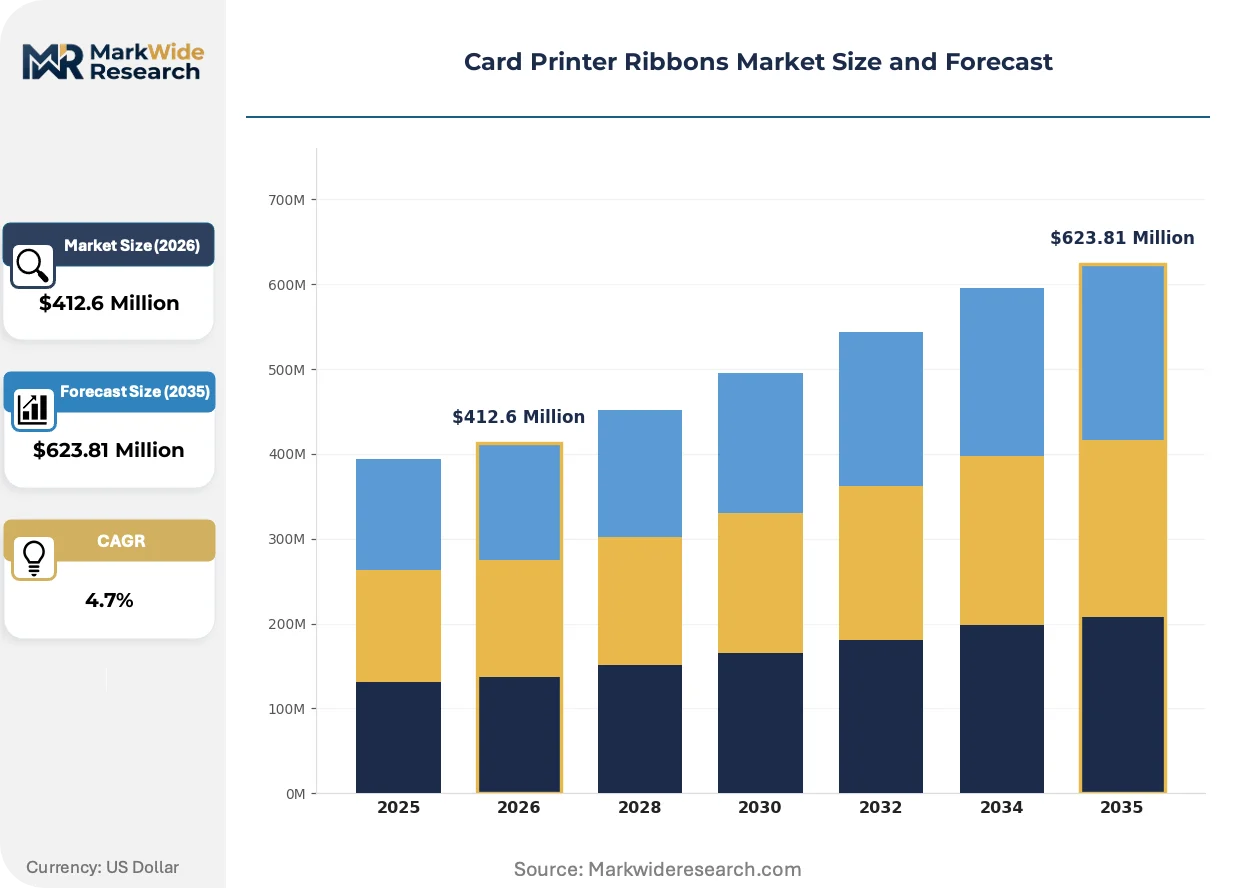
Market Dynamics
Healthcare credential modernization and biometric data governance are compressing product lifecycles for card printer ribbons, forcing suppliers to validate formulations against ten-year archival standards while managing REACH chemical compliance costs.
Growth Catalysts
- FDA UDI Mandates:Unique device identification requirements for healthcare credentials in the United States are expanding secure patient ID issuance programs, sustaining procurement volumes for high-durability resin ribbons in hospital networks.
- EU AI Act Biometric Provisions:Facial-image credential handling protocols across European healthcare and government sectors are tightening material specifications for ribbons used in national ID modernization programs.
- Half-Panel Ribbon Technology:Wax-resin hybrid formulations are capturing volume in corporate and education segments where full-bleed photographic quality is unnecessary, reducing per-card consumable costs.
Market Restraints
- Petroleum-Derived Substrate Volatility:Polyester and PET film feedstock costs fluctuate with crude oil markets, compressing margin pools for ribbon converters unable to pass through input price swings.
- East Asian Substrate Concentration:Thermal transfer film manufacturing clusters in China and South Korea create supply vulnerability for European and North American ribbon finishers.
- Digital Credential Substitution:Mobile-based identity verification platforms are displacing physical card issuance in transit and retail loyalty applications.
Strategic Opportunities
- India National ID Scale-Up:Aadhaar-linked credential programs and state-level welfare card issuance present volume expansion potential for wax-resin ribbon suppliers.
- Cloud-Connected Print Management:Integration of ribbon consumption tracking with managed print services creates recurring revenue attachment for hardware-ribbon bundling models.
- EU Green Deal Chemical Compliance:Early reformulation to bio-based coating vehicles positions suppliers for preferred procurement status under public sector environmental purchasing criteria.
Industry Challenges
- ISO/IEC 7810 Dimensional Tolerance Certification:Card body standard compliance testing extends product validation timelines, delaying regional market entry for new ribbon formulations.
- Legacy Encoder Integration Complexity:Healthcare and government facilities with embedded card personalization infrastructure face high switching costs when migrating to newer ribbon chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Card Printer Ribbons Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $623.81 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monochrome Ribbons, Color Ribbons, Half-Panel Ribbons, Full-Panel Ribbons Material: Polyester, PVC, Nylon, PET Delivery Mode: Retail, Wholesale, Online, Direct Sales End User: Government, Education, Healthcare, Corporate |
| Companies Covered | Zebra Technologies Corporation, HID Global Corporation, Entrust Datacard Corporation, Evolis S.A., Magicard Limited, Matica Technologies, IDP Corporation, Nisca Corporation, AlphaCard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Card Printer Ribbons Market Emerging Trajectories
Thermal transfer ribbon technology is bifurcating between archival-grade resin systems and cost-optimized wax-resin hybrids, while regulatory pressure on chemical formulations accelerates substrate innovation cycles.
Re-transfer printing technology is displacing direct-to-card thermal transfer in high-security credential applications. Government agencies and financial institutions are adopting dye-sublimation re-transfer systems for edge-to-edge coverage and tamper-evident features. This migration is compressing demand for conventional YMCKO ribbons in premium specification tiers while expanding the addressable market for specialized re-transfer films.
REACH SVHC candidate list expansion is forcing reformulation of ribbon coating vehicles across European supply chains. ECHA scrutiny of phthalate plasticizers and halogenated flame retardants is driving substitution toward bio-based wax carriers and non-halogenated resin binders. Ribbon finishers serving German automotive and French healthcare credential programs are prioritizing pre-registration of alternative chemistries to maintain market access.
Managed consumables contracts are consolidating purchasing authority for card printer ribbons within integrated facility management providers. Corporate and education buyers are shifting from spot procurement to multi-year supply agreements bundling hardware, ribbons, and print management software. This concentration is most visible in United States healthcare systems and German municipal credential programs, where procurement departments favor single-source accountability over fragmented supplier relationships.
Card Printer Ribbons Market Segmentation
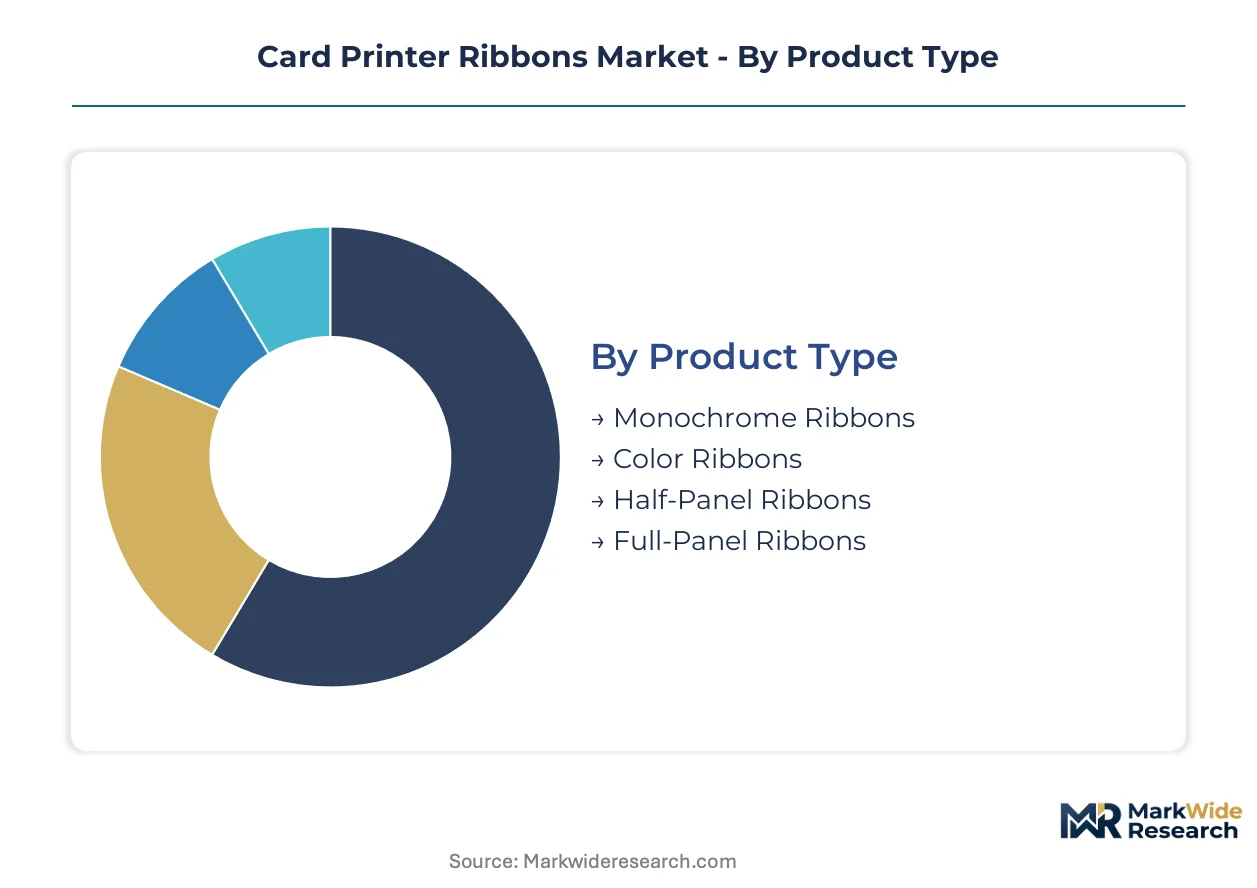
Ribbon formulation and procurement channel choices determine margin capture and compliance exposure across card printer consumables. Each segmentation dimension reveals distinct cost structures and customer concentration patterns that suppliers must navigate.
Product Type:
Channel mix bifurcates sharply between hardware-bundled supply contracts and spot aftermarket purchases, with resin formulations commanding premium distribution through authorized dealer networks.
- Color Ribbons:Wax-resin hybrid coatings transfer CMYK dye patterns onto PVC substrates at 150°C to 180°C operating temperatures. Corporate and education buyers in the United States concentrate procurement through managed print service contracts that bundle hardware, software, and consumable replenishment.
- Half-Panel Ribbons:Partial-panel wax-resin formulations cover only the card image area, leaving magnetic stripe and signature panel zones unprinted to reduce per-card ink consumption. German municipal credential programs favor this format for cost-optimized national ID modernization where photographic quality requirements are modest.
- Monochrome Ribbons:Single-color resin or wax formulations for text-only applications such as barcode labels and temporary badges.
- Full-Panel Ribbons:Edge-to-edge resin systems delivering complete card surface coverage for high-security government credentials.
Color ribbons dominate installed base. Half-panel ribbons are where expansion concentrates.
Material:
Cost tier stratification separates commodity-grade substrates from specialized films validated for ten-year archival standards.
- PET:Polyethylene terephthalate film substrates withstand thermal cycling up to 200°C without dimensional distortion, enabling high-speed print head compatibility. Japanese healthcare credential issuers specify PET-grade ribbons for FDA UDI-mandated patient ID programs where print durability must survive sterilization exposure.
- Polyester:General-purpose thermal transfer films balance tensile strength against unit cost, serving volume corporate badge programs.
- PVC:Alternative substrate for specialized low-temperature printing applications with limited thermal stress tolerance.
- Nylon:High-flexibility film for curved or flexible card body formats in emerging wearable credential segments.
PET commands premium positioning. Polyester captures volume scale.
Delivery Mode:
Customer type dictates channel preference, with enterprise accounts consolidating through direct procurement while small-batch buyers fragment across retail and digital channels.
- Direct Sales:Manufacturer-to-end-user contracts with negotiated service level agreements and technical support integration. Government agencies in Germany and healthcare networks in the United States anchor this channel through multi-year consumables agreements.
- Wholesale:Distributor-mediated supply to value-added resellers and system integrators serving mid-market corporate accounts.
- Online:E-commerce procurement for small education institutions and retail loyalty program operators with intermittent replenishment needs.
- Retail:Counter sales through office supply and electronics channels for emergency replacement and small-quantity purchases.
Direct sales anchors enterprise value. Online channels are climbing the fastest.
End User:
Application requirements drive formulation selection, with regulatory mandates creating non-negotiable performance thresholds in credential-intensive sectors.
- Healthcare:Resin-dominant ribbons meeting FDA unique device identification mandates for patient wristbands and staff credentials. Hospital networks in the United States validate formulations against ten-year archival standards and chemical resistance to sterilants.
- Government:Full-panel resin systems for national ID, passport, and secure facility access credentials. EU AI Act biometric provisions in France and Germany tighten material specifications for facial-image credential handling.
- Corporate:Wax-resin hybrids for employee badge and visitor pass programs where cost per impression dominates procurement criteria.
- Education:Half-panel and monochrome formats for student ID and library card issuance with moderate durability requirements.
Healthcare drives premium specification. Corporate accounts deliver volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate buyers in Germany and Japan prioritize ten-year archival durability over unit cost, while education and retail loyalty operators in India and Brazil drive volume procurement of half-panel wax-resin formats. This elasticity divergence shapes regional supply chain configurations and margin capture potential.
United States
Hospital networks sustain resin ribbon demand through FDA UDI-mandated patient ID modernization and staff credential programs. HIPAA-aligned data handling protocols tighten material traceability requirements for thermal transfer consumables. Dallas-Fort Worth healthcare IT clusters concentrate procurement authority for multi-hospital system contracts.
Germany
Municipal credential programs favor cost-optimized half-panel ribbons for national ID card modernization with modest photographic requirements. ECHA REACH SVHC compliance costs accelerate reformulation toward bio-based coating vehicles. Bavarian automotive supplier badge programs anchor premium resin specification volumes.
Japan
Healthcare facilities specify PET-grade ribbons for patient wristbands requiring sterilization resistance and dimensional stability. METI industrial standards validate thermal transfer films for high-speed print cycle compatibility. Tokyo-Yokohama medical device manufacturing corridors concentrate credential issuance infrastructure.
India
Aadhaar-linked welfare card programs and state-level credential issuance expand wax-resin ribbon procurement volumes. BIS certification requirements for plastic card materials shape substrate selection for domestic ribbon finishers. Gujarat pharmaceutical manufacturing zones drive demand for chemical-resistant patient identification systems.
China
MIIT-guided smart city initiatives and public transit credential programs sustain thermal transfer consumable demand despite mobile identity displacement in retail segments. GB standards for card dimensional tolerances govern import substitution strategies for domestic ribbon converters. Shenzhen electronics manufacturing clusters supply thermal transfer film substrates to regional finishers.
Card Printer Ribbons Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium resin formulation specialists commanding margin pools in government and healthcare while volume-oriented wax-resin suppliers capture education and corporate badge markets. The vendor base stratifies across three tiers: integrated hardware-ribbon bundlers with managed print service contracts, independent ribbon specialists with formulation flexibility, and regional converters serving price-sensitive spot procurement. Consolidation pressures concentrate among mid-scale finishers lacking backward integration into substrate supply. Strategic moves center on multi-year consumables agreements with healthcare networks and pre-registration of REACH-compliant chemistries to secure European public sector access.
Among North American technology conglomerates with identification hardware portfolios, Zebra Technologies Corporation and HID Global Corporation exemplify integrated bundling archetypes that anchor enterprise security contracts through combined hardware-ribbon-service offerings. Evolis S.A. occupies a position within the European specialist tier, with its French S.A. structure signaling formulation-focused competition for small-batch personalization segments. These three entities represent distinct competitive vectors: scale-driven channel density, enterprise security integration, and regional formulation agility.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| HID Global Corporation |
| Entrust Datacard Corporation |
| Evolis S.A. |
| Magicard Limited |
| Matica Technologies |
| IDP Corporation |
| Nisca Corporation |
| AlphaCard |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at East Asian PET film manufacturing clusters shapes margin floors for ribbon finishers worldwide, concentrating pricing power among substrate suppliers while forcing downstream converters to absorb volatility or pass through costs via long-term healthcare contracts.
Pricing Analysis
REACH SVHC candidate list expansion dictates the pricing tier structure across European supply chains, separating pre-registered bio-based formulations from legacy chemistries facing compliance-driven cost surges. Three-tier pricing structure across premium resin, standard wax-resin, and economy monochrome levels reflects certification grade and volume scale differentiation. Pricing pressure stems from petroleum-derived substrate volatility that ribbon converters cannot fully pass through to spot-market corporate buyers. Education and retail loyalty segments exhibit highest price sensitivity, while German municipal credential programs and United States hospital networks accept premium positioning for ten-year archival validation.
Supply Chain Analysis
Just-in-time replenishment dominates healthcare and government procurement through managed consumables contracts, while strategic stockpiling persists among corporate buyers hedging against East Asian substrate disruption. Thermal transfer film manufacturing concentrates in China and South Korea, with Japan supplying specialized PET grades for sterilization-resistant applications. Ribbon finishing draws from polyester and PET substrates, resin binder chemistries, and wax carrier formulations. Single-source vulnerability in East Asian substrate supply creates structural risk for European and North American finishers lacking backward integration. Distribution runs through authorized dealer networks for enterprise accounts, with e-commerce channels capturing intermittent small-batch demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA UDI mandates and EU AI Act biometric provisions creates durable defensive moats for validated suppliers, as switching costs lock healthcare and government buyers into approved formulation ecosystems.
For Market Incumbents: Shield market position by accelerating REACH-compliant chemistry pre-registration to secure European public sector access, and deepen backward integration into PET substrate supply to offset East Asian concentration risk. Digital credential substitution in transit and retail loyalty applications threatens volume-tier revenue, making healthcare contract renewal rates the critical defensive lever. For New Entrants and Emerging Players: Differentiate on bio-based coating vehicle formulations to capture EU Green Deal procurement preferences, and target India's Aadhaar-linked welfare card expansion where BIS certification barriers remain navigable for regional finishers. Cloud-connected print management integration offers the most penetrable go-to-market angle for recurring revenue attachment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated hardware-ribbon bundlers serving United States healthcare networks through multi-year consumables agreements. Long-term viability favors suppliers with validated ten-year archival formulations and pre-registered REACH chemistries. Acquisition targets should demonstrate regional regulatory entrenchment rather than commodity scale. The signal to watch is cloud-connected print management adoption rates as an indicator of contract consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Chemistry Pre-Registration | ECHA scrutiny of phthalate plasticizers accelerates reformulation timelines for European market access. |
| Cloud-Connected Print Management Integration | United States healthcare systems consolidate purchasing authority through bundled hardware-ribbon-software contracts. |
| Bio-Based Coating Vehicle Development | EU Green Deal environmental purchasing criteria favor suppliers with early alternative chemistry validation. |
| India Market Certification Investment | BIS requirements for plastic card materials shape domestic ribbon finisher competitive positioning. |
| Re-Transfer Film Technology Expansion | Government agencies in France and Germany adopt dye-sublimation systems for edge-to-edge credential coverage. |
Methodological Framework
Desk research of thermal transfer consumables trade publications, ECHA regulatory filings, and FDA UDI guidance documents preceded structured interviews with ribbon formulation chemists, healthcare procurement managers, government credential program directors, and thermal printer hardware engineers. Primary fieldwork validated secondary assumptions around REACH compliance cost structures and hospital network contract renewal patterns. Bottom-up modeling of ribbon consumption per installed printer base triangulated against top-down market sizing from customs data and distributor channel audits.
Variance decomposition across product type, material grade, delivery mode, and end-user application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume forecasts incorporating printer installed base growth, average ribbon yield per card, and replacement cycle assumptions. Industry-specific inputs included FDA UDI mandate implementation timelines and EU AI Act biometric provision enforcement trajectories.
Material uncertainties — crude oil price volatility affecting PET substrate costs, digital credential substitution acceleration, and REACH SVHC list expansion timing — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement continuity and healthcare credential modernization program funding. Revision becomes warranted when mobile identity verification penetration in corporate badge applications crosses thresholds that compress hardware placement rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
GCC Digital Printing Market
Printing Technology
Large Format Printer Market
Printing Technology
Print on Demand Software Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Digital Graphic Printing Market
Printing Technology
Global Cloud Printing Services Market
Printing Technology
Professional Printers Market
Printing Technology
Barcode Printers and Consumables Market
Printing Technology
Card Printers Market
Printing Technology
Europe Commercial Printing Market
Printing Technology
Global Point of Sale (Pos) Receipt Printer Market
Printing Technology
Global Computer to Plate Printing System Market
Printing Technology
Inkjet Printhead Market
Printing Technology
Hardcopy Peripherals and Printing Consumables Market
Printing Technology
Print Equipment Market
Printing Technology
Roll to Roll Printing Market