
 Global Cloud Printing Services Market | 2026-2036
Global Cloud Printing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Printing Services Market Intelligence
Serverless architecture is rewriting how cloud printing infrastructure scales across enterprise networks. HP Inc. leverages its installed base of hardware endpoints to anchor hybrid deployment conversations with large organizations. Ricoh Company Ltd. specializes in managed print services that integrate with existing document workflows. Google LLC competes through deep API connectivity with productivity suites, extending its cloud-native footprint into print management.
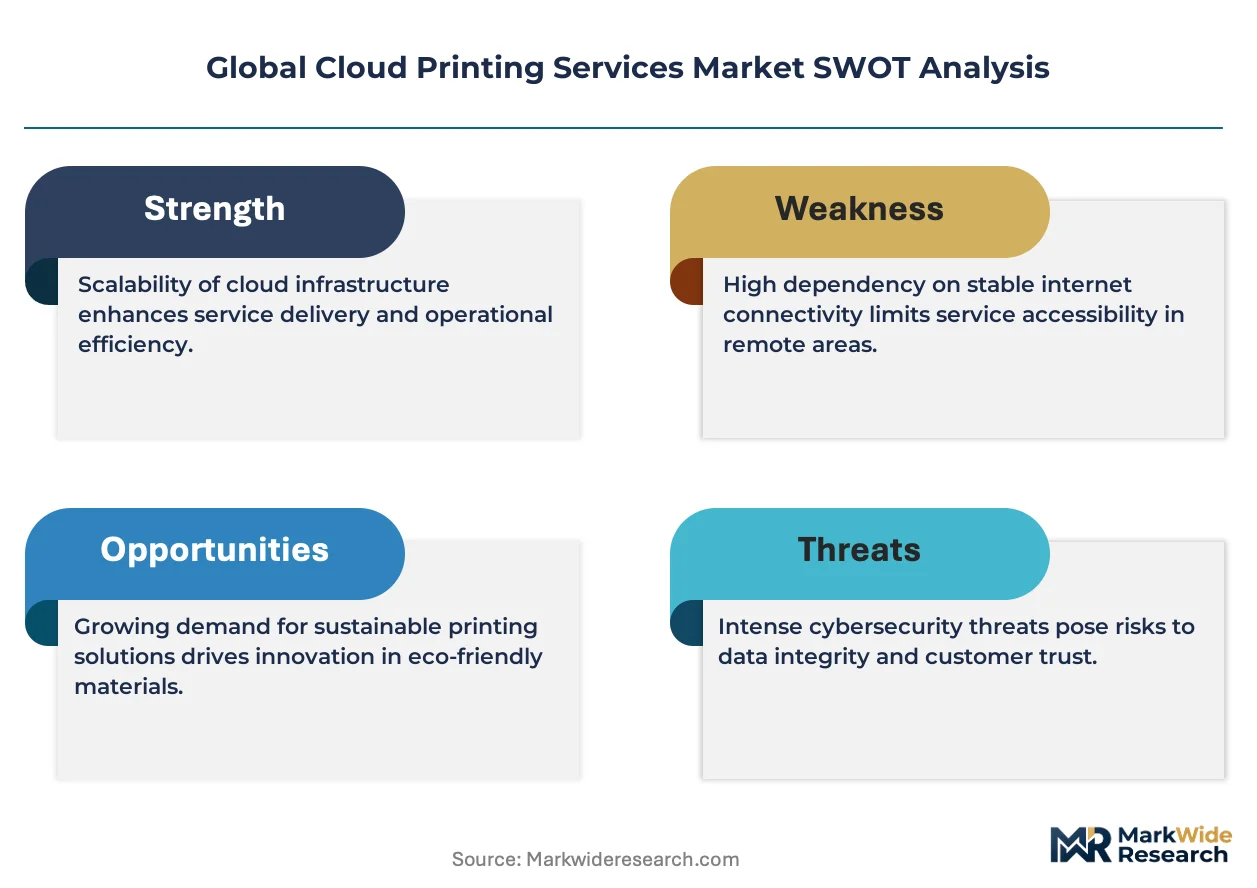
Cloud printing services deliver document output through internet-connected infrastructure that offloads print job processing, queue management, and device orchestration to remote data centers, typically supporting IPP Everywhere and universal print driver standards to eliminate local server dependencies. The primary commercial purpose is to reduce IT overhead while enabling centralized security policy enforcement across dispersed workforces. Managed print services and security compliance segments command the deepest margin pools because enterprises prioritize cost predictability and data protection over basic print functionality. Hybrid cloud deployments are gaining share fastest as organizations balance flexibility needs against regulatory constraints on data residency.
FDA cybersecurity guidance for networked medical devices indirectly shapes cloud printing requirements in healthcare settings by mandating encrypted transmission pathways. GDPR and the EU AI Act impose strict audit trails and automated decision-making disclosures that European cloud print vendors must embed. ISO 27001 certification has become a baseline market access requirement for providers serving financial services and legal firms. Stakeholders should monitor how zero-trust network architectures reshape authentication protocols for cloud-connected printers.
Market Dynamics
Serverless architecture is compressing deployment timelines for cloud printing infrastructure, forcing vendors to reconfigure service delivery models around API-first orchestration rather than hardware-centric provisioning.
Growth Catalysts
- GDPR audit mandates:European enterprises under the EU AI Act and GDPR must maintain immutable print logs, accelerating procurement of managed services with embedded compliance tooling.
- Healthcare digitization:FDA cybersecurity guidance for networked medical devices mandates encrypted transmission pathways, pulling hospital systems toward cloud-native print stacks.
- German industrial clustering:Data localization requirements and private cloud preferences in Germany's manufacturing corridors are concentrating demand for sovereign-hosted print infrastructure.
Market Restraints
- Input cost volatility:Specialized secure print hardware components face supply concentration in East Asian foundries, exposing margins to logistics disruption.
- Technical fragmentation:Legacy on-premise print servers persist in financial services due to ISO 27001 certification transfer complexity, slowing cloud migration velocity.
- Substitution pressure:Digital document workflows and e-signature platforms are compressing page volumes in professional services, capping addressable market expansion.
Strategic Opportunities
- India's PLI scheme:Electronics manufacturing incentives are attracting print hardware assembly, creating localized cloud print node deployment potential.
- Zero-trust convergence:Integration of zero-trust network architectures with print authentication protocols opens new security-service revenue layers.
- Japan's METI standards:Emerging smart factory guidelines are mandating connected device governance, positioning cloud print as industrial IoT infrastructure.
Industry Challenges
- Skill scarcity in DevSecOps:Cloud print vendors struggle to hire engineers capable of embedding security-by-design into serverless orchestration layers.
- Certification timeline compression:ISO 27001 and SOC 2 audit cycles for multi-tenant platforms now exceed eighteen months, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Printing Services Market |
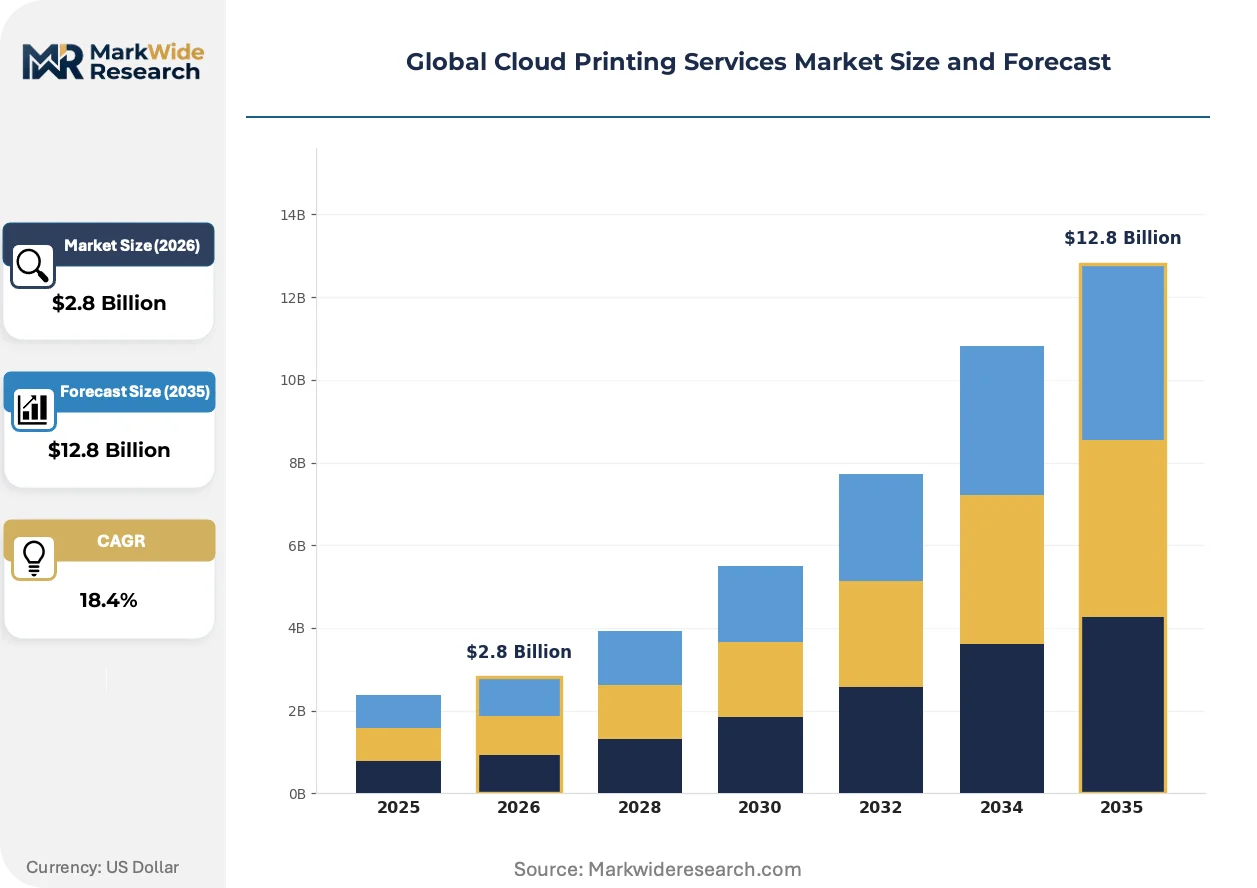
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $12.8 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Print Services, Document Management, Security & Compliance, Mobile Printing, Remote Printing Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User Industry: Information Technology, Education Institutions, Media Agencies, Legal Firms, Financial Services Pricing Model: Subscription-Based, Pay-As-You-Go, Tiered Pricing, Freemium, Per-Page Pricing |
| Companies Covered | HP Inc., Ricoh Company Ltd., Google LLC, PaperCut Software Pty Ltd, Canon Inc., Microsoft Corporation, Xerox Corporation, ezeep GmbH, Amazon Web Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Printing Services Market Strategic Shifts & Innovations
Competitive advantage in cloud printing is migrating from hardware scale to software-defined orchestration, with vendors racing to embed compliance automation and zero-trust authentication into API layers.
Edge-to-cloud print processing is hybridizing workload distribution across distributed manufacturing sites and centralized data centers. Automotive suppliers in Germany's Baden-Württemberg cluster are deploying this architecture to maintain local queue management while offloading analytics to sovereign cloud instances. This topology is compressing latency for time-sensitive production documentation while preserving GDPR-compliant data residency.
The EU AI Act's automated decision-making disclosure requirements are forcing print management platforms to expose algorithmic routing logic. European financial institutions must now document how cloud systems prioritize print jobs across shared device pools. Vendors serving this segment are rebuilding dashboards to satisfy CNIL audit expectations in France and BfDI scrutiny in Germany.
Enterprise buyers are consolidating vendor relationships around integrated document-to-print workflows rather than standalone print management. Legal and accounting firms in the United States are displacing point solutions with platforms that unify e-signature, document storage, and secure output. This bundling is visible most acutely in the professional services vertical, where procurement teams favor predictable per-seat pricing over transactional page-based models.
Global Cloud Printing Services Market Segmentation
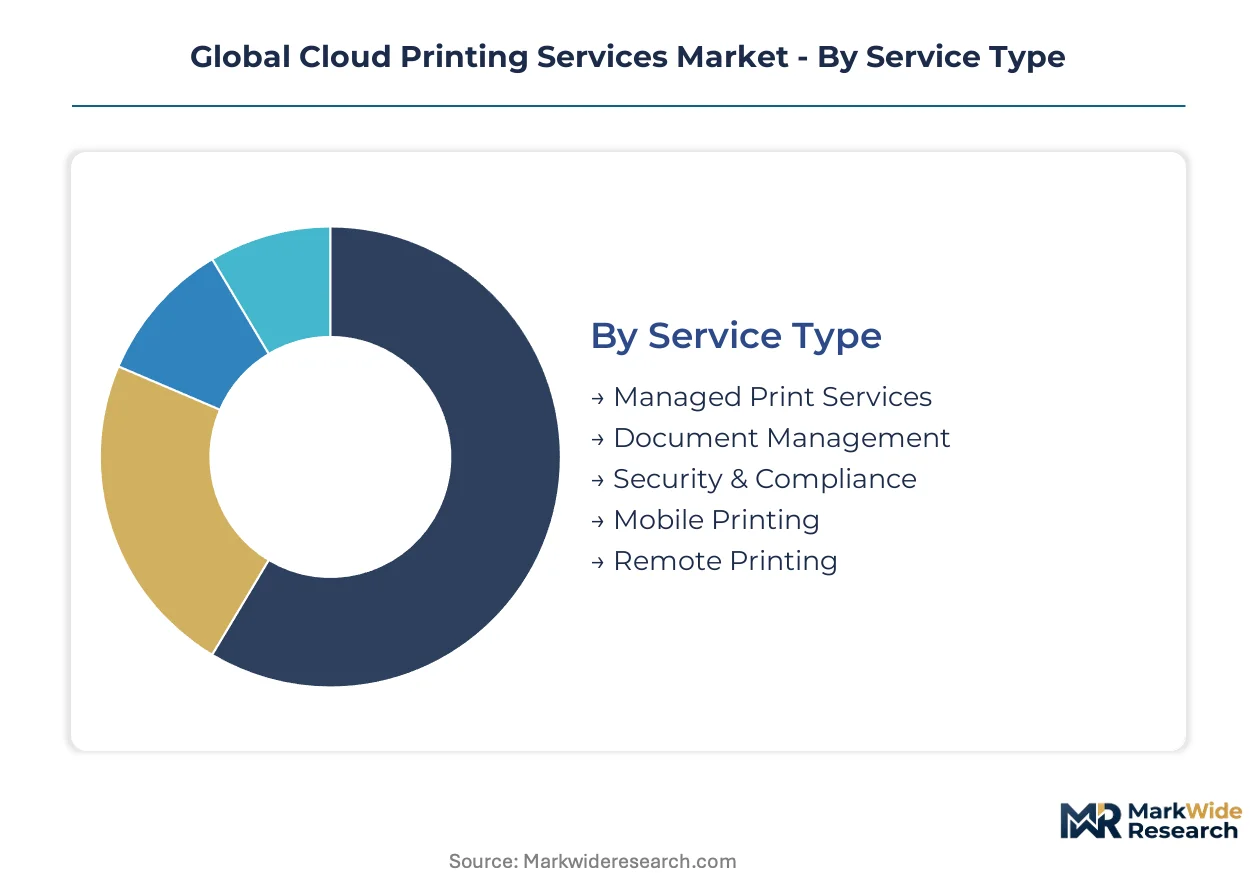
Cloud printing services fragment across service architecture, infrastructure tenancy, vertical application, and commercial terms. Each segmentation axis reveals distinct margin structures and procurement cycles that vendors must navigate to capture enterprise spend.
Service Type:
Refresh cycles vary dramatically across service types, with mobile and remote printing turning over fastest as endpoint diversity accelerates, while managed print services lock in multi-year enterprise commitments.
- Managed Print Services:Comprehensive outsourcing of print fleet operations including device provisioning, consumables management, and helpdesk support under fixed-fee contracts. Demand concentrates in Germany's automotive clusters where BfDI audit requirements favor predictable cost structures with embedded compliance tooling.
- Security & Compliance:Embedded governance layers providing encrypted job routing, immutable audit logs, and automated policy enforcement. Financial services in France prioritize this segment under CNIL scrutiny, with GDPR Article 30 documentation requirements driving procurement decisions.
- Document Management:Cloud-native repositories integrating capture, workflow, and archival with print orchestration.
- Mobile Printing:Smartphone and tablet-native job submission with proximity-based device discovery.
- Remote Printing:Home office and satellite location support with VPN-tunneled queue management.
Managed Print Services anchors the volume base while Security & Compliance gains share at the steepest rate.
Deployment:
Cost tiers separate this category, with public cloud offering lowest entry pricing and private cloud commanding premium positioning for regulated workloads.
- Hybrid Cloud:Split workload architecture maintaining local spooling for latency-sensitive jobs while offloading analytics and compliance logging to sovereign cloud instances. Germany's Baden-Württemberg manufacturing corridor deploys this topology extensively to satisfy GDPR data residency without sacrificing centralized visibility.
- Private Cloud:Single-tenant infrastructure with dedicated compute and storage resources. Japanese automotive suppliers under METI smart factory guidelines favor this model for industrial IoT integration with print governance.
- Public Cloud:Multi-tenant shared infrastructure with elastic scaling and lowest capital requirements.
- Community Cloud:Collaborative tenancy serving consortia with common compliance profiles, such as EU research institutions under CSRD disclosure mandates.
Public Cloud captures the highest transaction volume while Hybrid Cloud expands most quickly as sovereignty requirements harden.
End User Industry:
Application maturity diverges sharply, with Financial Services and Legal Firms operating the most sophisticated procurement while Education Institutions lag in cloud migration velocity.
- Financial Services:Institutions requiring SOC 2 Type II and ISO 27001 certified platforms with real-time fraud detection on document output. French banking groups under ECB supervision mandate immutable print logs for trading floor documentation.
- Legal Firms:Practices demanding attorney-client privilege protection with encrypted transmission and witness-tamper-evident output tracking. UK Magic Circle firms drive demand for client-matter code integration with billing systems.
- Information Technology:Technology vendors with DevSecOps-native procurement evaluating API-first orchestration capabilities.
- Education Institutions:Universities and K-12 districts prioritizing cost containment over advanced security features.
- Media Agencies:Creative shops requiring color-accurate proofing with rapid turnaround and client portal integration.
Financial Services commands the deepest pricing premiums while Information Technology shows the steepest adoption trajectory.
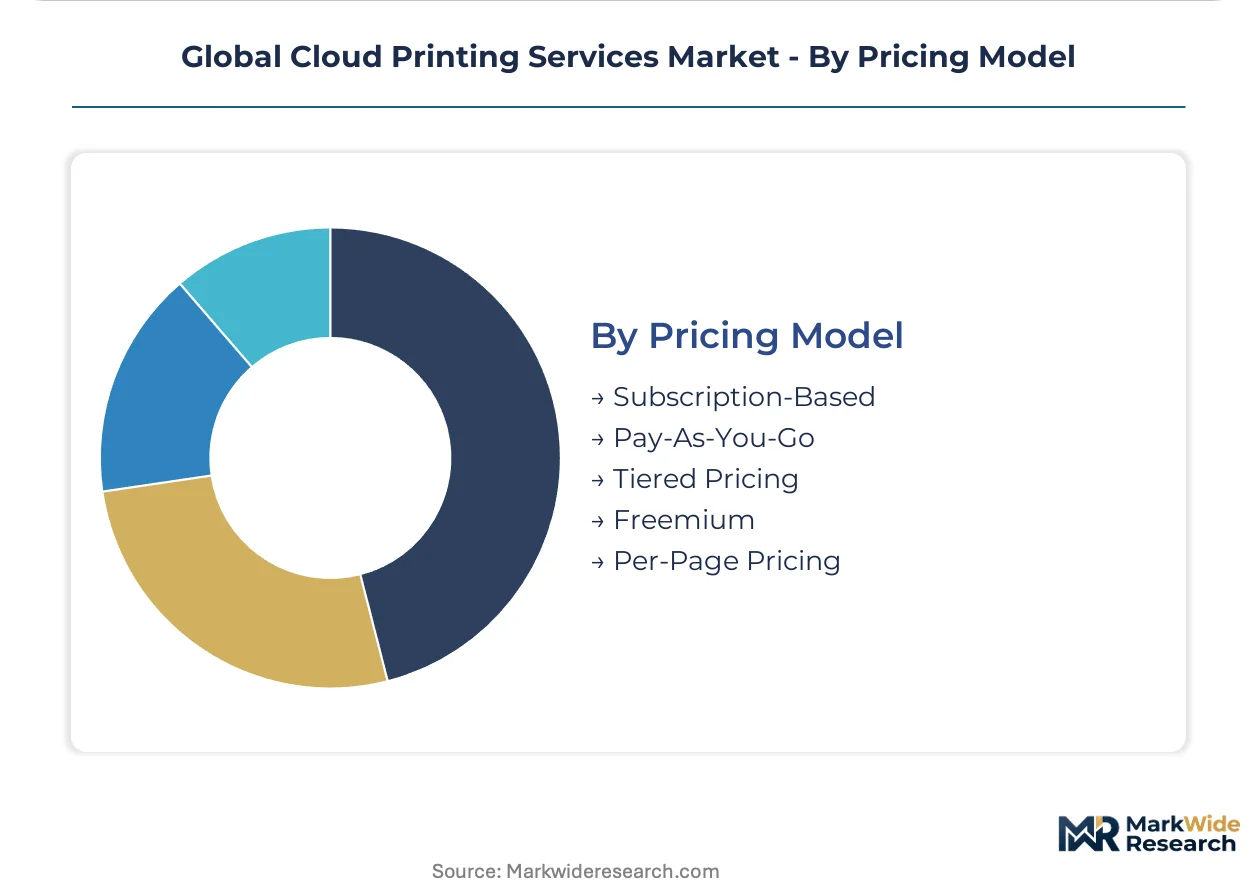
Pricing Model:
Customer type stratification dominates, with enterprise procurement teams favoring predictability and mid-market buyers accepting variable consumption exposure.
- Subscription-Based:Fixed monthly or annual fees covering unlimited or capped volume with full service bundling. German industrial Mittelstand prefers this structure for budget certainty under tight working capital constraints.
- Per-Page Pricing:Pure consumption metering with tiered rates declining at volume breakpoints. US legal and accounting partnerships historically favored this model though consolidation pressures are shifting preferences.
- Pay-As-You-Go:Pure variable pricing with no commitment minimums.
- Tiered Pricing:Feature-gated packages separating basic queue management from advanced security and analytics modules.
- Freemium:Entry-level offerings with volume or capability limits designed to convert to paid tiers.
Per-Page Pricing retains the largest installed base while Subscription-Based models climb the fastest as finance teams prioritize OpEx predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cloud print infrastructure exports to European automotive and financial services buyers anchor the trade corridor, with compliance-heavy procurement patterns diffusing from Baden-Württemberg manufacturing clusters to adjacent markets.
United States
Hospital systems and legal partnerships drive cloud print procurement under FDA cybersecurity guidance for networked medical devices and state-level data breach notification laws. Financial institutions in New York and Chicago mandate SOC 2 Type II certification for document output platforms. The Southeast technology corridor around Atlanta concentrates managed print service deployments for healthcare networks.
Germany
Automotive suppliers and Mittelstand manufacturers prioritize sovereign-hosted print infrastructure under BfDI audit requirements and GDPR data localization rules. The EU AI Act mandates automated decision-making disclosures for print job routing algorithms. Baden-Württemberg industrial clusters deploy hybrid cloud topologies to preserve local queue management while centralizing compliance logging.
Japan
Automotive and electronics manufacturers adopt cloud-native print stacks under METI smart factory guidelines mandating connected device governance. ISO 27001 certification serves as baseline market access for financial services procurement. The Nagoya industrial corridor concentrates private cloud deployments for industrial IoT integration with print orchestration.
India
IT services firms and banking groups accelerate cloud print adoption under RBI data localization circulars and the PLI scheme for electronics manufacturing. Domestic hardware assembly creates localized cloud print node deployment potential. Bengaluru and Hyderabad technology clusters concentrate demand for API-first orchestration platforms serving global delivery centers.
France
Banking groups under ECB supervision and CNIL scrutiny mandate immutable print logs for trading floor documentation and GDPR Article 30 compliance tooling. Legal practices require attorney-client privilege protection with encrypted transmission pathways. Paris financial services clusters drive premium pricing for security-embedded managed print services.
Global Cloud Printing Services Market Key Industry Players
On the supply side, the industry is consolidating around three strategic archetypes: legacy hardware vendors pivoting to subscription software models, cloud-native platforms competing through API connectivity, and managed service specialists embedding compliance automation. Competitive positioning hardens through M&A activity targeting regional service capabilities and strategic partnerships integrating zero-trust authentication protocols.
Within the legacy hardware pivot tier, HP Inc. and Ricoh Company Ltd. occupy positions anchored by installed base scale, while Google LLC exemplifies the cloud-native API-first archetype. These three entities represent the dominant competitive vectors: hardware-anchored hybrid deployment conversations, managed print service workflow integration, and productivity suite connectivity extension.
| Leading Market Players |
|---|
| HP Inc. |
| Ricoh Company Ltd. |
| Google LLC |
| PaperCut Software Pty Ltd |
| Canon Inc. |
| Microsoft Corporation |
| Xerox Corporation |
| ezeep GmbH |
| Amazon Web Services Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in East Asian secure print component foundries is compressing supplier pricing power while forcing cloud print vendors toward longer-term contract structures that lock in margin predictability against input volatility.
Pricing Analysis
Current-generation serverless orchestration platforms command subscription premiums against prior-generation hardware-centric managed print services, while next-generation zero-trust-embedded offerings remain in pilot pricing. Three-tier pricing structure across premium, standard, and economy levels separates SOC 2 Type II certified deployments from ISO 27001 baseline and uncertified entry tiers. Price differentiation rests on certification grade and geographic delivery cost, with German sovereign-hosted instances carrying substantial premiums over public cloud alternatives. Pricing pressure stems from digital document substitution in professional services, with legal and accounting partnerships exhibiting highest price sensitivity as page volumes compress.
Supply Chain Analysis
Upstream feedstock for specialized secure print hardware draws from semiconductor fabrication concentrated in Taiwan, South Korea, and Japan, with final assembly migrating toward India under PLI scheme incentives. Component dependencies span encryption chipsets, tamper-evident output mechanisms, and universal print driver firmware. Single-source vulnerability around advanced cryptographic processors creates exposure to export control restrictions. Distribution runs through direct enterprise sales teams for large accounts and managed service provider channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as compliance automation requirements splinter demand across vertical-specific configurations, with GDPR Article 30 documentation, FDA cybersecurity guidance, and METI smart factory standards creating incompatible procurement specifications.
For Market Incumbents: Harden competitive moats through backward integration into encryption chipset supply and certification investment in multi-tenant SOC 2 Type II platforms, defending against API-first entrants displacing hardware-anchored relationships in financial services procurement. For New Entrants and Emerging Players: Pursue white-space in India's domestic cloud print node deployment, where PLI scheme hardware assembly and RBI data localization circulars create localized infrastructure demand underserved by global platforms; angle through DevSecOps-native API orchestration for IT services firms. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed print service providers with embedded compliance tooling and multi-year German automotive contracts; long-term viability favors platforms with zero-trust authentication integration and sovereign cloud deployment capabilities; monitor BfDI audit enforcement intensity as inflection signal for European premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Authentication Integration | Positions vendors for BfDI and CNIL scrutiny in European financial services procurement. |
| Sovereign Cloud Deployment | Captures German automotive Mittelstand demand under GDPR data localization mandates. |
| API-First Orchestration Platform | Addresses DevSecOps-native evaluation criteria emerging in technology sector procurement. |
| Compliance Automation Embedding | Automates EU AI Act algorithmic disclosure and immutable audit log generation. |
| Regional Hardware Assembly | Leverages India's PLI scheme for localized cloud print node cost positioning. |
Research Approach
Initial hypotheses were tested against primary input from cloud infrastructure architects, enterprise procurement officers, managed print service operations directors, and DevSecOps engineers and refined through secondary validation against SEC filings of publicly traded hardware vendors, hyperscaler partnership announcements, EU regulatory implementation guidance, and hospital system RFP documentation. Bottom-up triangulation across vendor revenue disclosures and top-down cross-check against IT services spending patterns anchored market sizing.
Demand-supply-balance framing across the analysis window modeled deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from weighted scenario analysis incorporating compliance timeline acceleration, digital substitution elasticity, and sovereign cloud preference shifts. Industry-specific forecast inputs included FDA cybersecurity guidance implementation pace and EU AI Act enforcement intensity calibration.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT capital expenditure cycles and cross-border data flow restriction severity would shift the trajectory. Forecasts reflect documented assumptions around certification timeline compression and supply chain regionalization momentum. Cross-checking against hyperscaler print management partnership announcements and hospital system procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Technology
Photo Printing Market
Printing Technology
Digital Fabric Printer Market
Printing Technology
Large Format Printer Market
Printing Technology
North America Commercial Printing Market
Printing Technology
Global Microprinting Market
Printing Technology
Book Printing Service Market
Printing Technology
Commercial Printing Outsourcing Market
Printing Technology
Digital Franking Machine Market
Printing Technology
Industrial Inkjet Printer Market
Printing Technology
GCC Digital Printing Market
Printing Technology
Global Digital Printing Services Market
Printing Technology
Card Printer Ribbons Market
Printing Technology
Digital Paper System Market
Printing Technology
Dye-Sublimation Printing Machines Market
Printing Technology
US Print on Demand Market
Printing Technology
Oceania Digital Textile Printer Market