
 North America Family Floater Health Insurance Market | 2026-2036
North America Family Floater Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
North America Family Floater Health Insurance Market Analytics
Canadian provincial health authority contracting is realigning how insurers structure cross-border family floater products. UnitedHealth Group leverages its integrated Optum care delivery network to sustain competitive positioning in employer-sponsored family segments. Elevance Health anchors its growth through state-level Medicaid expansion partnerships that feed into commercial family plan conversions. CVS Group competes on pharmacy-benefit integration, embedding medication cost controls within family floater designs.
North America family floater health insurance constitutes a single-policy mechanism covering multiple family members under one sum insured, typically with shared deductible structures and dependent age limits extending to 26 years under US federal rules. The product pools risk across household units, reducing per-member administrative overhead while enabling portability between employer-sponsored and individual market channels. Family floater plans dominate the product type landscape, with comprehensive coverage tiers capturing the majority of premium volume due to ACA minimum essential coverage requirements. Low-to-moderate premium segments serve price-sensitive exchange enrollees, while high premium tiers concentrate among self-insured employer populations seeking out-of-network flexibility.
US Department of Health and Human Services oversight, state insurance commissioner rate review authority, and Canada's provincial health ministry coordination frameworks collectively determine product availability, pricing bands, and mandated benefit floors across the region. These regulatory layers shape insurer capital reserve requirements and restrict medical loss ratio flexibility, compressing margin pools for administrative functions. Stakeholders must monitor state waiver activity under Section 1332 of the ACA and provincial pharmacare expansion timelines to anticipate coverage overlap and displacement risks in family plan portfolios.
Market Dynamics
Employer-sponsored group coverage adoption among mid-sized businesses is compressing individual market enrollment channels while reshaping insurer distribution priorities across the United States and Canada.
Growth Catalysts
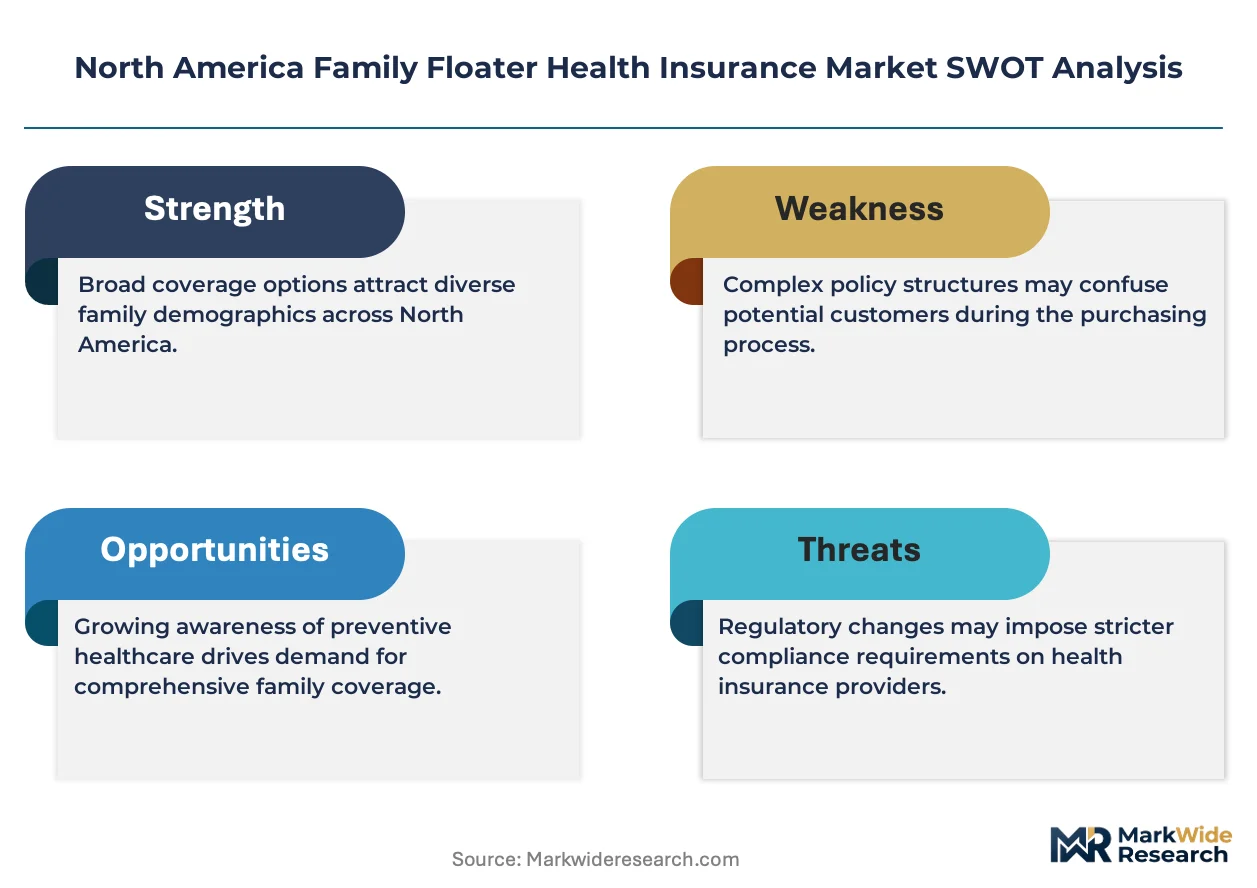
- Medicaid Expansion Partnerships:State-level Medicaid expansion under the Affordable Care Act creates conversion pathways into commercial family floater products. Insurers leverage these pipelines to migrate beneficiaries into higher-margin employer-sponsored tiers.
- Essential Health Benefits Mandate:The ACA's mandatory coverage floor standardizes comprehensive benefit designs, reducing product development friction and accelerating plan portability between exchange and employer channels.
- Metropolitan Corridor Concentration:Texas and Florida urban clusters generate dense employer populations that sustain group policy volume and enable risk-pooling efficiency for family floater structures.
Market Restraints
- Medical Loss Ratio Floors:The ACA's 80-85% medical loss ratio requirement caps administrative margin flexibility and compresses operating reserves for product innovation.
- Provincial Coordination Friction:Canadian provincial health ministry contracting creates cross-border product fragmentation, forcing insurers to maintain parallel policy architectures for US and Canadian households.
- Actuarial Risk Concentration:Family floater structures pool multi-member household risk into single sum-insured units, amplifying catastrophic claim exposure and reinsurance dependency.
Strategic Opportunities
- Pharmacy-Benefit Integration:Embedding medication cost controls within family floater designs creates differentiation through point-of-care spend management and chronic condition adherence programs.
- Section 1332 State Waivers:ACA waiver activity enables customized benefit designs and alternative subsidy structures that can unlock underpenetrated rural employer segments.
- Dependent Age Extension:Federal rules permitting coverage to age 26 capture young adult populations in family policies, delaying individual market migration and extending premium collection windows.
Industry Challenges
- Legacy System Interoperability:Insurers face integration friction when connecting modern family floater administration platforms to entrenched employer HRIS and payroll systems.
- Rate Review Timeline Compression:State insurance commissioner prior-approval processes create pricing uncertainty windows that complicate annual renewal negotiations with employer groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Family Floater Health Insurance Market |
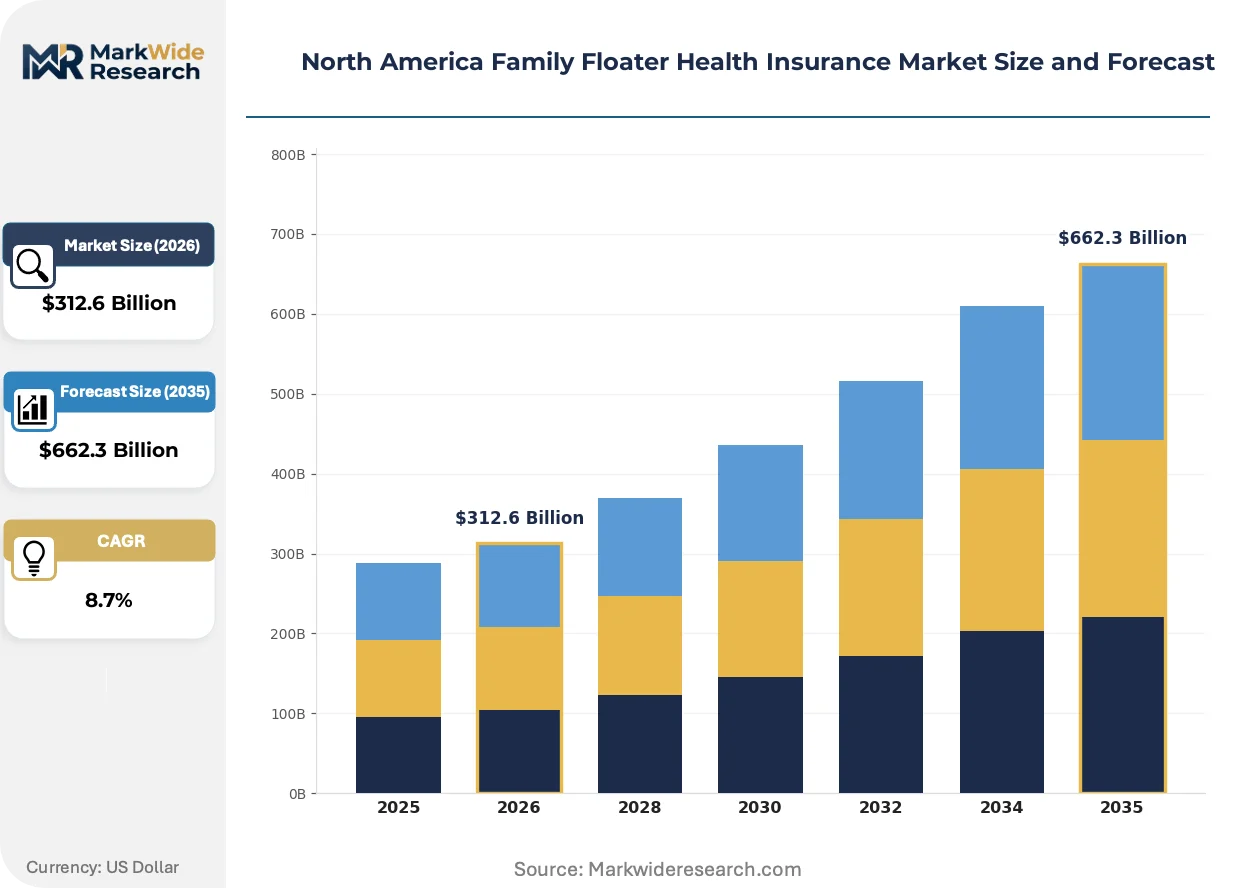
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Individual Plans, Family Floater Plans, Critical Illness Plans, Top-up Plans Coverage Type: Comprehensive Coverage, Basic Coverage, Preventive Care, In-patient Care Premium Range: Low Premium, Moderate Premium, High Premium, Ultra High Premium End User: Families, Couples, Individuals, Seniors |
| Companies Covered | UnitedHealth Group, Elevance Health, CVS Group, Centene Corp, Humana Group, Kaiser Permanente, Health Care Service Corp, Cigna Health, GuideWell, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Family Floater Health Insurance Market Evolving Landscape
Digital health infrastructure and regulatory flexibility mechanisms are restructuring how family floater products are administered, priced, and distributed across North American markets.
Telehealth platforms are decentralizing primary care access for family floater enrollees, enabling virtual-first consultation models that reduce per-episode costs. Mid-sized employers in Texas and Florida metropolitan corridors are adopting these platforms at accelerated pace to manage dependent utilization. This technology is decentralizing traditional brick-and-mortar network dependencies and compressing geographic access disparities between urban and rural household members.
The Affordable Care Act's Section 1332 waiver framework is permitting state-specific benefit substitutions and alternative subsidy mechanisms. This regulatory flexibility enables customized family floater designs that diverge from federal essential health benefit templates. Texas and Florida are actively exploring waiver submissions that would reshape plan affordability calculations for household units.
Households are consolidating coverage decisions through employer-sponsored enrollment portals rather than individual exchange navigation. This behavioral shift concentrates family floater procurement authority with HR benefit administrators and displaces direct-to-consumer exchange selection. The pattern is most visible among dual-income households in suburban Texas corridors where employer plan matching dominates household coverage strategy.
North America Family Floater Health Insurance Market Segmentation
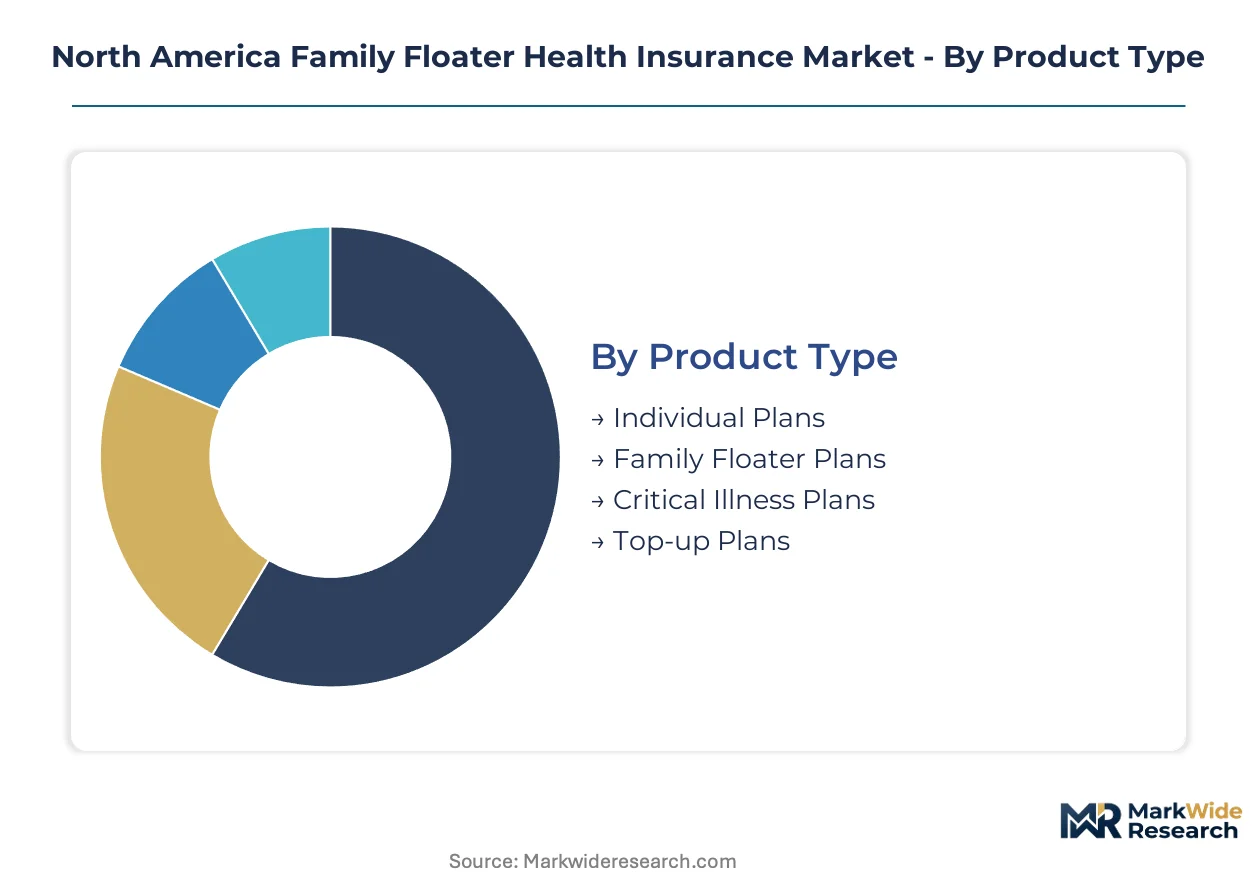
Family floater health insurance products demand precise segmentation to align household risk profiles with appropriate coverage structures. Insurers calibrate benefit tiers, premium bands, and eligibility rules across multiple dimensions to match heterogeneous family compositions and employer-sponsored versus individual market channels.
Product Type:
Customization intensity varies sharply across this category, with standardized group offerings at one pole and individually underwritten products at the other.
- Family Floater Plans:A single sum-insured pool covers multiple household members under one policy with shared deductible structures. Texas and Florida metropolitan employers drive group enrollment volume due to dense dependent populations and ACA portability requirements.
- Individual Plans:Separate policies for each household member with independent deductibles and benefit limits. Exchange marketplaces concentrate demand among households with non-traditional family structures ineligible for employer group pricing.
- Critical Illness Plans:Lump-sum payouts upon diagnosis of specified conditions complement base medical coverage.
- Top-up Plans:Supplementary coverage activates after base policy thresholds exhaust, targeting high-deductible plan enrollees.
Most installed capacity flows through Family Floater Plans. Expansion is steepest in Critical Illness Plans as employers seek defined-benefit cost containment tools.
Coverage Type:
Premium differentiation tracks directly against the breadth of services included, with narrow networks commanding lower price points.
- Comprehensive Coverage:Essential health benefits mandate compliance including hospitalization, prescription drugs, maternity, and mental health services. ACA exchange enrollment and self-insured employer populations in Florida sustain demand concentration.
- Basic Coverage:Catastrophic protection with high deductibles and limited provider networks. Young adult dependents through age 26 anchor uptake in Texas exchange corridors where premium sensitivity peaks.
- Preventive Care:Zero-cost screenings and wellness visits mandated by federal rules.
- In-patient Care:Hospital admission and surgical procedure coverage without outpatient extension.
Comprehensive Coverage commands the majority of premium volume. Preventive Care is gaining share fastest as value-based contracting incentives reshape plan design priorities.
Premium Range:
Household income stratification and employer contribution levels segment this category into distinct procurement pools.
- High Premium:Low deductibles, broad network access, and out-of-network flexibility characterize this tier. Self-insured employers in Texas metropolitan clusters sustain enrollment through generous contribution structures.
- Moderate Premium:Balanced cost-sharing with tiered network incentives targets dual-income suburban households. Florida exchange silver plans concentrate demand here due to cost-sharing reduction eligibility thresholds.
- Low Premium:Bronze-tier exchange products with catastrophic protection focus.
- Ultra High Premium:Concierge access and international coverage options serve executive populations.
Moderate Premium products carry the largest enrollment base. High Premium tier expansion is accelerating as employers restore pre-ACA benefit generosity to attract talent.
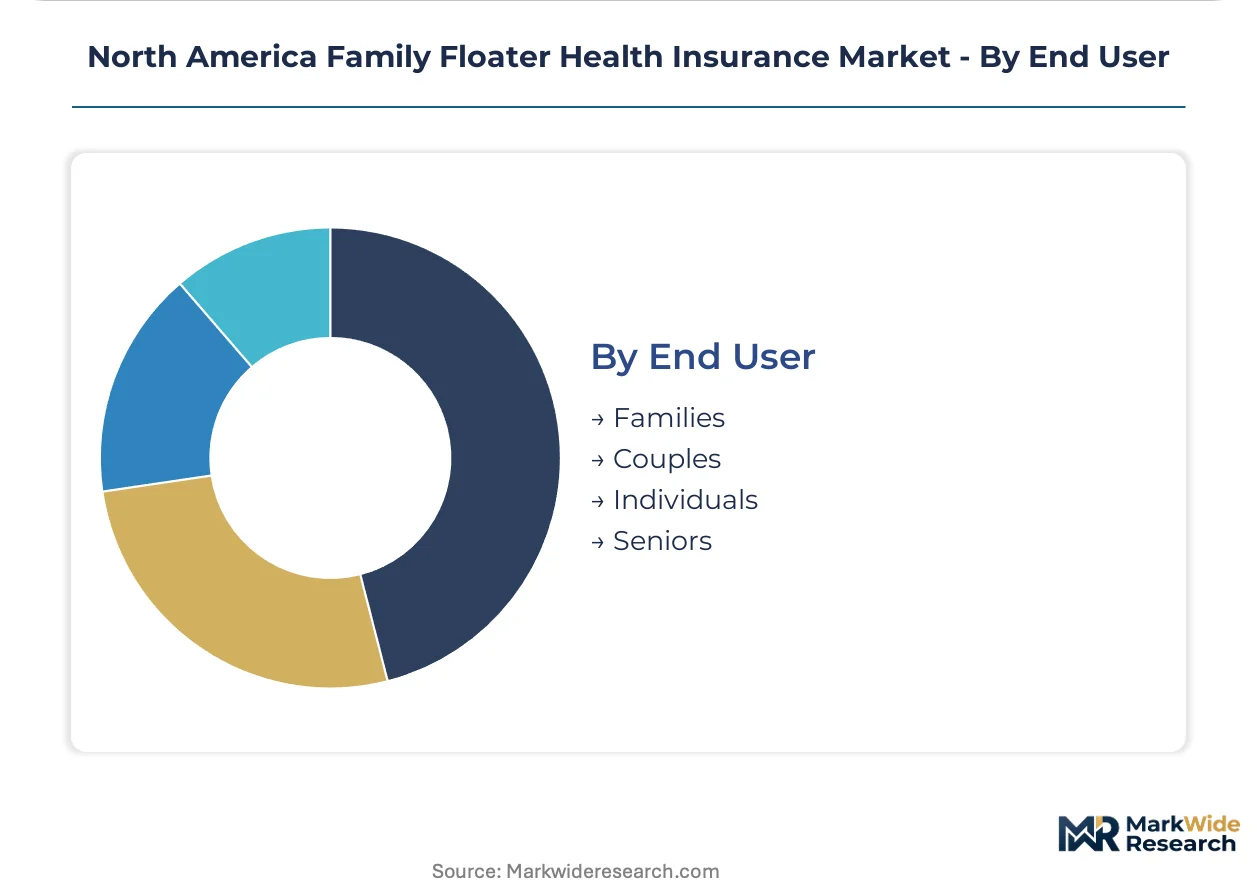
End User:
Household lifecycle stage and composition structure eligibility rules and benefit utilization patterns.
- Families:Multi-generational or multi-dependent households leverage floater structures to pool risk across three or more members. ACA dependent coverage to age 26 extends premium collection windows for this segment in Texas and Florida employer markets.
- Couples:Two-adult households without dependent children optimize for lower premiums than family-tier pricing. Empty-nester migration into this category is reshaping product development priorities.
- Individuals:Single-person coverage outside floater structures.
- Seniors:Medicare-eligible populations seeking supplemental gap coverage.
Families represent the dominant enrollment category. Couples is expanding most quickly as delayed childbearing and dual-income household formation reshape demographic composition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates premium volume through employer-sponsored channels, while Canada structures family coverage around provincial health authority coordination frameworks. Mexico anchors regional expansion through private insurance penetration in urban corridors. Each jurisdiction deploys distinct regulatory architectures that reshape product design and distribution economics.
United States
Texas and Florida metropolitan clusters generate dense employer populations that sustain group policy volume for family floater structures. The Affordable Care Act's essential health benefits mandate and HIPAA privacy rules standardize coverage floors while restricting medical loss ratio flexibility. Houston and Miami corridors see accelerated adoption of telehealth-integrated family plans among mid-sized businesses seeking dependent utilization management.
Canada
Provincial health ministry contracting realigns how insurers structure cross-border family floater products for households with US employment ties. Health Canada and provincial authorities coordinate pharmacare expansion timelines that create coverage overlap risks with private supplemental plans. Ontario and British Columbia concentrate enrollment through employer-sponsored supplementary coverage layered atop provincial single-payer foundations.
Mexico
Private insurance penetration in Mexico City and Monterrey metropolitan areas drives demand for family floater products among dual-nationality households and US subsidiary employees. The national health regulator and social security institute shape parallel public-private coverage architectures. Guadalajara corridor employers increasingly adopt floater structures to attract talent from US operations requiring portable dependent coverage.
North America Family Floater Health Insurance Market Competitive Landscape
United States insurers anchor the premium-tier segment; Canadian specialists hold supplementary coverage niches. The market structure concentrates around integrated health systems, pharmacy-benefit managers, and Medicaid-focused conversion platforms. Three archetypes dominate: vertically integrated care delivery networks, pharmacy-embedded cost controllers, and state-level Medicaid expansion partners. Competitive moves center on pharmacy-benefit integration and telehealth platform deployment.
Within the integrated network tier, UnitedHealth Group exemplifies care delivery consolidation through its Optum infrastructure. Elevance Health occupies a position as a Medicaid-to-commercial conversion specialist leveraging state expansion partnerships. CVS Group anchors pharmacy-benefit integration archetypes, embedding medication cost controls within family floater designs. These three represent distinct strategic postures rather than comparable scale positions.
| Leading Market Players |
|---|
| UnitedHealth Group |
| Elevance Health |
| CVS Group |
| Centene Corp |
| Humana Group |
| Kaiser Permanente |
| Health Care Service Corp |
| Cigna Health |
| GuideWell |
| Others |
Value Network & Pricing Analysis
High-premium employer-sponsored tiers and exchange-market bronze plans diverge sharply in both cost structure and sourcing configuration across North America. Texas and Florida metropolitan employers negotiate direct contracts with integrated delivery networks, while individual exchange enrollees in the same corridors face narrow-network constraints and prior-authorization bottlenecks that compress effective access.
Pricing Analysis
Broker commissions and administrative load fees absorb 15-20% of premium flows before medical claims payment. Three-tier pricing structure across premium, standard, and economy levels tracks employer contribution generosity and network breadth. Cost compression in bronze-tier exchange products intensifies as state regulators tighten rate review timelines. Price-sensitive individual exchange enrollees in Florida silver plans drive volume, while self-insured Texas employers show lowest sensitivity to premium increases.
Supply Chain Analysis
Domestic-content mandates under the ACA's medical loss ratio requirements reshape how insurers source care delivery and pharmacy benefits within US borders. Claims processing infrastructure concentrates in the United States, Canada, and India through third-party administrator networks. Cloud-based enrollment platforms, telehealth vendor contracts, and pharmacy-benefit manager agreements constitute critical dependencies. Single-source vulnerability in specialty pharmacy distribution runs through consolidated PBM networks. Distribution runs through employer HRIS portals, broker intermediaries, and direct exchange enrollment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in family floater products rests on pharmacy-cost containment and Medicaid-to-commercial conversion pipelines. Administrative expense reduction through digital enrollment infrastructure offers parallel leverage.
For Market Incumbents: Anticipate state-level Medicaid expansion shifts that could disrupt conversion funnel economics. Consolidate pharmacy-benefit integration depth to defend against PBM disintermediation. Elevance Health's state partnership model offers a template for locking in conversion pathways before competitors replicate the architecture. For New Entrants and Emerging Players: Employer benefits technology platforms represent the most penetrable channel for bypassing established broker networks. Mid-sized Texas businesses with 50-200 employees show coverage gaps in telehealth-integrated family plans. A direct-to-employer SaaS enrollment layer with embedded decision support captures procurement authority from legacy broker relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where state Medicaid contracts concentrate enrollment volume among three or fewer carriers. Long-term viability favors platforms with integrated care delivery assets or captive pharmacy infrastructure. Watch for Section 1332 waiver approvals in Texas and Florida as signals of regulatory arbitrage opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy-Benefit Integration | CVS Group's embedded medication cost controls reduce per-member per-month spend for chronic conditions. |
| Telehealth Platform Deployment | UnitedHealth Group's Optum virtual-first models compress primary care episode costs in Texas corridors. |
| Medicaid Expansion Partnership | Elevance Health's state-level contracts feed beneficiary conversion into commercial family tiers. |
| State Waiver Customization | Section 1332 submissions in Florida enable alternative subsidy structures for rural employer segments. |
| Dependent Age Extension Capture | Federal rules to age 26 delay individual market migration and extend premium collection windows. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged health plan actuaries, employer benefits directors, state insurance commissioner staff, and pharmacy-benefit manager contracting leads. Secondary validation drew from CMS Medicare data, state rate filing submissions, GPO contracts, and employer-sponsored insurance enrollment disclosures. Bottom-up policy-level modeling and top-down premium pool estimates triangulated to constrain forecast variance.
Comparable historical periods anchored the projection horizon against ACA implementation trajectories and Medicaid expansion wave timing. Segmentation dimensions spanned product type, coverage tier, premium band, household composition, and state regulatory cluster. CAGRs derived from fitted growth curves applied to enrollment and premium rate trajectories. Medical loss ratio floors and state waiver activity timelines served as industry-specific forecast inputs.
Revisions become necessary when federal essential health benefit mandates shift, state Medicaid expansion timelines accelerate, or provincial pharmacare expansion in Canada displaces private supplemental coverage. Forecasts reflect assumptions about employer contribution stability and regulatory enforcement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific Insurance Aggregators Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Insurance Aggregators Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
United States Bancassurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Marine Freight Insurance Market
Insurance
Boiler Insurance Market
Insurance
Green Insurance Market
Insurance
Umbrella Insurance Market
Insurance
Peru Insurance Market
Insurance
Title Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Europe Mobile Phone Insurance Market