
 Global Home Insurance Market | 2026-2036
Global Home Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Insurance Market Analysis
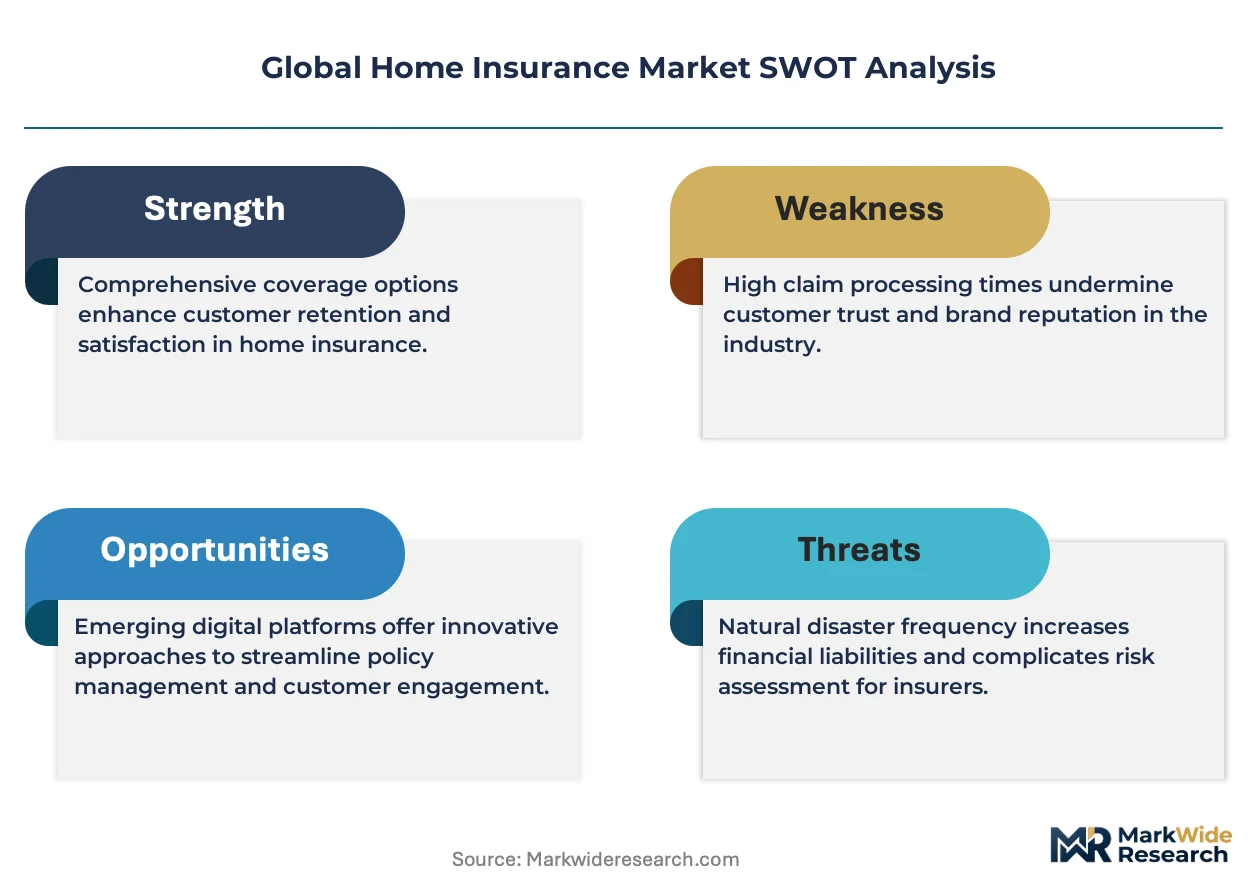
EU Green Deal climate stress-testing protocols is realigning the cost-of-entry calculus for carriers operating across European markets. Allianz leverages its integrated reinsurance capabilities to sustain pricing power in high-exposure German flood zones. State Farm anchors its competitive position through captive agency networks that dominate the US personal lines distribution architecture. Berkshire Hathaway differentiates via float-generated investment income that subsidizes underwriting volatility across its property-casualty portfolio.
Global Home Insurance constitutes a risk-transfer contract indemnifying residential property owners and occupants against structural damage, contents loss, and third-party liability, with policy terms typically spanning twelve months and incorporating deductibles, coverage limits, and exclusions for named perils such as flood or earthquake. The product serves as a financial stabilizer enabling mortgage lending and household wealth preservation by absorbing catastrophic loss events that would otherwise trigger systemic deleveraging. Homeowners Insurance commands the largest premium pool among product types, reflecting enduring primary residence penetration in developed economies, while Renters Insurance represents the fastest-expanding category as urbanization and multifamily construction accelerate in emerging markets. Dwelling Coverage carries the deepest margin pool due to replacement cost valuation complexity and reinsurance dependency, whereas Liability Coverage exhibits more stable loss ratios but lower premium density per policy.
FEMA flood zone remapping in the United States, the EU's Solvency II capital adequacy framework, and Japan's earthquake insurance pool administered through the General Insurance Association of Japan collectively shape product design, pricing transparency, and market access conditions for home insurance providers. These regulatory instruments elevate capital requirements, mandate catastrophe modeling disclosures, and standardize coverage terms that influence consumer purchasing decisions and carrier profitability thresholds. Stakeholders must monitor evolving climate litigation doctrines and parametric insurance innovations that threaten to displace traditional indemnity structures in high-frequency loss corridors.
Market Dynamics
Climate stress-testing mandates from the EU Green Deal and parallel US disclosure frameworks are forcing carriers to rebuild capital reserve models around forward-looking catastrophe exposure rather than historical loss data.
Growth Catalysts
- First-time buyer expansion:Demographic shifts in homeownership barriers are pulling younger households into the risk pool across Germany, the United Kingdom, and Australia.
- EU Green Deal protocols:Mandatory climate disclosure requirements are accelerating product innovation in parametric coverage and green building endorsements.
- Urban multifamily construction:Dense residential development in India, Brazil, and Vietnam is creating new addressable premium volume for renters insurance products.
Market Restraints
- Replacement cost inflation:Building material and labor input volatility is compressing underwriting margins in catastrophe-exposed US states.
- Reinsurance capacity concentration:Bermuda and London market dependency creates pricing power asymmetry for peak peril layers.
- FEMA flood zone remapping:Regulatory friction from updated risk classifications is forcing non-renewals in high-vulnerability coastal counties.
Strategic Opportunities
- Parametric technology convergence:Satellite imagery and IoT sensor networks are enabling index-triggered payouts that bypass traditional claims adjustment.
- Underpenetrated earthquake exposure:Japan's government-administered pool model offers a template for private carrier participation in Turkey and Chile.
- Embedded distribution channels:Mortgage origination platforms and proptech closing services are capturing policy placement at point of sale.
Industry Challenges
- Catastrophe modeling talent scarcity:Actuarial and geospatial analytics functions face recruitment gaps as climate risk quantification demands intensify.
- Legacy policy administration integration:Core system modernization timelines stretch 18-36 months, delaying product velocity for emerging peril coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Insurance Market |
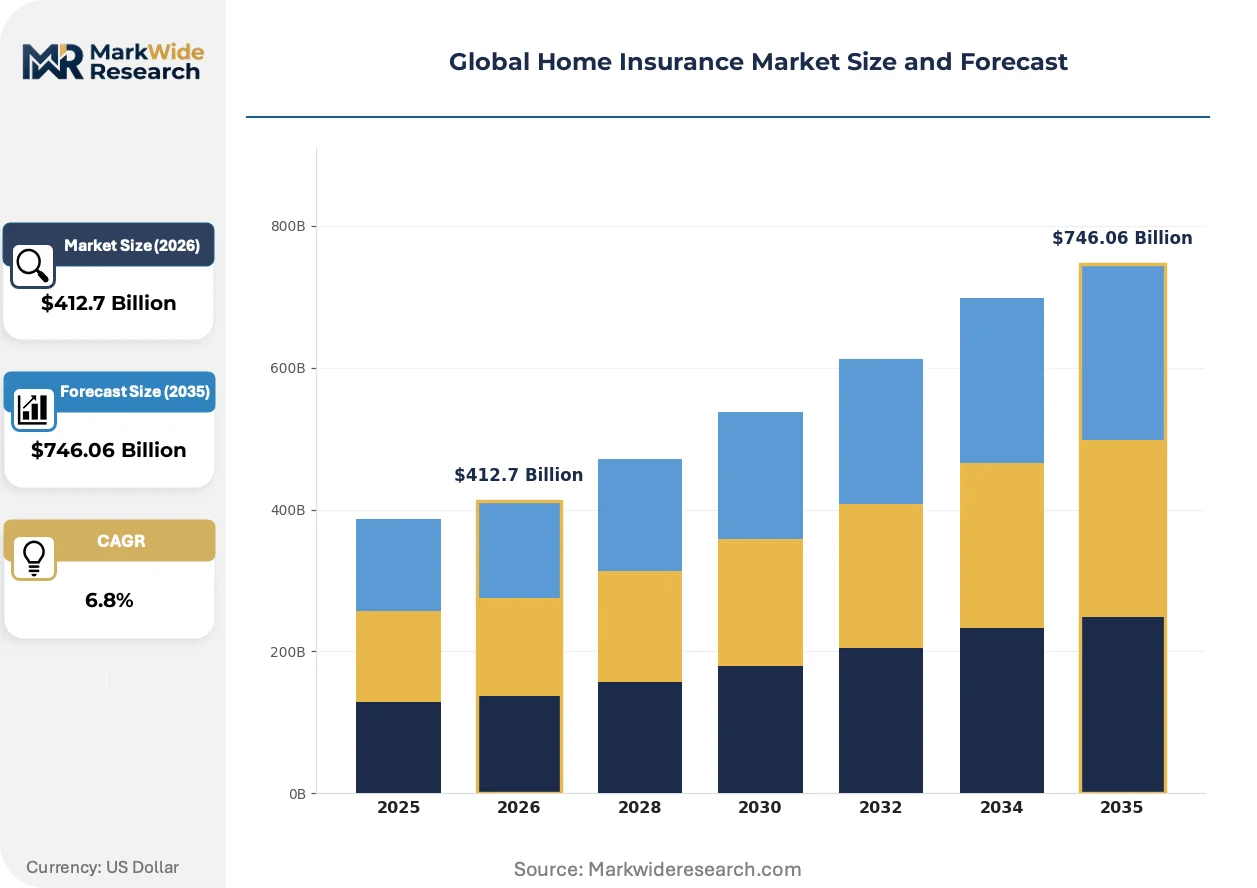
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $746.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homeowners Insurance, Renters Insurance, Landlord Insurance, Condo Insurance Coverage Type: Liability Coverage, Dwelling Coverage, Personal Property Coverage, Additional Living Expenses Customer Type: First-time Buyers, Home Investors, Tenants, Real Estate Agents Service Model: Online Services, Agent-Assisted Services, Direct Sales, Bundled Services |
| Companies Covered | Zurich Insurance Group, Legal & General, Allianz, State Farm, Berkshire Hathaway, Axa, Aviva, Allstate, Assicurazioni Generali, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Insurance Market Emerging Trajectories
Digital telemetry and algorithmic underwriting are compressing the policy lifecycle from quote to bind while reshaping how carriers price and segment residential risk.
Telematics-enabled home monitoring is unifying sensor data streams from water leak detectors, smart thermostats, and security systems into dynamic pricing engines. US and UK carriers are deploying these installations at scale for high-value dwellings. The technology is unifying preventive service dispatch with premium discounts, collapsing the traditional separation between risk transfer and risk mitigation.
CSRD climate disclosure requirements in the European Union are mandating granular exposure reporting across property portfolios. Carriers must now model forward-looking transition and physical risks under standardized scenarios. German and French markets are responding with green building endorsement products that tie coverage terms to energy efficiency certifications.
Direct-to-consumer platform purchasing is displacing captive agency relationships for standard homeowners coverage in digitally mature markets. Price comparison aggregators in the United Kingdom and Australia now dominate initial quote generation, forcing carriers to unbundle advisory services from policy placement. This channel shift is most pronounced among millennial and Gen Z first-time buyers seeking frictionless digital transactions.
Global Home Insurance Market Segmentation
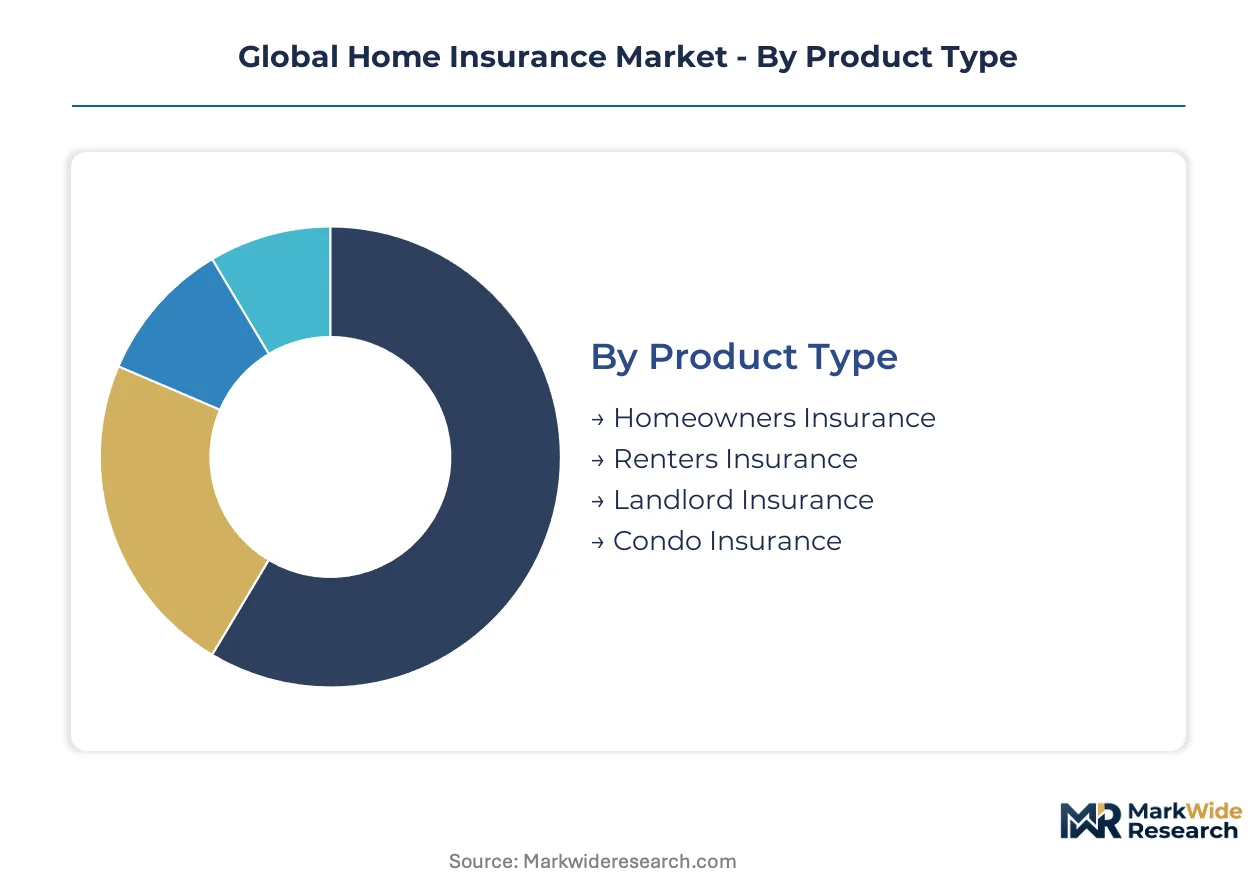
Home insurance segmentation reveals how carriers allocate capital across risk profiles with divergent loss frequencies and reinsurance dependencies. Product architecture and distribution channel choices determine margin capture in a market where climate exposure is rewiring traditional underwriting assumptions.
Product Type:
Standalone indemnity products dominate premium volume, while embedded coverage models gain traction through mortgage origination platforms and proptech partnerships.
- Homeowners Insurance:Comprehensive structural and contents protection for primary residence owners, incorporating named peril exclusions and replacement cost valuation clauses. Demand concentrates in catastrophe-exposed US states where mortgage lenders mandate coverage, though climate-driven non-renewals are compressing addressable households in Florida and California coastal counties.
- Renters Insurance:Personal property and liability coverage for leasehold occupants without structural protection, typically carrying lower premium density but minimal reinsurance dependency. Urban multifamily construction in São Paulo, Mumbai, and Ho Chi Minh City is pulling younger demographics into formal risk pools as landlord requirements spread.
- Landlord Insurance:Dwelling protection for income-generating residential properties, blending structural coverage with rental income loss provisions and tenant liability shields.
- Condo Insurance:Unit-interior coverage complementing master association policies, addressing fixtures, improvements, and personal property within individually owned strata units.
Volume placements concentrate in Homeowners Insurance; the faster expansion belongs to Renters Insurance.
Coverage Type:
Margin depth varies sharply across coverage layers, with structural components demanding sophisticated catastrophe modeling while liability lines exhibit more predictable loss development.
- Liability Coverage:Third-party injury and property damage protection extending beyond the residence premises, including personal injury and medical payments to others. German and UK carriers report stable combined ratios here as litigation frequency remains subdued relative to US tort exposure.
- Dwelling Coverage:Structural protection against physical damage to the residence, valued at replacement cost without depreciation deduction. US Gulf Coast and Australian bushfire corridors are forcing carriers to embed inflation guard endorsements as construction cost volatility outpaces historical trend assumptions.
- Personal Property Coverage:Contents protection for household belongings, typically written on an actual cash value basis with replacement cost upgrades available.
- Additional Living Expenses:Temporary housing and incremental cost reimbursement during repair periods following covered losses.
Premium density peaks in Dwelling Coverage; Additional Living Expenses is climbing the fastest as climate displacement events lengthen restoration timelines.
Customer Type:
Acquisition economics diverge across customer lifecycle stages, with first-time buyers requiring education-intensive distribution while investor segments prioritize portfolio efficiency.
- First-time Buyers:Demographic cohort entering homeownership with limited prior insurance literacy and heightened price sensitivity. Australian and UK price comparison aggregators capture this segment through digital-first quote journeys, though agent-assisted channels retain dominance in US states with complex catastrophe exposure.
- Home Investors:Portfolio landlords and fractional ownership participants seeking streamlined coverage across multiple properties. Proptech platforms in Germany and the Netherlands are embedding landlord policies into closing workflows for buy-to-let transactions.
- Tenants:Leasehold occupants with minimal asset exposure but growing liability awareness, particularly in dense urban rental markets.
- Real Estate Agents:Intermediaries facilitating coverage placement as a value-added service during property transactions, capturing referral economics in high-velocity markets.
Policy count concentrates in First-time Buyers; Home Investors are gaining share fastest as institutional rental platforms expand across European and Asia-Pacific urban cores.
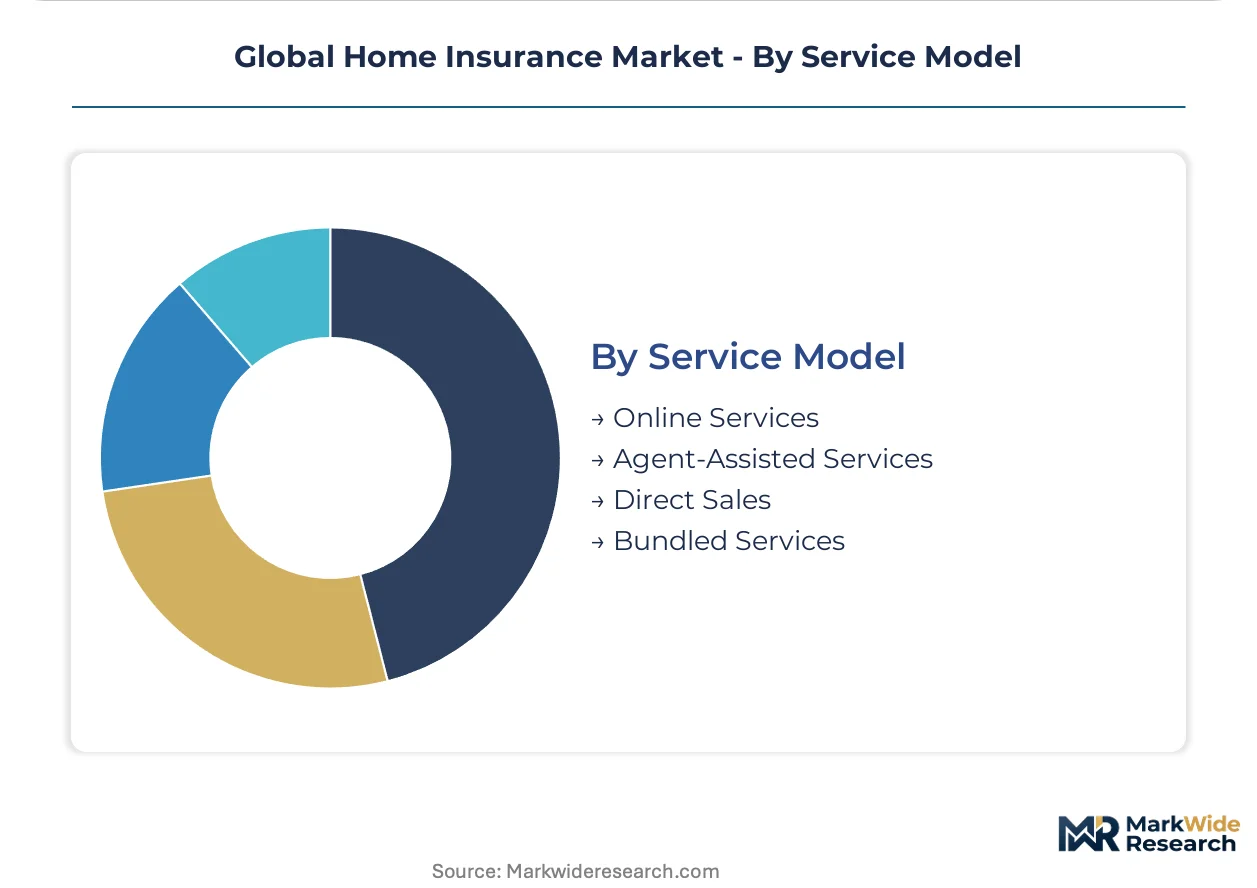
Service Model:
Distribution infrastructure investments are separating carriers with captive agent networks from those building direct-to-consumer capabilities.
- Online Services:Fully digital quote-to-bind platforms with algorithmic underwriting and self-service policy management. UK and Australian markets exhibit the deepest penetration here, though US carriers are accelerating platform investments to capture millennial and Gen Z preference shifts.
- Agent-Assisted Services:Human intermediary networks providing advisory depth for complex coverage needs and catastrophe-exposed risks. This model retains pricing power in US states where regulatory friction and claims litigation reward relationship-based distribution.
- Direct Sales:Carrier-owned channels bypassing independent intermediaries, common among mutual insurers and affinity marketing programs.
- Bundled Services:Multi-line packaging combining home coverage with auto, life, or financial products, leveraging cross-sell economics to improve retention.
Written premium concentrates in Agent-Assisted Services; Online Services are expanding most quickly as telematics integration enables real-time risk pricing without physical inspection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Dubai's International Financial Centre and Singapore's Marina Bay cluster have concentrated reinsurance capital and captive management operations, drawing primary carriers to establish regional headquarters alongside regulatory arbitrage advantages.
United States
Catastrophic weather exposure and replacement cost inflation are restructuring policy terms across Gulf Coast and California markets. FEMA flood zone remapping is forcing non-renewals in high-vulnerability coastal counties while elevating capital reserve requirements for admitted carriers. Miami-Dade and Harris County (Houston) represent the deepest premium pools for wind and flood coverage respectively.
Germany
EU Green Deal climate stress-testing protocols are recalibrating Solvency II capital adequacy models for flood-exposed portfolios. The Federal Financial Supervisory Authority (BaFin) mandates granular catastrophe modeling disclosures that favor integrated reinsurance capabilities. Munich and Frankfurt anchor the highest density of primary carrier headquarters with captive reinsurance subsidiaries.
United Kingdom
Price comparison aggregator dominance is compressing distribution margins for standard homeowners coverage while accelerating direct-to-consumer platform adoption. The Prudential Regulation Authority's climate disclosure frameworks align with CSRD exposure reporting requirements. London's Lloyd's market retains pricing power for high-value dwelling risks requiring bespoke underwriting.
Japan
Government-administered earthquake insurance pools administered through the General Insurance Association of Japan limit private carrier exposure while standardizing coverage terms. METI's dual carbon goals are reshaping building code incentives that feed into property risk ratings. Tokyo and Osaka metropolitan zones concentrate the majority of residential premium volume.
Australia
Bushfire corridor exposure and cyclone risk in Queensland are forcing inflation guard endorsements into standard policy wordings. The Australian Prudential Regulation Authority's climate vulnerability assessments elevate capital charges for catastrophe-exposed portfolios. Sydney and Melbourne price comparison aggregators capture first-time buyer segments through digital-first distribution.
Global Home Insurance Market Vendor Landscape
North American carriers anchor one tier through captive agency networks and direct-to-consumer platforms; European specialists hold another via integrated reinsurance capabilities and climate-aligned product innovation. Market structure exhibits moderate consolidation with scale advantages accruing to multi-line personal lines writers and mutual insurers with captive distribution. Three archetypes dominate: integrated reinsurance-primary hybrids, mutual insurers with agency captivity, and direct-to-consumer algorithmic underwriters. Competitive intensity centers on embedded distribution partnerships with mortgage originators and proptech closing services.
Within the integrated reinsurance tier, Allianz and Zurich Insurance Group represent the archetype of carriers leveraging captive reinsurance subsidiaries to sustain pricing power in peak peril zones. State Farm anchors the mutual-agency model with exclusive agent networks that dominate US personal lines distribution architecture. Berkshire Hathaway occupies a position where float-generated investment income subsidizes underwriting volatility across property-casualty portfolios.
| Leading Market Players |
|---|
| Zurich Insurance Group |
| Legal & General |
| Allianz |
| State Farm |
| Berkshire Hathaway |
| Axa |
| Aviva |
| Allstate |
| Assicurazioni Generali |
| Others |
Supply Flow & Price Mechanics
Mutual insurers with captive agency networks anchor supply discipline through exclusive distribution control, translating relationship-based placement into pricing power that resists direct-to-consumer compression. Their ownership structure buffers capital reserve demands from EU Green Deal climate stress-testing, while Bermuda reinsurance capacity concentration forces peak-peril layer pricing upward across catastrophe-exposed US states.
Pricing Analysis
Short lead-time capacity commands premium placement in catastrophe-exposed US states where FEMA flood zone remapping has compressed policy availability. Three-tier pricing structure across premium, standard, and economy levels stratifies by replacement cost valuation complexity and reinsurance dependency, with dwelling coverage carrying the deepest margin pool. Cost compression in standard homeowners tiers is intensifying because building material and labor input volatility outpaces historical trend assumptions. First-time buyers exhibit the highest price sensitivity, while home investors prioritize portfolio efficiency over per-policy cost minimization.
Supply Chain Analysis
Actuarial and catastrophe modeling talent scarcity in London, Zurich, and Singapore constrains underwriting capacity expansion as climate risk quantification demands intensify. Raw material dependencies center on satellite imagery data feeds, IoT sensor hardware, and geospatial analytics software platforms. Single-source vulnerability concentrates in Bermuda and London market reinsurance capacity for peak peril layers. Distribution runs through captive agency networks in the United States and price comparison aggregators in the United Kingdom and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal climate disclosure mandates erect a compliance moat that rewards carriers with integrated reinsurance capabilities and forward-looking catastrophe modeling infrastructure. Solvency II capital adequacy recalibration favors incumbents who pre-invested in granular exposure reporting systems.
For Market Incumbents: Hedge against parametric insurance displacement by embedding sensor-enabled preventive services into standard policy wordings, collapsing the separation between risk transfer and risk mitigation. Acquire catastrophe modeling talent clusters in London and Singapore before recruitment gaps widen further. Channel control through exclusive agent networks retains pricing power in US states with complex regulatory friction.
For New Entrants and Emerging Players: Urban multifamily tenants in São Paulo, Mumbai, and Ho Chi Minh City represent an underserved buyer archetype with minimal reinsurance dependency and accelerating landlord-mandated coverage requirements. Capture this segment through embedded distribution partnerships with proptech closing services and mortgage origination platforms. Digital-first quote journeys targeting first-time buyers in Australian and UK markets bypass incumbent agency captivity.
For Investors and Strategic Acquirers: FEMA flood zone remapping acceleration is the leading indicator that non-renewal volume in Florida and California coastal counties will concentrate into surplus lines and alternative capital vehicles. Long-term viability rests on carriers who balance climate-exposed primary portfolios with captive reinsurance subsidiaries. Monitor EU Green Deal implementation timelines as the signal for capital reserve requirement inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Technology Integration | Satellite imagery and IoT sensor networks enable index-triggered payouts that bypass traditional claims adjustment. |
| Green Building Endorsement Development | CSRD climate disclosure requirements in the European Union mandate granular exposure reporting across property portfolios. |
| Embedded Distribution Partnership | Mortgage origination platforms and proptech closing services capture policy placement at point of sale. |
| Catastrophe Modeling Talent Acquisition | Actuarial and geospatial analytics functions face recruitment gaps as climate risk quantification demands intensify. |
| Reinsurance Subsidiary Captivation | Integrated reinsurance capabilities sustain pricing power in peak peril zones like German flood corridors. |
Methodological Framework
Multi-period observation of premium volume trajectories, policy non-renewal rates, and reinsurance capacity pricing anchored the trend analysis, supplemented by interviews with underwriting executives, actuarial directors, distribution channel heads, and regulatory compliance officers. Secondary validation drew from NAIC statutory filings, Lloyd's market reports, EU Solvency II disclosures, and General Insurance Association of Japan earthquake pool data. Bottom-up policy count modeling and top-down premium pool estimation were triangulated against carrier-reported segment disclosures.
Segment-weighting across product type, coverage layer, customer lifecycle stage, and service model distribution channel shaped the analytical framework. CAGRs were derived from fitted trend projections across the modeling period, with explicit incorporation of climate stress-testing mandate implementation schedules and replacement cost inflation assumptions. Forward-looking catastrophe exposure replaced historical loss data as the primary forecast input.
Revisions become necessary when regulatory disclosure timelines accelerate, reinsurance capacity contracts beyond modeled thresholds, or parametric insurance adoption rates exceed baseline assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Peer to Peer Insurance Market
Insurance
Art Insurance Market
Insurance
Aerospace Insurance Market
Insurance
Insurance Big Data Analytics Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
US Homeowner's Insurance Market
Insurance
Insurance Protection Products Market
Insurance
South Korea Liability Insurance Market
Insurance
Financial Protection Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Commercial Cyber Insurance Market
Insurance
Travel Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
Car Insurance Market
Insurance
Canada House Insurance Market
Insurance
France Car Insurance Market