
 Digital Innovation in Insurance Market | 2026-2036
Digital Innovation in Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Innovation in Insurance Market Analysis
Modular policy bundling is repositioning buyer choice in personal and commercial lines, letting customers assemble coverage components rather than accepting static packages. Next Insurance leverages this shift by specializing in configurable small-business policies that adjust with workforce changes. AXA competes through embedded distribution partnerships that embed insurance at the point of commercial transaction. Wefox anchors its model on a hybrid advisory-digital platform that sustains agent relationships while automating back-office processes.
Digital innovation in insurance encompasses the application of advanced computational technologies—including machine learning algorithms processing structured and unstructured data at sub-second latency, distributed ledger architectures for immutable policy records, and sensor networks capturing real-time asset telemetry—to transform risk evaluation, contract execution, and claims settlement across the insurance value chain. Artificial Intelligence leads technology deployment by displacing manual underwriting in property and casualty lines, while Blockchain occupies narrower but high-margin applications in reinsurance contract certainty and parametric payout automation. Cloud-Based deployment is expanding fastest among mid-tier carriers seeking to bypass legacy core system replacement costs.
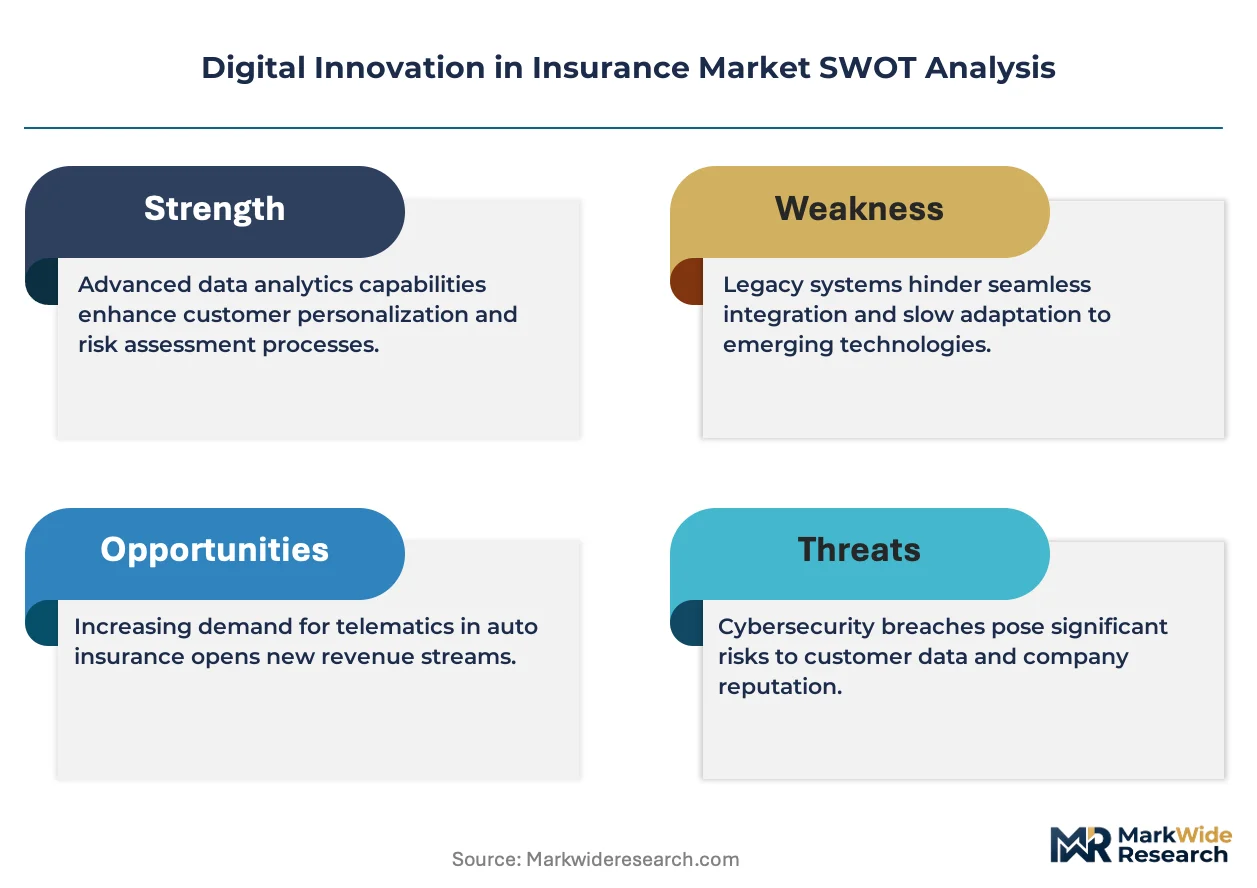
FDA oversight of software-as-medical-device applications intersects with health insurance innovation, while the EU AI Act imposes conformity requirements on automated underwriting decisions that affect European consumers. HIPAA constraints on health data portability shape how US insurers integrate wearable telemetry into pricing models. State-level insurance department scrutiny of algorithmic fairness is intensifying across multiple jurisdictions. Stakeholders must monitor whether regulatory fragmentation between federal and state frameworks fragments platform economics or creates first-mover advantages for carriers with compliance infrastructure that spans multiple regimes.
Market Dynamics
Commercial property carriers face mounting pressure to replace manual underwriting with automated decision systems that satisfy both speed requirements and emerging algorithmic accountability mandates across multiple jurisdictions.
Growth Catalysts
- EU AI Act conformity requirements:Automated underwriting decisions affecting European consumers now demand explainable algorithmic documentation, accelerating carrier investment in interpretable machine learning architectures and audit-ready model governance.
- Sensor telemetry proliferation:Real-time asset monitoring through IoT networks enables dynamic risk pricing and parametric claim triggers, particularly in commercial property and fleet auto lines where loss prevention data directly informs premium adjustments.
- German insurtech cluster density:Munich and Berlin host concentrated digital labs and venture-backed startups that generate talent pipelines and partnership opportunities for incumbent carriers seeking modular platform components.
Market Restraints
- Legacy core system entanglement:Policy administration systems built on decades-old COBOL architectures impose integration costs that consume 40-60% of digital transformation budgets at mid-tier carriers.
- Data residency fragmentation:GDPR requirements for European policyholder data and state-level US privacy laws force multi-jurisdictional cloud architectures that duplicate infrastructure spend and complicate single-platform strategies.
- Algorithmic bias liability exposure:State insurance department scrutiny of proxy discrimination in pricing models creates litigation risk that slows deployment of fully automated underwriting in personal lines.
Strategic Opportunities
- Embedded distribution at transaction points:Partnerships with vertical SaaS platforms and e-commerce marketplaces enable insurance attachment at moments of asset acquisition or business formation, bypassing traditional agent channel economics.
- Parametric product expansion:Blockchain-executed smart contracts enable automatic payout upon verified trigger events, opening addressable markets in climate-exposed agriculture and supply chain interruption coverage.
- Hybrid advisory-digital models:Agent-facing platforms that automate back-office workflows while preserving human relationship management capture underserved small-commercial segments that resist pure direct-to-consumer approaches.
Industry Challenges
- Actuarial-technologist collaboration gaps:Underwriting departments lack personnel fluent in both traditional risk pricing and machine learning model validation, slowing production deployment of AI-assisted decision tools.
- Model governance certification timelines:Internal validation and external audit processes for algorithmic fairness extend 12-18 months, compressing competitive windows for first-mover product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Innovation in Insurance Market |
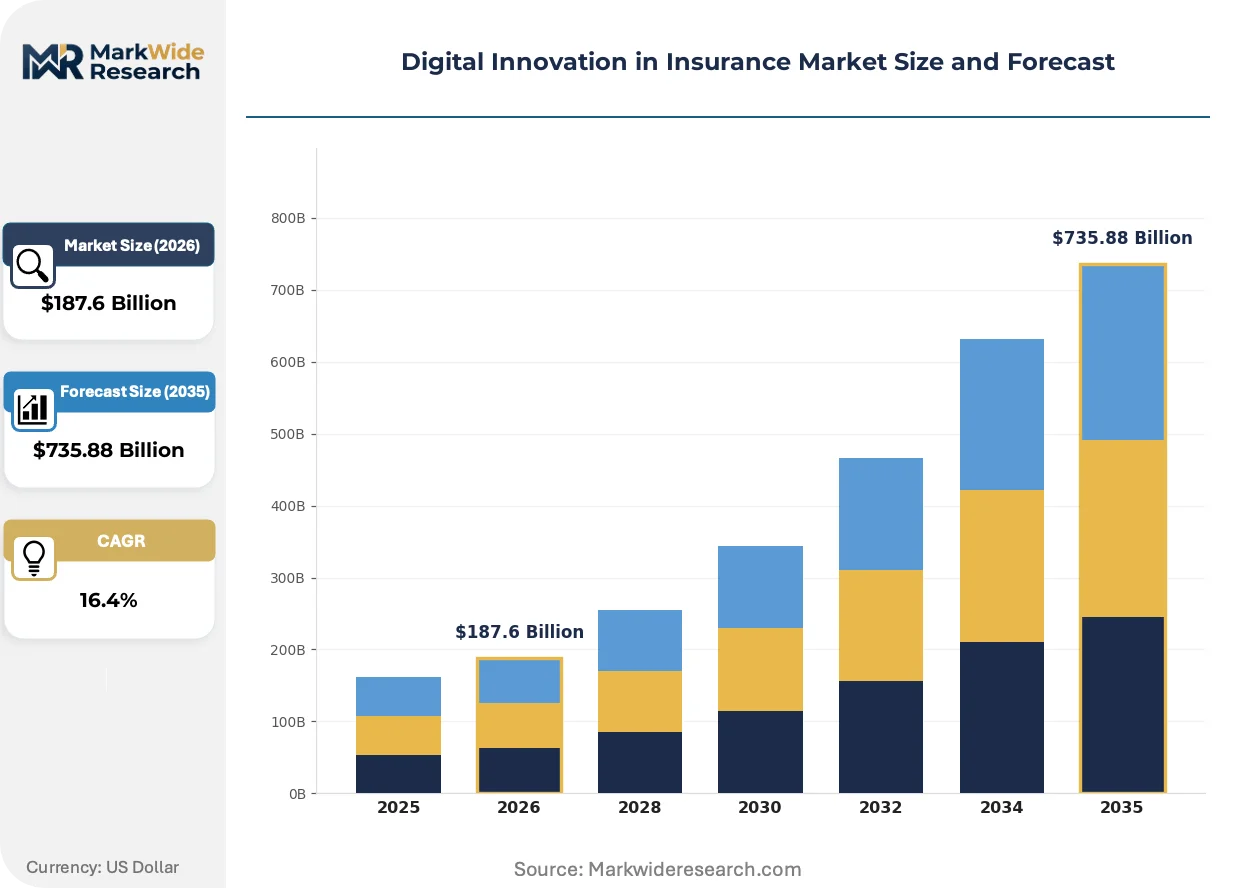
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $735.88 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, Artificial Intelligence, IoT, Big Data Service Type: Claim Processing, Policy Management, Customer Support, Risk Assessment End User: Insurers, Brokers, Third-Party Administrators, Regulators Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Next Insurance, Hippo Insurance, NTT DATA, Ethos Life, Alan, State Farm, Wefox, Devoted Health, AXA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Innovation in Insurance Market Emerging Trajectories
Computational capabilities and regulatory mandates are converging to restructure how risk is evaluated, priced, and distributed across personal and commercial insurance lines.
Machine learning architectures are integrating natural language processing of unstructured submission documents with structured loss history databases to generate bindable quotes in under 60 seconds for standard commercial risks. Mid-market carriers lacking legacy system replacement capital are adopting cloud-native policy administration platforms that enable API-first distribution partnerships without core system overhaul.
The EU AI Act imposes conformity assessment requirements on automated underwriting systems that affect European consumers, compelling carriers to maintain algorithmic documentation, human oversight protocols, and bias monitoring infrastructure. German and French regulators have initiated sector-specific guidance on proxy discrimination in pricing models, accelerating carrier investment in fairness-aware machine learning techniques.
Small-business buyers are assembling coverage components through modular policy builders rather than accepting static package policies, forcing carriers to unbundle traditionally combined coverages. This pattern concentrates among digitally native business formations in urban metropolitan areas, where entrepreneurs expect consumer-grade configuration interfaces for commercial protection products.
Digital Innovation in Insurance Market Segmentation
Technology, service, and deployment configurations in insurance innovation carry distinct regulatory footprints. EU AI Act conformity requirements apply unevenly across segments, shaping capital allocation and platform architecture decisions.
Technology:
EU AI Act high-risk system classifications and FDA software-as-medical-device oversight create tiered certification burdens that segment investment timelines and compliance costs.
- Artificial Intelligence:Machine learning architectures process structured loss histories and unstructured submission documents at sub-second latency for automated underwriting decisions. German and French carriers concentrate procurement here to satisfy emerging algorithmic accountability mandates while compressing quote-to-bind cycles in commercial property lines.
- Blockchain:Distributed ledger architectures enforce immutable policy records and execute smart contracts for parametric payouts in reinsurance and climate-linked coverage. Demand clusters in high-margin contract certainty applications where counterparty verification costs exceed platform implementation spend.
- IoT:Sensor networks capture real-time asset telemetry enabling dynamic premium adjustments and loss prevention interventions.
- Big Data:Aggregated behavioral and risk datasets inform predictive pricing models across personal and commercial lines.
Leading the category by volume: Artificial Intelligence. Growing fastest: Blockchain.
Service Type:
Service specialization determines which HIPAA, GDPR, or state insurance department frameworks govern operational design and data handling protocols.
- Claim Processing:Automated document ingestion, damage assessment algorithms, and payment execution systems reduce settlement cycles from weeks to hours. US carriers facing state-level scrutiny of algorithmic fairness concentrate investment here to demonstrate transparent decision trails.
- Risk Assessment:Predictive models synthesize historical loss data, external hazard databases, and real-time telemetry to generate bindable quotes. EU-based commercial property insurers prioritize this segment to satisfy EU AI Act explainability requirements while maintaining competitive speed-to-quote.
- Policy Management:Core administration platforms handle contract lifecycle, endorsement processing, and regulatory reporting.
- Customer Support:Natural language interfaces and automated inquiry routing reduce service cost per interaction.
Dominant by revenue concentration: Claim Processing. Expanding most quickly: Risk Assessment.
End User:
End-user category determines platform customization depth and regulatory interface complexity, with direct carriers facing stricter solvency and conduct requirements than intermediaries.
- Insurers:Direct carriers deploy end-to-end digital platforms spanning underwriting, policy administration, and claims, absorbing full compliance burden for EU AI Act and state algorithmic fairness mandates. Munich and Berlin-based insurtechs target this segment with modular components that incumbent carriers integrate without legacy system replacement.
- Brokers:Intermediary-facing platforms require quote-comparison engines, client management tools, and commission tracking systems.
- Third-Party Administrators:Outsourced claims and policy service providers demand workflow automation and audit-ready documentation systems.
- Regulators:Supervisory technology platforms enable market conduct monitoring, solvency surveillance, and algorithmic oversight.
Highest platform spend: Insurers. Fastest adoption velocity: Third-Party Administrators.
Deployment:
Deployment mode selection reflects legacy system entanglement severity and data residency fragmentation exposure across GDPR and US state privacy regimes.
- Cloud-Based:API-first platforms enable rapid distribution partnerships and modular capability expansion without core system overhaul. Mid-tier US and European carriers lacking legacy replacement capital drive demand here to bypass COBOL architecture constraints.
- Hybrid:Split architectures maintain sensitive policy data on-premises while leveraging cloud compute for analytics and customer-facing applications. German carriers favor this configuration to satisfy GDPR data residency requirements while accessing scalable processing.
- On-Premises:Fully captive infrastructure preserves maximum control over sensitive data and system availability.
- Managed Services:Outsourced platform operation transfers operational and compliance risk to specialized vendors.
Largest installed base: Cloud-Based. Steepest expansion trajectory: Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital innovation in insurance concentrates where capital depth, regulatory clarity, and technical talent intersect. The United States consumes the largest share of AI-powered underwriting platforms, while Germany and the United Kingdom export insurtech architectures to adjacent markets. China and Japan represent distinct deployment models shaped by data governance frameworks and incumbent carrier structures.
United States
Commercial property carriers and health insurers drive AI underwriting procurement. HIPAA constraints on wearable telemetry integration force carriers to architect pricing models around de-identified data streams. Silicon Valley and New York Metro host dense clusters of venture-backed insurtechs supplying modular policy administration components to incumbent carriers.
Germany
Mid-tier commercial carriers and industrial mutual insurers dominate demand for explainable algorithmic systems. The EU AI Act and BaFin guidance on automated decision-making accelerate investment in interpretable machine learning and audit-ready model governance. Munich anchors Europe's densest insurtech cluster, with Berlin hosting digital labs focused on small-commercial platform development.
United Kingdom
Lloyd's syndicates and London market carriers prioritize blockchain-enabled contract certainty and parametric payout automation. The Financial Conduct Authority's scrutiny of algorithmic fairness in pricing models shapes vendor selection criteria. The London-Edinburgh corridor concentrates insurtech engineering talent serving both domestic carriers and export markets.
China
Internet platform conglomerates and state-owned carriers co-invest in embedded distribution partnerships. SAMR oversight of algorithmic recommendation systems and data security law requirements constrain foreign platform architectures. Shanghai and Shenzhen host captive development centers producing insurance-specific natural language processing engines.
Japan
Non-life mutual insurers and regional banks with insurance subsidiaries lead adoption of hybrid advisory-digital platforms. METI guidance on AI utilization principles shapes carrier procurement of human-in-the-loop underwriting systems. Tokyo-Osaka corridor carriers partner with domestic systems integrators rather than global cloud providers for core platform replacement.
Digital Innovation in Insurance Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology deployment, distribution architecture, and service specialization. Market structure shows moderate consolidation around incumbent carriers with captive digital labs, fragmented vendor supply for modular components, and emerging concentration in embedded distribution platforms. Three archetypes dominate: full-stack carriers owning end-to-end technology, platform vendors supplying white-label infrastructure, and vertical SaaS intermediaries attaching insurance at transaction points. Competitive intensity manifests through strategic partnerships with cloud providers and API-first integration plays that bypass legacy system replacement cycles.
Among full-stack digital carriers, Next Insurance and Hippo Insurance exemplify the focused pure-play archetype, occupying positions built around configurable small-business coverage and sensor-integrated home protection respectively. AXA represents the diversified incumbent model, embedding distribution partnerships across commercial transaction points while maintaining captive technology development. Wefox anchors the hybrid advisory-digital tier, sustaining agent-facing platform architectures that automate back-office workflows without displacing human relationship management.
| Leading Market Players |
|---|
| Next Insurance |
| Hippo Insurance |
| NTT DATA |
| Ethos Life |
| Alan |
| State Farm |
| Wefox |
| Devoted Health |
| AXA |
| Others |
Supply Flow & Price Mechanics
Cloud compute capacity costs cascade through SaaS-tiered insurance platform pricing, with hyperscaler infrastructure spend in Frankfurt and Virginia data centers translating directly into per-policy subscription tiers for mid-tier carriers seeking to bypass legacy system replacement.
Pricing Analysis
Margin tightening in cloud-native platform tiers reflects hyperscaler concentration and GDPR-compliant architecture premiums. Three-tier pricing structure across premium, standard, and economy levels separates carriers with full algorithmic audit trails from those with basic automation. Certification investment in EU AI Act conformity drives price differentiation between European-deployable and standard global configurations. Small-commercial carriers exhibit highest price sensitivity, while Lloyd's syndicates absorb premium pricing for contract certainty.
Supply Chain Analysis
Specialized machine learning engineering talent supply rests on Munich, Berlin, and London metropolitan clusters feeding vendor development pipelines. Core dependencies include cloud infrastructure from hyperscalers, proprietary natural language processing engines from Shanghai-Shenzhen development centers, and blockchain consensus architectures from London-Edinburgh engineering corridors. Single-source vulnerability concentrates in cloud infrastructure provision. Distribution runs through API-first integration partnerships that bypass traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Machine learning architectures are displacing manual underwriting workflows, compressing quote-to-bind cycles from days to seconds while forcing compliance infrastructure investment.
For Market Incumbents: Extend interpretable model governance capabilities to satisfy EU AI Act documentation requirements before regulatory deadlines harden competitive moats. Consolidate around captive cloud infrastructure investments in Frankfurt and Virginia to reduce hyperscaler dependency. Prioritize acquisition of modular policy administration vendors in Munich and Berlin to accelerate platform unbundling without legacy system overhaul.
For New Entrants and Emerging Players: Embedded distribution partnerships with vertical SaaS platforms offer the most penetrable route for bypassing agent channel economics in small-commercial lines. Target climate-exposed agriculture and supply chain interruption segments where parametric smart contract capabilities remain underdeveloped. Lead with API-first integration plays that demonstrate sub-60-second quote generation.
For Investors and Strategic Acquirers: BaFin guidance publication on automated decision-making is the leading indicator that German carrier procurement cycles will accelerate interpretable ML vendor consolidation. Long-term viability centers on platforms spanning multiple regulatory regimes with pre-built compliance infrastructure. Watch for state insurance department algorithmic fairness enforcement actions as signal for US market inflection toward audit-ready vendor selection.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Documentation infrastructure satisfies BaFin oversight requirements while creating switching costs for European carriers. |
| Embedded Distribution Partnership | Vertical SaaS integration captures small-commercial buyers at business formation moments outside traditional channels. |
| Hybrid Advisory-Digital Platform | Agent-facing automation preserves relationship economics in segments resisting pure direct-to-consumer approaches. |
| Parametric Smart Contract Expansion | Blockchain-executed payouts open climate-linked coverage markets with automatic trigger verification. |
| Cloud-Native Core Replacement | API-first architecture enables modular capability expansion without COBOL system entanglement costs. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with chief underwriting officers, insurtech platform engineers, regulatory affairs specialists at BaFin and state insurance departments, and procurement leads at mid-tier carriers. Primary fieldwork covered technology deployment patterns across Munich, Berlin, London, and New York Metro clusters. Bottom-up policy administration platform spend estimates triangulated against top-down carrier IT budget disclosures.
Granularity-level modeling segmented the analysis window by technology deployment mode, service specialization, and end-user category, with additional dimensioning for regulatory jurisdiction clusters affecting compliance cost allocation. CAGRs derived from slope-intercept analysis of carrier procurement cycle data and vendor booking trends. Forecast inputs incorporated EU AI Act implementation timelines and state-level algorithmic fairness enforcement probability.
Inputs from carrier earnings calls and vendor S-1 filings were available through the study window; gaps in private insurtech valuation data introduce uncertainty bands around platform market sizing. Forecasts reflect documented assumptions regarding regulatory implementation pacing and cloud infrastructure cost trajectories. Regulatory fragmentation between federal and state frameworks, plus EU AI Act enforcement variance, warrants ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Global AI in Auto-Insurance Market
Insurance
US Extended Warranty Market
Insurance
Germany Reinsurance Market
Insurance
Asia-Pacific EV Insurance Market
Insurance
Aerospace Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
Switzerland Reinsurance Market
Insurance
Boiler Insurance Market
Insurance
Insurance Brokerage Market
Insurance
Digital Insurance Market
Insurance
Workers Compensation Insurance Market
Insurance
GCC Bancassurance Market
Insurance
Financial Protection Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Global Flood Insurance Market
Insurance
Saudi Arabia Property and Casualty Insurance Market