
 Asia-Pacific Liability Insurance Market | 2026-2036
Asia-Pacific Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Liability Insurance Market Analytics
Market Context
Singapore's regional underwriting hub expansion is reshaping how carriers service cross-border liability portfolios across ASEAN. Ping An Insurance leverages its domestic scale to dominate China's professional liability segment. Tokio Marine & Nichido Fire Insurance Co. Ltd. anchors Japanese corporate demand through specialized manufacturing coverage. QBE Insurance Group extends its Australasian brokerage relationships into emerging Asian markets.
Technical Definition and Structural Segments
Asia-Pacific liability insurance encompasses contractual risk transfer instruments that indemnify policyholders against third-party claims for bodily injury, property damage, or financial loss arising from negligence, defective products, or professional errors, with policies typically specifying per-occurrence limits, aggregate caps, and retroactive dates calibrated to exposure duration. General liability coverage occupies the largest premium pool due to mandatory requirements across construction and hospitality sectors, while professional liability accelerates fastest as technology consultancies and financial advisors face heightened litigation frequency in India and Singapore. Claims-made policy structures dominate medical and legal professions where long-tail exposure complicates occurrence-based pricing.
Regulatory Framework and Outlook
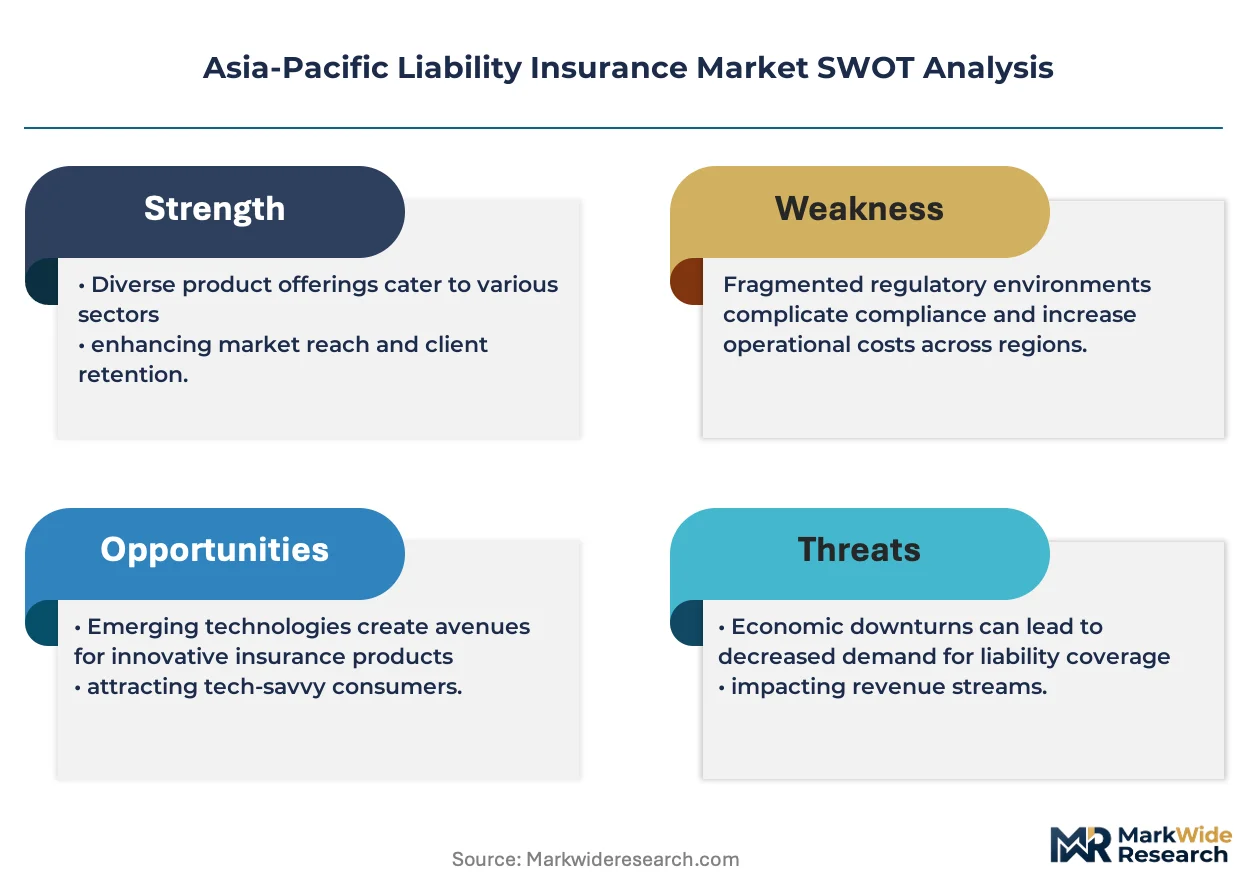
APRA in Australia, China's CBIRC, and Japan's FSA enforce capital adequacy and consumer protection standards that dictate product filing requirements, solvency margins, and policy form disclosures across their respective jurisdictions. India's IRDAI mandates bancassurance and digital distribution protocols that reshape broker commission structures and direct-to-consumer channel viability. Stakeholders must monitor how ESG disclosure obligations and climate litigation precedents redefine coverage exclusions and premium adequacy across the region.
Market Dynamics
APRA's tightening disclosure mandates for directors and officers liability coverage are compressing policy issuance timelines while elevating capital reserves across Australian carriers, forcing regional underwriters to restructure pricing models and retroactive date conventions.
Growth Catalysts
- Construction liability mandates:Southeast Asian regulators now require statutory liability coverage for infrastructure projects exceeding defined capital thresholds, pulling premium volume from Vietnam's port expansions and Indonesia's toll-road developments.
- Professional liability acceleration:Technology consultancies in Singapore and India face litigation frequency from software implementation failures, expanding errors-and-omissions policy uptake among fintech and insurtech vendors.
- Climate litigation exposure:Australian courts are establishing precedents for director liability tied to inadequate climate risk disclosure, prompting ASX-listed firms to secure enhanced D&O limits.
Market Restraints
- Reinsurance capacity contraction:Lloyd's syndicates have reduced Asia-Pacific casualty treaty support by tightening attachment points and excluding certain product liability classes.
- Long-tail reserve volatility:Asbestos and environmental claims from Australia's manufacturing legacy continue to distort loss-ratio projections for occurrence-based general liability portfolios.
- Regulatory fragmentation:Divergent policy form filing requirements between China's CBIRC, Japan's FSA, and India's IRDAI inflate compliance overhead for multi-jurisdictional programs.
Strategic Opportunities
- Philippines underpenetration:Professional liability penetration remains below regional benchmarks among Manila-based business process outsourcing firms, creating whitespace for targeted coverage modules.
- Cyber liability bundling:Convergence of network security protocols with traditional E&O structures allows carriers to package first-party incident response with third-party privacy liability.
- Parametric triggers:Index-based settlement mechanisms for natural catastrophe business interruption are gaining traction among Thai and Vietnamese manufacturing risks.
Industry Challenges
- Actuarial talent scarcity:Asia-Pacific markets face acute shortages of casualty actuaries familiar with claims-made policy reserving and IBNR estimation for emerging liability classes.
- Legacy system integration:Established carriers in Japan and Australia struggle to embed telematics and IoT sensor data into traditional underwriting workflows for real-time exposure monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Liability Insurance Market |
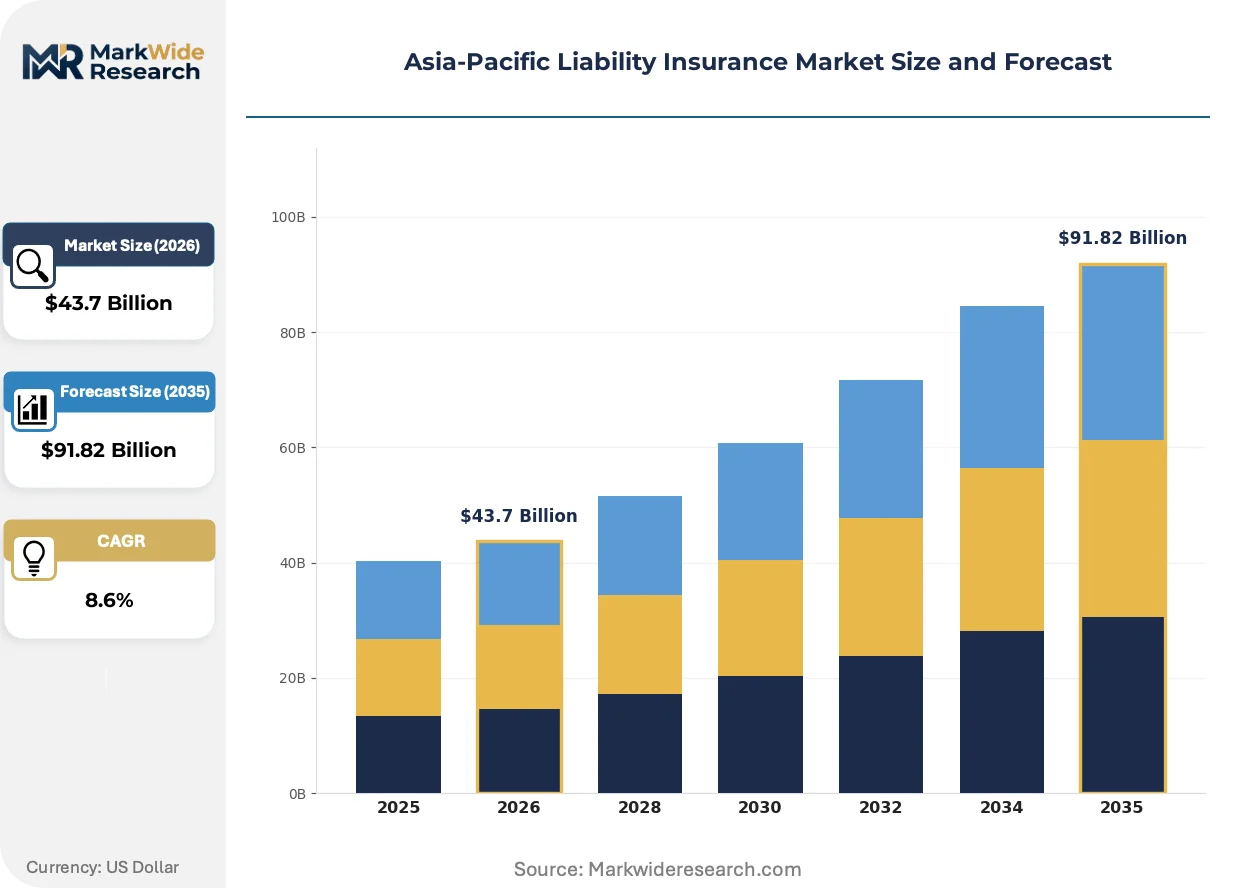
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $91.82 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: General Liability, Professional Liability, Product Liability, Environmental Liability End User: SMEs, Large Enterprises, Public Sector, Non-Profit Organizations Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents Policy Type: Occurrence, Claims-Made, Combined, Tail Coverage |
| Companies Covered | Ping An Insurance, Tokio Marine & Nichido Fire Insurance Co. Ltd., QBE Insurance Group, Axa Group, Allianz Group, AIA Group, China Life Insurance, Chubb Limited, People's Insurance Company of China, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Liability Insurance Market Evolving Landscape
Digital distribution infrastructure and embedded coverage APIs are compressing policy issuance cycles while enabling granular risk segmentation previously unavailable through conventional broker channels across the region.
Parametric liability triggers are virtualizing traditional indemnity structures by replacing lengthy claims adjustment with pre-defined index-based payouts. Agricultural cooperatives in Thailand and flood-exposed manufacturers in Vietnam are piloting these instruments for business interruption coverage. This virtualization is compressing settlement timelines from months to days while reducing loss-adjustment expense ratios.
Australia's APRA has mandated enhanced climate risk disclosure in D&O policy applications, requiring boards to document governance frameworks for physical and transition risk oversight. ASX-listed entities must now secure coverage affirmations that explicitly address director liability for inadequate climate governance. Mining and energy sectors are responding by negotiating standalone climate liability endorsements separate from traditional D&O towers.
Corporate risk managers are consolidating vendor relationships around integrated casualty programs rather than purchasing general liability, professional liability, and cyber coverage through disparate channels. This concentration is displacing fragmented single-line placements in Singapore and Hong Kong, where multinational headquarters prefer unified policy administration and cross-class aggregate limits.
Asia-Pacific Liability Insurance Market Segmentation
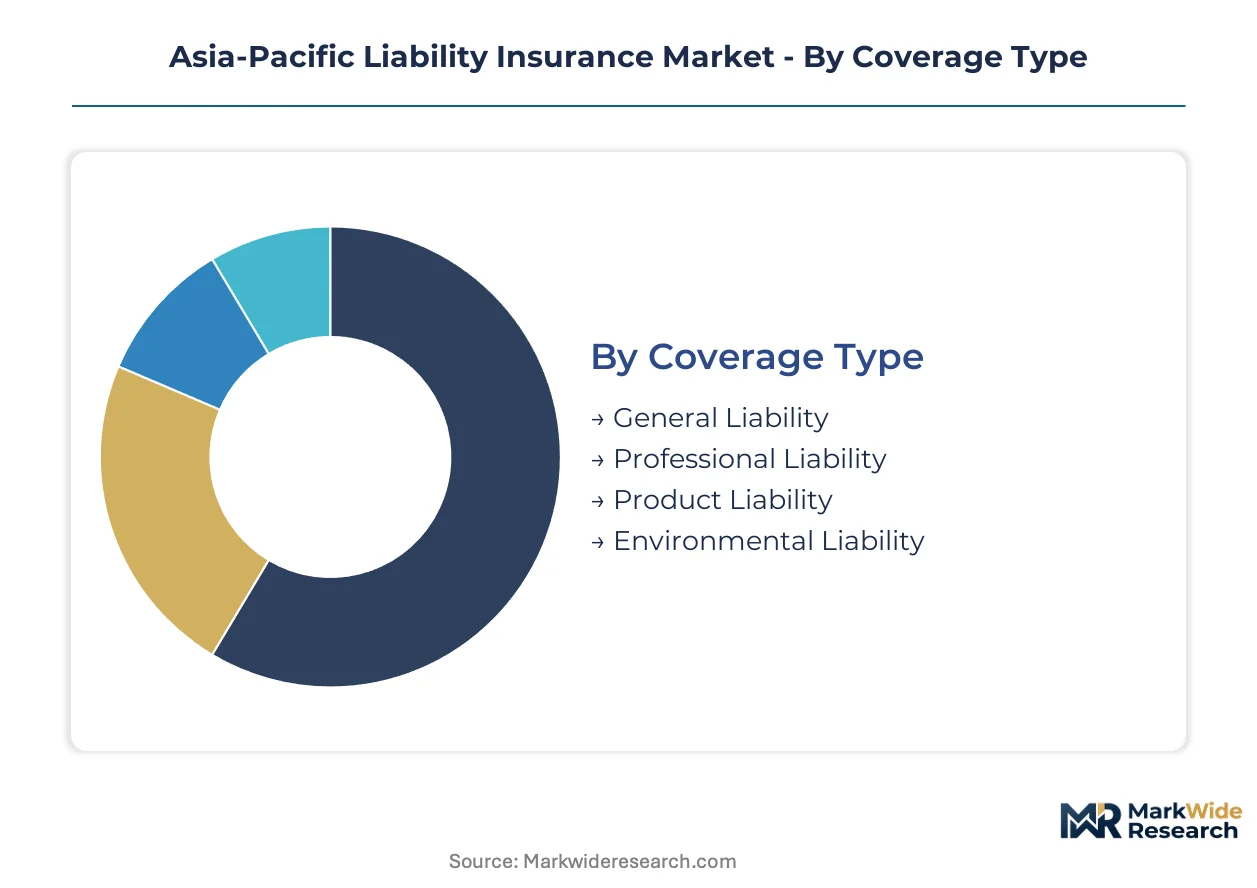
Liability insurance segmentation in Asia-Pacific reflects divergent renewal cycles and risk maturity across coverage lines. Policy structures and distribution channels vary dramatically in capital intensity and underwriting complexity across the region's fragmented regulatory landscape.
Coverage Type:
General liability policies renew annually with minimal friction, while environmental liability contracts extend across multi-year terms given the extended latency of contamination claims. Professional liability sits in the middle with 12-18 month cycles tied to professional licensing calendars.
- General Liability:Broad-spectrum coverage addressing bodily injury and property damage from business operations. Mandatory requirements across Australian construction and Vietnamese manufacturing pull premium volume, though rate adequacy pressure persists from long-tail asbestos exposure in legacy industrial zones.
- Professional Liability:Errors-and-omissions protection for consultants, advisors, and technical specialists. Singaporean fintech implementations and Indian IT service contracts are driving litigation frequency, compressing policy issuance timelines as carriers demand enhanced pre-bind risk assessments.
- Product Liability:Defective product exposure coverage with occurrence-based structures dominating Chinese manufacturing exports.
- Environmental Liability:Contamination and remediation cost protection with 5-10 year policy terms common in Australian mining and Indonesian palm oil operations.
General liability anchors the volume base while professional liability gains share at the steepest rate.
End User:
Premium per policy escalates across the customer size spectrum, with SMEs representing high-frequency low-severity placements and large enterprises demanding complex multi-jurisdictional towers.
- SMEs:Standardized coverage modules with limited customization and streamlined underwriting. Australia's mandated workers compensation requirements and Thailand's hospitality sector licensing drive penetration, though price sensitivity limits limit adequacy.
- Large Enterprises:Bespoke casualty programs with integrated general liability, D&O, and cyber towers. ASX-listed firms and Japanese trading houses negotiate multi-year arrangements with captive participation and regional aggregate limits.
- Public Sector:Statutory liability coverage for infrastructure authorities and municipal utilities with sovereign immunity considerations complicating placement structures.
- Non-Profit Organizations:Volunteer protection and directors liability with restricted premium pools and grant-funded purchasing constraints.
Large enterprises command the premium pool while SME penetration expands most quickly across Southeast Asian emerging markets.
Distribution Channel:
Commission structures and policy servicing costs vary substantially across intermediary types, with digital platforms compressing acquisition expense ratios below traditional broker arrangements.
- Brokers:Full-service placement and claims advocacy for complex commercial risks. International brokerage networks dominate Singapore and Hong Kong multinational placements, while domestic brokers control Indonesian and Philippine mid-market access.
- Direct Sales:Carrier-employed producers targeting large corporate accounts with captive relationship management. Ping An and Tokio Marine maintain substantial direct forces for key account retention.
- Online Platforms:API-enabled quotation and policy issuance for standardized SME coverage. India's IRDAI-mandated digital distribution protocols and Australian comparison site regulation are accelerating adoption.
- Agents:Tied representative arrangements with exclusive carrier appointments prevalent in rural Australian and Japanese regional markets.
Brokers retain the placement volume base while online platforms climb the fastest in policy count growth.
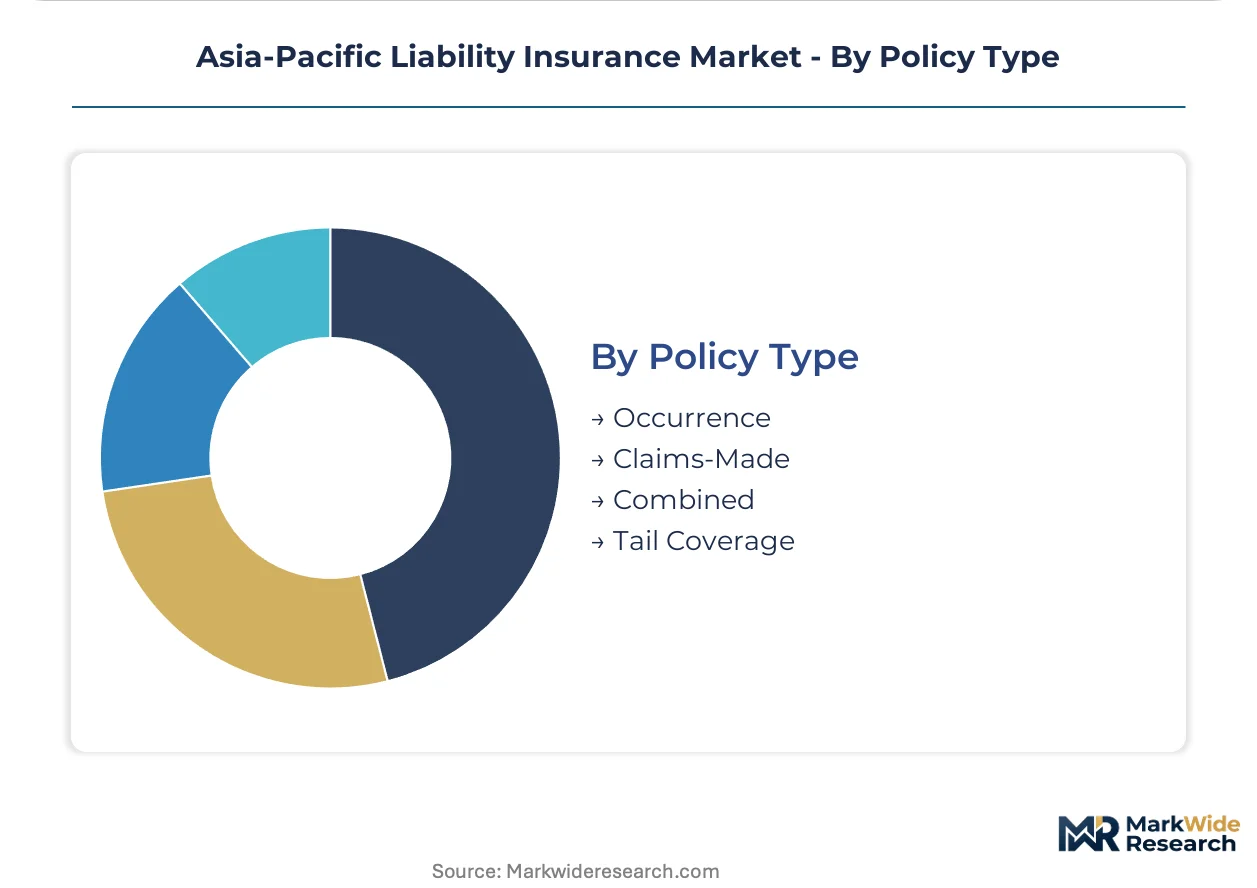
Policy Type:
Claims notification mechanics and premium recognition patterns differ fundamentally between occurrence and claims-made structures, with implications for reserve volatility and capital allocation.
- Occurrence:Event-triggered coverage with unlimited reporting latency and highest reserve uncertainty. Australian legacy manufacturing exposures and Chinese product export liability retain this structure despite pricing challenges.
- Claims-Made:Notification-triggered coverage with explicit retroactive dates dominating medical malpractice and legal professional lines. Singaporean law firms and Indian hospitals face mandatory claims-made requirements from their respective professional indemnity pools.
- Combined:Hybrid structures blending occurrence and claims-made elements for multi-line corporate programs seeking administrative simplification.
- Tail Coverage:Extended reporting endorsements for professional liability run-off, critical for retiring practitioners and dissolved firms in Japan's aging medical profession.
Occurrence structures anchor the premium base while claims-made formats expand most rapidly across professional service sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore's transshipment dominance anchors ASEAN liability demand, underwriting cross-border coverage flows that cascade through Southeast Asian manufacturing corridors and Australian resource extraction zones.
China
Eastern coastal manufacturing clusters in Jiangsu and Guangdong drive product liability exposure as export volumes climb. CBIRC mandates stricter solvency reporting for multi-line carriers underwriting industrial risks. Shenzhen's technology hardware concentration is pulling specialized E&O capacity from domestic underwriters.
Australia
APRA's tightened D&O disclosure requirements are compressing policy issuance timelines for ASX-listed mining and energy firms. Sydney and Melbourne headquarters dominate regional program purchasing for multinational towers. Legacy asbestos claims from Western Australian manufacturing continue distorting general liability reserve projections.
Japan
Tokio Marine anchors corporate demand through specialized manufacturing coverage tailored to automotive and electronics supply chains. METI guidelines on corporate governance disclosure are elevating D&O limit requirements for Nikkei-listed industrials. Osaka's precision engineering cluster maintains occurrence-based product liability structures despite regional shifts toward claims-made formats.
Singapore
The regional underwriting hub expansion is reshaping cross-border liability servicing for ASEAN multinational programs. MAS regulatory frameworks enable captive domiciliation that pulls premium volume from Indonesian and Vietnamese infrastructure projects. Raffles Place financial district concentration supports specialized fintech E&O capacity.
India
IRDAI-mandated digital distribution protocols are accelerating direct-to-consumer professional liability penetration among Bangalore IT services exporters. Mumbai's financial services corridor faces rising litigation frequency from securities advisory errors. Statutory liability mandates for infrastructure projects are pulling construction coverage volume from Delhi-NCR highway developments.
Asia-Pacific Liability Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower risk appetites. The market structures around three tiers: domestic champions with scale advantages, regional specialists with sector focus, and global carriers with multi-jurisdictional program capabilities. Strategic archetypes include balance-sheet-heavy underwriters prioritizing retention, reinsurance-dependent writers seeking distribution leverage, and hybrid platforms blending captive management with direct underwriting. Competitive moves concentrate on M&A for geographic footprint and strategic partnerships for technology-enabled risk assessment.
Among China-based scale underwriters, Ping An Insurance exemplifies domestic platform dominance through integrated financial services distribution. Tokio Marine & Nichido Fire Insurance Co. Ltd. represents the specialized manufacturing coverage archetype anchoring Japanese corporate demand. QBE Insurance Group occupies a position bridging Australasian brokerage relationships into emerging Asian markets, sitting within the regional expansion specialist tier.
| Leading Market Players |
|---|
| Ping An Insurance |
| Tokio Marine & Nichido Fire Insurance Co. Ltd. |
| QBE Insurance Group |
| Axa Group |
| Allianz Group |
| AIA Group |
| China Life Insurance |
| Chubb Limited |
| People's Insurance Company of China |
| Others |
Value Network & Pricing Analysis
Singapore's Raffles Place underwriting hub concentration feeds capacity scarcity dynamics that elevate premium adequacy for cross-border ASEAN programs. Lloyd's syndicate retrenchment from Asia-Pacific casualty treaties has compressed supply-side leverage into domestic balance sheets, forcing regional carriers to restructure retroactive date conventions and attachment point pricing.
Pricing Analysis
Volume-discount tiering separates large enterprise multi-line placements from SME standardized modules. Premium-mid-economy pricing differentiation rests on claims history granularity and captive participation depth. Cost compression in the SME tier is intensifying because IRDAI-mandated digital distribution protocols compress acquisition expense ratios below traditional broker arrangements. Price sensitivity concentrates among Philippine BPO firms and Vietnamese manufacturing risks, while ASX-listed mining entities demonstrate inelastic demand for climate liability endorsements.
Supply Chain Analysis
Tariff exposure between Lloyd's London and Singapore treaty markets dominates reinsurance capacity allocation decisions. Capacity feeds from Australian domestic balance sheets, Japanese non-life specialists, and Chinese state-backed carriers. Retrocession dependencies on Bermuda and European markets create single-source vulnerability for catastrophe aggregate covers. Distribution runs through international brokerage networks for multinational towers, with domestic brokers controlling Indonesian and Philippine mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Claims-made policy administration and run-off management services attach more durably to underlying liability placements than traditional occurrence-based structures, creating recurring-revenue streams that outpace premium growth in the base coverage layer.
For Market Incumbents: Build captive management capabilities as the defensive moat against reinsurance-dependent writers seeking distribution leverage. Deepen backward integration into telematics-enabled underwriting workflows to offset actuarial talent scarcity. Secure exclusive relationships with Australian APRA-licensed entities facing compressed D&O issuance timelines. For New Entrants and Emerging Players: Establish a beachhead in Philippine professional liability among Manila-based BPO firms where penetration trails regional benchmarks. Target cyber liability bundling opportunities in Thai manufacturing risks seeking parametric natural catastrophe triggers. Lead with API-enabled quotation infrastructure to bypass entrenched broker relationships in India's IRDAI-regulated digital distribution corridor. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among balance-sheet-heavy underwriters with integrated captive management platforms. Long-term viability favors carriers with proprietary risk assessment technology embedded in policy administration systems. Monitor climate litigation precedent volume in Australian courts as the inflection signal for D&O limit adequacy re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Cyber Liability Bundling | Converges network security protocols with E&O structures for fintech vendors in Singapore. |
| Parametric Trigger Development | Replaces lengthy claims adjustment with index-based payouts for Thai agricultural cooperatives. |
| Captive Domiciliation Expansion | Leverages MAS regulatory frameworks to pull premium from Indonesian infrastructure projects. |
| Climate Risk Disclosure Integration | Addresses APRA mandates requiring ASX-listed boards to document governance frameworks. |
| Digital Distribution Infrastructure | Compresses policy issuance cycles through IRDAI-mandated protocols for Indian SME penetration. |
Research Methodology
Two parallel data streams informed the analysis: structured dialogues with underwriting executives, actuarial directors, and broker placement specialists; and secondary validation through APRA solvency filings, CBIRC product registration databases, IRDAI distribution reports, and Lloyd's market returns. Bottom-up premium volume estimates triangulated against top-down regulatory aggregate disclosures.
Forecast inputs incorporated coverage line segmentation by policy structure, end-user size tier, and distribution channel complexity across the projection horizon. CAGRs derived from historical loss-ratio trends, regulatory mandate implementation schedules, and reinsurance capacity cycle positioning. Modeled variables included professional liability litigation frequency in Indian IT services, climate disclosure enforcement intensity in Australian courts, and digital adoption curves in Southeast Asian SME markets.
Sensitivities concentrate around reinsurance treaty renewal terms, regulatory filing requirement harmonization failures, and climate litigation precedent acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Property and Casualty Insurance Market
Insurance
Aerial Imaging in Insurance Service Market
Insurance
Europe Health Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Boiler Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Insurance Aggregators Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Parametric Insurance Market
Insurance
Jewelry Insurance Market
Insurance
EV Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
United States Bancassurance Market
Insurance
Green Insurance Market
Insurance
Europe Mobile Phone Insurance Market