
 Germany Reinsurance Market | 2026-2036
Germany Reinsurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Reinsurance Market Insights
Parametric and software-defined risk transfer layers are pivoting how reinsurance contracts are priced and settled in Germany. Munich Re leverages its proprietary catastrophe modeling platforms to dominate nat-cat treaty placements. Hannover Rückversicherung SE anchors its competitive position through deep specialization in marine and aviation reinsurance. General Re AG differentiates via long-tail casualty expertise and direct relationships with mid-sized German insurers.
Reinsurance is a risk transfer mechanism where a primary insurer cedes portions of its underwriting exposure to a specialized counterparty, governed by contractual attachment points, coverage limits, and loss-sharing ratios calibrated to the cedent's risk appetite and capital structure. Its commercial purpose is to stabilize insurer balance sheets, expand underwriting capacity, and optimize regulatory capital under risk-based frameworks. Treaty reinsurance commands the deepest margin pools in Germany due to multi-year relationships and embedded servicing fees, while facultative reinsurance occupies a faster-growing niche for complex, non-standard risks outside treaty scopes. Life reinsurance remains structurally mature with limited new entrant activity.
BaFin enforces Solvency II capital requirements that directly shape reinsurance demand by mandating risk-mitigation credit for qualifying cessions. The German Insurance Supervision Act and EIOPA technical standards further constrain product design and reporting granularity for cross-border reinsurance arrangements. German carriers must also navigate GDPR protocols when transferring policy-level data to reinsurance analytics platforms. Stakeholders should monitor how the EU's evolving climate stress-test regime for insurers will recalibrate attachment points and pricing models for property catastrophe covers.
Market Dynamics
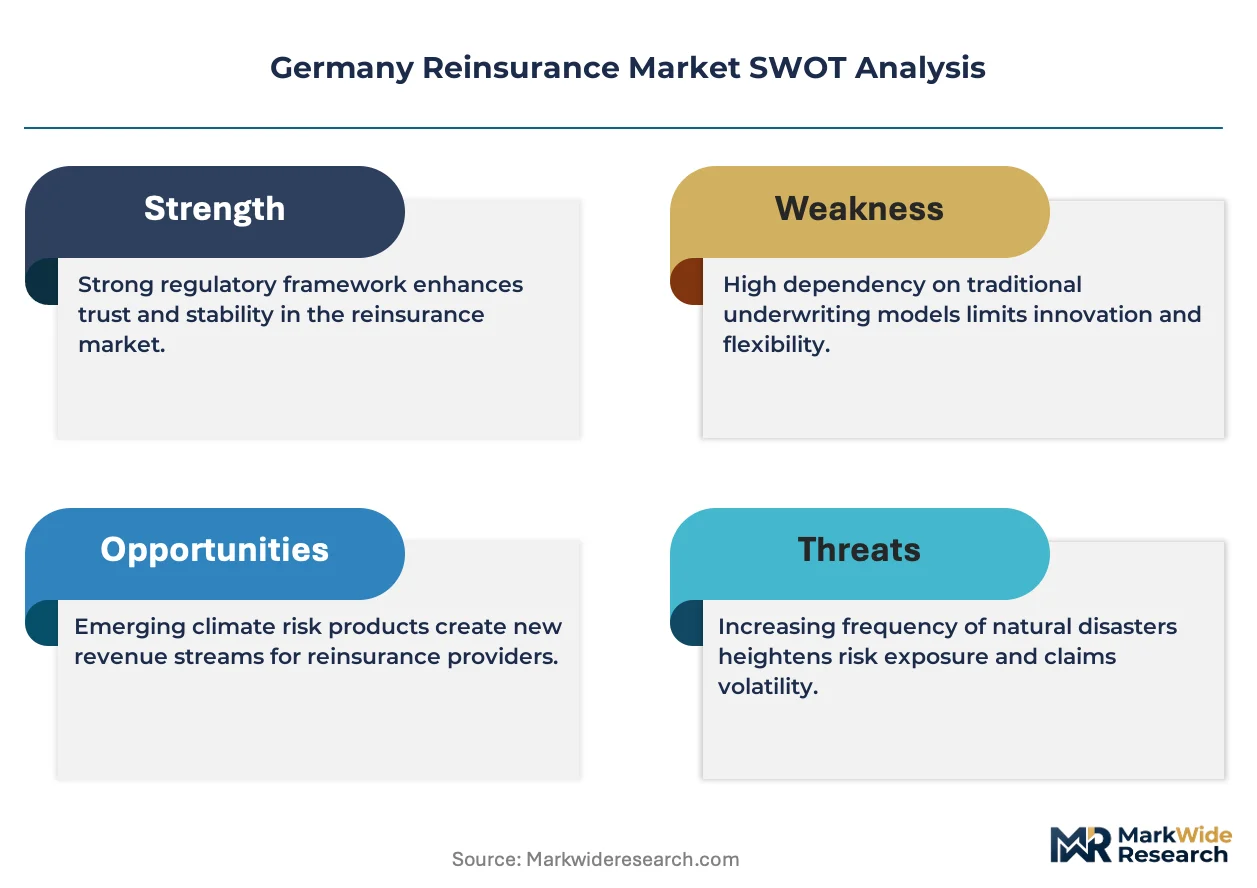
BaFin's tightening Solvency II capital adequacy rules are forcing German primary insurers to recalibrate their risk transfer strategies, driving concentrated demand toward multi-year treaty structures that optimize regulatory capital relief.
Growth Catalysts
- EIOPA Climate Stress-Testing:Mandatory scenario analysis for physical risk exposures is compelling German property insurers to expand catastrophe reinsurance coverages.
- Parametric Trigger Mechanisms:Satellite-indexed settlement protocols are accelerating claims resolution for flood and storm losses across Bavaria and North Rhine-Westphalia.
- Mid-Sized Cedent Consolidation:Regional mutual insurers in Baden-Württemberg are pooling capacity to access treaty markets previously reserved for national carriers.
Market Restraints
- Retrocession Capacity Squeeze:Bermudian and London market providers have tightened collateral terms for German peak perils, compressing available protection layers.
- GDPR Data Friction:Cross-border policy-level data transfers to catastrophe modeling platforms face consent and anonymization hurdles under German federal data protection enforcement.
- Long-Tail Asbestos Reserves:Legacy casualty exposures from industrial liability policies written in the 1980s continue draining capital from domestic reinsurance balance sheets.
Strategic Opportunities
- Embedded Insurance Partnerships:Automotive OEMs in Stuttgart and Munich are integrating parametric motor reinsurance into connected vehicle platforms.
- Green Bond-Linked Covers:EU Green Deal taxonomy alignment is opening preferential capital treatment for renewable energy project reinsurance.
- AI-Assisted Underwriting Convergence:Machine learning risk scoring combined with traditional actuarial methods is reducing quote-to-bind cycles for commercial property treaties.
Industry Challenges
- Catastrophe Modeler Talent Gap:German actuarial programs produce insufficient specialists in nat-cat simulation software, forcing carriers to recruit from Swiss and UK labor pools.
- Legacy IT Integration Burden:Core policy administration systems at established cedents resist API connectivity with modern reinsurance placement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Reinsurance Market |
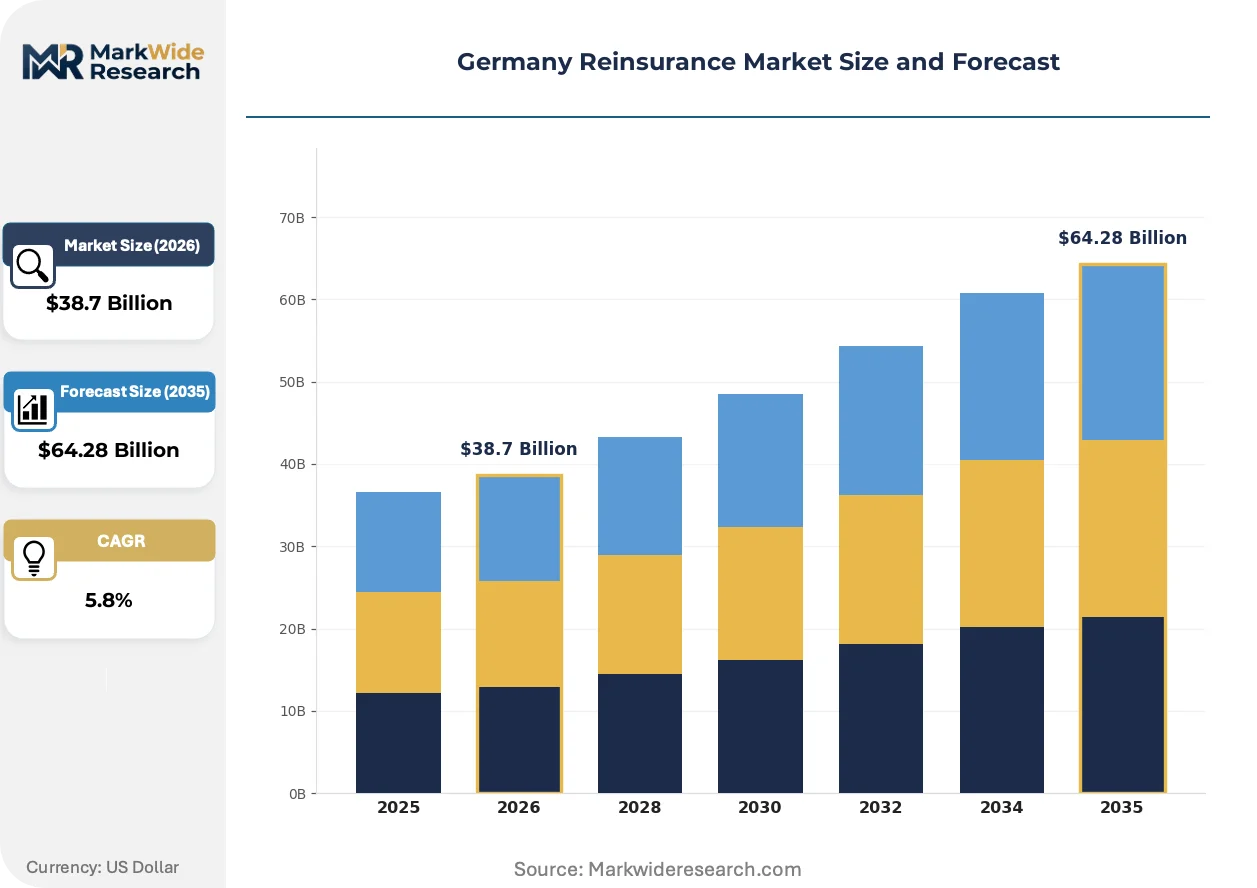
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Reinsurance, Property Reinsurance, Casualty Reinsurance, Health Reinsurance End User: Insurance Companies, Corporations, Government Entities, Financial Institutions Service Type: Facultative Reinsurance, Treaty Reinsurance, Excess of Loss Reinsurance, Quota Share Reinsurance Distribution Channel: Brokers, Direct Sales, Reinsurance Companies, Online Platforms |
| Companies Covered | Munich Re, Hannover Rückversicherung SE, General Re AG, R+V Versicherung AG, E+S Rückversicherung AG, SCOR SE, Deutsche Rückversicherung AG, DEVK Re, Allianz SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Reinsurance Market Trends and Innovations
Software-defined risk transfer is compressing traditional reinsurance placement timelines, with algorithmic pricing engines and blockchain settlement layers restructuring how German carriers access capacity.
Parametric index triggers tied to satellite-derived flood depth measurements are overtaking traditional indemnity structures for German commercial property programs. Mid-sized industrial insurers in the Rhine-Ruhr corridor are adopting these instruments to eliminate loss adjustment disputes. The shift is compressing settlement cycles from months to days while ceding basis risk to specialized ILS funds.
BaFin's implementation of EIOPA technical standards for climate risk disclosure is mandating granular exposure reporting for property catastrophe portfolios. German insurers must now submit spatially-resolved flood and storm footprint data as part of supervisory review processes. The regulation is accelerating investment in geospatial analytics infrastructure across Frankfurt and Munich underwriting hubs.
Primary carriers are unbundling facultative placement from bundled broker arrangements, establishing direct digital channels to reinsurance underwriters for complex industrial risks. This disintermediation is most visible among energy sector cedents in Lower Saxony seeking bespoke offshore wind coverage. The model reduces placement fees but demands enhanced in-house technical underwriting capabilities.
Germany Reinsurance Market Segmentation
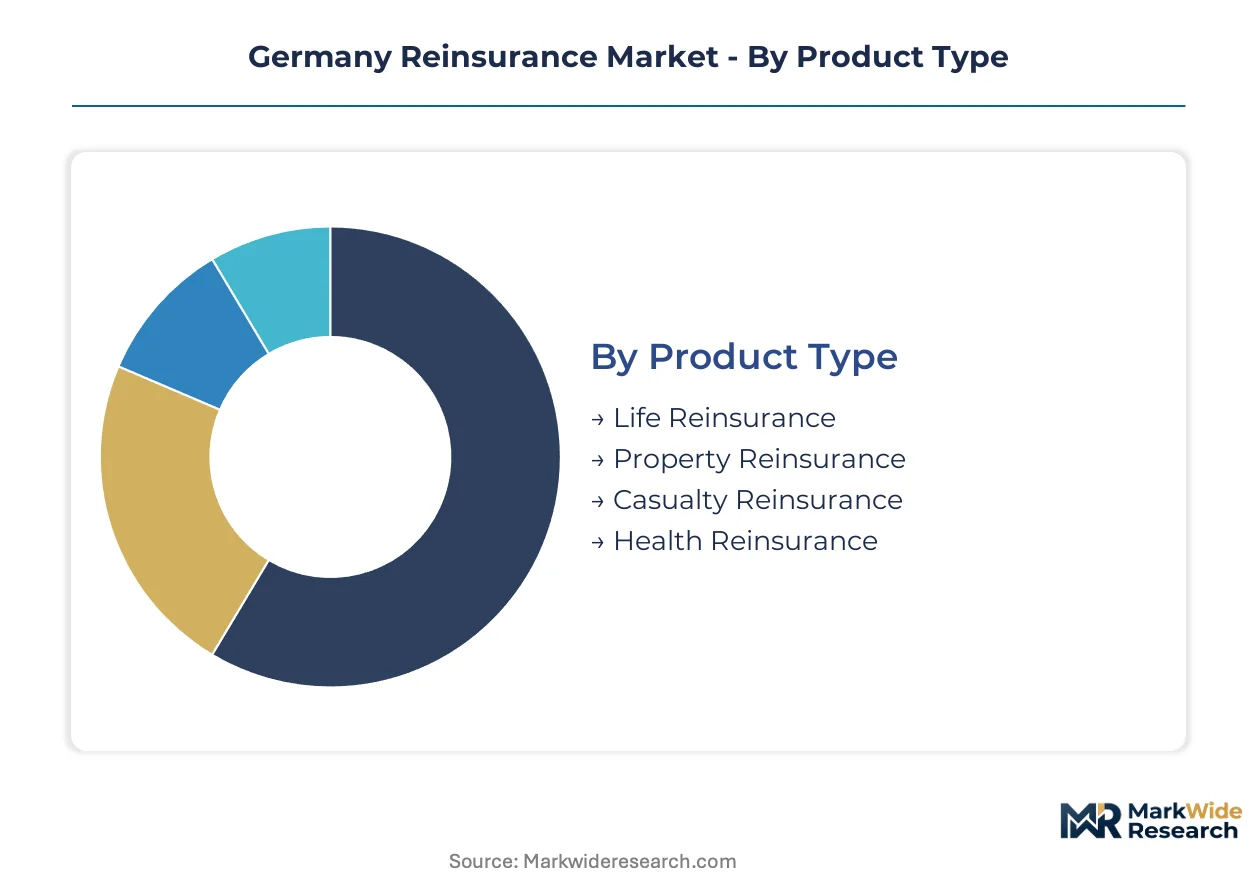
Reinsurance segmentation in Germany reflects divergent capital requirements across product lines and the structural divide between treaty-based relationships and facultative placements. Understanding these axes clarifies where BaFin's Solvency II framework creates differentiated demand pressures and margin pools.
Product Type:
Risk transfer mechanisms vary sharply in capital intensity and duration, with property and life occupying opposite ends of the maturity spectrum.
- Life Reinsurance:Long-duration mortality and longevity risk transfer dominates balance sheet optimization for annuity writers. German life insurers cede blocks to manage Solvency II liability valuation volatility, with demand concentrated among established mutual carriers in Bavaria facing demographic stress on guaranteed products.
- Property Reinsurance:Nat-cat exposure aggregation drives the most active pricing cycles, with flood and storm covers commanding premium attachment point negotiations. Climate stress-testing mandates from EIOPA are accelerating demand for multi-year treaty structures among primary carriers in North Rhine-Westphalia.
- Casualty Reinsurance:Long-tail industrial liability reserves drain capital from domestic reinsurers.
- Health Reinsurance:Supplementary medical coverage cessions remain structurally limited in Germany's statutory-dominant system.
Mature deployment sits with Life Reinsurance. Newer deployment is concentrated in Property Reinsurance.
End User:
Customer archetypes determine contract complexity, with insurance companies driving standardized treaty economics and corporations demanding bespoke structures.
- Insurance Companies:Primary carriers cede peak peril concentrations to optimize regulatory capital ratios under BaFin supervision. Treaty renewals in Frankfurt and Munich underwriting hubs anchor the deepest volume pools and longest relationship tenures.
- Corporations:Large industrial groups in the Rhine-Ruhr corridor access captive reinsurance vehicles for non-traditional risk transfer, particularly for supply chain interruption and cyber exposure aggregation.
- Government Entities:Public sector risk pools seek pandemic and terrorism coverage extensions.
- Financial Institutions:Banks cede credit risk through financial guarantee reinsurance structures.
Established relationships concentrate with Insurance Companies. Emerging demand patterns are visible among Corporations.
Service Type:
Contract architecture determines settlement speed, basis risk allocation, and the feasibility of parametric trigger integration.
- Treaty Reinsurance:Multi-year automatic coverage agreements govern the bulk of German cession volume, with predefined capacity commitments eliminating placement friction for standard risks. Embedded servicing fees and relationship economics create durable margin structures.
- Facultative Reinsurance:Risk-by-risk negotiation addresses non-standard exposures outside treaty scopes, with energy sector cedents in Lower Saxony driving disintermediation toward direct digital placement channels.
- Excess of Loss Reinsurance:Catastrophe layer protection attaches above primary retention thresholds.
- Quota Share Reinsurance:Proportional participation agreements distribute premium and loss symmetrically.
Volume concentration favors Treaty Reinsurance. Fastest technology adoption appears in Facultative Reinsurance.
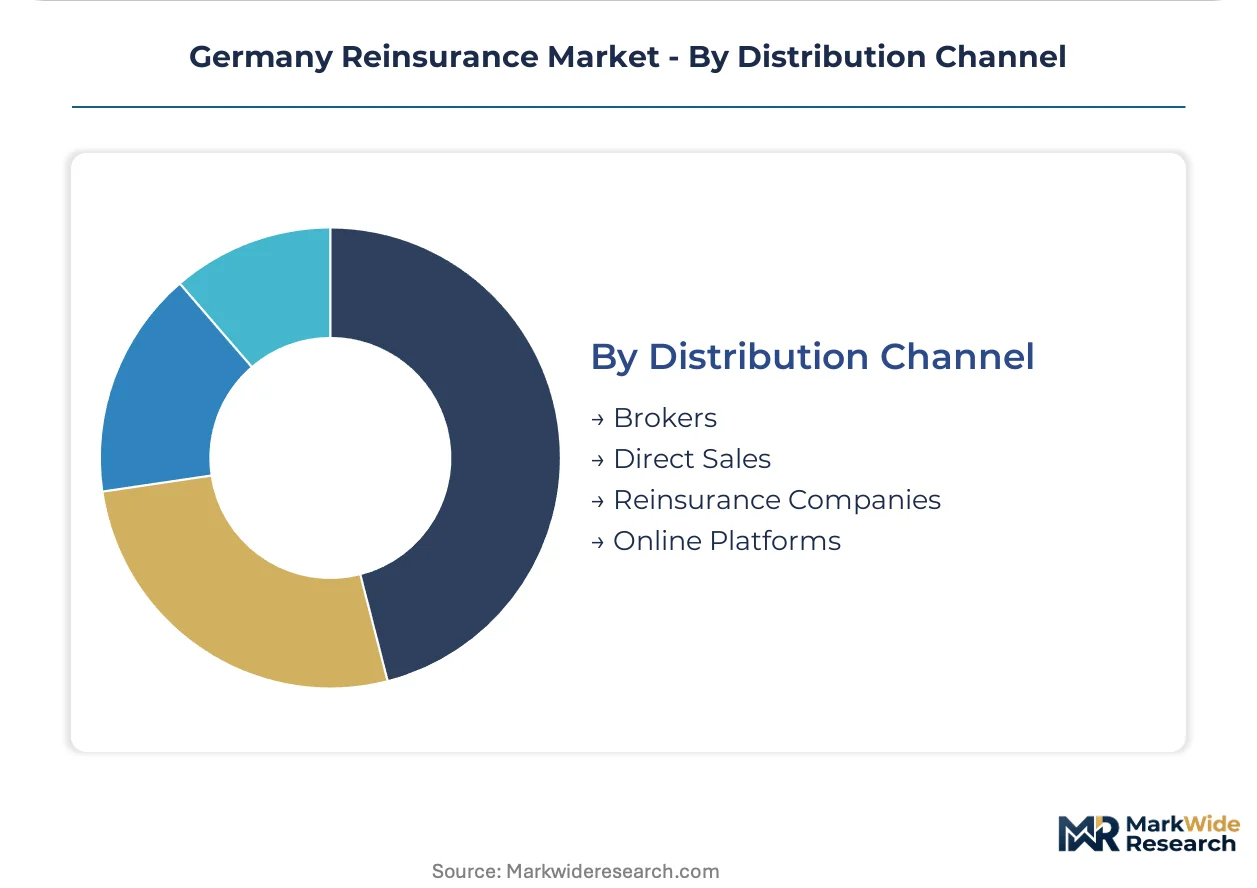
Distribution Channel:
Channel selection reflects risk complexity and the cedent's in-house technical underwriting capabilities.
- Brokers:Lloyd's coverholders and continental intermediaries dominate complex international placements, particularly for German carriers accessing London and Bermuda capacity for peak peril protections.
- Direct Sales:Established relationships between Munich-based reinsurers and mid-sized primary carriers bypass intermediary economics for treaty renewals.
- Reinsurance Companies:Captive and affiliated vehicles handle intra-group cessions.
- Online Platforms:Algorithmic placement interfaces gain traction for standardized facultative risks.
Traditional placement runs through Brokers. Digital migration is advancing fastest via Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes the bulk of reinsurance capacity generated within its borders, though treaty placements increasingly draw collateral from London and Bermuda markets. The production-consumption gap widens for peak peril protections, forcing domestic carriers to access international retrocession layers.
North Rhine-Westphalia
Industrial property concentration in the Rhine-Ruhr corridor drives nat-cat reinsurance demand as flood exposure accumulates along the Rhine basin. BaFin's Solvency II climate stress-testing mandates compel Düsseldorf-based carriers to expand catastrophe treaty coverages. Cologne and Essen host the densest clusters of primary insurer headquarters seeking multi-year capacity commitments.
Bavaria
Life reinsurance cessions dominate as Munich-based mutual carriers manage demographic stress on guaranteed annuity products. The German Insurance Supervision Act shapes liability valuation requirements for longevity risk transfer. Munich anchors the deepest concentration of reinsurer headquarters, with treaty negotiations concentrated in the Maxvorstadt financial district.
Baden-Württemberg
Regional mutual insurers pool capacity to access treaty markets previously reserved for national carriers, driven by Stuttgart's automotive supply chain risk aggregation. EIOPA technical standards for climate disclosure reshape property portfolio reporting. Karlsruhe and Mannheim host emerging direct digital placement channels for facultative energy risks.
Lower Saxony
Offshore wind project development in the North Sea drives bespoke facultative demand for energy sector cedents. GDPR protocols constrain cross-border data transfers to catastrophe modeling platforms serving Hanover-based underwriters. Wolfsburg automotive clusters integrate parametric motor reinsurance into connected vehicle platforms.
Hesse
Frankfurt's banking sector cedes credit risk through financial guarantee reinsurance structures, complementing traditional property-casualty flows. BaFin enforcement of risk-mitigation credit rules accelerates structured reinsurance adoption among investment-heavy insurers. The Mainhattan financial district concentrates broker relationships linking German cedents to London capacity.
Germany Reinsurance Market Competitive Landscape
Top-tier vendors anchor treaty capacity provision, while mid-tier specialists carve niches in facultative and long-tail casualty segments. The German market exhibits concentrated hierarchy with three dominant domestic carriers controlling automatic coverage placements. Strategic archetypes separate catastrophe modelers leveraging proprietary platforms, marine-aviation specialists, and long-tail casualty underwriters. Competitive moves concentrate on portfolio diversification into parametric structures and direct digital channel establishment bypassing traditional broker economics.
Among Munich-based reinsurance groups, Munich Re and General Re AG exemplify distinct archetype positioning within the tiered vendor structure. Hannover Rückversicherung SE anchors the specialist tier through geographic concentration in northern Germany. These three entities represent the dominant competitive anchors shaping treaty renewal negotiations and capacity allocation across German primary carrier segments.
| Leading Market Players |
|---|
| Munich Re |
| Hannover Rückversicherung SE |
| General Re AG |
| R+V Versicherung AG |
| E+S Rückversicherung AG |
| SCOR SE |
| Deutsche Rückversicherung AG |
| DEVK Re |
| Allianz SE |
| Others |
Pricing and Supply Chain Analysis
Mid-sized primary carriers in North Rhine-Westphalia anchor German reinsurance demand, concentrating purchasing power around multi-year treaty structures that embed servicing fees and automatic capacity commitments. This buyer archetype's preference for relationship-based pricing over transactional placement shapes how Munich and Hannover underwriters structure margin pools and renewal economics.
Pricing Analysis
Margin tightening in treaty layers reflects retrocession capacity squeezes from Bermudian and London markets, compressing available protection for German peak perils. Pricing stratifies across premium catastrophe covers, standard property treaties, and economy facultative placements, with differentiation driven by attachment point granularity and loss adjustment expense loadings. Cost-down pressure on facultative placements accelerates as primary carriers build direct digital channels, bypassing broker economics. Regional mutual insurers in Baden-Württemberg exhibit highest price sensitivity due to pooled capacity constraints, while national carriers in Frankfurt prioritize relationship stability over rate competition.
Supply Chain Analysis
Dual-sourcing requirements from BaFin-supervised cedents mandate multi-reinsurer qualification for peak peril protections, preventing single-carrier dependency in nat-cat layers. Capacity concentrates in Germany, Bermuda, and London, with collateral terms tightening for German flood and storm exposures. Retrocession capacity draws from ILS funds, traditional European carriers, and Lloyd's syndicates, resting on satellite-derived risk models and proprietary catastrophe platforms. Single-source vulnerability sits with Munich Re's dominance in nat-cat treaty modeling. Distribution runs through broker networks for complex international placements, while direct channels gain share in treaty renewals between established domestic relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German reinsurance is consolidating around vertical-integration races into proprietary risk analytics and captive retrocession structures, with players pursuing upstream control over catastrophe modeling capabilities as the decisive lever.
For Market Incumbents: Anticipate disintermediation pressure from direct digital placement platforms by deepening proprietary catastrophe modeling investments and locking multi-year treaty relationships through embedded servicing fee structures. Defend against parametric ILS fund encroachment on peak peril layers by acquiring satellite analytics specialists or licensing exclusive index-trigger datasets. Prioritize backward integration into climate risk data infrastructure over capacity expansion alone. For New Entrants and Emerging Players: The premium-economy price-point gap in facultative energy reinsurance creates entry space for algorithmic underwriters targeting Lower Saxony offshore wind projects with rapid quote-to-bind capabilities. White-space concentrates in parametric flood covers for Bavarian commercial property outside traditional treaty scopes. Establish credibility through BaFin regulatory sandbox participation before scaling to national carrier panels. For Investors and Strategic Acquirers: The window for entry favors catastrophe modeling software specialists with EIOPA climate stress-testing compliance and existing German cedent relationships. Long-term viability hinges on regulatory data infrastructure rather than pure capacity provision. Watch for inflection in BaFin's implementation of EU-wide climate disclosure standards as the signal for accelerated geospatial analytics consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Catastrophe Modeling Investment | Munich Re's dominance in nat-cat treaty placements rests on exclusive flood simulation platforms. |
| Parametric Trigger Product Development | Satellite-indexed settlement protocols compress claims cycles from months to days for Rhine-Ruhr industrial cedents. |
| Direct Digital Channel Establishment | Disintermediation of broker economics reduces placement fees for energy sector facultative covers in Lower Saxony. |
| Climate Risk Data Infrastructure Acquisition | BaFin's EIOPA disclosure mandates force granular geospatial exposure reporting across Frankfurt underwriting hubs. |
| Multi-Year Treaty Relationship Lock-In | Embedded servicing fees create durable margin structures resistant to annual price competition. |
Research Methodology
Multi-period observation of treaty renewal pricing, facultative placement velocity, and regulatory capital relief utilization anchored the trend analysis, supplemented by interviews with chief reinsurance officers, treaty underwriters at Munich and Hannover headquarters, BaFin supervisory staff, and catastrophe modeler technical leads. Secondary validation drew from BaFin solvency reports, EIOPA technical standards documentation, Lloyd's market filings, and reinsurance broker placement data. Bottom-up segmentation modeling triangulated against top-down market sizing from primary carrier cession disclosures.
Segment-weighting across product type, end user archetype, service architecture, and distribution channel shaped the analytical framework, with granularity on climate stress-testing compliance status as an additional dimension. CAGRs were derived from trend extrapolation of treaty renewal economics and facultative digitization rates, calibrated to Solvency II capital requirement trajectories and retrocession capacity availability indicators across the projection horizon.
Inputs from BaFin supervisory disclosures and EIOPA climate risk databases were available through the study window; gaps in proprietary catastrophe modeler pricing granularity introduce uncertainty bands around nat-cat treaty forecasts. Deviation in Bermudian retrocession collateral terms or EIOPA stress-testing implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Trade Credit Insurance Market
Insurance
Usage-Based Insurance (UBI) Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Global Long Term Care Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Digital Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Global Property and Casualty Reinsurance Market
Insurance
Middle East Business Income Insurance Market
Insurance
Income Protection Insurance Market
Insurance
Financial Protection Market
Insurance
Art Insurance Market