
 Auto Extended Warranty Market | 2026-2036
Auto Extended Warranty Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Extended Warranty Market Analysis
The EPA's tightened emissions enforcement is decoupling warranty liability from traditional mechanical failure models. Endurance leverages direct-to-consumer digital channels to sustain pricing transparency across state-level insurance regulations. CarShield anchors its growth through aggressive national advertising that competes for mass-market used-vehicle owners. Zurich differentiates with captive finance integration through major automotive OEM partnerships, occupying the premium tier of manufacturer-backed coverage.
An auto extended warranty constitutes a service contract that indemnifies vehicle owners against defined mechanical or electrical failures beyond the manufacturer's original coverage period, typically spanning powertrain components, electrical systems, and increasingly software-dependent subsystems. These contracts transfer repair cost risk from owners to underwriters, functioning as a financial hedge against post-warranty vehicle degradation. Powertrain coverage dominates transaction volume due to lower claims frequency and predictable cost structures, while comprehensive plans capture disproportionate margin pools from risk-averse luxury vehicle owners. Third-party providers lead policy issuance across online platforms, though manufacturer-backed contracts command higher per-unit premiums through dealership channel control.
The National Association of Insurance Commissioners coordinates state-level warranty regulatory frameworks that govern reserve requirements and claims handling standards, while the Consumer Financial Protection Bureau monitors dealer-finance packaging practices that embed warranty products into auto loans. The Federal Trade Commission's Used Car Rule mandates disclosure protocols that shape how warranty terms are presented at point of sale. Stakeholders must monitor evolving EV battery degradation coverage definitions as these powertrain components lack established failure curves and repair cost benchmarks.
Market Dynamics
The EPA's tightened emissions enforcement is decoupling warranty liability from traditional mechanical failure models. Powertrain complexity from electrification and software-dependent subsystems is forcing underwriters to rebuild actuarial frameworks around battery degradation curves and thermal management failures.
Growth Catalysts
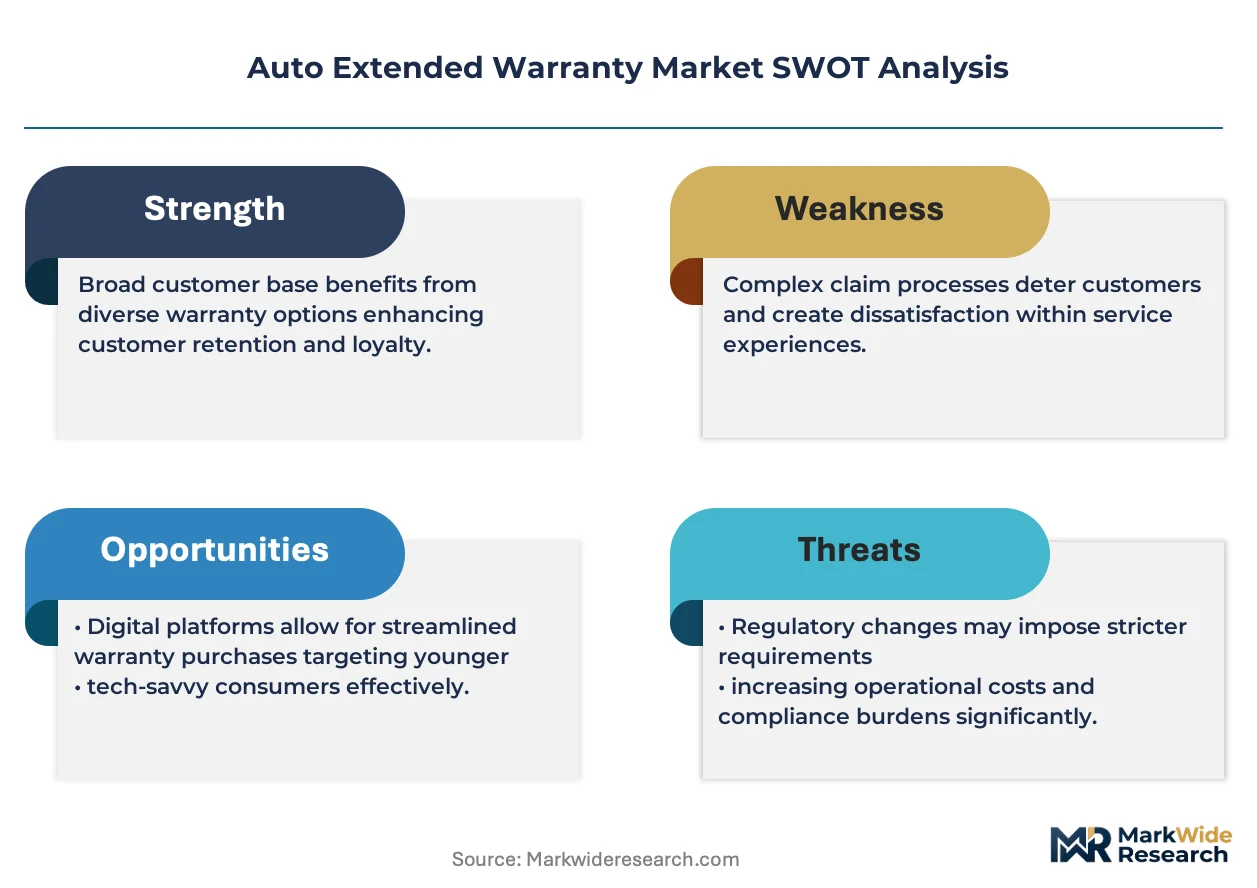
- Fleet Operator Demand:Commercial vehicle uptime protection has become critical for logistics and delivery operators managing total cost of ownership across electric and diesel powertrains.
- Used-Vehicle Penetration:Secondary market buyers in the United States seek coverage for post-warranty vehicles as average vehicle age extends beyond manufacturer protection periods.
- EV Powertrain Complexity:Battery thermal management and inverter systems create repair cost uncertainty that drives contract uptake among risk-averse owners.
Market Restraints
- Input Cost Volatility:Semiconductor and lithium-ion battery pricing instability compresses underwriter margins on comprehensive coverage plans.
- Regulatory Fragmentation:State-level insurance reserve requirements governed by the National Association of Insurance Commissioners create compliance overhead for multi-state providers.
- Technical Limitation:Absence of established failure curves for solid-state batteries and silicon carbide inverters prevents accurate premium pricing.
Strategic Opportunities
- Telematics Integration:Real-time vehicle health monitoring enables dynamic pricing models and predictive maintenance bundling.
- Subscription Channel Expansion:Direct-to-consumer digital platforms bypass dealership markups and capture margin from price-sensitive used-vehicle buyers.
- Commercial Fleet Tailwinds:California's Advanced Clean Trucks regulation accelerates electric fleet adoption and associated uptime protection demand.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of specialists capable of modeling EV battery degradation and software failure probabilities.
- Integration Complexity:Legacy claims management systems require reconfiguration to handle over-the-air diagnostic data and remote repair authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Extended Warranty Market |
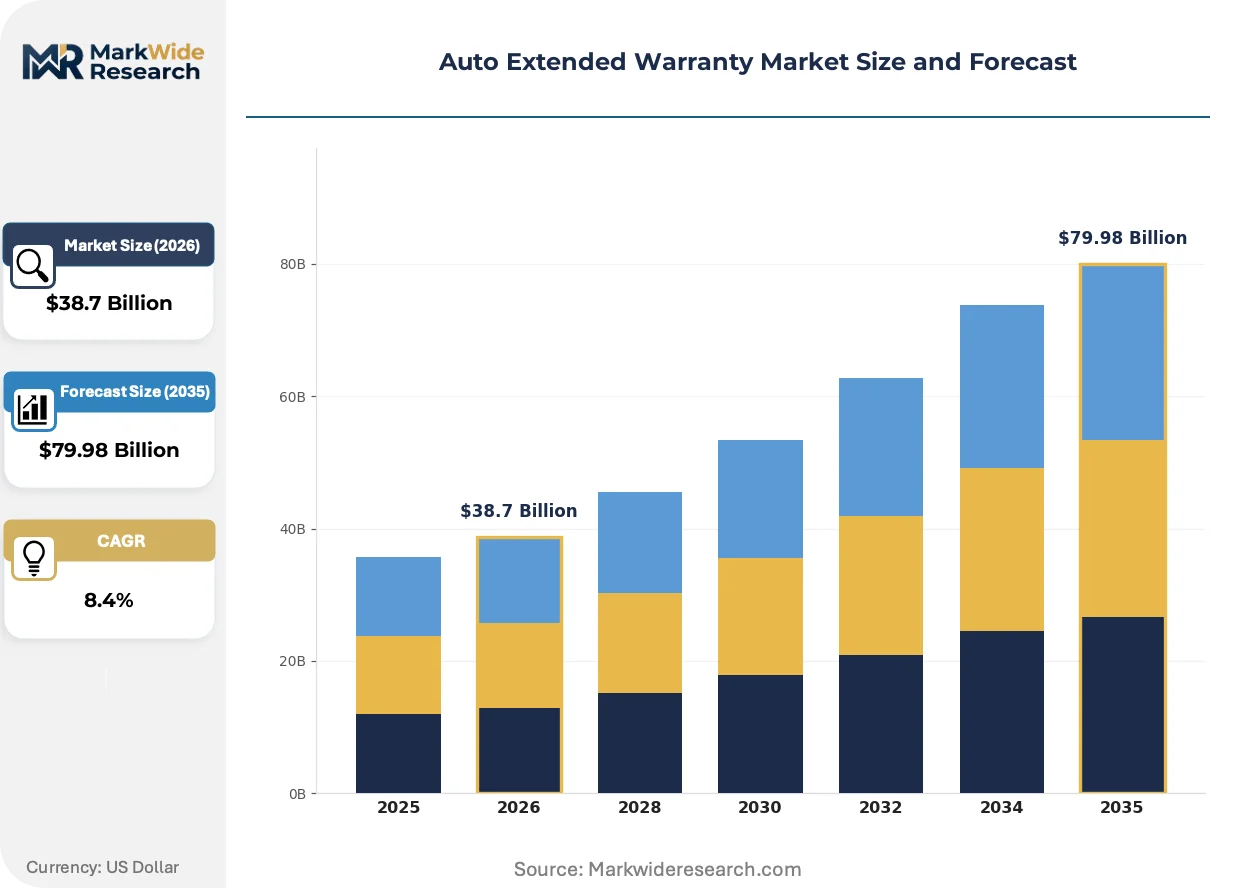
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Powertrain, Comprehensive, Exclusionary, Component Provider Type: Third-Party, Manufacturer, Dealership, Online Platform Contract Length: Short-Term, Mid-Term, Long-Term, Customizable Customer Segment: Individual Owners, Fleet Operators, Dealerships, Corporates |
| Companies Covered | Toco Warranty, Premier Auto Protect, Endurance, Omega Auto Care, Olive, CarShield, American Dream Auto Protect, Zurich, Carchex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Extended Warranty Market Emerging Trajectories
Digital distribution channels are compressing traditional dealership gatekeeper roles while telematics-enabled usage-based contracts reshape risk transfer mechanics. Underwriters now compete on data integration speed rather than captive finance relationships alone.
Blockchain-based smart contracts are decentralizing claims verification and payment execution across distributed ledger networks. Fleet operators and commercial buyers pilot automated indemnity triggers tied to telematics-reported component failures. This architecture eliminates adjuster lag and compresses dispute resolution cycles from weeks to hours.
The EPA's tightened emissions enforcement is forcing coverage definitions to incorporate catalytic converter theft and aftertreatment system failures. Underwriters must price regional theft patterns and diesel particulate filter replacement costs into comprehensive plans. California and Texas markets exhibit the steepest adjustment curves as enforcement intensity varies by state.
After-sales service unbundling is fragmenting the traditional dealer-captive warranty bundle. Independent repair networks and mobile technician platforms capture maintenance volume previously reserved for franchised service departments. This shift concentrates fastest in metropolitan United States markets where consumer price transparency tools erode dealership markup power.
Auto Extended Warranty Market Segmentation
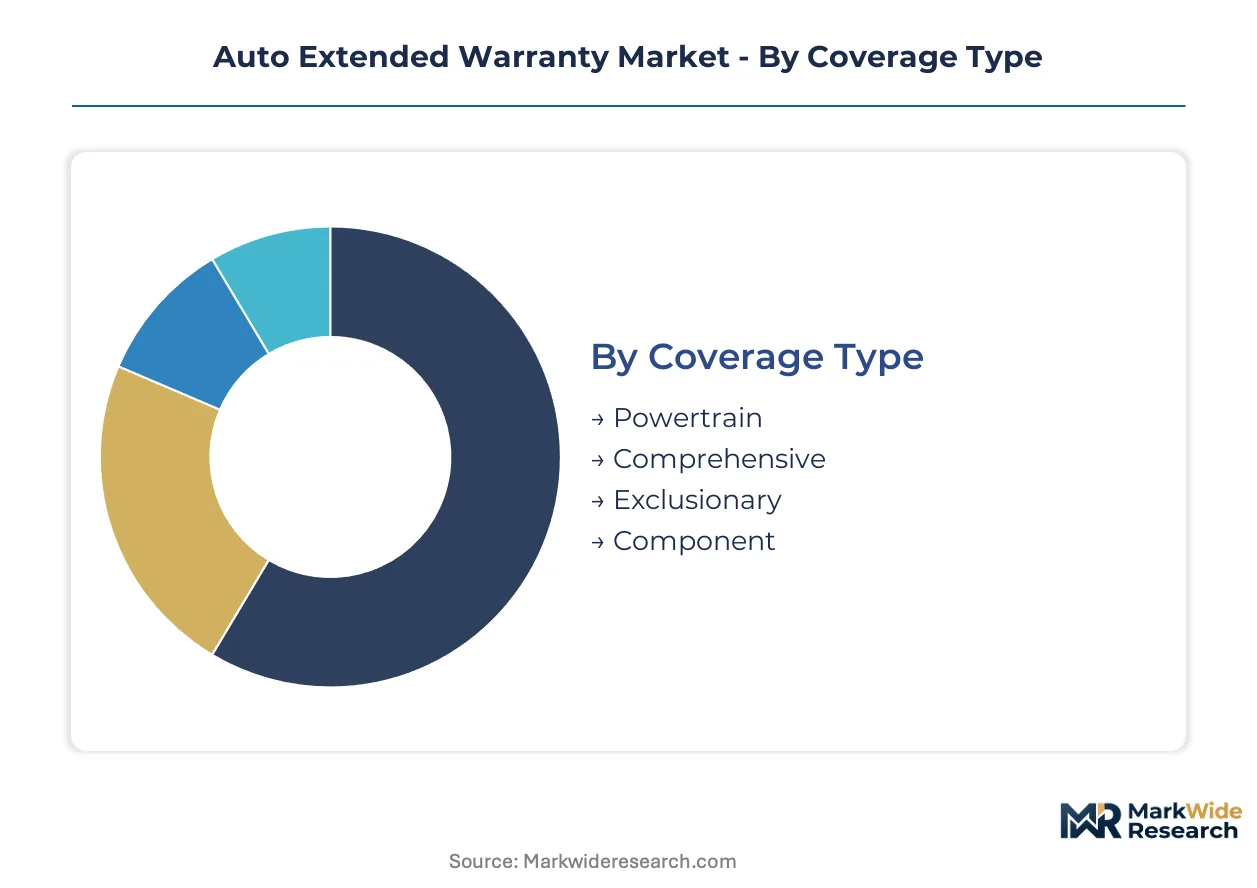
Extended warranty segmentation reveals how risk transfer mechanics vary across coverage depth, distribution channels, and ownership models. Each axis carries distinct pricing logic and claims frequency profiles that reshape competitive positioning.
Coverage Type:
Technology and specification depth define the coverage hierarchy, with powertrain complexity driving tier differentiation.
- Powertrain:Engine, transmission, and drivetrain components constitute the core mechanical exposure. Fleet operators in Texas and California concentrate demand here as commercial uptime protection outweighs peripheral system concerns.
- Comprehensive:Expanded protection spans electrical, HVAC, and infotainment systems alongside mechanical components. Luxury vehicle owners in Florida and New York drive disproportionate margin capture through risk-averse contract selection.
- Exclusionary:Named-exclusion contracts list only uncovered items rather than protected components. Simpler policy language reduces dispute volume for direct-to-consumer platforms.
- Component:Single-system coverage targets specific high-failure items like turbochargers or air suspension. Used-vehicle buyers seeking targeted protection favor this tier.
Mature deployment sits with Powertrain. Newer deployment is concentrated in Exclusionary as digital distributors seek streamlined policy structures.
Provider Type:
Channel economics and captive finance integration separate the provider landscape into distinct margin architectures.
- Third-Party:Independent underwriters operate through direct-response advertising and online marketplaces. These providers capture price-sensitive used-vehicle buyers bypassing dealership markups.
- Manufacturer:OEM-backed contracts leverage dealership channel control and captive finance bundling. Premium per-unit pricing reflects perceived backing stability and integrated service networks.
- Dealership:Point-of-sale packaging embeds warranties into vehicle financing at purchase. FTC Used Car Rule disclosure mandates shape presentation protocols.
- Online Platform:Digital-native distributors compress acquisition costs through search and social channels. Real-time quote comparison tools erode traditional information asymmetry.
Volume concentrates with Third-Party. Margin expansion is climbing the fastest through Online Platform as telematics integration enables dynamic pricing models.
Contract Length:
Duration structures align with vehicle ownership cycles and residual value timing.
- Short-Term:Coverage spans 12-24 months for near-warranty vehicles or temporary ownership periods. High turnover markets like Arizona and Nevada show concentration.
- Mid-Term:3-5 year contracts match average used-vehicle holding periods. This tier captures the largest transaction volume across the United States.
- Long-Term:Extended 6-10 year protection targets owners of vehicles with established reliability records. Premium pricing reflects compounded risk exposure.
- Customizable:Mileage and month combinations tailored to individual driving patterns. Telematics data enables personalized term construction.
Standardized terms dominate through Mid-Term. Flexibility investment is accelerating fastest in Customizable as usage-based insurance models mature.
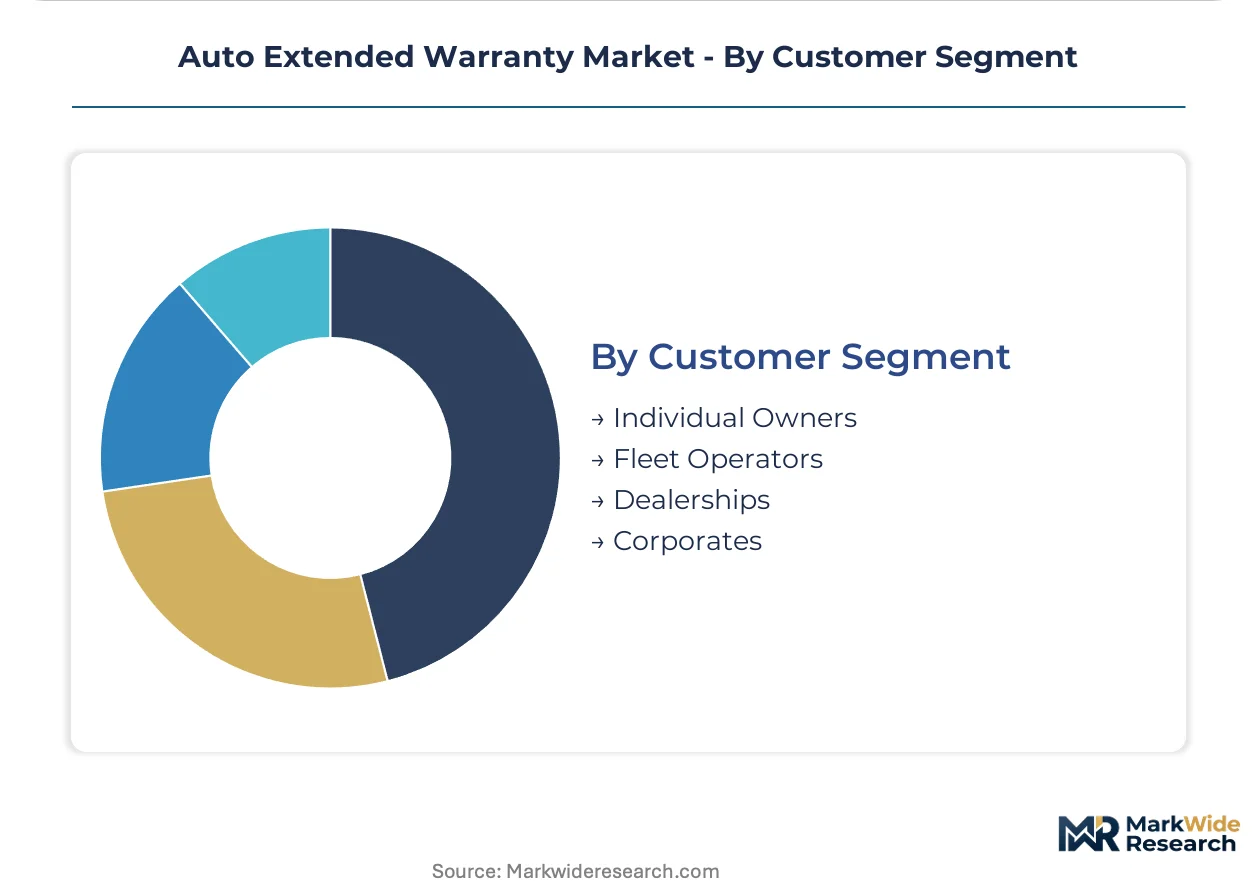
Customer Segment:
Ownership scale and procurement authority segment demand into distinct service requirements.
- Individual Owners:Personal vehicle protection driven by risk aversion and repair cost uncertainty. Secondary market buyers outside manufacturer coverage periods show steepest contract uptake.
- Fleet Operators:Commercial vehicle managers prioritize uptime guarantees across electric and diesel powertrains. California's Advanced Clean Trucks regulation accelerates electric fleet adoption and associated warranty demand.
- Dealerships:Inventory protection and certified pre-owned program backing. Volume commitments enable preferential reinsurance rates.
- Corporates:Employee vehicle programs and executive fleet coverage. Procurement departments negotiate master service agreements with national providers.
Individual Owners anchor transaction volume. Commercial deployment is expanding most quickly through Fleet Operators as logistics electrification intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones across the United Arab Emirates concentrate regional warranty underwriting operations. These tax-advantaged jurisdictions attract captive finance arms seeking Middle East market entry points.
United States
Used-vehicle penetration deepens across Texas and Florida as secondary market buyers seek post-manufacturer protection. The FTC Used Car Rule mandates disclosure protocols at point of sale. Dallas-Fort Worth anchors third-party provider concentration where direct-to-consumer platforms compete for price-sensitive owners.
Germany
OEM-backed contracts dominate through captive finance integration with premium automotive brands. The KBA enforces type-approval standards that shape warranty coverage definitions. Bavaria's automotive cluster around Munich hosts underwriter operations serving manufacturer-dealer networks.
China
EV powertrain complexity drives contract uptake among battery-electric vehicle owners. MIIT regulations on new energy vehicle warranties establish minimum coverage baselines. The Yangtze River Delta around Shanghai concentrates telematics-enabled warranty innovation.
United Kingdom
Risk-averse luxury vehicle owners in London and Southeast England drive comprehensive plan margins. The Financial Conduct Authority governs insurance-warranty hybrid products. The Midlands automotive corridor hosts third-party administrator operations.
Canada
Extended coverage penetration rises among used-vehicle buyers in Ontario and Quebec. Provincial insurance regulators coordinate reserve requirements across multi-jurisdictional providers. Toronto anchors digital distribution platform headquarters serving cross-border operations.
Auto Extended Warranty Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across channel and coverage tiers. The vendor base spans insurance-backed underwriters, direct-to-consumer marketers, and OEM-captive finance operations. Three archetypes dominate: digital-native distributors compressing acquisition costs, manufacturer-integrated providers commanding premium pricing, and telematics-enabled innovators reshaping risk transfer mechanics. Competitive moves concentrate on M&A for customer base expansion and strategic partnerships for telematics data access.
Within the digital-native tier, Endurance and CarShield exemplify direct-response advertising scale. Zurich occupies the manufacturer-integrated position through captive finance relationships. These three anchors illustrate the channel economics separating third-party price competition from OEM-backed premium positioning.
| Leading Market Players |
|---|
| Toco Warranty |
| Premier Auto Protect |
| Endurance |
| Omega Auto Care |
| Olive |
| CarShield |
| American Dream Auto Protect |
| Zurich |
| Carchex |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up third-party warranty specialists have consolidated fragmented underwriter capacity across Texas and Florida, concentrating pricing power while compressing commission structures for independent agents. This ownership pattern feeds supply chain discipline through centralized reinsurance purchasing and standardized claims management platforms that reduce per-unit administrative costs.
Pricing Analysis
Short lead-time contract activation commands premium pricing from used-vehicle buyers seeking immediate post-purchase protection, while spot inventory of pre-underwritten policies trades at modest discounts. The dominant pricing structure runs through subscription-tiered models spanning powertrain, comprehensive, and exclusionary coverage levels. Price differentiation stems from telematics-enabled risk scoring and state-level regulatory compliance costs. Cost compression in comprehensive tiers is intensifying because lithium-ion battery thermal management claims lack established actuarial baselines. Fleet operators show least price sensitivity due to uptime guarantees, whereas individual used-vehicle buyers in Arizona and Nevada exhibit highest elasticity.
Supply Chain Analysis
Reinsurance capacity for extended warranty underwriters rests on Bermuda-based specialty insurers, London-market syndicates, and domestic US property-casualty carriers. Raw material dependencies span semiconductor components for telematics hardware, lithium-ion cells for EV powertrain coverage reserves, and actuarial software licenses for claims prediction. Single-source vulnerability concentrates in telematics data aggregation platforms that feed dynamic pricing algorithms. Distribution runs through direct-response advertising networks, captive finance bundling at franchised dealerships, and digital-native comparison marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The auto extended warranty sector sits in a technology-transition phase as battery-electric powertrains displace internal combustion actuarial models. Software-defined vehicle architectures are replacing legacy mechanical failure curves with predictive degradation analytics.
For Market Incumbents: Anchor defensive positioning through backward integration into telematics data streams and captive repair network control. Consolidate distressed third-party administrator assets in Texas and Florida to secure customer base density. Invest in EV battery degradation modeling capabilities before solid-state chemistry obsoletes existing reserve frameworks. Channel control through dealership finance-and-insurance departments remains the critical lever against digital-native disintermediation.
For New Entrants and Emerging Players: The pricing gap between manufacturer-backed premium contracts and third-party economy coverage creates white-space opportunity for mid-tier digital distributors. Target individual used-vehicle buyers in metropolitan United States markets where price transparency tools have eroded dealership markup power. Penetrate commercial fleet segments in California where Advanced Clean Trucks regulation accelerates electric adoption without established warranty infrastructure. Pursue telematics-native go-to-market positioning that bundles real-time vehicle health monitoring with dynamic contract adjustment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor telematics-enabled warranty platforms with established data partnerships in United States coastal markets. Long-term viability hinges on underwriting capacity to model silicon carbide inverter and solid-state battery failure probabilities. Monitor regulatory clarity from the National Association of Insurance Commissioners on EV battery reserve requirements as the primary inflection signal for sector repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership | Enables dynamic pricing models that compress adverse selection for battery-electric vehicle coverage. |
| Reinsurance Capacity Lock-up | Secures multi-year underwriting backing from Bermuda syndicates before rate hardening cycles. |
| EV Battery Degradation Modeling | Builds proprietary actuarial frameworks around thermal management failure curves lacking industry standards. |
| Direct-to-Consumer Platform Expansion | Bypasses dealership finance-and-insurance markups to capture margin from price-sensitive used-vehicle buyers. |
| Commercial Fleet Master Service Agreement | Captures volume commitments from logistics operators managing total cost of ownership across electrified powertrains. |
Methodological Framework
Multi-period observation of warranty contract pricing dispersion, claims frequency by powertrain type, and reinsurance rate movements anchored the trend analysis, supplemented by interviews with underwriting executives at third-party administrators, captive finance directors at OEM warranty operations, claims adjusters specializing in EV thermal management failures, and regulatory affairs leads at state insurance commissions. Secondary validation drew from NAIC reserve requirement filings, FTC Used Car Rule enforcement actions, EPA emissions compliance cost studies, and vehicle registration databases tracking extended warranty attachment rates. Bottom-up policy issuance data triangulated against top-down reinsurance market capacity estimates.
Segment-weighting approaches distributed total market value across coverage type, provider channel, contract duration, and customer segment dimensions, with additional stratification by powertrain architecture to capture electrification transition effects. CAGRs were derived from fitted growth curves calibrated to historical penetration rates and projected vehicle age distribution shifts. Forecast inputs incorporated battery-electric vehicle adoption trajectories, semiconductor pricing volatility, and state-level regulatory harmonization timelines.
Underlying measurement precision varies by segment; powertrain coverage carries tighter precision than comprehensive plans due to established failure curves, while EV battery degradation contracts exhibit wider confidence intervals. Forecasts reflect documented assumptions regarding regulatory stability, reinsurance market capacity, and battery chemistry transition timelines. A small set of triggers—including solid-state battery commercialization, catalytic converter theft enforcement intensity, and telematics data privacy rulings—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Solar Panel Warranty Insurance Market
Insurance
Group Health Insurance Market
Insurance
China Parametric Insurance Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Liability Insurance Market
Insurance
Business Insurance Market
Insurance
Japan Bancassurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Reinsurance Market
Insurance
UK Dental Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
China Liability Insurance Market
Insurance
Specialty Insurance Market
Insurance
Asia-Pacific Family Floater Health Insurance Market