
 Asia-Pacific Usage-Based Insurance Market | 2026-2036
Asia-Pacific Usage-Based Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Usage-Based Insurance Market Analytics
Premium telematics-grade data accuracy is reorganizing competitive dynamics across the Asia-Pacific Usage-Based Insurance Market. Allianz SE leverages its proprietary IoT infrastructure to sustain pricing precision in pay-how-you-drive programs. Octo Group SpA anchors its regional position through deep specialization in cloud-native analytics platforms. AXA competes by controlling distribution partnerships with major automotive OEMs in Japan and South Korea.
Usage-Based Insurance deploys real-time driving behavior monitoring through onboard diagnostic ports, accelerometers, and cellular-connected black boxes to calculate dynamic risk-adjusted premiums. The primary commercial purpose is to replace traditional actuarial pooling with individualized risk pricing that aligns premium costs to actual exposure. Pay-How-You-Drive programs command the deepest margin pools as behavioral scoring models mature, while fleet customer types generate the most predictable recurring data streams across the Asia-Pacific corridor. Telematics technology dominates underlying infrastructure investment, though mobile app-based alternatives are gaining traction among individual policyholders seeking lower-friction onboarding.
Japan's METI mandates connected vehicle data interoperability standards that directly shape telematics device specifications for insurers operating in that market. Australia's TGA-equivalent transport safety frameworks and South Korea's MFDS-aligned automotive cybersecurity rules further constrain product design and cross-border platform deployment. China's MIIT imposes GB-standard compliance on all in-vehicle data collection hardware, creating a fragmented certification landscape that vendors must navigate country by country. Stakeholders must monitor which regulator moves first on cross-border data portability rules, as this will determine whether regional platforms can scale or remain trapped in national silos.
Market Dynamics
Telematics hardware miniaturization and India's PLI scheme for automotive electronics are compressing device costs while accelerating insurer deployment timelines across the Asia-Pacific corridor. Fleet operators now demand real-time risk visibility that static actuarial models cannot deliver.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for automotive electronics manufacturing are slashing telematics hardware procurement costs for domestic insurers and fleet integrators.
- Fleet telematics adoption:Commercial vehicle operators across Southeast Asia are mandating connected black boxes to optimize fuel consumption and driver safety scoring.
- Pay-How-You-Drive behavioral models:Dynamic premium algorithms now reward defensive driving patterns with immediate cost reductions, pulling individual policyholders from traditional pooled risk products.
Market Restraints
- GB-standard certification costs:China's MIIT mandates country-specific hardware compliance that fragments regional platform economics and extends product launch timelines.
- Semiconductor supply concentration:Cellular modem chip fabrication concentrates in Taiwan and South Korea, exposing insurers to allocation delays during capacity crunches.
- Cross-border data portability friction:Absent unified Asia-Pacific frameworks, vehicle data remains trapped in national regulatory silos, preventing scalable cloud analytics architectures.
Strategic Opportunities
- Indonesia's underpenetrated fleet segment:Commercial vehicle insurance in Jakarta and Surabaya operates on traditional mileage estimates, creating white space for telematics-verified exposure pricing.
- Mobile app-based onboarding:Smartphone sensor integration eliminates hardware distribution costs, opening individual policyholder segments previously uneconomical for black-box programs.
- Japan's METI interoperability mandates:Standardized connected vehicle data formats position insurers to offer seamless cross-OEM coverage without proprietary device lock-in.
Industry Challenges
- Actuarial talent scarcity:Insurers lack sufficient data scientists capable of training behavioral scoring models on noisy telematics streams.
- Legacy core system integration:Policy administration platforms built for annual renewal cycles struggle to ingest real-time driving data and compute dynamic premium adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Usage-Based Insurance Market |
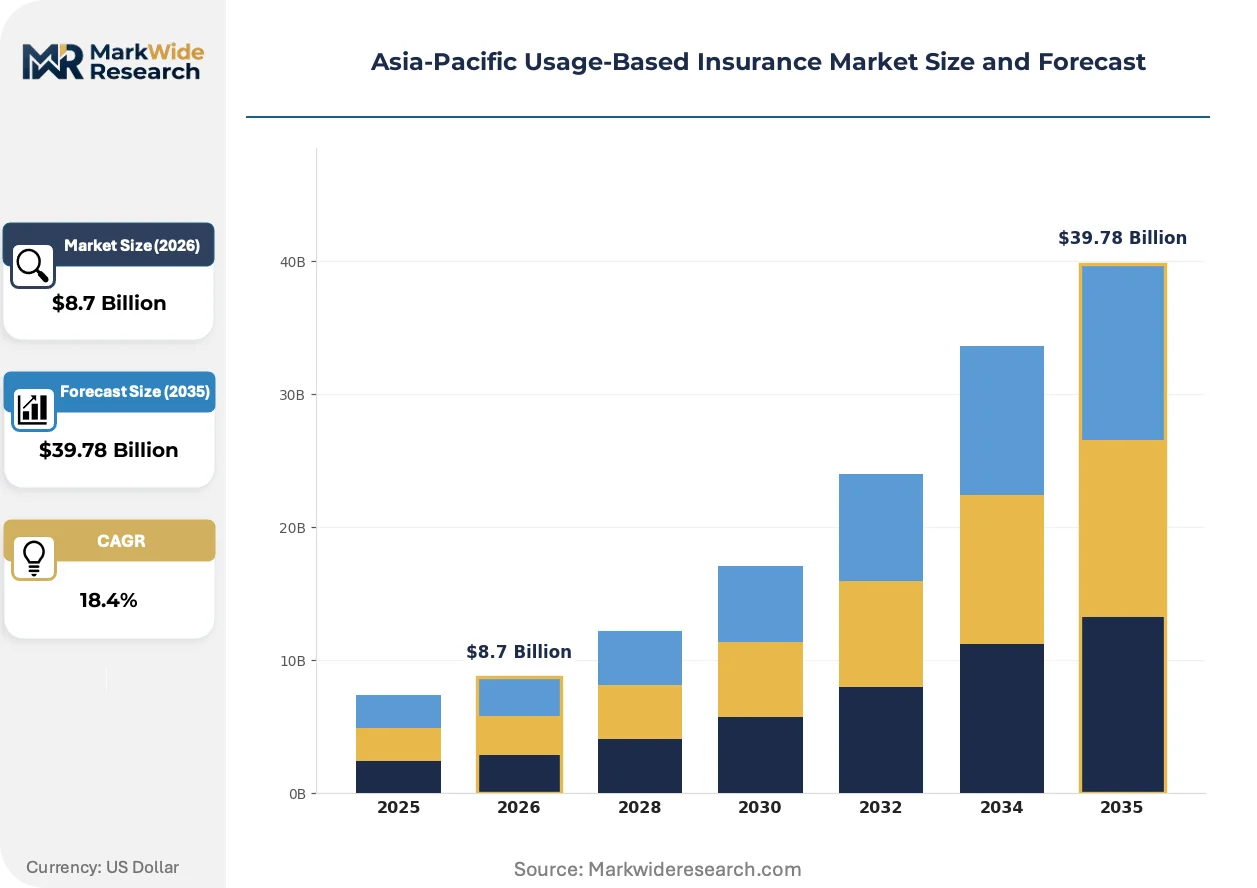
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pay-As-You-Drive, Pay-How-You-Drive, Distance-Based, Time-Based Customer Type: Individual, Fleet, Commercial, Enterprise Technology: Telematics, Mobile Apps, GPS Tracking, Cloud Computing Insurance Product: Personal Auto, Commercial Auto, Motorcycle, Specialty Vehicle |
| Companies Covered | Liberty Mutual Holding Company Inc., Allstate Insurance Company, MAPFRE RE, COMPAÑÍA DE REASEGUROS, S.A., The Progressive Corporation, Allianz SE, AXA, TomTom International, Octo Group SpA, Cambridge Mobile Telematics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Usage-Based Insurance Market Evolving Landscape
Edge computing architectures and smartphone-native data collection are displacing centralized black-box infrastructure across the Asia-Pacific Usage-Based Insurance Market. These shifts compress latency, cut hardware costs, and expand addressable policyholder bases beyond fleet commercial lines.
Multi-axis accelerometer-on-chip technology is miniaturizing. Individual insurers in South Korea and Australia are embedding these sensors directly into windshield-mounted tags rather than OBD-port dongles. The form factor reduction is miniaturizing installation friction and enabling self-service policy activation without technician visits.
Japan's METI interoperability standards now mandate open vehicle data interfaces for all new passenger cars. Insurers must redesign telematics platforms to ingest standardized CAN-bus feeds rather than proprietary OEM streams. Japanese non-life carriers are responding by consolidating data pipelines onto cloud-native architectures that can parse multiple manufacturer formats.
Fleet procurement teams now demand unbundled telematics hardware from insurance coverage, treating risk data as an operational asset independent of premium financing. Third-party fleet management platforms in Singapore and Thailand are inserting themselves between vehicle owners and insurers, capturing data relationships that carriers once controlled directly. This disintermediation is most visible among logistics operators running cross-border ASEAN routes who prioritize single-dashboard visibility over insurer-integrated offerings.
Asia-Pacific Usage-Based Insurance Market Segmentation
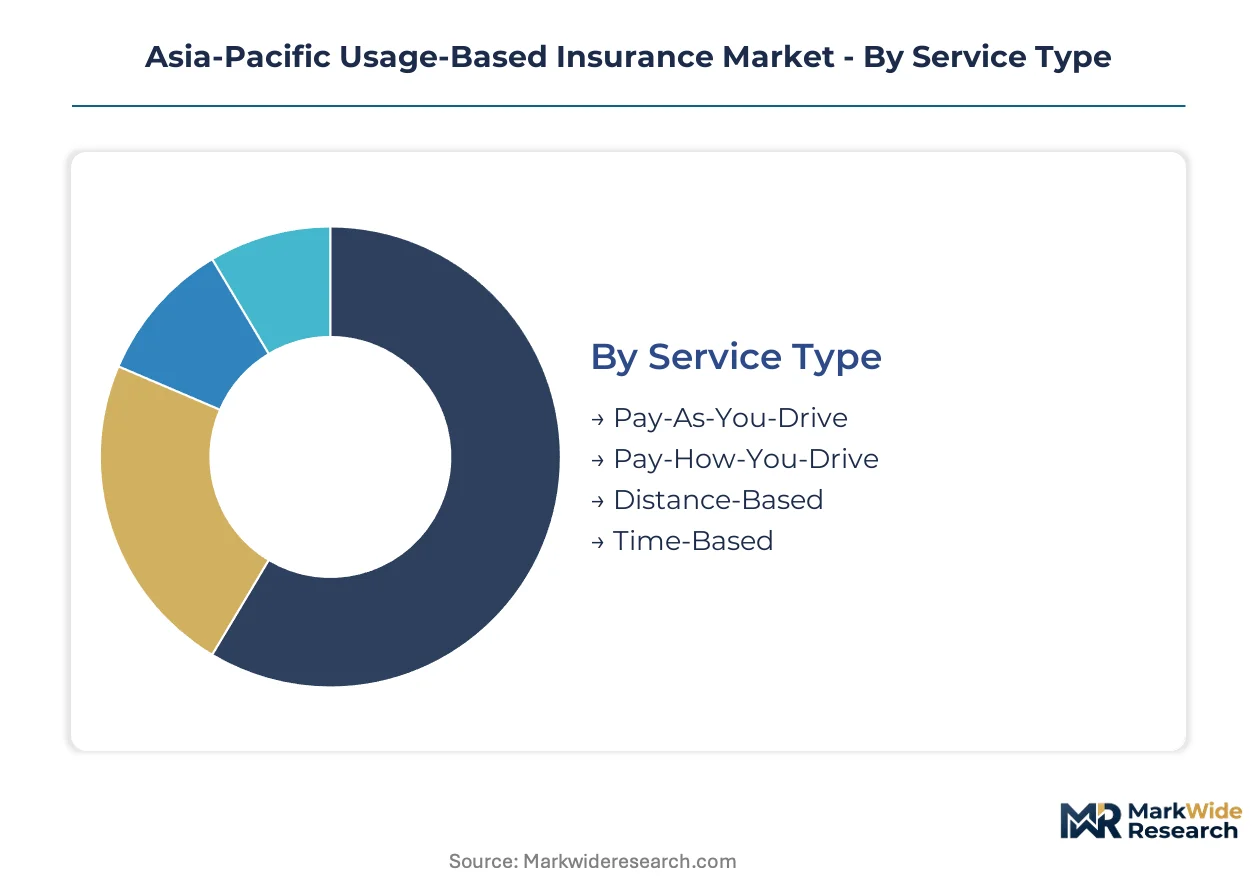
Segmentation in Asia-Pacific Usage-Based Insurance determines how insurers structure data collection infrastructure, price risk, and comply with divergent national regulations. Each dimension carries distinct margin profiles and deployment cost structures across the region's fragmented regulatory landscape.
Service Type:
Regulatory frameworks in China, Japan, and South Korea impose divergent data consent and pricing transparency requirements that reshape how each service model operates across national boundaries.
- Pay-How-You-Drive:Behavioral scoring algorithms ingest accelerometer data, braking patterns, and cornering forces to calculate dynamic premiums. Japan's METI interoperability mandates enable insurers to access standardized CAN-bus feeds without proprietary OEM negotiations, accelerating deployment in Tokyo and Osaka metropolitan corridors.
- Pay-As-You-Drive:Mileage-verified exposure pricing replaces estimated annual distance with odometer-corrected actuals. Fleet operators in Jakarta and Surabaya favor this model for its straightforward audit trails under Indonesia's evolving transport safety frameworks.
- Distance-Based:Kilometer-tiered rate bands simplify underwriting for price-sensitive individual policyholders in India's tier-two cities where smartphone penetration exceeds black-box accessibility.
- Time-Based:Usage windows restrict coverage to specific driving periods, appealing to weekend-only vehicle owners in Australia's urban periphery where public transit substitutes for weekday mobility.
Pay-How-You-Drive handles the majority of throughput; Pay-As-You-Drive is the fastest mover on share.
Customer Type:
Procurement sophistication varies sharply across the customer spectrum, with enterprise buyers demanding API-integrated data pipelines that individual policyholders rarely require.
- Fleet:Commercial vehicle operators mandate real-time risk dashboards combining fuel efficiency, driver safety scores, and geofenced route compliance. Logistics operators running cross-border ASEAN routes prioritize single-dashboard visibility over insurer-captive offerings.
- Commercial:Small business vehicle pools seek telematics-verified exposure pricing without enterprise-scale integration overhead, concentrating demand among Singapore and Bangkok service sector operators.
- Individual:Smartphone-native data collection eliminates hardware distribution friction, opening segments previously uneconomical for black-box programs in India's price-sensitive personal auto market.
- Enterprise:Multi-national corporations with Asia-Pacific vehicle fleets negotiate unbundled telematics procurement, treating risk data as an operational asset independent of premium financing arrangements.
Fleet commands the dominant revenue pool; Individual is expanding most quickly as mobile onboarding reduces acquisition costs.
Technology:
Hardware cost trajectories and India's PLI scheme for automotive electronics are compressing device economics while shifting competitive advantage toward software-layer analytics capabilities.
- Telematics:OBD-port dongles and cellular-connected black boxes remain the accuracy benchmark for behavioral scoring. China's MIIT GB-standard certification fragments regional platform economics, forcing vendors to navigate country-specific hardware approval processes.
- Cloud Computing:Native architectures parse multiple OEM data formats required by Japan's METI interoperability mandates, consolidating previously siloed manufacturer-specific pipelines.
- Mobile Apps:Smartphone sensor integration captures accelerometer and GPS data without dedicated hardware, gaining traction among Australian and South Korean individual policyholders seeking lower-friction onboarding.
- GPS Tracking:Location-verified exposure pricing supports theft recovery and geofence enforcement for commercial auto fleets operating across Malaysia's peninsula and archipelago territories.
Telematics retains the dominant installed base; Mobile Apps are gaining share fastest as semiconductor supply constraints periodically disrupt cellular modem availability.
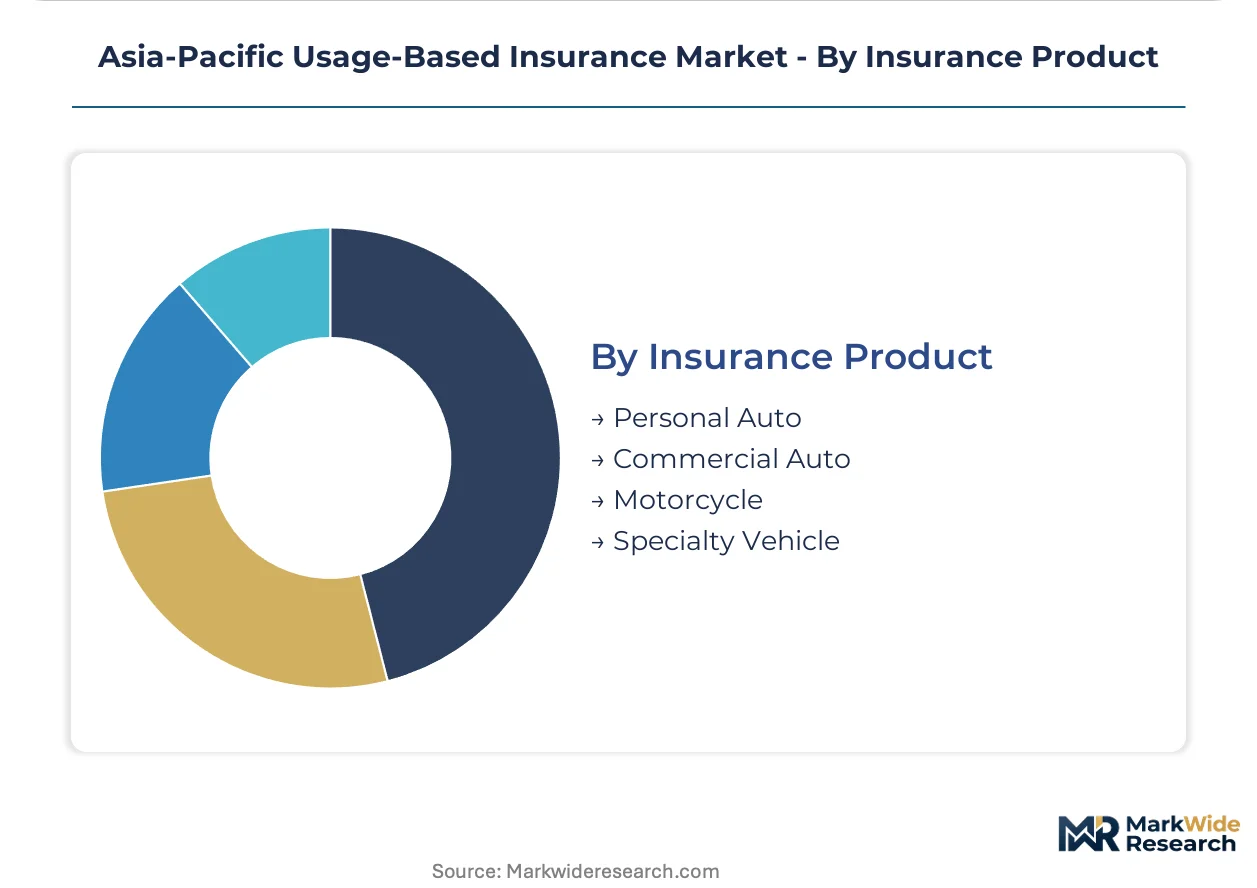
Insurance Product:
Vehicle category risk profiles and data collection feasibility determine which products support telematics-native pricing versus traditional actuarial pooling.
- Personal Auto:Passenger vehicle policies dominate addressable volume, with connected vehicle penetration deepest in China's tier-one cities where OEM telematics integration is standard.
- Commercial Auto:Delivery van and light truck fleets generate predictable recurring data streams with immediate fuel and safety optimization returns, anchoring insurer prioritization in Southeast Asian logistics corridors.
- Motorcycle:Two-wheeler telematics faces form-factor constraints that mobile app solutions partially address, particularly in Indonesia's dense urban cores where motorcycle ownership dominates personal transport.
- Specialty Vehicle:Construction equipment and agricultural machinery policies require ruggedized hardware capable of extreme-environment operation, limiting addressable carriers to those with industrial equipment underwriting expertise.
Personal Auto carries the largest premium volume; Commercial Auto is climbing the fastest as fleet digitization accelerates across ASEAN markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telematics hardware fabrication concentrates in Taiwan and South Korea, creating supply dependencies that insurers across the Asia-Pacific corridor must manage through dual-sourcing strategies and inventory buffers.
China
Connected vehicle penetration peaks in Shanghai, Beijing, and Shenzhen where OEM telematics integration is standard. MIIT's GB-standard certification mandates fragment regional platform economics, forcing vendors to navigate country-specific hardware approval processes before deployment. Tier-one cities generate the deepest behavioral data pools for Pay-How-You-Drive algorithm training.
Japan
Tokyo and Osaka metropolitan corridors anchor demand for standardized CAN-bus data feeds under METI interoperability mandates. Non-life carriers consolidate data pipelines onto cloud-native architectures capable of parsing multiple manufacturer formats. The regulatory push eliminates proprietary OEM lock-in, accelerating insurer platform deployment timelines.
India
PLI scheme incentives slash telematics hardware procurement costs for domestic insurers and fleet integrators. Maharashtra and Karnataka host the primary automotive electronics manufacturing clusters feeding regional deployment. Tier-two cities see mobile app-based onboarding expand addressable bases beyond black-box economics.
Australia
Sydney and Melbourne fleets drive commercial auto telematics adoption with unbundled hardware procurement treating risk data as operational assets. TGA-equivalent transport safety frameworks constrain product design for cross-border platform deployment. Smartphone-native data collection gains traction among individual policyholders seeking lower-friction activation.
South Korea
Seoul Capital Area insurers embed multi-axis accelerometer-on-chip technology directly into windshield-mounted tags, miniaturizing installation friction. MFDS-aligned automotive cybersecurity rules shape telematics device specifications. Domestic semiconductor fabrication supports cellular modem supply, reducing allocation risk during capacity crunches.
Asia-Pacific Usage-Based Insurance Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Usage-Based Insurance Market. Global multi-line carriers with captive telematics infrastructure compete against specialized analytics platforms and regional insurers partnering with third-party data providers. The structure fragments across three strategic archetypes: proprietary IoT owners, cloud-native specialists, and distribution-integrated underwriters. Competitive moves concentrate on M&A for data science capabilities and strategic partnerships with automotive OEMs for embedded distribution.
Among global carriers with Asia-Pacific presence, Allianz SE and AXA exemplify the proprietary infrastructure archetype, leveraging captive IoT investments and OEM distribution control respectively. Octo Group SpA occupies a specialist position in cloud-native analytics platforms, anchoring the technology-layer segment that serves insurers lacking in-house behavioral scoring capabilities.
| Leading Market Players |
|---|
| Liberty Mutual Holding Company Inc. |
| Allstate Insurance Company |
| MAPFRE RE, COMPAÑÍA DE REASEGUROS, S.A. |
| The Progressive Corporation |
| Allianz SE |
| AXA |
| TomTom International |
| Octo Group SpA |
| Cambridge Mobile Telematics |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory buffers at Taiwan-based cellular modem fabricators directly shape premium pricing power for insurers deploying Pay-How-You-Drive programs across the Asia-Pacific corridor. Hardware procurement costs hinge on semiconductor allocation cycles, while GB-standard certification expenses in China fragment platform economics and compress margin pools for cross-border deployments.
Pricing Analysis
China's MIIT GB-standard certification dictates the pricing tier structure across the Asia-Pacific Usage-Based Insurance Market. Three-tier pricing structure across premium telematics-grade, standard OBD-port, and economy mobile-app tiers separates behavioral scoring accuracy levels. Cost compression in economy tiers is intensifying because smartphone-native onboarding eliminates hardware distribution overhead. Fleet operators in Southeast Asia exhibit lowest price sensitivity due to operational asset treatment of risk data, while individual policyholders in India's tier-two cities drive hardest bargain hunting.
Supply Chain Analysis
Strategic stockpile preferences dominate insurer procurement strategies as semiconductor supply volatility reshapes inventory planning. Taiwan, South Korea, and China concentrate cellular modem chip fabrication, drawing from silicon wafers, RF components, and automotive-grade memory modules. Single-source vulnerability concentrates in Taiwan Strait logistics corridors, exposing carriers to allocation delays during capacity crunches. Distribution runs through Tier 1 automotive electronics integrators who bundle telematics hardware with insurance policy administration platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
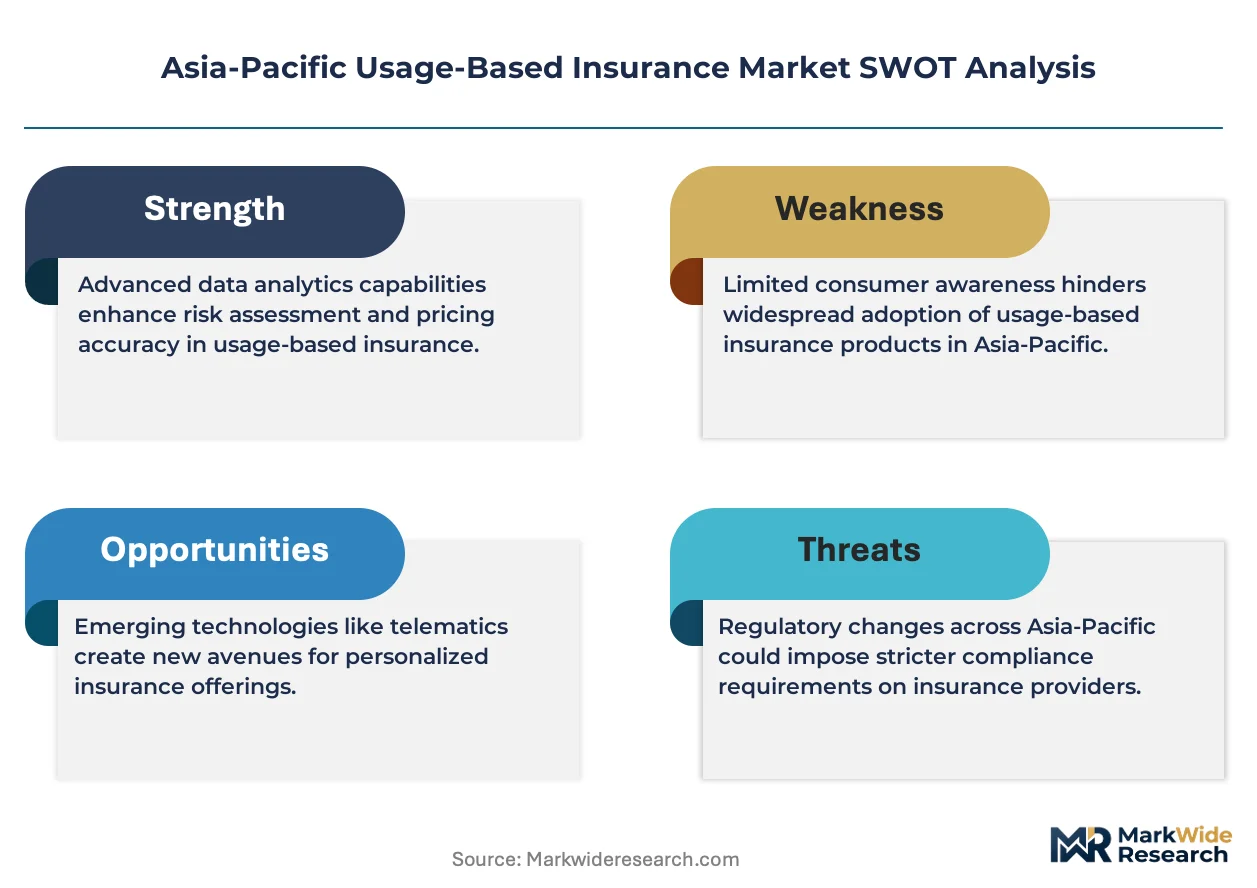
Incumbents face substitution pressure from mobile app-based data collection that bypasses proprietary black-box infrastructure entirely. Smartphone-native onboarding threatens to commoditize behavioral scoring capabilities that once required dedicated hardware investment.
For Market Incumbents: Fortify data pipeline control by embedding cloud-native analytics architectures that parse standardized CAN-bus feeds under Japan's METI interoperability mandates. Consolidate API-integrated relationships with fleet management platforms before third-party intermediaries capture operational data ownership. Prioritize backward integration into telematics hardware assembly through India's PLI scheme incentives to secure cost-competitive device supply.
For New Entrants and Emerging Players: Service-layer gaps in Indonesia's underpenetrated commercial vehicle segment offer immediate white-space opportunity where traditional mileage estimates still dominate premium calculation. Jakarta and Surabaya fleet operators seek telematics-verified exposure pricing without legacy insurer integration overhead. Pursue mobile app-first onboarding to bypass hardware distribution economics that encumber established carriers.
For Investors and Strategic Acquirers: Long-term, this sits as a data-asset accumulation play because behavioral scoring model training sets compound competitive moats over multi-year policyholder retention cycles. Target acquisition candidates with cloud-native platform architectures and existing OEM distribution partnerships in Japan or South Korea. Watch for cross-border data portability regulatory harmonization as the inflection signal determining whether regional platforms achieve scale or remain trapped in national silos.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Consolidates data pipelines onto architectures parsing multiple OEM formats required by METI interoperability mandates. |
| Mobile App-Based Onboarding | Eliminates hardware distribution costs and expands addressable bases beyond black-box economics in price-sensitive segments. |
| PLI Scheme Hardware Localization | Secures cost-competitive telematics device supply through India's production-linked incentive manufacturing clusters. |
| OEM Distribution Partnership | Locks in embedded policy activation channels at vehicle point-of-sale in markets with deepest connected vehicle penetration. |
| API Fleet Platform Integration | Prevents third-party fleet management intermediaries from disintermediating data relationships carriers once controlled directly. |
Research Methodology
A standing panel of insurance product executives, telematics platform engineers, fleet procurement directors, and regulatory compliance officers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against MIIT certification databases, METI interoperability standards filings, ASEAN automotive production statistics, and cellular modem trade flow records. Bottom-up policyholder segmentation analysis triangulated against top-down premium pool estimates across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework modeled service type, customer tier, technology deployment mode, and insurance product category across the projection horizon. CAGRs derived from annual premium pool trajectories incorporated connected vehicle penetration curves, hardware cost compression rates, and regulatory implementation timelines as core inputs.
Underlying assumptions cover semiconductor supply normalization, PLI scheme incentive continuity, and cross-border data portability stasis, with deviation risk concentrated in Taiwan Strait logistics disruptions and unilateral regulatory harmonization moves. Revision becomes warranted when cellular modem allocation delays exceed six-month thresholds or when major economies enact reciprocal data portability frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific EV Insurance Market
Insurance
Europe Extended Warranty Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Gap Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
Liability Insurance Market
Insurance
Entertainment Insurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
GCC Health Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Business Income Insurance Market
Insurance
Europe EV Insurance Market
Insurance
Europe Health Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Agricultural Insurance Market