
 Jewelry Insurance Market | 2026-2036
Jewelry Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Jewelry Insurance Market Foresight
EU AI Act compliance is recalibrating the cost-of-entry calculus for automated claims-processing platforms entering European markets. Chubb leverages its century-old underwriting infrastructure to sustain premium positioning in high-value jewelry lines across North America and Asia. Jewelers Mutual Insurance Company anchors its competitive moat through captive relationships with retail jeweler networks, controlling distribution at the point of sale.
Jewelry insurance is a specialized property and casualty product covering loss, theft, damage, and mysterious disappearance of precious items, typically requiring independent gemological appraisal with carat weight, cut grade, and replacement value documentation to establish policy limits and claims baselines. Its primary commercial purpose is to indemnify owners against the financial and sentimental cost of irreplaceable asset loss while enabling lenders to secure collateralized jewelry portfolios. Scheduled coverage policies command the deepest margin pools due to individualized underwriting and appraisal fees, while blanket coverage competes on convenience for moderate-value collections. Online platforms represent the fastest-growing distribution vector as direct-to-consumer quoting engines displace traditional agent-mediated sales for standard-tier jewelry assets.
FDA oversight of laser inscription and traceability technologies intersects with insurance fraud detection, while state-level department of insurance regulations in New York, California, and Texas mandate specific disclosure standards for policy exclusions and valuation methodologies. The National Association of Insurance Commissioners coordinates model laws that shape reserve requirements and market conduct examinations across multiple jurisdictions. Stakeholders must monitor how generative AI tools for automated damage assessment reshape regulator scrutiny of claims-handling fairness and bias.
Market Dynamics
Blockchain-based provenance verification is compressing underwriting timelines while digitized appraisal workflows recalibrate loss-adjustment accuracy across high-value jewelry portfolios. This technological inflection is redrawing competitive boundaries between legacy carriers and insurtech entrants.
Growth Catalysts
- EU AI Act:Automated claims-processing platforms face heightened compliance thresholds in European markets, accelerating vendor consolidation around audit-ready algorithmic systems.
- Heirloom portfolio expansion:High-net-worth households are scheduling coverage for generational jewelry transfers, deepening policy attachment rates among multi-generational clients.
- Laser inscription traceability:FDA-registered gemological marking systems are reducing fraud incidence in diamond and colored-stone claims, lowering loss ratios for underwriters.
Market Restraints
- Appraisal cost volatility:Independent gemological certification fees fluctuate with laboratory capacity constraints, compressing margins on moderate-value scheduled policies.
- Specialty carrier concentration:Underwriting capacity clusters among a narrow cohort of legacy insurers, limiting price competition in ultra-high-value segments.
- Valuation methodology friction:State-level department of insurance regulations in New York and California mandate divergent replacement-value disclosure standards, complicating multi-jurisdictional policy administration.
Strategic Opportunities
- Point-of-sale embedded distribution:Retail jeweler networks represent captive underwriting channels where coverage activation at purchase reduces customer acquisition costs substantially.
- Generative AI damage assessment:Machine-learning models trained on gemological imagery are enabling remote first-notice-of-loss triage, compressing cycle times for routine claims.
- Blanket coverage penetration:Moderate-value collections in secondary metropolitan markets remain underpenetrated relative to scheduled policy saturation in primary cities.
Industry Challenges
- Gemological appraiser scarcity:Certified valuation professionals are concentrated in legacy financial centers, creating bottlenecks for geographic expansion into emerging affluent suburbs.
- Legacy policy administration integration:Mainframe-based core systems at established carriers resist API connectivity with digital-first distribution platforms, delaying real-time quoting deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jewelry Insurance Market |
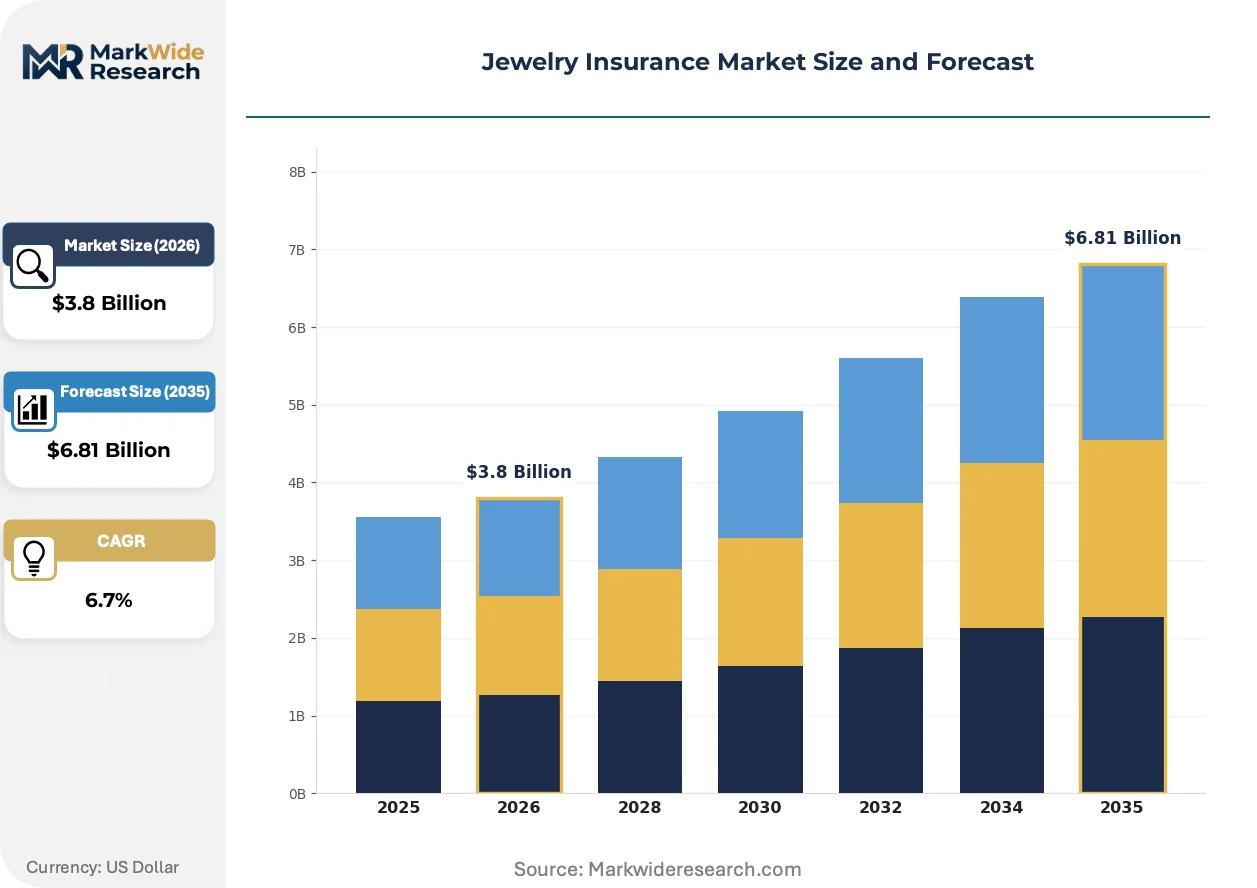
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Full Coverage, Limited Coverage, Theft Protection, Damage Protection Policy Type: Personal Property, Scheduled Coverage, Blanket Coverage, Appraisal-Based Customer Type: Individual Owners, Collectors, Retail Jewelers, Estate Executors Distribution Channel: Direct Sales, Brokers, Online Platforms, Insurance Agents |
| Companies Covered | Lavalier, Chubb, BriteCo, JIBNA, GemShield, Jewelers Mutual Insurance Company, Zillion, Travelers Insurance, WAX Insurance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jewelry Insurance Market Shifts & Advancements
Distributed ledger architectures and machine-vision assessment tools are converging to compress the trust-to-transaction cycle in jewelry insurance. These innovations are redrawing where value capture accrues across the policy lifecycle.
Blockchain provenance registries are integrating with underwriting engines to verify chain-of-custody documentation prior to policy issuance. Specialty carriers serving ultra-high-net-worth clients are deploying these systems most aggressively. The technology is integrating previously siloed appraisal, sales, and claims records into immutable audit trails that reduce moral hazard exposure.
The EU AI Act's risk-classification framework for automated decision-making systems is mandating algorithmic transparency in claims-processing platforms. European regulators now require human-in-the-loop protocols for high-value jewelry claim denials. Carriers with significant EU exposure are reengineering their AI stacks to satisfy documentation and bias-auditing requirements.
Direct-to-consumer quoting engines are displacing traditional agent-mediated distribution for standard-tier jewelry assets. Millennial and Gen Z collectors are initiating coverage research through mobile-optimized comparison platforms rather than broker referrals. This channel rotation is most pronounced in United States coastal metropolitan markets where digital-native purchasing behaviors predominate.
Jewelry Insurance Market Segmentation
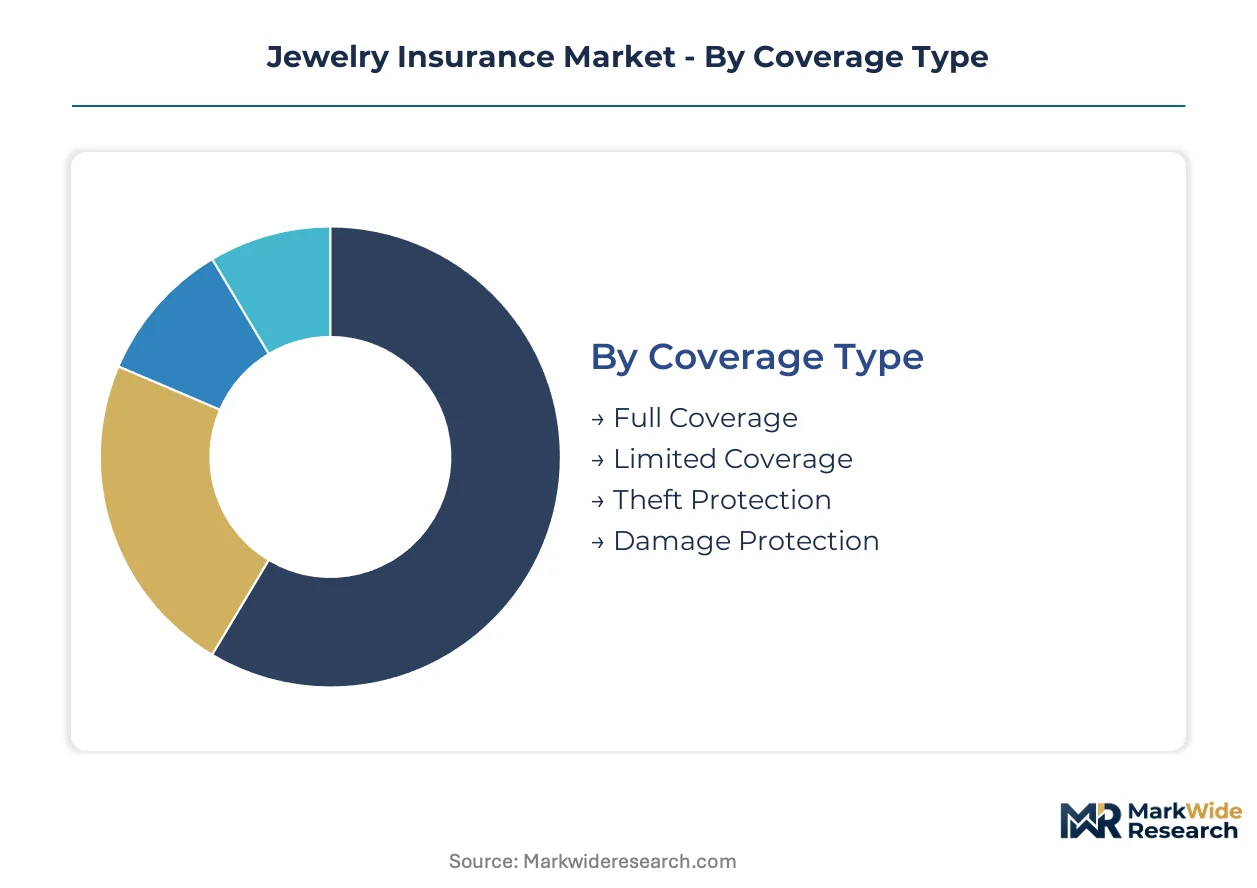
Jewelry insurance segmentation reflects divergent risk appetites and purchasing behaviors across owner profiles. Coverage structures, policy mechanisms, and distribution pathways each create distinct margin pools and underwriting complexity tiers.
Coverage Type:
Premium sensitivity and asset concentration drive selection between comprehensive protection and peril-specific policies.
- Full Coverage:Comprehensive protection spanning loss, theft, damage, and mysterious disappearance with named-peril clarity. High-net-worth households in coastal United States metros prioritize this tier for heirloom portfolios where sentimental value exceeds appraised replacement cost.
- Limited Coverage:Restricted protection excluding specific perils such as gradual wear or unexplained loss. Cost-conscious individual owners in secondary metropolitan markets select this option for moderate-value collections where premium minimization outweighs breadth of protection.
- Theft Protection:Single-peril coverage addressing criminal acquisition with streamlined claims documentation. Urban collectors facing elevated burglary exposure favor this structure for portable high-value items.
- Damage Protection:Physical peril coverage excluding theft and mysterious disappearance. Retail jewelers maintaining inventory on premises utilize this for operational asset protection against accidental breakage.
Full Coverage leads on scale; Theft Protection leads on momentum.
Policy Type:
Documentation intensity and valuation methodology separate scheduled precision from blanket convenience.
- Personal Property:Standard homeowners or renters endorsement with aggregate sublimits for jewelry categories. Younger individual owners initiating first coverage gravitate toward this accessible entry point bundled with residential policies.
- Scheduled Coverage:Itemized declaration with independent gemological appraisal establishing agreed-value limits. Collectors across Germany, Switzerland, and the United Kingdom demand this structure for unique pieces where generic replacement fails.
- Blanket Coverage:Aggregate limit without individual itemization, leveraging representative sampling for valuation. Moderate-value portfolio owners in suburban United States markets prefer this administrative efficiency.
- Appraisal-Based:Dynamic limit adjustment tied to periodic certified revaluation. Estate executors managing generational transfers favor this mechanism for probate-aligned coverage accuracy.
Scheduled Coverage commands premium positioning; Blanket Coverage expands most quickly.
Customer Type:
Ownership motivation and transaction frequency shape underwriting relationship depth and service expectations.
- Individual Owners:Personal acquisition holders seeking protection for engagement rings, watches, and commemorative pieces. This segment concentrates in United States primary cities where specialty carrier competition intensifies.
- Collectors:Curatorial investors assembling thematic or historical jewelry portfolios with appreciation tracking. Swiss and UAE private banking clients dominate this category with multi-jurisdictional coverage requirements.
- Retail Jewelers:Commercial operators requiring inventory protection and customer goods custody coverage. Point-of-sale embedded distribution partnerships concentrate underwriting relationships with Jewelers Mutual and comparable specialty carriers.
- Estate Executors:Fiduciaries managing probate jewelry assets with valuation and disposition timing uncertainties. California and New York trust administrators generate concentrated demand for temporary coverage structures.
Individual Owners anchor volume; Collectors drive margin expansion.
Distribution Channel:
Touchpoint preference and advice requirements fragment pathways between human-mediated and digital-native acquisition.
- Direct Sales:Carrier-proprietary channels including call centers and owned digital properties. Chubb and comparable legacy insurers deploy this for established high-net-worth relationships with renewal efficiency.
- Brokers:Independent intermediaries accessing multiple carrier panels for coverage comparison. London and New York specialty brokers dominate ultra-high-value placements requiring manuscript policy negotiation.
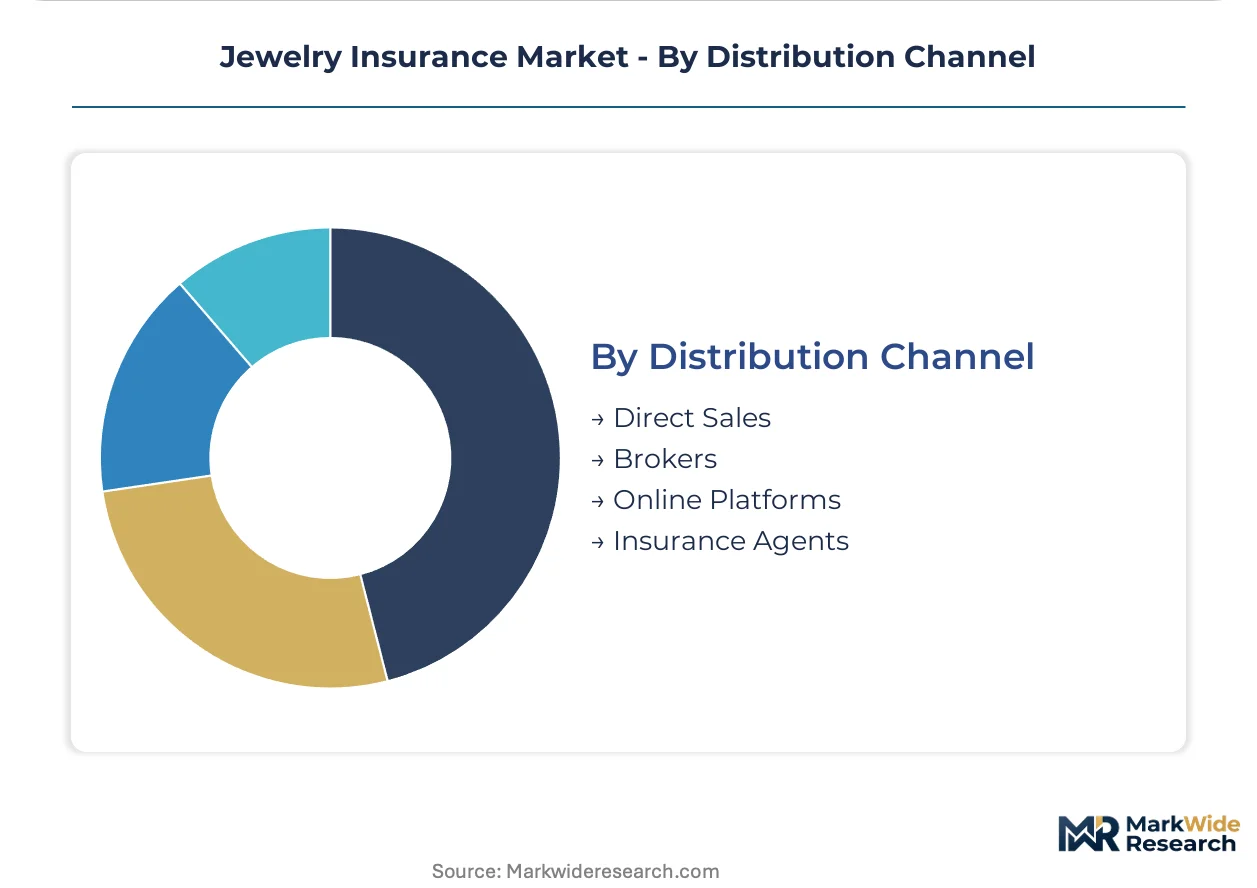
- Online Platforms:Digital-first quoting engines with algorithmic underwriting and instant binding. Millennial and Gen Z collectors across United States coastal metros initiate coverage through mobile-optimized comparison tools.
- Insurance Agents:Captive or independent producers with personal relationship accountability. Secondary metropolitan markets retain this channel preference for moderate-value scheduled policies.
Insurance Agents sustain relationship density; Online Platforms gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified gemological appraisers concentrate in legacy financial centers, creating geographic bottlenecks that constrain carrier expansion into emerging affluent suburbs. This talent distribution shapes underwriting capacity and claims-handling velocity across markets.
United States
High-net-worth households in coastal metropolitan markets drive scheduled coverage demand for heirloom and luxury watch portfolios. State-level department of insurance regulations in New York, California, and Texas mandate divergent replacement-value disclosure standards, complicating multi-jurisdictional policy administration. Miami and Los Angeles anchor specialty carrier competition for affluent household accounts.
Germany
Collectors across Munich and Frankfurt demand itemized scheduled coverage with independent gemological appraisal for unique pieces. The EU AI Act's risk-classification framework mandates algorithmic transparency in automated claims-processing platforms, accelerating vendor consolidation. Hamburg and Düsseldorf concentrate insurtech development for digitized appraisal workflows.
Switzerland
Private banking clients in Zurich and Geneva dominate collector segment demand with multi-jurisdictional coverage requirements for thematic jewelry portfolios. Swissmedic oversight intersects with laser inscription traceability standards for fraud detection in high-value claims. Basel anchors blockchain-based provenance verification development for ultra-high-net-worth underwriting.
United Kingdom
London specialty brokers dominate ultra-high-value placements requiring manuscript policy negotiation for estate executor coverage. The Financial Conduct Authority coordinates disclosure standards that shape reserve requirements across coverage tiers. Mayfair and the City of London concentrate legacy insurer relationships with multi-generational collector families.
United Arab Emirates
MOHAP regulations govern healthcare-adjacent gemological marking systems while Dubai's free zones attract insurtech entrants targeting collector portfolios. Abu Dhabi and Dubai anchor point-of-sale embedded distribution partnerships with luxury retail jeweler networks. The emirates' zero-tax environment concentrates high-net-worth individual owner demand from regional expatriate communities.
Jewelry Insurance Market Competitive Landscape
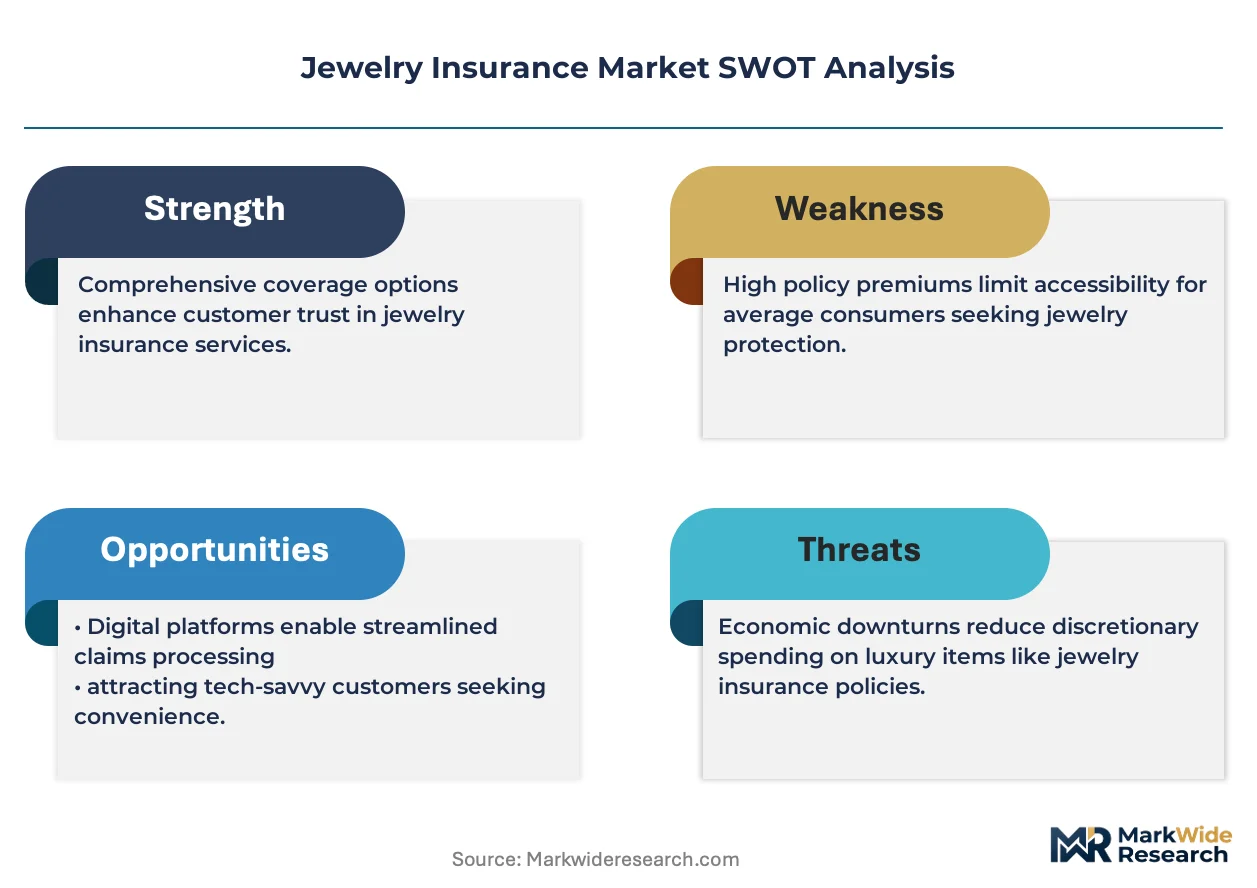
The competitive structure tilts toward specialty carriers with century-old underwriting infrastructure and captive retail distribution networks. Legacy insurers command premium positioning in scheduled coverage through established gemological appraisal relationships, while digital-first entrants compress customer acquisition costs via direct-to-consumer quoting engines. Two strategic archetypes dominate: underwriting-heavy specialists with point-of-sale captive channels, and technology-native platforms with algorithmic risk scoring. Competitive moves concentrate on M&A to acquire appraisal workflow capabilities and strategic partnerships with blockchain provenance registries.
Among underwriting specialists, Chubb and Jewelers Mutual Insurance Company exemplify divergent moat strategies. Chubb leverages its century-old infrastructure to sustain premium positioning across North American and Asian high-value lines. Jewelers Mutual anchors its market position through captive relationships with retail jeweler networks, controlling distribution activation at the point of sale. On the digital-native vector, BriteCo and Zillion occupy positions as algorithmic underwriting platforms targeting millennial and Gen Z collectors through mobile-optimized acquisition channels.
| Leading Market Players |
|---|
| Lavalier |
| Chubb |
| BriteCo |
| JIBNA |
| GemShield |
| Jewelers Mutual Insurance Company |
| Zillion |
| Travelers Insurance |
| WAX Insurance |
| Others |
Supply & Pricing Matrix
EU AI Act compliance mandates are gating qualified supply for automated claims-processing platforms and premium-tier pricing access for carriers with audit-ready algorithmic systems. These regulatory thresholds concentrate underwriting technology procurement among vendors with certified transparency documentation, compressing margins for non-compliant entrants while elevating pricing power for established carriers.
Pricing Analysis
Bundled appraisal-and-coverage packages command premium positioning against unbundled standalone policies where owners source independent gemological certification separately. Three-tier pricing structure across premium, standard, and economy levels separates scheduled coverage with independent valuation from blanket policies with representative sampling and basic homeowners endorsements. Pricing pressure stems from appraisal cost volatility as laboratory capacity constraints in legacy financial centers compress margins on moderate-value scheduled policies. Younger individual owners initiating first coverage through bundled residential policies exhibit highest price sensitivity, while ultra-high-net-worth collectors demonstrate inelastic demand for manuscript scheduled coverage with agreed-value limits.
Supply Chain Analysis
Single-source vulnerability sits with certified gemological appraisers concentrated in New York, London, and Zurich, creating geographic bottlenecks for carrier expansion into emerging affluent suburbs. Underwriting technology draws from insurtech development clusters in Hamburg, Düsseldorf, and Basel for blockchain provenance verification and machine-vision assessment tools. Raw material dependencies include FDA-registered laser inscription systems, distributed ledger infrastructure, and cloud-based claims-processing platforms. Tariff exposure on gemological equipment imports complicates cost forecasting for digitized appraisal workflows. Distribution runs through captive retail jeweler networks, independent broker channels in specialty financial centers, and direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Jewelry insurance functions as a late-cycle quality story as high-net-worth households shift demand toward premium scheduled coverage with independent gemological appraisal for heirloom portfolio transfers.
For Market Incumbents: Hedge against insurtech disintermediation by deepening captive distribution control through exclusive point-of-sale partnerships with luxury retail jeweler networks. Acquire appraisal workflow capabilities through targeted technology investments to reduce dependence on concentrated gemological laboratory capacity in legacy financial centers. Fortify algorithmic transparency documentation to satisfy EU AI Act compliance thresholds and defend European market positioning against audit-ready competitors. For New Entrants and Emerging Players: Enter via underpenetrated blanket coverage segments in secondary United States metropolitan markets where moderate-value collections lack scheduled policy saturation. Target millennial and Gen Z collectors through mobile-optimized direct-to-consumer quoting engines with instant binding capabilities. Deploy generative AI damage assessment tools to compress claims cycle times and differentiate service experience against legacy carrier mainframe limitations. For Investors and Strategic Acquirers: Valuations sit cheapest among algorithmic underwriting platforms with proven customer acquisition efficiency but limited balance sheet capacity for risk retention. Long-term viability over the intermediate horizon rests on acquiring licensed carrier shells or reinsurance partnerships to enable full-stack underwriting. The signal to watch is consolidation momentum around blockchain provenance registry partnerships as carriers race to integrate immutable chain-of-custody documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Immutable audit trails reduce moral hazard exposure for ultra-high-net-worth scheduled coverage. |
| Point-of-Sale Embedded Distribution | Captive retail jeweler partnerships lower customer acquisition costs and deepen policy attachment rates. |
| Generative AI Claims Assessment | Machine-vision triage compresses cycle times for routine damage claims in standard-tier portfolios. |
| EU AI Act Compliance Stack | Algorithmic transparency documentation gates European market access for automated processing platforms. |
| Gemological Appraiser Network Expansion | Geographic diversification beyond legacy financial centers unlocks suburban affluent market penetration. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct a multi-source evidence base for jewelry insurance market dynamics. Primary fieldwork engaged underwriting executives at specialty carriers, gemological laboratory directors, retail jeweler network managers, estate trust administrators, and insurtech platform engineers. Secondary validation drew from National Association of Insurance Commissioners model law databases, state department of insurance filings in New York and California, SEC 10-K disclosures from listed carriers, and EU regulatory transparency documentation. Bottom-up policy volume estimates triangulated against top-down premium pool calculations from industry aggregate data.
Historical reference periods anchored the projection framework against documented market size and growth trajectories across the analysis window. Segmentation modeling incorporated coverage type, policy mechanism, customer archetype, and distribution channel dimensions with geographic regulatory cluster overlays. CAGRs were derived from trend extrapolation adjusted for technology diffusion curves and regulatory implementation timelines. Forecast inputs included digitized appraisal workflow adoption rates, blockchain provenance registry integration milestones, and generative AI claims-processing deployment velocity.
Inputs from carrier regulatory filings and gemological laboratory capacity reports were available through the study window; gaps in real-time policy binding data from digital-first platforms introduce uncertainty bands around channel share estimates. Forecasts reflect documented assumptions regarding EU AI Act implementation pace and state-level valuation methodology harmonization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Germany Property and Casualty Insurance Market
Insurance
India Dental Insurance Market
Insurance
Estonia Property and Casualty Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
Africa Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Earthquake Insurance Market
Insurance
GCC Health Insurance Market
Insurance
Europe Car Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
China Business Income Insurance Market
Insurance
Consumer Electronics Extended Warranty Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Finland Cyber (Liability) Insurance Market