
 5G Monetization Market | 2026-2036
5G Monetization Market Size, Share, and Industry Trends Forecast 2026-2036
5G Monetization Market Outlook
The capital-intensity divergence between cloud-native platform vendors and legacy telecom equipment suppliers is reorganizing competitive hierarchies in 5G monetization. Ericsson leverages its dual-mode 5G core to anchor operator relationships across European markets. Qualcomm differentiates through chipset-level API integration that enables granular service-tier billing for device manufacturers.
5G monetization encompasses the systems, platforms, and business models that translate fifth-generation wireless network capabilities into commercial revenue streams through dynamic pricing, quality-of-service guarantees, and API-driven service exposure to third-party developers. Network slicing partitions a single physical infrastructure into multiple virtual networks with distinct latency, bandwidth, and reliability parameters, enabling telecom operators to sell differentiated connectivity contracts to enterprise clients. Edge computing services command premium positioning within the service type segment as manufacturing and automotive buyers require sub-ten-millisecond processing for real-time automation. The deployment model segment shows structural momentum toward hybrid architectures that blend public network coverage with private network control for industrial campuses and healthcare systems.
The Federal Communications Commission in the United States, the European Telecommunications Standards Institute across EU member states, and Japan's Ministry of Internal Affairs and Communications each enforce spectrum allocation rules and interconnection standards that directly determine which monetization services operators can legally offer and at what price points. China's Ministry of Industry and Information Technology mandates domestic encryption protocols for 5G core networks, creating compliance barriers for foreign platform vendors seeking market access. Stakeholders must monitor evolving national security designations for core network elements, as these classifications increasingly dictate vendor eligibility and service pricing authority across major economies.
Market Dynamics
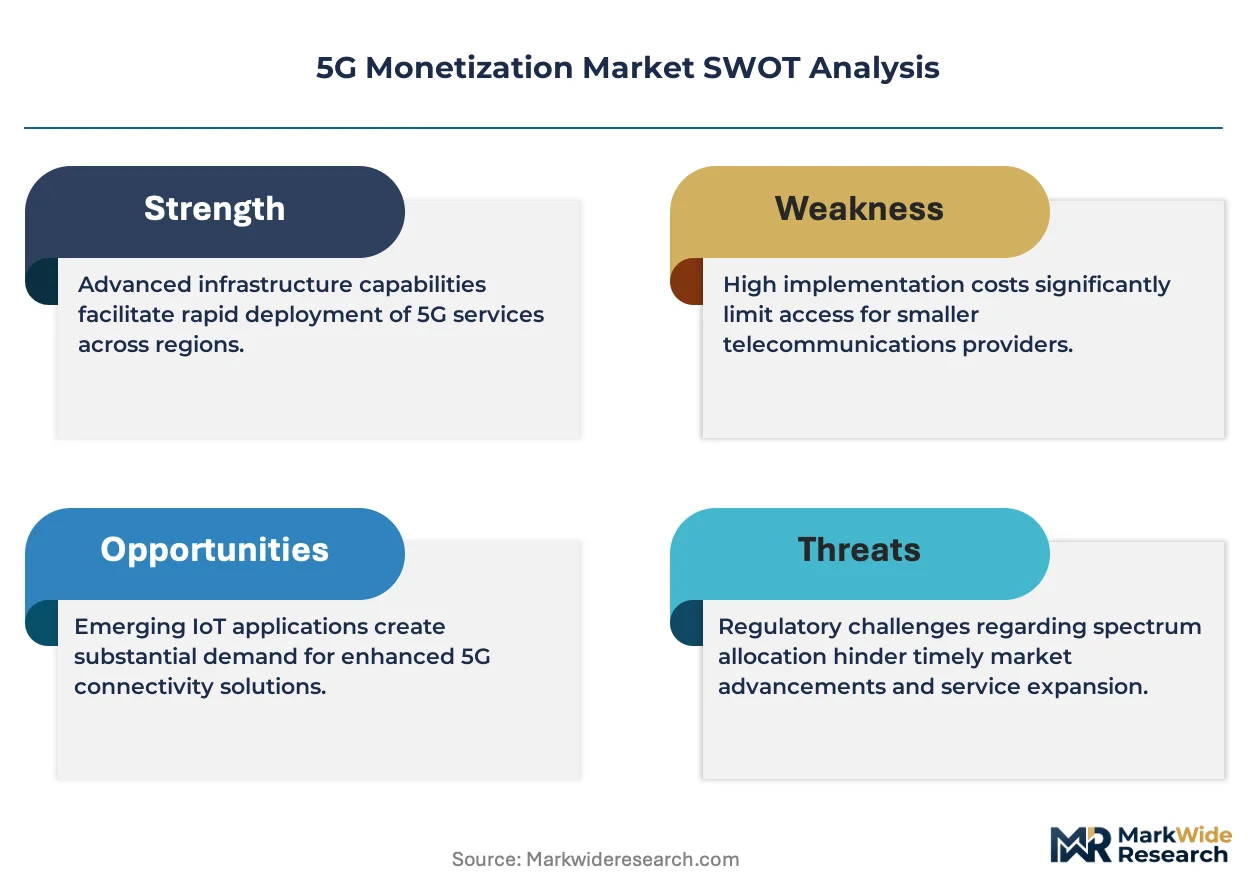
Network slicing infrastructure investments by telecom operators are compressing time-to-revenue cycles for enterprise connectivity contracts, forcing platform vendors to reconfigure pricing architectures around latency guarantees rather than bandwidth tiers.
Growth Catalysts
- EU AI Act compliance mandates:Enterprise buyers across automotive and manufacturing verticals now require auditable quality-of-service documentation, accelerating demand for API-driven monetization platforms that embed regulatory reporting.
- Private 5G deployments:Industrial campuses in Germany, Japan, and South Korea are procuring dedicated network slices for real-time automation, creating captive demand that bypasses public network congestion constraints.
- Edge computing latency requirements:Sub-ten-millisecond processing thresholds for robotic control systems are forcing operators to monetize proximity-based compute nodes as premium service tiers distinct from connectivity.
Market Restraints
- Domestic encryption mandates:China's MIIT protocol requirements for 5G core networks block foreign platform vendors from accessing state-owned operator procurement channels.
- Radio frequency component concentration:Gallium nitride semiconductor supply chains cluster in East Asian foundries, exposing infrastructure buildout timelines to single-source geographic risk.
- Spectrum auction debt service:European operators face sustained balance sheet pressure from mid-band license acquisitions, constraining discretionary spending on monetization software upgrades.
Strategic Opportunities
- Healthcare system hybrid architectures:Hospital networks in France and Italy are piloting blended public-private 5G deployments for surgical robotics, creating first-mover advantage for vendors with medical-grade certification pathways.
- API marketplace standardization:TM Forum Open APIs are converging with 3GPP service exposure frameworks, enabling cross-operator developer ecosystems that abstract network complexity into consumable software interfaces.
- Carbon accounting integration:EU CSRD disclosure requirements position energy-efficient network slicing as a monetizable sustainability feature for enterprise ESG reporting.
Industry Challenges
- Cloud-native talent scarcity:Container orchestration and microservices architecture expertise remains concentrated among Silicon Valley and Bangalore engineering pools, constraining European operator transformation timelines.
- Interoperability certification delays:Multi-vendor core network validation cycles extend 18-24 months, compressing revenue recognition windows for platform deployments.
- Legacy billing system entanglement:Proprietary charging architectures from 3G/4G eras resist API abstraction, forcing parallel infrastructure maintenance during migration periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Monetization Market |
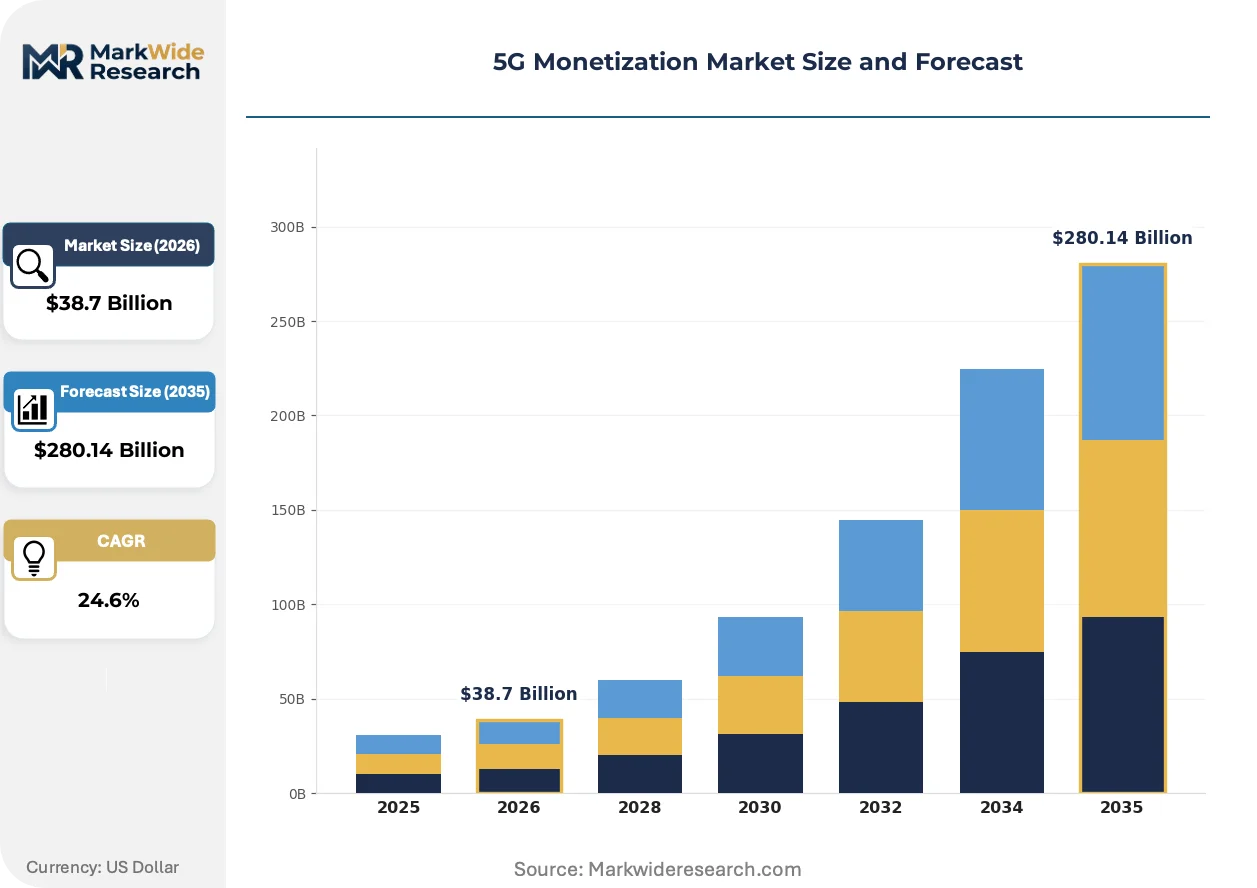
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Slicing, Edge Computing, Enhanced Mobile Broadband, Massive IoT End User: Telecom Operators, Enterprises, Government, Consumer Electronics Pricing Model: Subscription, Pay-per-Use, Freemium, Tiered Pricing Deployment Model: Private Network, Public Network, Hybrid Model, Shared Infrastructure |
| Companies Covered | Ericsson, Nokia, Huawei, Qualcomm, AT&T, Vodafone, Amdocs, IBM Corporation, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Monetization Market Strategic Shifts
Artificial intelligence inference engines are migrating from centralized data centers toward radio access network edge nodes, restructuring where computational value is captured within the 5G service stack.
Containerized network function software is miniaturizing the physical footprint of 5G core components. Manufacturing buyers in South Korea are deploying these compact cores within factory-floor server cabinets. The technology is miniaturizing capital deployment requirements for private network installations, compressing total cost of ownership calculations against Wi-Fi 6E alternatives.
The EU AI Act risk classification framework is mandating algorithmic transparency for automated network optimization systems. Operators must now maintain audit trails for AI-driven resource allocation decisions. German automotive manufacturers are demanding these compliance features as contractual prerequisites for connected vehicle service contracts.
Enterprise procurement teams are unbundling connectivity from platform services, treating 5G as a utility input while negotiating separately for edge computing and API management. Japanese industrial conglomerates are leading this disaggregation, signing direct agreements with hyperscale cloud providers for application-layer services. The shift fragments operator revenue streams and forces price transparency on previously opaque service bundles.
5G Monetization Market Segmentation
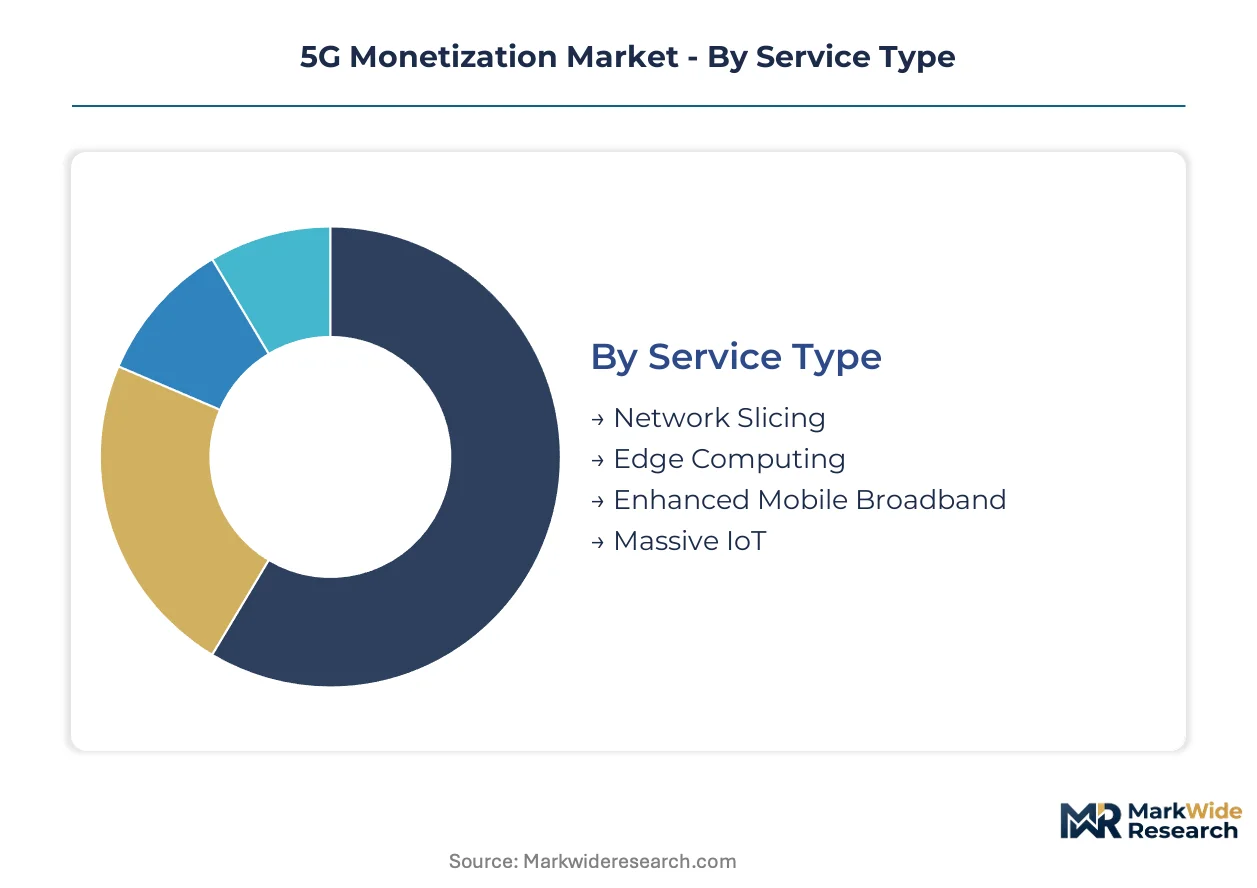
5G monetization architectures diverge sharply across service types and deployment configurations, with enterprise buyers demanding granular control over latency parameters while consumer segments prioritize bandwidth economics. Pricing model selection directly determines platform vendor revenue recognition cycles and operator capital recovery timelines.
Service Type:
Network slicing and edge computing deployments concentrate in Germany, Japan, and South Korea where manufacturing automation drives premium service tier adoption, while enhanced mobile broadband and massive IoT scale through volume-led emerging markets.
- Network Slicing:Virtual network partitioning creates isolated logical networks with guaranteed quality-of-service parameters for mission-critical applications. German automotive manufacturers procure dedicated slices for connected vehicle platforms, with EU AI Act compliance mandates accelerating audit-ready deployment documentation.
- Edge Computing:Distributed compute nodes positioned at radio access network boundaries enable sub-ten-millisecond processing for real-time industrial control. South Korean semiconductor fabs and Japanese robotics clusters anchor current demand, with latency guarantees commanding price premiums over raw connectivity.
- Enhanced Mobile Broadband:High-throughput consumer and enterprise data services leveraging millimeter-wave and mid-band spectrum allocations.
- Massive IoT:Low-power wide-area connectivity for sensor networks and industrial telemetry with minimal bandwidth requirements.
Network slicing holds the largest share; momentum sits with edge computing.
End User:
Enterprise procurement teams now unbundle connectivity from platform services, treating 5G as utility infrastructure while negotiating separately for API management and compute layers.
- Telecom Operators:Traditional service providers monetizing infrastructure through wholesale network exposure and retail service packaging. European operators face spectrum auction debt service constraints that compress discretionary software upgrade budgets.
- Enterprises:Industrial campuses and corporate campuses procuring private network slices or hybrid deployments for operational technology integration. Manufacturing verticals in Germany and Japan lead contract volumes.
- Government:Public sector agencies requiring secure, sovereign-controlled connectivity for critical infrastructure and emergency services.
- Consumer Electronics:Device manufacturers integrating chipset-level APIs for granular service-tier billing and quality-of-service negotiation.
Telecom operators retain revenue concentration; enterprises are expanding most quickly.
Pricing Model:
Subscription architectures dominate recurring revenue recognition, though pay-per-use models align vendor incentives with actual enterprise consumption patterns.
- Subscription:Fixed recurring fees for guaranteed service levels with predictable operator cash flows. Japanese industrial conglomerates favor multi-year commitments with embedded service-level agreement penalties.
- Pay-per-Use:Consumption-based metering tied to actual data throughput, compute cycles, or API call volumes. German manufacturing buyers prefer this structure for variable production schedules.
- Freemium:Tiered entry points with basic connectivity at zero marginal cost and premium features gated behind paid upgrades.
- Tiered Pricing:Discrete service bundles with bronze-silver-gold differentiation across latency, bandwidth, and reliability parameters.
Subscription models dominate current bookings; pay-per-use is climbing the fastest.
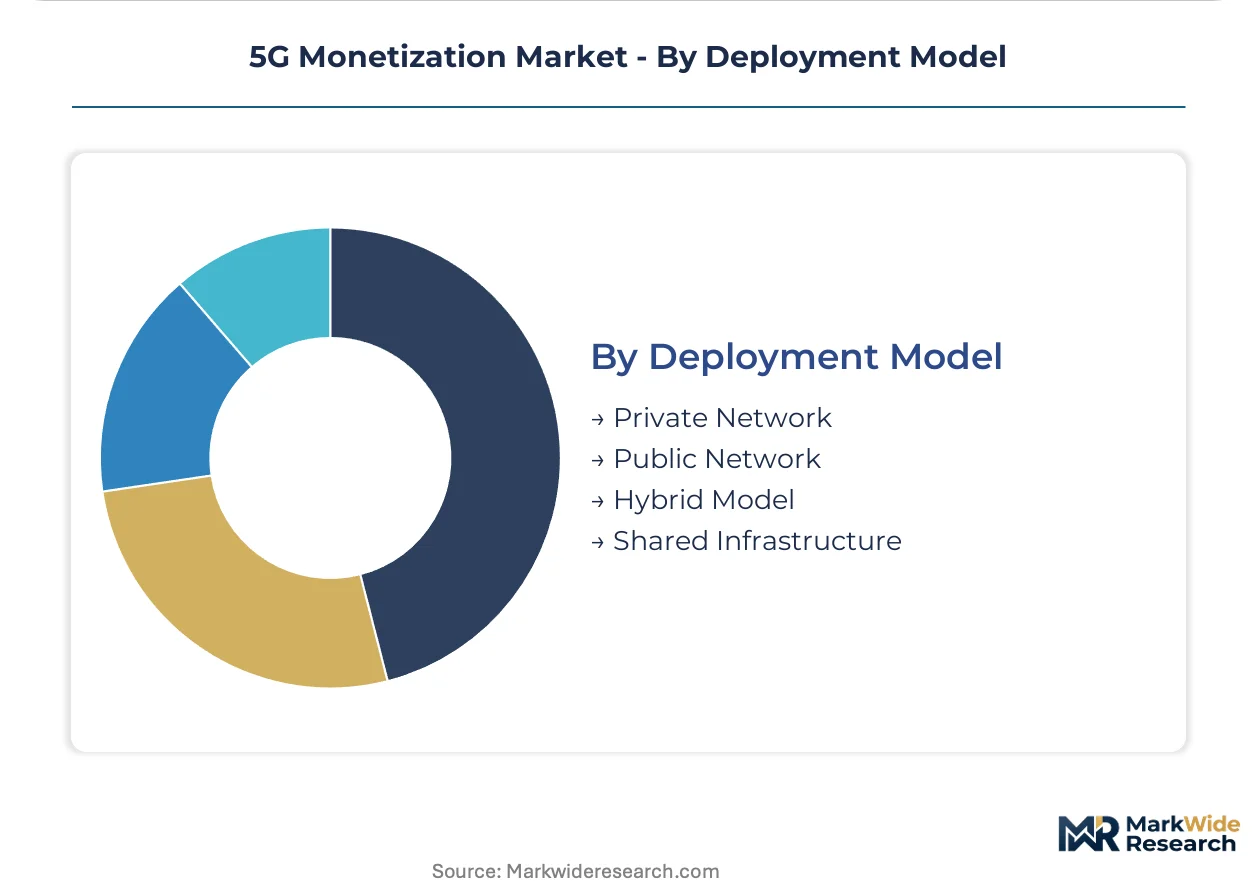
Deployment Model:
Hybrid architectures blend public network coverage economies with private network control requirements, particularly for healthcare systems and industrial campuses.
- Private Network:Dedicated spectrum and infrastructure with complete enterprise control over security and quality-of-service configuration. France and Italy pilot hospital networks for surgical robotics.
- Public Network:Shared operator infrastructure with standard service level agreements and national roaming coverage.
- Hybrid Model:Blended architectures using public network for wide-area coverage and private slices for critical campus operations. South Korean manufacturing deployments favor this structure.
- Shared Infrastructure:Multi-tenant network functions virtualization enabling cost distribution across multiple enterprise tenants.
Hybrid models are gaining share fastest; private networks command premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in 5G monetization platforms favor vendors with established operator relationships in spectrum-rich jurisdictions. Net importers of network infrastructure software concentrate procurement authority in national telecom regulators. Trade balances shift as domestic encryption mandates in key markets redirect vendor eligibility toward local champions.
United States
Enterprise private network deployments drive platform demand across manufacturing corridors in Michigan and Ohio. The FCC enforces spectrum allocation rules and interconnection standards that determine which monetization services operators can legally offer. Dallas-Fort Worth anchors AT&T's network slicing pilot programs for industrial automation clients.
Germany
Automotive manufacturers procure dedicated network slices for connected vehicle platforms with stringent latency requirements. The EU AI Act mandates auditable quality-of-service documentation for automated network optimization systems. Stuttgart and Wolfsburg industrial clusters lead contract volumes for manufacturing automation.
China
State-owned operators dominate procurement channels with mandated domestic encryption protocols blocking foreign platform access. MIIT requirements for 5G core networks create compliance barriers for international vendors. Shenzhen and Beijing concentrate R&D investment in containerized network function miniaturization.
Japan
Industrial conglomerates unbundle connectivity from platform services, negotiating directly with hyperscale cloud providers. METI standards guide spectrum efficiency benchmarks for enterprise slice deployments. Nagoya and Osaka manufacturing hubs pilot hybrid public-private architectures for robotics clusters.
South Korea
Semiconductor fabs and robotics clusters anchor demand for sub-ten-millisecond edge computing services. National spectrum policy prioritizes industrial automation use cases in mid-band allocations. Seoul Capital Area and Busan-Ulsan corridor drive private 5G deployment density for smart factory integration.
5G Monetization Market Competitive Environment
Concentration sits with legacy telecom equipment suppliers holding established operator relationships across European and Asian markets. The vendor base spans three strategic tiers: integrated infrastructure-hardware platforms, cloud-native software specialists, and chipset-level API enablers. Competitive dynamics center on dual-mode core certification cycles and developer ecosystem expansion through standardized service exposure frameworks.
Within the integrated infrastructure tier, Ericsson and Nokia exemplify vendors anchoring operator procurement decisions through dual-mode 5G core deployments. Qualcomm occupies a distinct position at the chipset level, enabling granular service-tier billing architectures for device manufacturers. These three entities represent the dominant competitive archetypes: European infrastructure incumbents, Nordic network specialists, and American semiconductor-API integrators.
| Leading Market Players |
|---|
| Ericsson |
| Nokia |
| Huawei |
| Qualcomm |
| AT&T |
| Vodafone |
| Amdocs |
| IBM Corporation |
| Microsoft |
| Others |
Value Chain & Pricing Dynamics
Long-term network slice reservation contracts lock in both supply access for telecom operators and price visibility for enterprise buyers across German automotive and South Korean semiconductor verticals. These structures embed latency guarantee premiums that compress margin elasticity for platform vendors facing EU AI Act compliance cost absorption.
Pricing Analysis
Industrial OEM buyers anchor subscription-dominant pricing structures with consumption-based overlays for variable production schedules. Price differentiation centers on latency certification tiers and edge compute proximity, with sub-ten-millisecond guarantees commanding substantial premiums over standard connectivity. Pricing pressure stems from spectrum auction debt service constraining European operator discretionary spend on software upgrades. German manufacturing buyers exhibit lowest price sensitivity due to automation downtime costs, while emerging market telecom operators face acute budget compression.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for gallium nitride semiconductor components critical to radio access network infrastructure. Manufacturing concentration centers on Taiwan, South Korea, and Japan for advanced RF semiconductors, with Chinese domestic encryption protocols blocking foreign vendor participation in state-owned procurement channels. Single-source geographic risk in East Asian foundries threatens infrastructure buildout timelines. Distribution runs through operator-direct procurement with hyperscale cloud provider bypass emerging in Japanese industrial conglomerate segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around spectrum licensing and domestic encryption mandates creates durable barriers to competitive displacement.
For Market Incumbents: Shield core network relationships through accelerated dual-mode 5G core certification cycles that outpace multi-vendor interoperability validation timelines. Deepen API marketplace integration with TM Forum Open APIs to raise switching costs for enterprise developers. Vertical integration into containerized network function miniaturization addresses cloud-native talent scarcity threatening European operator transformation velocity. For New Entrants and Emerging Players: Differentiate on healthcare system hybrid architecture deployments where medical-grade certification pathways remain underdeveloped relative to manufacturing verticals. Target French and Italian hospital network pilots for surgical robotics as the most penetrable segment with limited incumbent lock-in. Pursue direct hyperscale cloud provider partnerships to bypass operator-controlled distribution channels fragmenting in Japan. For Investors and Strategic Acquirers: Cloud-native software specialists with container orchestration expertise concentrated in Silicon Valley and Bangalore engineering pools represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory compliance automation capabilities embedding EU AI Act audit trail functionality. Watch for spectrum auction debt service stress indicators among European operators as inflection signals for distressed monetization platform procurement opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| API Marketplace Standardization | TM Forum Open API convergence with 3GPP frameworks enables cross-operator developer ecosystem expansion. |
| Edge Computing Node Deployment | Sub-ten-millisecond proximity compute installations capture premium pricing from South Korean semiconductor fabs. |
| Healthcare Certification Pathway Investment | Medical-grade hybrid architecture qualification opens French and Italian surgical robotics procurement channels. |
| Carbon Accounting Integration | EU CSRD disclosure requirements position energy-efficient network slicing as monetizable ESG reporting features. |
| Containerized Core Miniaturization | Factory-floor server cabinet deployments compress total cost of ownership against Wi-Fi 6E alternatives in manufacturing. |
Study Parameters
A spread of perspectives from telecom network planning executives, enterprise procurement directors, regulatory affairs specialists, and cloud platform engineers converged on the working assumptions underlying this analysis. Primary intelligence combined structured interviews with secondary validation through FCC spectrum allocation records, ETSI standardization documents, MIIT encryption protocol filings, and operator capex disclosure statements. Bottom-up service type segmentation triangulated against top-down regional demand aggregation.
Segmentation dimensions modeled encompass service type, deployment architecture, pricing structure, end-user vertical, and geographic regulatory cluster across the projection horizon. CAGRs derived from logistic curve fitting to historical infrastructure investment patterns with adjustment for spectrum auction timing and enterprise private network procurement cycle acceleration. Industry-specific forecast inputs incorporated EU AI Act compliance cost absorption curves and containerized network function adoption rates in manufacturing verticals.
Material uncertainties — spectrum auction schedule shifts, domestic encryption mandate expansions, gallium nitride supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding enterprise unbundling velocity and hyperscale cloud provider channel bypass penetration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Relay Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Global Premium A2P and P2A Messaging Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Russia ICT Market
Telecommunications
IP Telephony Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Cellular Modem Market
Telecommunications
Denmark Telecom Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Mexico MNVO Market