
 Voice Communication Control System Market | 2026-2036
Voice Communication Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Voice Communication Control System Market Intelligence
F-Gas Regulation compliance is hardening the cost-of-entry calculus for analog system manufacturers across European aviation markets. Rohde & Schwarz GmbH & Co. KG leverages its integrated test and measurement heritage to anchor premium positioning in digital air traffic control consoles. Frequentis AG specializes in mission-critical communication architectures for airport and emergency response applications. Thales Group competes through sustained defense-sector relationships and cross-border NATO standardization contracts.
A voice communication control system integrates hardware switch matrices, software-defined routing layers, and human-machine interface panels to manage multiple simultaneous audio channels with sub-50-millisecond latency for air traffic, maritime, and emergency coordination operators. IP-based control systems capture the fastest expansion as aviation authorities phase out circuit-switched infrastructure, while hybrid architectures retain significant installed-base maintenance revenue through the transition window. Codec integration and noise cancellation technologies concentrate margin pools where military specification requirements exceed commercial aviation thresholds.
FAA NextGen mandates and EUROCONTROL interoperability standards shape product roadmaps for North American and European suppliers, while China's CAAC and GB standards create parallel certification pathways for domestic champions. Defense Forces procurement through NATO STANAG frameworks and national security classifications adds a compliance layer that narrows vendor qualification lists. Stakeholders must monitor spectrum reallocation decisions and quantum-resistant encryption timelines as these will determine replacement cycles for installed command and control infrastructure.
Market Dynamics
The migration from circuit-switched to IP-based architectures is compressing replacement cycles across air traffic management, maritime coordination, and defense command infrastructure. This technology transition is redrawing supplier qualification criteria and concentrating procurement authority among digital-native system integrators.
Growth Catalysts
- EU F-Gas Regulation:Mandates for refrigerant phase-down in cooling systems are forcing aviation authorities to replace aging analog consoles with modern digital alternatives that eliminate legacy thermal management dependencies.
- FAA NextGen:The Federal Aviation Administration's modernization framework is accelerating procurement of voice-over-IP control systems with integrated data link capabilities across US terminal radar approach control facilities.
- Sub-50ms latency requirements:Military specification thresholds for command-and-control response times are expanding addressable market scope beyond commercial aviation into naval and ground-force coordination centers.
Market Restraints
- Semiconductor supply concentration:Specialized FPGA and DSP components for real-time audio processing depend heavily on Taiwanese foundry capacity, exposing lead time volatility.
- NATO STANAG compliance costs:Defense-sector encryption and interoperability certifications impose multi-year qualification timelines that exclude smaller system vendors.
- Hybrid architecture maintenance:Transitional installations requiring simultaneous analog circuit and IP packet support create persistent service revenue drag without corresponding hardware margin.
Strategic Opportunities
- China CAAC domestic certification:Parallel GB standards pathways for voice communication systems create protected demand pools for locally qualified suppliers as airport construction accelerates.
- Quantum-resistant encryption mandates:Emerging national security timelines for post-quantum cryptographic standards will force premature replacement of installed command infrastructure.
- Maritime autonomous vessel coordination:Shore-based remote operation centers for unmanned shipping require redundant voice-data integration beyond traditional port authority configurations.
Industry Challenges
- Real-time systems engineering talent:Expertise in deterministic audio routing with guaranteed latency bounds is concentrating among defense contractors and aging specialist workforces.
- Legacy analog integration complexity:Backward compatibility requirements for existing microphone arrays, headset standards, and recorder interfaces extend deployment timelines and escalate field engineering costs.
- Multi-standard certification parallelism:Simultaneous pursuit of FAA, EUROCONTROL, and military security classifications fragments R&D resources and delays product release windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice Communication Control System Market |
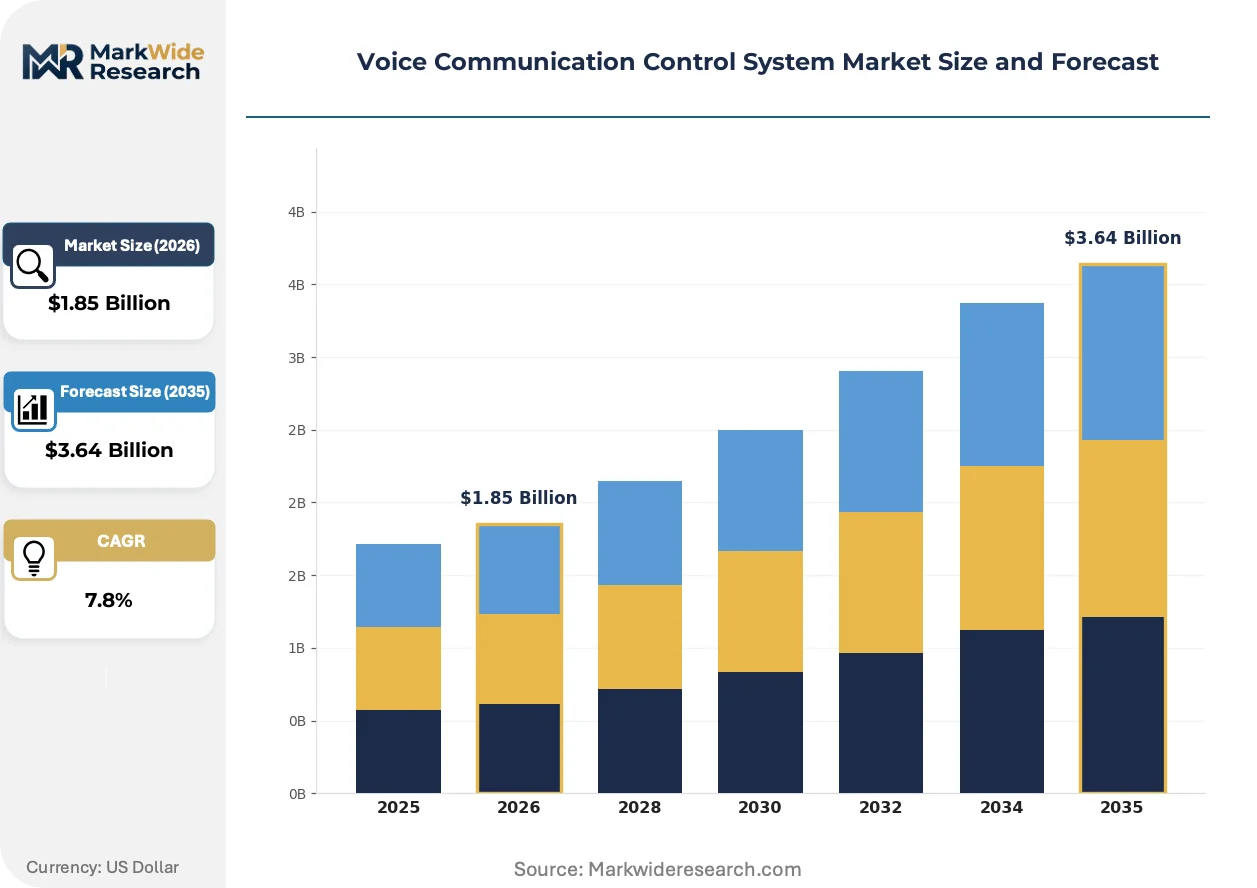
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.64 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Control Systems, Digital Control Systems, IP-based Control Systems, Hybrid Control Systems Technology: Voice Recognition, Signal Processing, Noise Cancellation, Speech Enhancement, Codec Integration Application: Aviation Communication, Emergency Response Coordination, Maritime Communication, Command & Control Centers End User: Public Safety Agencies, Defense Forces, Transportation Authorities, Industrial Facilities |
| Companies Covered | Rohde & Schwarz GmbH & Co. KG, Indra Sistemas, S.A., Frequentis AG, Honeywell International Inc., Saab AB, Thales Group, S.I.T.T.I. SpA, Northrop Grumman Corporation, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice Communication Control System Market Strategic Shifts & Innovations
Software-defined architectures are dissolving the boundary between hardware switch matrices and application-layer routing intelligence. This convergence is enabling feature deployment through firmware updates rather than physical replacement, altering long-term vendor-customer relationships.
Artificial intelligence-based noise cancellation and speaker identification is integrating into control room consoles, replacing discrete DSP hardware with trained neural models running on standard compute platforms. European air navigation service providers are piloting these capabilities at high-density hubs including London Heathrow and Frankfurt. The technology is compressing hardware bill-of-materials while raising software maintenance contract values.
EUROCONTROL interoperability standards and the EU's F-Gas Regulation are jointly accelerating console replacement programs across member states. The regulatory combination mandates both digital functionality and thermal efficiency improvements that legacy analog systems cannot satisfy. Germany's DFS and France's DSNA are consolidating procurement specifications to reduce supplier qualification overhead.
Consolidated procurement frameworks are displacing individual airport authority purchasing across major aviation markets. ANSPs in the United States, Germany, and China are centralizing voice communication system acquisition through multi-site framework agreements. This concentration favors suppliers with established service networks and long-term spare parts commitments over point-solution vendors.
Voice Communication Control System Market Segmentation
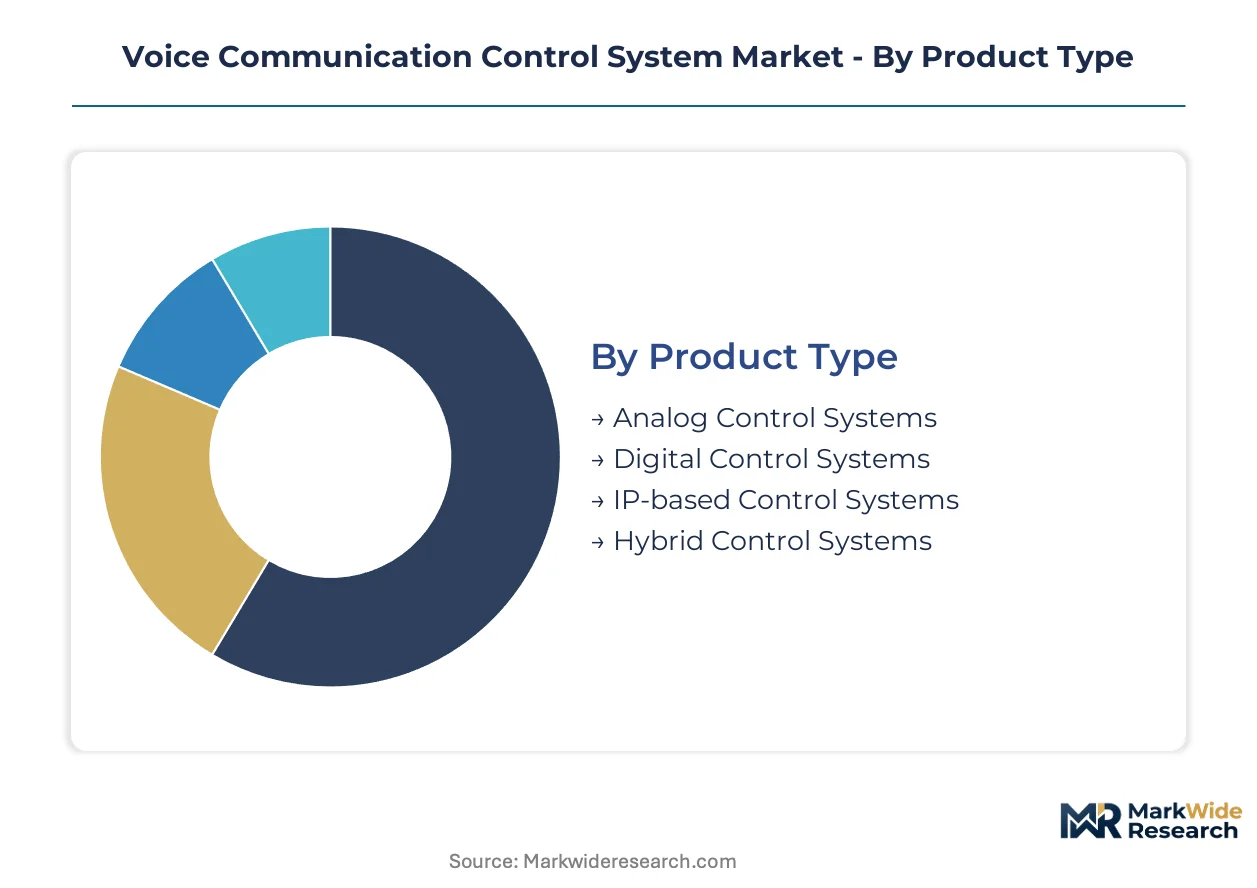
Voice communication control systems fragment across four interlocking dimensions that determine procurement specifications, certification pathways, and vendor qualification requirements. Product architecture choices lock in decades-long infrastructure commitments, while technology integration depth separates premium defense contracts from commercial aviation deployments.
Product Type:
Standardization tightens from fully proprietary analog consoles through modular IP-native platforms, with customization latitude inversely tracking thermal efficiency compliance.
- IP-based Control Systems:Native packet-switched architectures eliminate circuit-switching hardware through software-defined routing layers. German DFS and French DSNA procurement frameworks prioritize these systems for high-density air traffic hubs under combined EUROCONTROL interoperability and F-Gas Regulation mandates.
- Digital Control Systems:Discrete hardware switch matrices with deterministic latency bounds serve transitional installations requiring legacy recorder compatibility. United States terminal radar approach control facilities favor these for FAA NextGen phased upgrades.
- Hybrid Control Systems:Simultaneous analog circuit and IP packet support extends service revenue through transition windows without corresponding hardware margin expansion.
- Analog Control Systems:Legacy thermal management dependencies face forced obsolescence under refrigerant phase-down regulations.
Leading the category by volume: Digital Control Systems. Growing fastest: IP-based Control Systems.
Technology:
Integration depth stratifies from discrete hardware components through neural-model software layers, with cost tier rising alongside real-time processing guarantees.
- Signal Processing:FPGA and DSP architectures for deterministic audio routing concentrate expertise among defense contractors with guaranteed sub-50-millisecond latency specifications. Military command-and-control centers in NATO member states drive qualification timelines that exclude smaller vendors.
- Noise Cancellation:Artificial intelligence-based neural models replace discrete hardware at London Heathrow and Frankfurt pilot installations, compressing bill-of-materials while elevating software maintenance contract values.
- Codec Integration:Compression-decompression standards determine interoperability between national air navigation service providers.
- Voice Recognition:Speaker identification capabilities integrate into control room consoles for authentication logging.
- Speech Enhancement:Real-time audio clarity optimization supports high-stress emergency coordination environments.
Highest margin concentration: Signal Processing. Steepest expansion trajectory: Noise Cancellation.
Application:
Operational criticality scales from routine port authority communications through multi-domain military coordination, with certification burden tracking consequence severity.
- Aviation Communication:Air traffic management consoles integrate voice-over-IP with data link capabilities under FAA and EUROCONTROL standardization. Germany, the United States, and China concentrate procurement authority through multi-site framework agreements.
- Command & Control Centers:Defense-sector installations require NATO STANAG encryption and multi-year security classifications that narrow vendor qualification lists to established service networks.
- Emergency Response Coordination:Public safety dispatch centers demand redundant failover architectures for disaster scenarios.
- Maritime Communication:Shore-based remote operation centers for autonomous vessels require redundant voice-data integration beyond traditional port configurations.
Dominant revenue share: Aviation Communication. Emerging demand pool: Maritime Communication.
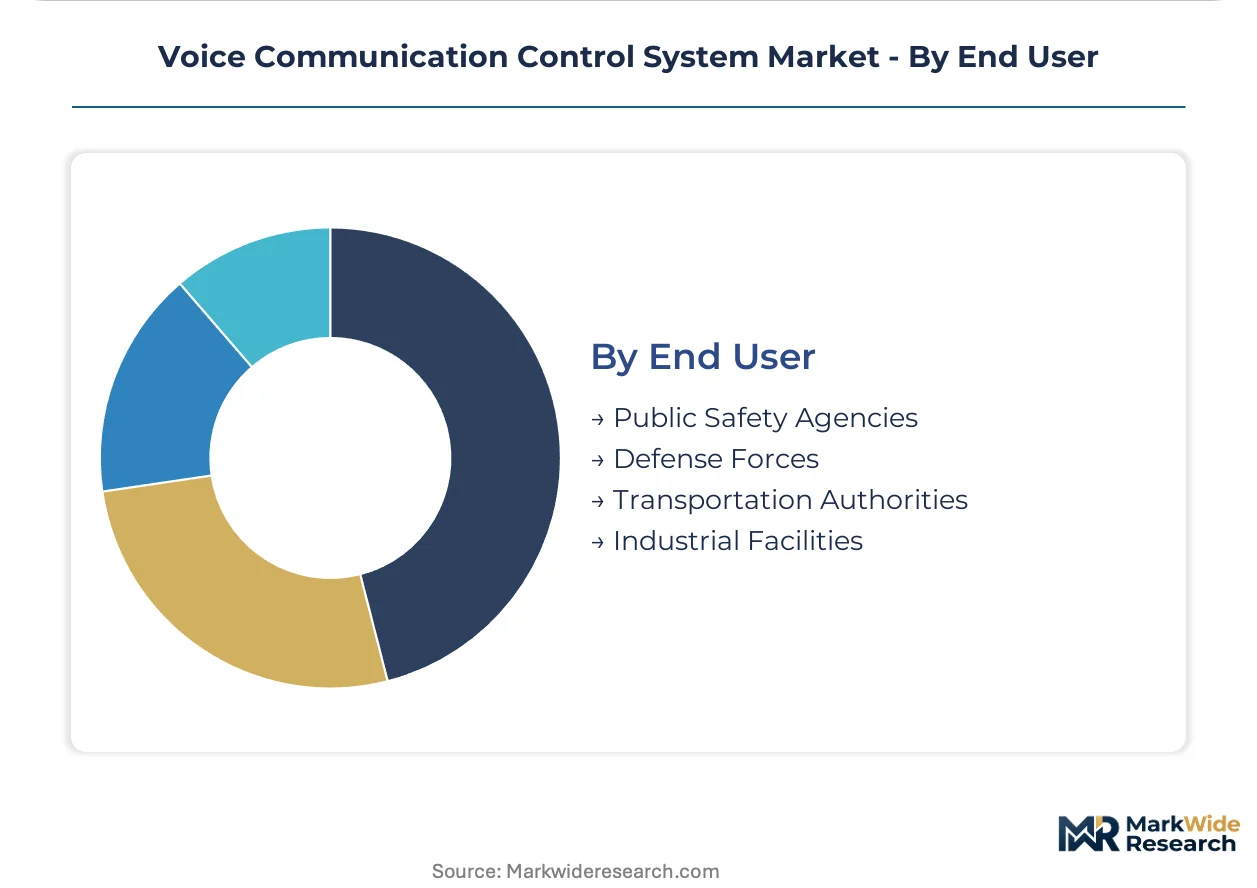
End User:
Procurement authority concentrates from fragmented industrial facilities through centralized defense and transportation hierarchies, with contract duration inversely tracking customer dispersion.
- Defense Forces:National security classifications and post-quantum cryptographic mandates force premature replacement cycles for installed command infrastructure. Procurement runs through NATO frameworks and bilateral national agreements.
- Transportation Authorities:Air navigation service providers in the United States, Germany, and China consolidate acquisition through centralized frameworks favoring long-term spare parts commitments.
- Public Safety Agencies:Emergency dispatch modernization programs drive regional procurement clusters.
- Industrial Facilities:Process control and coordination centers represent dispersed lower-volume demand with reduced certification requirements.
Longest contract durations: Defense Forces. Fastest procurement velocity: Transportation Authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones and aviation cluster incentives in Germany, the United States, and China are concentrating procurement authority for voice communication control systems. Air navigation service providers in these jurisdictions consolidate multi-site framework agreements that favor established service networks.
United States
FAA NextGen mandates drive terminal radar approach control upgrades across high-density corridors. The Federal Aviation Administration requires integrated voice-over-IP with data link capabilities at facilities handling over 500,000 annual operations. Chicago O'Hare and Dallas-Fort Worth anchor procurement concentration for digital console replacement programs.
Germany
DFS Deutsche Flugsicherung consolidates acquisition specifications for high-density hubs under combined EUROCONTROL and F-Gas Regulation timelines. The refrigerant phase-down mandates eliminate legacy analog thermal management dependencies. Frankfurt and Munich airport clusters coordinate centralized procurement frameworks reducing supplier qualification overhead.
China
CAAC domestic certification pathways create protected demand pools as airport construction accelerates under national infrastructure targets. GB standards for voice communication systems run parallel to international certification routes. Beijing Daxing and Shanghai Pudong anchor procurement concentration for IP-native control system deployment.
France
DSNA procurement consolidation aligns with EUROCONTROL interoperability mandates and thermal efficiency regulations. The national air navigation service provider coordinates multi-site framework agreements reducing vendor fragmentation. Paris Charles de Gaulle and Lyon-Saint Exupéry anchor digital console replacement timelines.
United Kingdom
NATS procurement frameworks prioritize EUROCONTROL-compliant digital architectures for high-density North Atlantic corridor management. The air navigation service provider coordinates multi-site spare parts commitments favoring long-term service networks. London Heathrow and Manchester anchor control room modernization programs.
Voice Communication Control System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across defense, aviation, and emergency response verticals. Market structure concentrates procurement authority among digital-native system integrators with established NATO STANAG qualification histories. Three archetypes dominate: defense contractors leveraging security classifications, aviation specialists anchoring air traffic management frameworks, and diversified electronics groups cross-selling from test and measurement heritage. Competitive moves center on multi-year service contract capture and quantum-resistant encryption capability positioning.
Within the defense-contractor archetype, Northrop Grumman Corporation and L3Harris Technologies, Inc. occupy positions shaped by sustained national security relationships and cross-border NATO standardization contracts. Among European aviation specialists, Frequentis AG and S.I.T.T.I. SpA exemplify mission-critical communication architectures for airport and emergency response applications. Rohde & Schwarz GmbH & Co. KG anchors the diversified electronics tier, representing integrated test and measurement heritage applied to premium digital air traffic control console positioning.
| Leading Market Players |
|---|
| Rohde & Schwarz GmbH & Co. KG |
| Indra Sistemas, S.A. |
| Frequentis AG |
| Honeywell International Inc. |
| Saab AB |
| Thales Group |
| S.I.T.T.I. SpA |
| Northrop Grumman Corporation |
| L3Harris Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
EUROCONTROL interoperability mandates and F-Gas Regulation timelines are compressing procurement cycles for air navigation service providers, forcing suppliers to pre-position inventory and absorb carrying costs that pass through as lead-time premiums or volume discounts.
Pricing Analysis
Lead-time premiums dominate pricing differentiation in voice communication control systems, with urgent FAA NextGen deployment schedules commanding 15-25% uplifts over standard delivery windows. Three-tier pricing structure across NATO STANAG-certified, EUROCONTROL-compliant, and non-certified economy tiers separates defense contractors from commercial aviation specialists. Cost compression in hybrid architecture maintenance tiers is intensifying because transitional installations generate service revenue without hardware margin expansion. Transportation authorities in Germany and the United States exhibit lowest price sensitivity due to consolidated framework agreements, while fragmented industrial facilities drive hardest bargain negotiations.
Supply Chain Analysis
Freight costs for specialized FPGA and DSP components from Taiwanese foundries are elevating landed costs for European and North American system integrators dependent on just-in-time manufacturing models. Supply concentration centers on Taiwan for semiconductor fabrication, Germany for precision mechanical assemblies, and the United States for encryption-grade processors. Raw material dependencies include gallium nitride substrates for RF components, high-reliability capacitors for avionics specifications, and rare earth elements for magnetics. Single-source vulnerability in Taiwanese foundry capacity exposes lead time volatility. Distribution runs through direct OEM relationships with air navigation service providers and defense procurement frameworks rather than channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voice communication control systems are undergoing a forced technology transition as IP-native architectures displace circuit-switched legacy infrastructure, compressing replacement cycles and redrawing supplier qualification criteria.
For Market Incumbents: Hedge against semiconductor supply concentration by securing alternative foundry relationships in South Korea and Japan while accelerating software-defined feature deployment to reduce hardware bill-of-materials exposure. NATO STANAG compliance investments create defensive moats against emerging entrants lacking multi-year security classification histories. Backward integration into FPGA design capabilities reduces dependency on Taiwanese supply volatility.
For New Entrants and Emerging Players: Launch via maritime autonomous vessel coordination applications where shore-based remote operation centers demand redundant voice-data integration beyond traditional port authority configurations and incumbent penetration remains shallow. China's CAAC domestic certification pathway offers the most penetrable geography given parallel GB standards and protected demand pools from airport construction acceleration. Target emergency response coordination segments with simplified certification requirements compared to aviation or defense verticals.
For Investors and Strategic Acquirers: The window for entry favors software-defined specialists with AI-based noise cancellation capabilities and established EUROCONTROL qualification histories. Long-term viability hinges on positioning for quantum-resistant encryption mandate cycles that will force premature replacement of installed command infrastructure. Monitor FAA spectrum reallocation decisions as the critical inflection signal for next-generation procurement timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Migration | Firmware-based feature deployment reduces hardware replacement frequency and elevates recurring software maintenance contract values. |
| Post-Quantum Cryptography Certification | Early positioning against NIST standards timelines captures defense-sector replacement cycles before competitor qualification completion. |
| Maritime Remote Operation Center Integration | Autonomous vessel coordination requirements extend addressable market beyond saturated aviation communication verticals. |
| Consolidated Procurement Framework Capture | Multi-site agreements with German DFS and French DSNA reduce customer acquisition costs and lock in decade-long service commitments. |
| AI-Based Noise Cancellation Pilot Expansion | Neural model deployment at London Heathrow and Frankfurt validates technology for broader EUROCONTROL hub adoption. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with air traffic control system procurement officers, defense contractor program managers, ANSP technology directors, and semiconductor supply chain specialists. FAA NextGen implementation schedules, EUROCONTROL interoperability specifications, and NATO STANAG framework documents provided validation benchmarks. Customs records on FPGA and DSP import flows, combined with EU F-Gas Regulation compliance filings, informed supply-side concentration assessments. Bottom-up segment sizing triangulated against top-down aviation infrastructure spending forecasts.
Granularity-level modeling addressed product architecture transitions from analog through hybrid to IP-native systems, technology integration depth from discrete hardware through neural software layers, application criticality from port authority through multi-domain military coordination, and end-user procurement concentration from fragmented industrial facilities through centralized defense hierarchies. CAGRs derived from replacement cycle compression analysis and regulatory mandate timing across the analysis window. Deterministic latency specification evolution and quantum-resistant encryption standard timelines served as industry-specific forecast inputs.
Semiconductor supply disruptions, spectrum reallocation delays, and post-quantum cryptographic standard revisions are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Esim Subscription Market
Telecommunications
LTE and 5G NR-Based CBRS Networks Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
5G RAN Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
Dialer Market
Telecommunications
SIP Trunking Services Market
Telecommunications
Video Door Phones Market
Telecommunications
Finland Telecom Market
Telecommunications
Mexico MNVO Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Telecom Services Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Fixed LTE Market