
 Hong Kong Telecom Market | 2026-2036
Hong Kong Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Telecom Market Outlook
Hong Kong's telecom infrastructure is consolidating around fiber densification and 5G standalone core deployments. HKT leverages its legacy copper-to-fiber migration program to sustain enterprise ARPU in Central and Tsim Sha Tsui business districts. China Mobile Hong Kong anchors mainland corridor traffic through its cross-border submarine cable landing rights. HKBN competes on price-transparent gigabit broadband with self-owned last-mile fiber assets.
Hong Kong telecom encompasses fixed-line, mobile, broadband, and satellite services delivered over 4G, 5G, fiber optic, and legacy DSL infrastructure with spectrum assignments managed through competitive bidding processes. Mobile service generates the highest revenue intensity per subscriber, while fiber optic deployment commands capital allocation priority due to latency-sensitive enterprise demand. Broadband penetration among residential end users approaches saturation, shifting provider focus toward SMEs and large enterprises requiring symmetric upload-download SLAs. Bundled packages dominate consumer pricing models, though prepaid mobile retains traction among transient worker populations.
The Office of the Communications Authority enforces net neutrality principles and spectrum utilization mandates that shape infrastructure investment timelines. TRAI-aligned technical standards for cross-border interconnectivity influence mainland-Hong Kong data routing architecture. Stakeholders must monitor spectrum auction schedules and building access regulations for in-building wireless systems to anticipate competitive positioning shifts.
Market Dynamics
Private 5G network deployments by financial services firms are compressing infrastructure upgrade cycles while the Office of the Communications Authority's spectrum reallocation policy accelerates mmWave commercialization timelines.
Growth Catalysts
- Enterprise fiber densification:Low-latency trading infrastructure requirements from financial services firms are pulling capital into Central and Tsim Sha Tsui business districts.
- Cross-border submarine cable expansion:Mainland corridor traffic growth is anchoring demand for enhanced landing station capacity and redundant routing architecture.
- Edge computing proximity mandates:Cloud providers are concentrating server deployments in Kowloon East's data center corridor to minimize latency to enterprise clients.
Market Restraints
- Building access regulatory friction:In-building wireless system deployment timelines face delays from municipal permitting processes for fiber entry into commercial towers.
- Limited mmWave spectrum availability:Competitive bidding constraints for high-band frequencies restrict capacity expansion for ultra-dense urban coverage.
- Legacy copper maintenance burden:Ongoing support obligations for retiring DSL infrastructure divert technical resources from pure-fiber rollout acceleration.
Strategic Opportunities
- Symmetric SLA penetration among SMEs:Small and medium enterprises in industrial zones remain underserved for upload-matching-download service guarantees.
- Prepaid mobile service innovation:Transient worker populations in construction and logistics verticals present volume expansion potential beyond saturated residential broadband.
- Net neutrality compliance services:Traffic management transparency requirements create advisory and technical implementation revenue streams for enterprise clients.
Industry Challenges
- 5G standalone core integration complexity:Migration from non-standalone architectures demands simultaneous radio access network and packet core upgrades without service interruption.
- Specialized fiber splicing technician shortage:Last-mile deployment velocity constraints stem from limited certification programs for fusion splicing in dense urban environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Telecom Market |
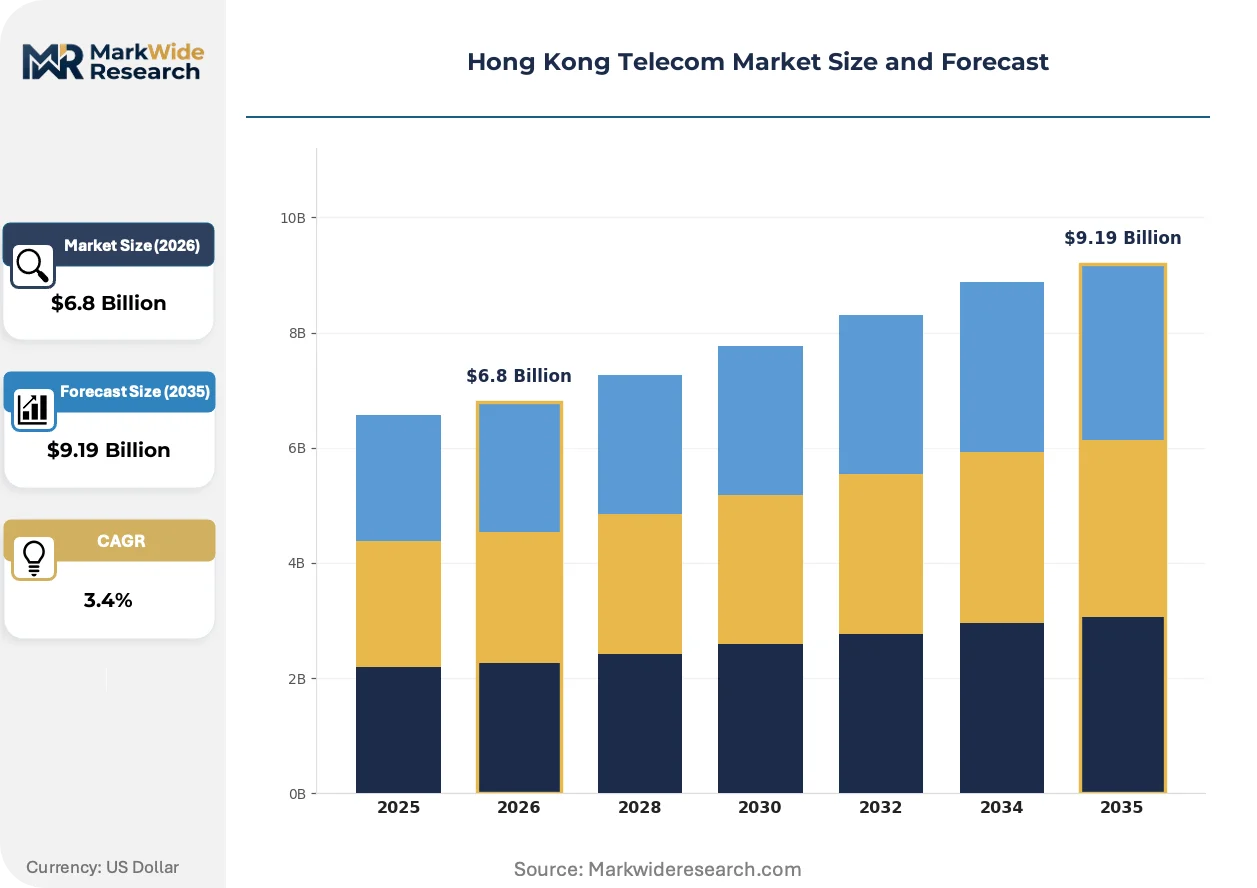
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fixed Line, Mobile, Broadband, Satellite End User: Residential, SMEs, Large Enterprises, Government Technology: 4G, 5G, Fiber Optic, DSL Pricing Model: Prepaid, Postpaid, Bundled Packages, Discounted Plans |
| Companies Covered | Hong Kong Telecommunications (HKT), China Mobile Hong Kong, HK Broadband Network (HKBN), SmarTone, 3 Hong Kong, Hutchison Telecommunications, HGC Global Communications, China Unicom Hong Kong, PCCW-HKT Telephone, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Telecom Market Strategic Shifts
Standalone 5G core architecture is overtaking non-standalone deployments as the foundation for network slicing and ultra-reliable low-latency services. This shift is compressing vendor selection cycles and forcing infrastructure procurement model revisions.
Open RAN hardware specifications are overtaking proprietary baseband equipment in new macro site deployments. Mobile network operators are piloting multi-vendor radio access networks in Tseung Kwan O industrial zones to reduce supplier concentration risk. The structural consequence is a fragmentation of equipment procurement across radio unit, distributed unit, and centralized unit suppliers.
The Office of the Communications Authority's spectrum utilization mandates are accelerating infrastructure sharing agreements among competing carriers. These regulations force co-location of base stations in dense urban corridors where site acquisition costs otherwise prohibit individual deployment. Enterprise clients in Quarry Bay and Kwun Tong are benefiting from improved coverage depth without corresponding price inflation.
Consumption patterns among residential subscribers are pivoting from speed-tier upgrades to quality-of-service guarantees. Buyers now prioritize latency consistency over peak bandwidth for remote work and cloud gaming applications. This behavioral shift is most pronounced in new town developments across Sha Tin and Tai Po where fiber-to-the-home penetration already exceeds ninety percent.
Hong Kong Telecom Market Segmentation

Telecom service segmentation in Hong Kong reveals divergent infrastructure requirements across customer tiers. Enterprise clients demand symmetric SLAs and private network isolation while residential segments prioritize bundled value and speed consistency.
Service Type:
Fixed-line services command premium pricing in Central's financial district where dedicated circuits support algorithmic trading infrastructure.
- Fixed Line:Traditional copper and fiber-based voice connectivity serves legacy enterprise PBX systems and fax-dependent legal workflows in Wan Chai. Banking compliance mandates for recorded voice lines sustain demand despite VoIP displacement elsewhere.
- Mobile:5G standalone core deployments enable network slicing for ultra-reliable low-latency applications in logistics and construction verticals. HKT and China Mobile Hong Kong compete on coverage depth in MTR tunnels and outlying islands.
- Broadband:Gigabit fiber-to-the-home penetration exceeds saturation thresholds in new town developments, shifting provider focus toward SME symmetric upload guarantees.
- Satellite:Maritime connectivity for container shipping routes through Victoria Harbour and fishing fleets in Sai Kung relies on geostationary and emerging LEO constellations.
Mobile leads volumes today; broadband is gaining share fastest.
End User:
Customer scale determines SLA architecture and support tier access across the territory.
- Residential:Speed-tier competition has compressed margins in Sha Tin and Tai Po where fiber penetration exceeds ninety percent. Bundled OTT content and gaming latency guarantees now differentiate providers.
- SMEs:Industrial zones in Kwun Tong and Kwai Chung remain underserved for symmetric upload-download guarantees. Cloud backup and video conferencing requirements are pulling fiber densification into factory buildings.
- Large Enterprises:Private 5G network deployments by financial services firms in Central and Tsim Sha Tsui demand dedicated spectrum slices and edge computing integration.
- Government:Smart city infrastructure mandates drive unified communications procurement for municipal services and emergency response coordination.
Residential subscribers dominate headcount; SME connectivity is expanding most quickly.
Technology:
Legacy infrastructure obligations constrain capital allocation toward next-generation deployments.
- 4G:Non-standalone architecture retains coverage responsibility in outlying islands and rural New Territories where 5G site economics fail. Voice over LTE core investments sustain voice service continuity during 5G migration.
- 5G:Standalone core deployment enables network slicing for financial services ultra-reliable low-latency requirements. mmWave commercialization in Kowloon East data center corridor accelerates under Office of the Communications Authority spectrum reallocation.
- Fiber Optic:Fusion splicing technician shortages limit last-mile velocity in dense urban environments. Cross-border submarine cable landing rights anchor mainland corridor traffic growth.
- DSL:Copper retirement programs divert technical resources from pure-fiber acceleration while maintaining service obligations for legacy building stock.
Fiber optic commands capital priority today; 5G standalone is climbing the fastest.
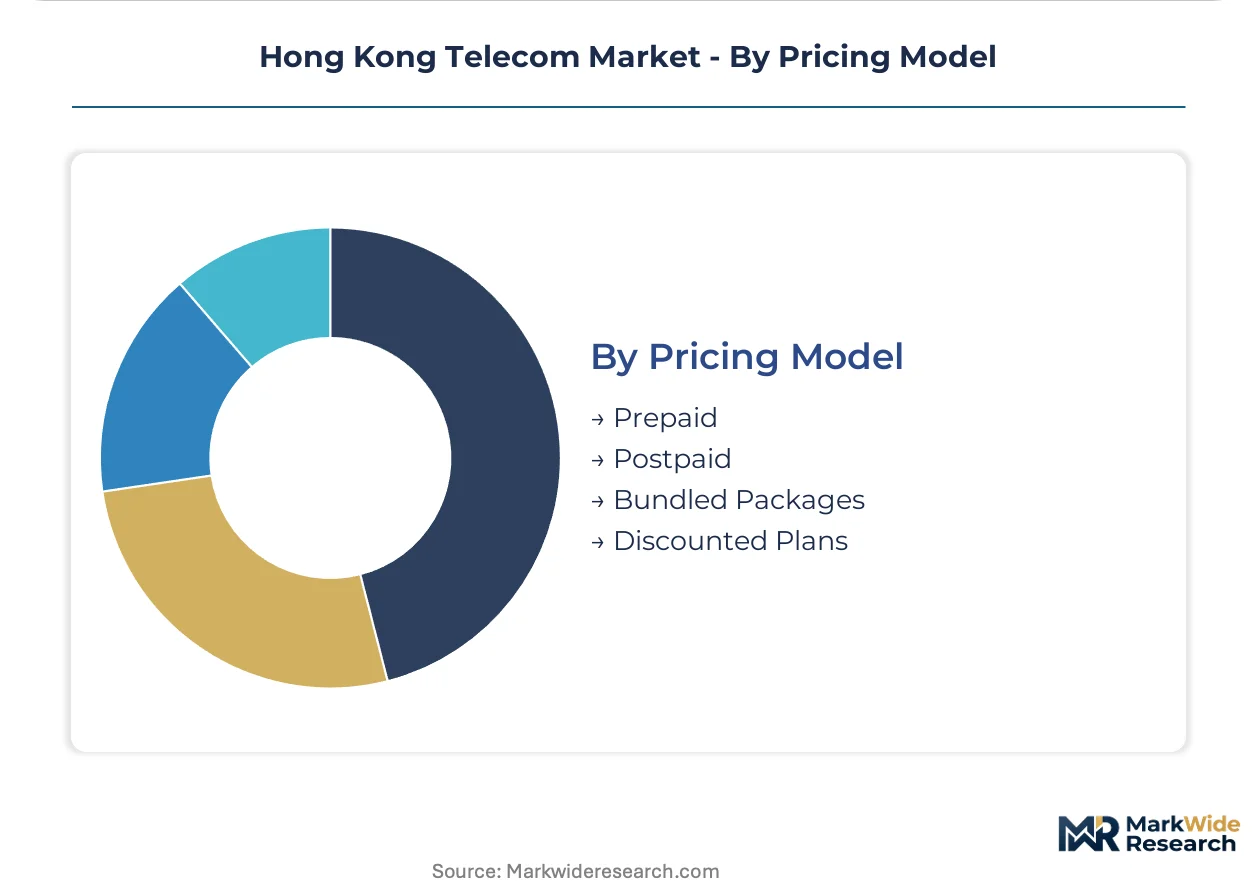
Pricing Model:
Payment structure correlates with customer tenure expectations and usage predictability.
- Prepaid:Transient construction and logistics worker populations in Tseung Kwan O industrial zones favor no-commitment mobile access. Volume expansion potential exists beyond saturated residential broadband.
- Postpaid:Contract tenure locks in enterprise ARPU through device financing and loyalty program integration. Credit-backed billing enables premium service tier access.
- Bundled Packages:Quad-play convergence of fixed-line, mobile, broadband, and OTT content dominates consumer acquisition strategy. Price transparency competition from HKBN pressures incumbent margin structures.
- Discounted Plans:Student and senior demographic targeting sustains subscriber acquisition in saturated markets. Seasonal promotional cycles align with handset launch windows.
Bundled packages lead revenue concentration today; prepaid innovation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage shapes infrastructure investment flows as operators migrate capital toward districts offering streamlined permitting for fiber entry and spectrum utilization clarity. The Office of the Communications Authority's building access regulations create compliance cost differentials across Hong Kong's districts.
Central and Western
Financial services firms demand private 5G networks with dedicated spectrum slices for algorithmic trading infrastructure. The Office of the Communications Authority enforces net neutrality principles that shape traffic management transparency requirements. Central's business district concentrates enterprise fiber densification investment from HKT and China Mobile Hong Kong competing on low-latency SLAs.
Kowloon East
Cloud providers anchor server deployments in the data center corridor to minimize latency to enterprise clients. Spectrum reallocation policy accelerates mmWave commercialization timelines for ultra-dense coverage. Kwun Tong industrial zones attract edge computing proximity mandates from logistics and manufacturing verticals seeking symmetric upload guarantees.
Tsim Sha Tsui
Cross-border submarine cable landing rights anchor mainland corridor traffic growth through redundant routing architecture. TRAI-aligned technical standards influence data routing architecture for mainland-Hong Kong interconnectivity. The district's commercial towers face building access regulatory friction delaying in-building wireless system deployments.
New Territories East
Sha Tin and Tai Po new town developments exceed ninety percent fiber-to-the-home penetration shifting focus to quality-of-service guarantees. Residential subscribers pivot from speed-tier upgrades to latency consistency for remote work applications. HKBN competes on price-transparent gigabit broadband with self-owned last-mile fiber assets in these saturated markets.
Outlying Islands
Maritime connectivity for container shipping routes relies on geostationary and emerging LEO satellite constellations. 4G non-standalone architecture retains coverage responsibility where 5G site economics fail. Fishing fleets in Sai Kung and Lantau sustain demand for satellite broadband where terrestrial infrastructure deployment remains uneconomical.
Hong Kong Telecom Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue niche specialization in private network deployment and edge computing integration. The market structure consolidates around legacy incumbents with copper-to-fiber migration programs and challenger operators with asset-light wholesale models. Three archetypes dominate: integrated infrastructure owners with submarine cable landing rights, retail-focused broadband specialists with transparent pricing, and mobile-first operators leveraging cross-border spectrum coordination. Dominant competitive moves include infrastructure sharing agreements forced by spectrum utilization mandates and fiber densification partnerships with cloud providers seeking data center proximity.
Among Hong Kong-based integrated operators, Hong Kong Telecommunications (HKT), China Mobile Hong Kong, and HK Broadband Network (HKBN) exemplify contrasting strategic positions. HKT occupies the legacy infrastructure owner archetype leveraging decades of copper-to-fiber migration investment. China Mobile Hong Kong represents the cross-border corridor specialist anchoring mainland traffic through submarine cable landing rights. HKBN sits within the challenger broadband tier competing on price transparency and self-owned last-mile fiber velocity. These three operators collectively illustrate how spectrum access, building entry rights, and wholesale-retail model selection determine competitive positioning in a territorially constrained market.
| Leading Market Players |
|---|
| Hong Kong Telecommunications (HKT) |
| China Mobile Hong Kong |
| HK Broadband Network (HKBN) |
| SmarTone |
| 3 Hong Kong |
| Hutchison Telecommunications |
| HGC Global Communications |
| China Unicom Hong Kong |
| PCCW-HKT Telephone |
| Others |
Value Chain & Pricing Dynamics
Financial services firms in Central and Tsim Sha Tsui anchor pricing power for enterprise fiber services, pulling premium subscription models upward while residential broadband competition compresses consumer-tier margins.
Pricing Analysis
Direct-to-enterprise discounts dominate the channel-margin layer, with financial services firms negotiating dedicated circuit pricing below standard retail tariffs. Three-tier pricing structure across premium symmetric SLAs, standard gigabit residential, and economy prepaid mobile separates enterprise buyers from mass-market consumers. Cost compression in residential broadband intensifies because HKBN's price-transparent positioning forces incumbent repricing. SMEs in industrial zones exhibit highest price sensitivity, while algorithmic trading houses accept premium tiers without negotiation.
Supply Chain Analysis
Fusion splicing technician shortages in dense urban Hong Kong constrain last-mile deployment velocity, forcing equipment vendors to anchor training programs in Shenzhen and Dongguan manufacturing corridors. Network equipment draws from China, South Korea, and Taiwan for baseband units, radio heads, and fiber optic components. Single-source vulnerability concentrates in submarine cable landing station hardware. Distribution runs through carrier-direct procurement with limited distributor intermediation for enterprise fiber builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong telecom operates as a late-cycle quality story, with enterprise demand shifting toward sub-millisecond latency specifications that reward infrastructure-heavy incumbents over asset-light challengers.
For Market Incumbents: Anchor defensive positioning through accelerated copper retirement in Central and Kowloon East, freeing technical resources for pure-fiber densification. Deepen submarine cable landing rights through cross-border corridor expansion to offset emerging entrant pressure from mainland-coordinated operators. Prioritize certification investment for in-building wireless system deployment to capture regulatory compliance revenue streams. For New Entrants and Emerging Players: The Office of the Communications Authority's spectrum reallocation policy opens a window for mmWave specialist positioning in Kowloon East's data center corridor. Target underserved SME symmetric SLA demand in Kwun Tong and Kwai Chung industrial zones where upload-matching-download guarantees remain scarce. Pursue prepaid mobile innovation for transient construction and logistics worker populations as the most penetrable volume expansion path. For Investors and Strategic Acquirers: Cloud providers are the most active acquirer in this space, seeking edge computing proximity through infrastructure partnerships or captive fiber builds. Long-term viability favors integrated operators with submarine cable landing rights and self-owned last-mile assets over wholesale-dependent challengers. Monitor spectrum auction schedules and building access regulation amendments as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Standalone 5G Core Deployment | Enables network slicing for financial services ultra-reliable low-latency requirements in Central. |
| Submarine Cable Landing Expansion | Anchors mainland corridor traffic growth through redundant routing architecture in Tsim Sha Tsui. |
| Open RAN Hardware Pilot | Reduces supplier concentration risk through multi-vendor radio access networks in Tseung Kwan O. |
| Fiber Densification Partnership | Positions cloud providers for edge computing proximity in Kowloon East data center corridor. |
| Infrastructure Sharing Agreement | Complies with Office of the Communications Authority spectrum utilization mandates for urban co-location. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with network planning executives, regulatory affairs specialists at the Office of the Communications Authority, enterprise procurement managers in financial services, fiber deployment contractors, and submarine cable landing station operators with secondary validation against spectrum auction records, carrier capex disclosures, building access permit databases, and cross-border traffic statistics. Bottom-up service revenue modeling and top-down infrastructure investment triangulation anchored value estimates.
Segment-weighting across service type, end user tier, technology generation, and pricing model dimensions shaped the analytical framework across the projection horizon. CAGRs derived from infrastructure deployment velocity, spectrum commercialization timelines, and enterprise demand elasticity curves. Industry-specific inputs included fiber-to-the-home penetration saturation thresholds and 5G standalone core migration schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under spectrum auction delays or building access regulatory friction. Projections reflect documented assumptions regarding mmWave commercialization timelines and cross-border data routing policy alignment. Material deviation in spectrum reallocation schedules or submarine cable landing rights amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Telecom Service Assurance Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Cambodia Telecom Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
South Korea Telecom Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Mobile Voice Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Underwater Modems Market
Telecommunications
Fixed LTE Market
Telecommunications
A2P Messaging Market
Telecommunications
C-RAN Market
Telecommunications
Smart SIM Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Africa Entertainment and Telecommunication Market