
 Rich Communication Services (RCS) Market | 2026-2036
Rich Communication Services (RCS) Market Size, Share, and Industry Trends Forecast 2026-2036
Rich Communication Services (RCS) Market Analytics
GSMA Universal Profile certification is redrawing competitive boundaries in RCS infrastructure. Google LLC leverages its Android Messages platform to anchor RCS distribution across device OEMs. Mavenir competes through cloud-native IMS core specialization for carrier deployments. Twilio Inc. extends its messaging API portfolio to incorporate RCS channels for enterprise developers.
Rich Communication Services denotes an IP-based messaging protocol specified by the GSM Association that replaces SMS with read receipts, typing indicators, high-resolution media sharing, and interactive cards transmitted over LTE or Wi-Fi data channels. Enterprise Messaging commands the largest revenue share as banks and retailers replace SMS one-time passwords and promotional blasts with verified branded interactions; Public Cloud deployment grows fastest by eliminating carrier capex barriers for mid-tier operators. Interactive Messaging captures premium margins where conversational commerce workflows integrate payment buttons and appointment scheduling within the thread.
The Federal Communications Commission oversees messaging regulation in the United States while the GSMA sets technical interoperability mandates; the European Electronic Communications Code shapes RCS deployment timelines across EU member states by classifying rich messaging under electronic communications services. Stakeholders must monitor whether Apple’s device-level RCS support alters platform gatekeeping dynamics and enterprise API pricing power.
Market Dynamics
Carrier infrastructure consolidation around GSMA Universal Profile specifications is compressing interoperability timelines and forcing tier-two operators into cloud-native deployment models to remain competitive.
Growth Catalysts
- Retail enterprise messaging:Branded verified channels replace SMS promotional blasts with interactive product cards and appointment scheduling, deepening customer engagement metrics.
- FCC messaging oversight:Regulatory clarity on rich messaging classification accelerates carrier investment in IP-based infrastructure upgrades.
- LTE/Wi-Fi data channel ubiquity:Smartphone penetration and flat-rate data plans eliminate cost barriers to media-rich message transmission.
Market Restraints
- IMS core capex requirements:Cloud-native migration demands substantial upfront investment in virtualized network functions and orchestration layers.
- Device certification bottlenecks:GSMA Universal Profile testing protocols create multi-month approval delays for OEM software updates.
- OTT messaging substitution:WhatsApp and iMessage maintain installed-base advantages in consumer peer-to-peer segments.
Strategic Opportunities
- Conversational commerce workflows:Integration of payment buttons and inventory queries within messaging threads opens new transaction revenue streams.
- Mid-tier operator cloud migration:Public deployment models eliminate capital barriers for regional carriers seeking feature parity.
- EU Electronic Communications Code:Classification of rich messaging under electronic communications services mandates operator readiness timelines.
Industry Challenges
- Interoperability testing complexity:Multi-carrier message routing validation requires specialized engineering resources and extended certification cycles.
- Legacy SMS revenue cannibalization:Operators face internal resistance to migrating high-margin text messaging volumes to lower-yield RCS pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rich Communication Services (RCS) Market |
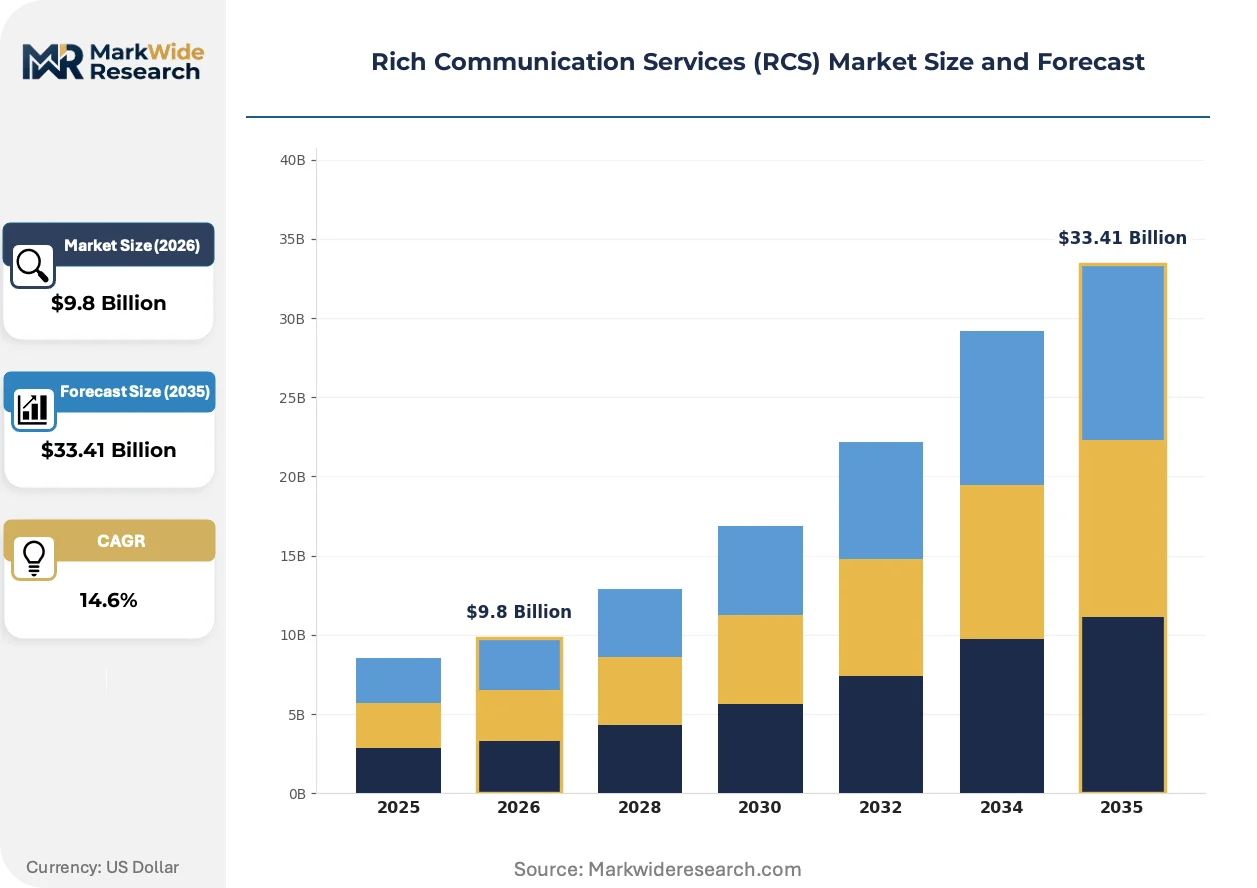
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $33.41 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enterprise Messaging, Interactive Messaging, Group Chat, Rich Media Deployment: On-Premises, Private Cloud, Public Cloud, Hybrid Cloud End User: Retail, Telecom, Financial Services, Education Integration Level: API-Based, Platform Bundled, Standalone, Legacy Systems |
| Companies Covered | Twilio Inc., Mavenir, Google LLC, Telefonaktiebolaget LM Ericsson, Vodafone Group, Sinch, Infobip, Huawei Technologies Co. Ltd, AT&T Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rich Communication Services (RCS) Market Evolving Landscape
RCS deployment patterns are diverging between carrier-hosted infrastructure and API-mediated enterprise channels, creating parallel commercialization paths with distinct technical requirements.
Rich messaging functionality is bifurcating across consumer and enterprise use cases. Consumer implementations emphasize read receipts and high-resolution media sharing, while enterprise deployments prioritize verified sender branding and interactive card-based workflows. Banks and retailers adopt conversational interfaces at accelerated pace, compressing traditional SMS authentication and promotional channels into unified messaging experiences.
GDPR data portability requirements are reshaping how carriers handle message content storage and cross-border transmission. The European Electronic Communications Code mandates interoperability standards that force national regulators to accelerate compliance timelines. Messaging infrastructure vendors respond by embedding privacy-by-design architectures into cloud-native IMS cores, with Germany and France setting precedent for enforcement stringency.
Enterprise procurement of messaging services is consolidating around API-first platforms that abstract carrier complexity. Developers increasingly demand single-integration access to multi-channel delivery spanning RCS, SMS, and OTT alternatives. This pattern concentrates most visibly in United States financial services, where fraud prevention requirements drive preference for verified sender protocols over unauthenticated channels.
Rich Communication Services (RCS) Market Segmentation
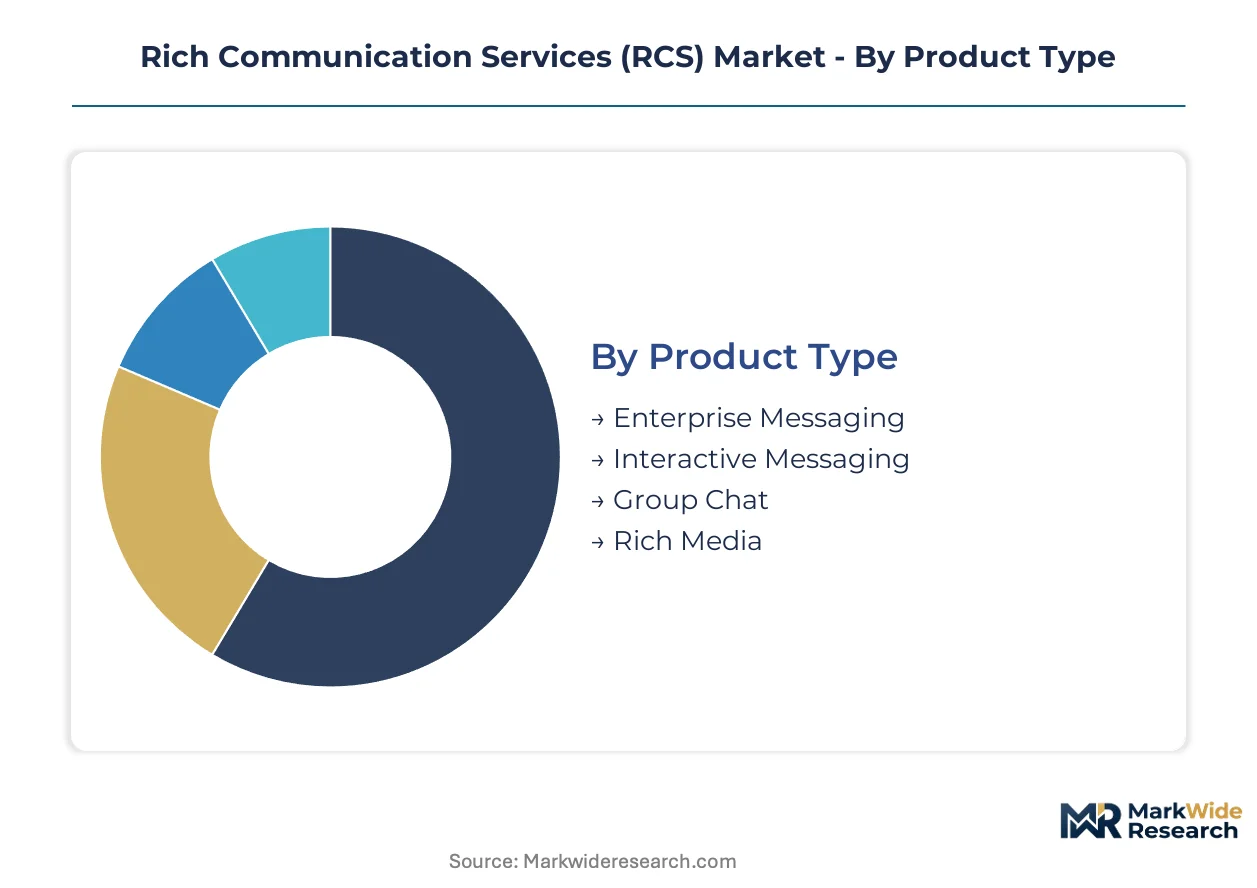
RCS market segmentation reveals divergent commercialization paths between carrier-hosted infrastructure and API-mediated enterprise channels. Regulatory mandates across the United States and European Union accelerate deployment model fragmentation, while end-use concentration in financial services and retail reshapes integration requirements.
Product Type:
FCC oversight of messaging authentication and the EU Electronic Communications Code create divergent compliance burdens across product categories, with verified sender protocols commanding premium positioning in regulated verticals.
- Enterprise Messaging:Branded verified channels deliver read receipts, typing indicators, and high-resolution media sharing over IP data channels. Banks and retailers in the United States concentrate procurement here, driven by fraud prevention requirements that favor authenticated sender protocols over unverified SMS alternatives.
- Interactive Messaging:Card-based workflows integrate payment buttons, appointment scheduling, and inventory queries within message threads. European financial services demand this capability most intensely, compelled by GDPR data portability mandates and the Electronic Communications Code interoperability timelines.
- Group Chat:Multi-party threaded conversations with presence indicators and media sharing.
- Rich Media:High-resolution image, video, and audio transmission replacing MMS limitations.
Enterprise Messaging handles the majority of throughput; Interactive Messaging is gaining share fastest through conversational commerce adoption.
Deployment:
Cost tier differentiation separates capital-intensive carrier infrastructure from consumption-priced cloud alternatives, with mid-tier operators facing compressed decision timelines.
- Public Cloud:Virtualized IMS core functions delivered as managed services eliminate carrier capex barriers. Regional operators in the United States adopt this model most aggressively, constrained by Verizon, AT&T, and T-Mobile infrastructure investments that threaten competitive parity.
- Private Cloud:Dedicated tenant environments with carrier-controlled orchestration layers and data sovereignty guarantees. German and French operators favor this deployment, responding to GDPR enforcement stringency and national regulator precedents for data localization.
- On-Premises:Physical IMS hardware with full operational control retained by carrier engineering teams.
- Hybrid Cloud:Split workloads across owned infrastructure and cloud-hosted network functions.
Public Cloud expands most quickly by removing capital barriers; Private Cloud retains margin premiums in regulated European markets.
End User:
Application concentration varies sharply by vertical, with authentication and promotional use cases driving divergent technical specifications.
- Financial Services:Verified sender protocols for one-time passwords, transaction alerts, and fraud notifications. United States banks lead procurement volume, compelled by FCC messaging oversight and liability frameworks for authentication failures.
- Retail:Interactive product cards, appointment scheduling, and promotional campaigns replacing SMS blasts. National chains concentrate adoption here, leveraging read receipts and engagement metrics to optimize conversion funnels.
- Telecom:Carrier-branded customer service and account management interfaces.
- Education:Administrative communications and emergency alert systems with delivery confirmation.
Financial Services dominates current deployment value; Retail shows the steepest expansion trajectory as conversational commerce matures.
Integration Level:
Customer type segmentation separates developer-facing API platforms from turnkey solutions, with procurement consolidation favoring abstraction layers.
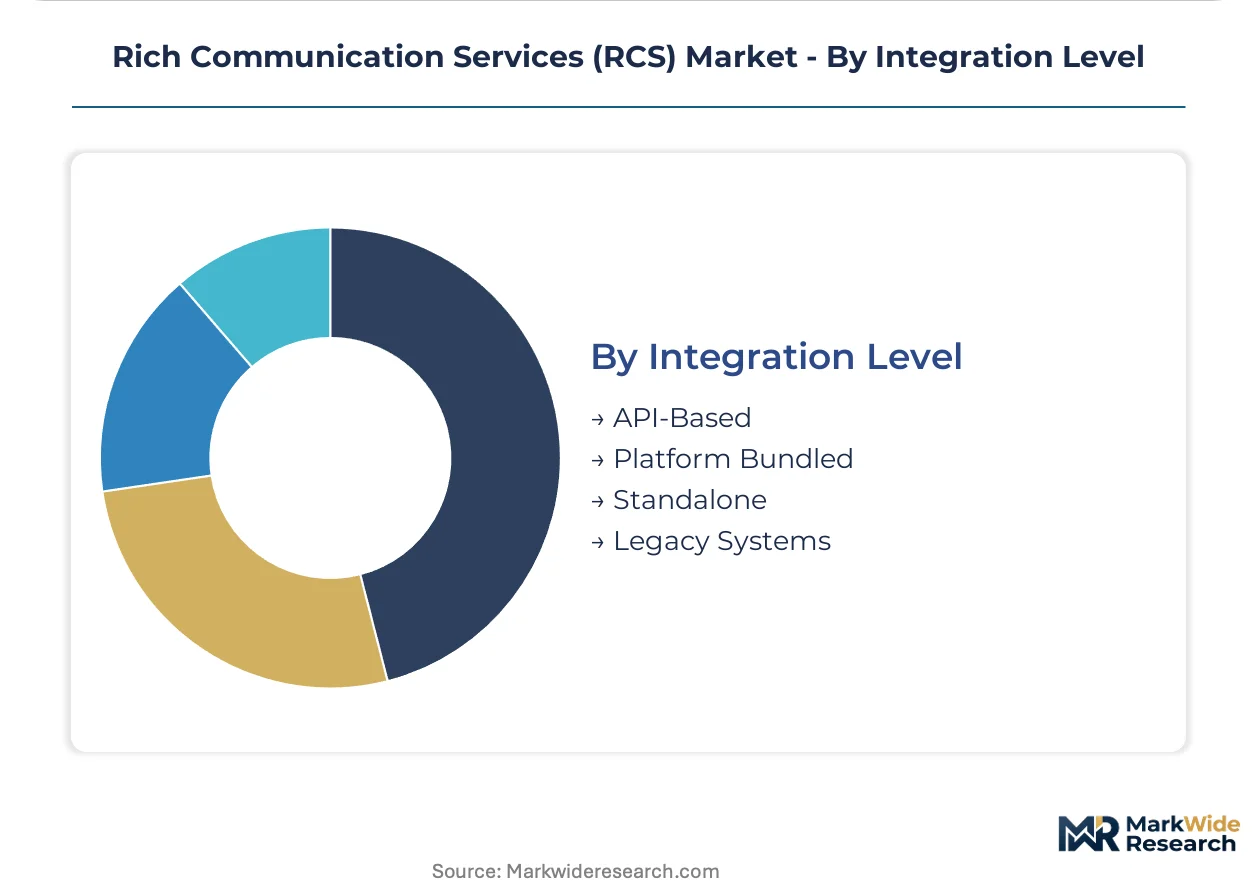
- API-Based:RESTful interfaces enabling single-integration access to multi-channel delivery spanning RCS, SMS, and OTT alternatives. Enterprise developers in United States financial services concentrate here, demanding carrier complexity abstraction for rapid deployment cycles.
- Platform Bundled:Pre-integrated modules within broader customer engagement suites.
- Standalone:Dedicated RCS clients without broader messaging ecosystem connectivity.
- Legacy Systems:SMS gateway retrofits with limited rich messaging feature exposure.
API-Based integration captures the majority of new procurement; Platform Bundled solutions climb fastest as enterprise suites consolidate messaging capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in financial services and retail chains concentrate procurement in markets with mature IP infrastructure and clear regulatory frameworks for authenticated messaging.
United States
Verizon, AT&T, and T-Mobile have deployed Universal Profile infrastructure nationwide. FCC messaging oversight accelerates carrier investment in verified sender protocols. New York and San Francisco financial services clusters drive authentication demand for one-time passwords and fraud alerts.
Germany
GDPR enforcement stringency shapes carrier deployment of privacy-by-design IMS cores. The national telecommunications regulator mandates interoperability timelines under EU Electronic Communications Code alignment. Frankfurt and Munich banking centers prioritize verified sender channels for transaction security.
United Kingdom
API-first enterprise procurement concentrates among London fintech developers seeking multi-channel abstraction. Ofcom messaging classification rules mirror EU electronic communications frameworks. The London financial district leads conversational commerce adoption for retail banking interfaces.
France
CNIL data localization precedents push carriers toward private cloud IMS deployments with sovereign guarantees. The Electronic Communications Code transposition accelerates national interoperability mandates. Paris retail headquarters pilot interactive product cards and appointment scheduling workflows.
India
TRAI messaging regulations and rising smartphone penetration create conditions for RCS substitution of SMS promotional channels. Mumbai and Bangalore enterprise clusters experiment with verified business messaging for e-commerce authentication. Cloud-native deployment models attract mid-tier operators seeking feature parity without capital intensity.
Rich Communication Services (RCS) Market Competitive Landscape
Player mix skews toward cloud-native infrastructure specialists and API platform aggregators with carrier distribution partnerships. Tier-one operators maintain vertical integration through proprietary IMS cores, while tier-two carriers outsource to managed service providers. Strategic archetypes include Android ecosystem gatekeepers, virtualized network function vendors, and enterprise messaging API platforms. Competitive moves center on Universal Profile certification acceleration and conversational commerce workflow integration.
Within the API platform tier, Twilio Inc. and Sinch exemplify developer-facing abstraction models that aggregate carrier complexity into single-integration endpoints. Google LLC anchors consumer-side distribution through Android Messages pre-installation across device OEMs. Mavenir occupies a position among cloud-native IMS specialists serving operator infrastructure migration.
| Leading Market Players |
|---|
| Twilio Inc. |
| Mavenir |
| Google LLC |
| Telefonaktiebolaget LM Ericsson |
| Vodafone Group |
| Sinch |
| Infobip |
| Huawei Technologies Co. Ltd |
| AT&T Inc. |
| Others |
Value Network & Pricing Analysis
Carrier-grade IMS core capacity utilization above eighty percent anchors cost structures across cloud-native and on-premises deployment models, compressing price floors for mid-tier operators while concentrating supply leverage among hyperscale infrastructure providers in the United States and Germany.
Pricing Analysis
Cost-plus contracts with CPU-hour indexation dominate public cloud IMS procurement, with tiered pricing separating GSMA Universal Profile certified deployments from uncertified alternatives. Price differentiation rests on data sovereignty guarantees and latency SLAs rather than raw compute scale. Cost compression in private cloud tiers is intensifying because GDPR enforcement stringency mandates localized orchestration layers. Regional carriers in India exhibit highest price sensitivity; United States financial services buyers prioritize verified sender authentication over per-message economics.
Supply Chain Analysis
Strait of Malacca cable transit underwrites submarine connectivity for Asian RCS infrastructure, creating chokepoint exposure for cloud-native IMS traffic routing. Supply concentrates in the United States, Germany, and India for virtualized network function software; Taiwan and South Korea for baseband silicon. Raw material dependencies include high-purity silicon wafers, specialized optical transceivers, and lithium-ion backup power systems. Single-source vulnerability runs through GSMA certification testing laboratories with twelve-month backlogs. Distribution runs through carrier procurement departments and API platform aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RCS infrastructure incumbents face substitution defense imperatives as WhatsApp Business API and Apple Business Chat capture enterprise messaging budgets that carriers targeted for migration from SMS.
For Market Incumbents: Secure GSMA Universal Profile certification acceleration through dedicated testing partnerships, reducing OEM software update delays from multi-month cycles to weeks. Anchor cloud-native IMS deployments in India and Southeast Asia before mid-tier operators consolidate around hyperscale alternatives. Vertical integration into conversational commerce workflow tools counters API platform disintermediation. For New Entrants and Emerging Players: Differentiate on GDPR-compliant private cloud orchestration with sovereign data guarantees, targeting German and French operators facing CNIL localization precedents. White-space concentration sits in mid-tier Indian carriers seeking feature parity without Verizon-scale capital intensity. Go-to-market leverage rests on TRAI messaging regulation alignment and smartphone penetration tailwinds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native IMS specialists with carrier distribution lock-in over hardware-dependent legacy vendors. Long-term viability across the projection horizon hinges on conversational commerce transaction revenue streams displacing per-message pricing. Acquisition target archetype: API-first platforms with multi-channel abstraction and financial services fraud prevention integration. Signal to watch: Apple device-level RCS support altering platform gatekeeping dynamics and enterprise API pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| GSMA Universal Profile Certification Acceleration | Compresses OEM software update delays and unlocks carrier interoperability timelines. |
| Cloud-Native IMS Core Migration | Eliminates capital barriers for regional operators competing with Verizon infrastructure scale. |
| Conversational Commerce Workflow Integration | Captures transaction revenue streams through payment buttons embedded in messaging threads. |
| GDPR Privacy-by-Design Architecture | Addresses CNIL enforcement stringency and German data localization mandates. |
| API Platform Multi-Channel Abstraction | Aggregates carrier complexity for enterprise developers demanding single-integration access. |
Research Methodology
Desk research of GSMA technical specifications, FCC messaging oversight filings, and carrier infrastructure disclosure reports preceded structured interviews with cloud-native IMS product managers, enterprise messaging API platform engineers, carrier network planning officers, and retail chain digital marketing executives. Secondary validation drew from TRAI regulatory circulars, EU Electronic Communications Code transposition documents, and smartphone penetration databases. Bottom-up deployment model sizing triangulated against top-down enterprise messaging spend estimates.
Variance decomposition across product type, deployment model, end-user vertical, and integration level segments shaped the analytical framework throughout the forecast period. CAGRs derived from carrier capex trajectory analysis and enterprise API consumption elasticity modeling. Industry-specific inputs included GSMA Universal Profile certification pipeline velocity and conversational commerce transaction volume proxies.
The analysis sits within stated boundaries; outcomes outside sustained LTE/Wi-Fi data channel ubiquity and regulatory clarity on rich messaging classification would require recalibration. Forecasts assume carrier infrastructure consolidation timelines and Apple RCS support decisions as modeled. Practitioners should keep alternative scenarios live as OTT messaging substitution rates and GDPR enforcement stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Technology Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
Telecom Expense Management Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Belgium ICT Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Argentina Telecom Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
C-RAN Market
Telecommunications
Global Telecommunication Market
Telecommunications
Turkey Telecom Market
Telecommunications
IoT Telecom Services Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
Global International Calling Apps Market