
 United States SCADA Market | 2026-2036
United States SCADA Market Size, Share, and Industry Trends Forecast 2026-2036
United States SCADA Market Intelligence
Texas is narrowing its gap with traditional Midwest automation hubs through petrochemical capacity expansions along the Gulf Coast. Rockwell Automation leverages its Logix platform dominance to anchor large manufacturing deployments across the Rust Belt. Emerson Electric sustains deep relationships with oil and gas majors through its Ovation distributed control architecture. Schneider Electric differentiates via EcoStruxure integration, competing for hybrid cloud deployments in municipal water districts.
Supervisory Control and Data Acquisition (SCADA) denotes an industrial control system architecture comprising programmable logic controllers, remote terminal units, and human-machine interface software that enables centralized monitoring of geographically dispersed physical processes through serial, Ethernet, or wireless communication protocols. The technology serves critical infrastructure operators by delivering real-time telemetry, alarm management, and historical data logging for pipeline networks, treatment facilities, and generation plants. Programmable Logic Controllers occupy the largest installed base due to decades of hardwired reliability in process industries, while SCADA Software captures expanding margin pools as vendors shift toward subscription-based analytics platforms. Edge Computing represents the fastest-growing technology dimension as latency-sensitive applications in renewable energy sites and smart substations push computation closer to field assets.
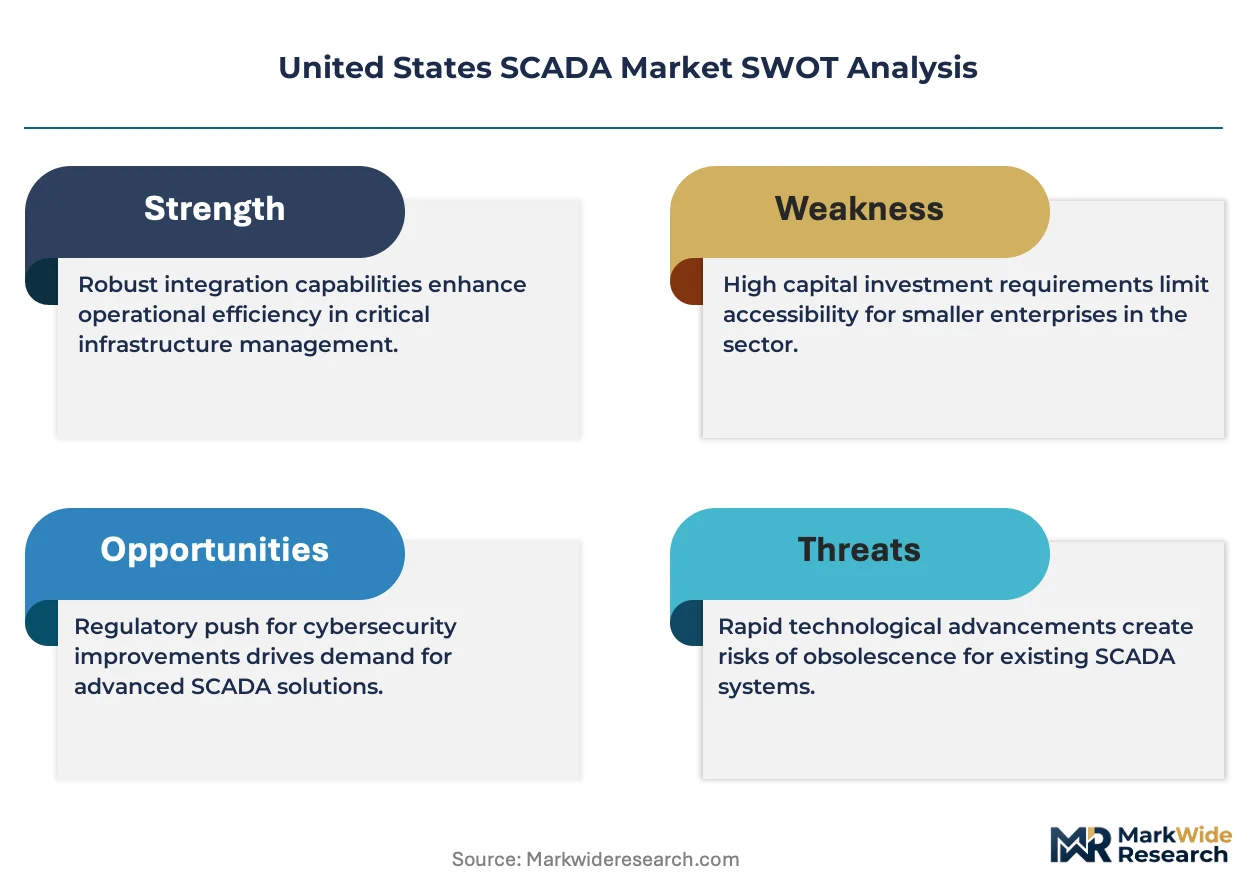
The EPA mandates cybersecurity assessments for public water systems under its Safe Drinking Water Act authority, compelling utilities to replace unpatched legacy SCADA installations with encrypted, access-controlled architectures. NERC CIP standards enforce comparable rigor across bulk electric system operators, with FERC penalties driving transmission owners toward audited compliance frameworks. OSHA process safety management rules further shape chemical facility control system specifications, particularly around alarm rationalization and operator interface design. Stakeholders must weigh the capital efficiency of cloud-native SCADA platforms against the operational continuity assurances of air-gapped on-premises architectures when planning multi-decade infrastructure commitments.
Market Dynamics
The United States SCADA market is undergoing a forced architectural transition as EPA cybersecurity mandates for water utilities collide with legacy system obsolescence, compelling operators to replace unencrypted serial networks with zero-trust architectures. This regulatory pressure is reshaping procurement timelines and vendor selection criteria across critical infrastructure sectors.
Growth Catalysts
- EPA Cybersecurity Directives:The Safe Drinking Water Act enforcement arm mandates encrypted, access-controlled SCADA architectures for public water systems, accelerating compliance-driven replacement cycles in municipal utilities.
- Gulf Coast Petrochemical Expansion:Capacity additions along the Texas-Louisiana corridor are modernizing distributed control architectures to manage complex process safety and real-time optimization requirements.
- Edge Computing Integration:Latency-sensitive renewable energy sites and smart substations are pushing computation closer to field assets, expanding addressable infrastructure for hybrid SCADA deployments.
Market Restraints
- Legacy System Entrenchment:Decades of hardwired PLC installations in process industries create high switching costs and integration complexity that slow architectural transitions.
- Specialized Talent Scarcity:Shortages of OT cybersecurity professionals and control systems engineers with cross-domain expertise constrain deployment velocity for encrypted architectures.
- Capital Intensity of Air-Gapped Migration:Utilities face multi-year budget cycles to fund parallel infrastructure builds that maintain operational continuity during zero-trust transitions.
Strategic Opportunities
- California Water District Modernization:Aging distribution infrastructure and drought-driven efficiency mandates create demand for cloud-integrated SCADA with advanced leak detection analytics.
- NERC CIP Compliance Services:Bulk electric system operators require audited frameworks for critical infrastructure protection, opening managed security service attach rates for transmission owners.
- Hybrid Cloud Convergence:Subscription-based analytics platforms are displacing perpetual license models, enabling vendors to capture recurring revenue from municipal customers with constrained capex flexibility.
Industry Challenges
- OT-IT Integration Complexity:Converging operational technology networks with enterprise IT systems introduces attack surface expansion that conflicts with air-gapped security traditions.
- Alarm Rationalization Requirements:OSHA process safety management rules mandate redesigned operator interfaces, forcing chemical facilities to re-engineer human-machine interaction protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States SCADA Market |
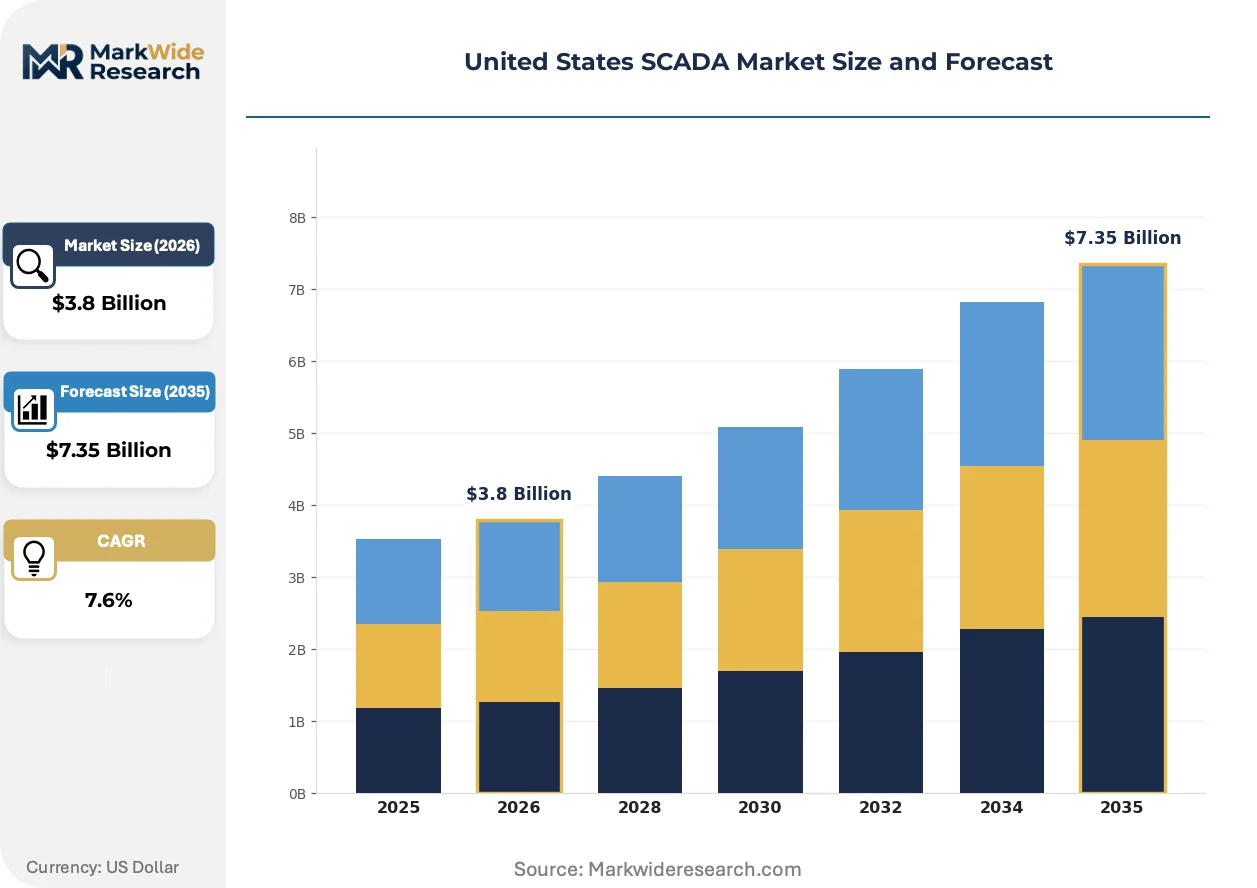
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Programmable Logic Controllers, Human-Machine Interfaces, Remote Terminal Units, SCADA Software End User: Oil & Gas, Water & Wastewater, Energy, Manufacturing Technology: Cloud-Based, On-Premises, Hybrid, Edge Computing Deployment: Institutional, Municipal, Industrial, Commercial |
| Companies Covered | Rockwell Automation, Emerson Electric, Honeywell International, Schneider Electric, ABB, Siemens, General Electric, Yokogawa Electric, Inductive Automation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States SCADA Market Strategic Shifts & Innovations
SCADA architecture is fragmenting across deployment models as operators weigh cloud-native telemetry against operational continuity requirements. Vendors are responding with containerized software stacks that port across edge, on-premises, and hybrid environments.
Edge-native SCADA platforms are hybridizing traditional centralized architectures by embedding analytics and control logic directly at remote terminal units. Renewable energy developers in Texas and California are deploying these systems fastest to manage intermittent generation profiles. The technology is hybridizing vendor business models as hardware margins compress and software subscription revenue pools expand.
FERC enforcement of NERC CIP standards is tightening audit requirements for bulk electric system operators, with penalty structures driving transmission owners toward certified compliance frameworks. The industrial consequence is accelerated replacement of serial communication protocols with encrypted Ethernet architectures. Generation and transmission segments in the Midwest and Southeast are responding with dedicated cybersecurity procurement line items.
Buyer procurement patterns are compressing vendor evaluation cycles as utilities face regulatory deadlines with limited implementation windows. Municipal water districts are consolidating vendor relationships to reduce integration risk, displacing multi-supplier best-of-breed approaches. California and Texas utilities exhibit this concentration most visibly, with single-platform commitments spanning telemetry, analytics, and managed security services.
United States SCADA Market Segmentation
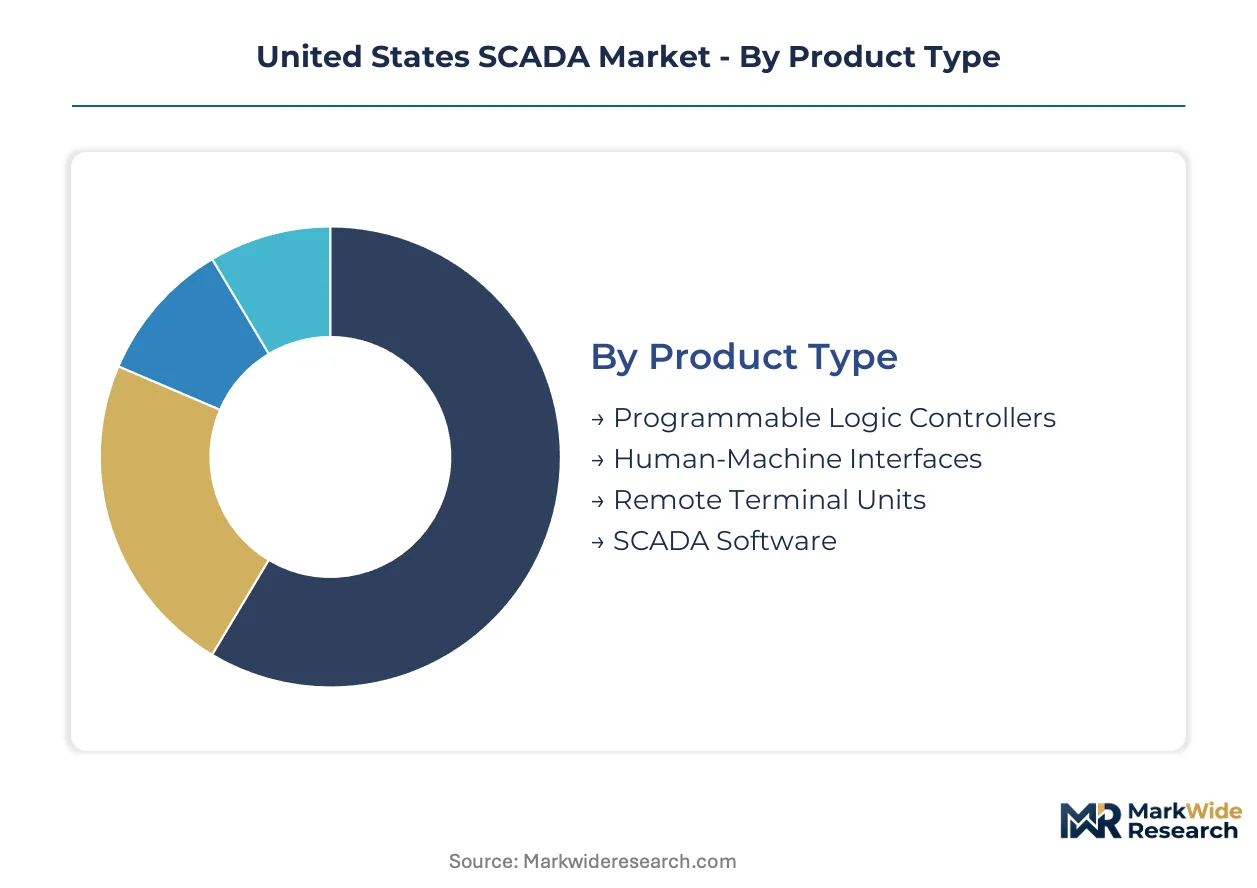
SCADA market segmentation reveals divergent technology lifecycles across industrial infrastructure. Product mix reflects decades of PLC entrenchment against accelerating software subscription models. Deployment patterns track regulatory pressure gradients between municipal compliance mandates and industrial modernization cycles.
Product Type:
Cost tier differentiation separates capital-intensive hardware installations from recurring software revenue streams.
- Programmable Logic Controllers:Hardwired relay logic successors execute deterministic control sequences with microsecond response guarantees. Gulf Coast petrochemical operators maintain extensive installed bases despite integration friction with encrypted network architectures. Texas and Louisiana facilities face high switching costs during zero-trust transitions.
- SCADA Software:Subscription analytics platforms aggregate telemetry streams into operator dashboards and predictive maintenance algorithms. Municipal water districts in California favor these deployments for leak detection and drought-driven efficiency optimization.
- Human-Machine Interfaces:Touchscreen panels and visualization software translate process data into actionable operator displays.
- Remote Terminal Units:Field-hardened data acquisition modules bridge sensor networks to central control systems.
Programmable Logic Controllers command the established base. The steepest expansion runs through SCADA Software.
End User:
Application concentration maps directly to regulatory enforcement intensity and infrastructure age profiles.
- Water & Wastewater:EPA Safe Drinking Water Act mandates drive encrypted architecture replacements across aging distribution networks. Texas utilities face compressed procurement timelines to meet cybersecurity directive deadlines. California districts layer drought efficiency requirements onto compliance-driven capital programs.
- Oil & Gas:Pipeline operators and upstream producers manage geographically dispersed assets through serial-to-Ethernet protocol migrations. OSHA process safety management rules shape alarm rationalization and operator interface specifications for Gulf Coast chemical facilities.
- Energy:FERC penalty structures under NERC CIP standards compel transmission owners toward audited compliance frameworks.
- Manufacturing:Discrete and process automation lines in the Rust Belt modernize legacy control architectures for operational efficiency gains.
Oil & Gas retains the largest revenue pool. Water & Wastewater generates the fastest procurement velocity.
Technology:
Customer risk tolerance stratifies across air-gapped traditions and cloud-native adoption curves.
- Edge Computing:Embedded analytics execute control logic at remote terminal units without round-trip latency to central servers. Texas renewable energy developers deploy these systems fastest to manage intermittent generation profiles from wind and solar assets. California smart substations adopt comparable architectures for real-time grid stabilization.
- Hybrid:Containerized software stacks port across on-premises and cloud environments, appealing to municipal utilities with constrained capex flexibility and continuity requirements.
- On-Premises:Air-gapped architectures satisfy critical infrastructure operators with strict operational technology isolation protocols.
- Cloud-Based:Fully hosted telemetry platforms attract commercial and smaller institutional deployments with limited in-house cybersecurity expertise.
On-Premises systems anchor current infrastructure. Edge Computing climbs the fastest as latency-sensitive applications proliferate.
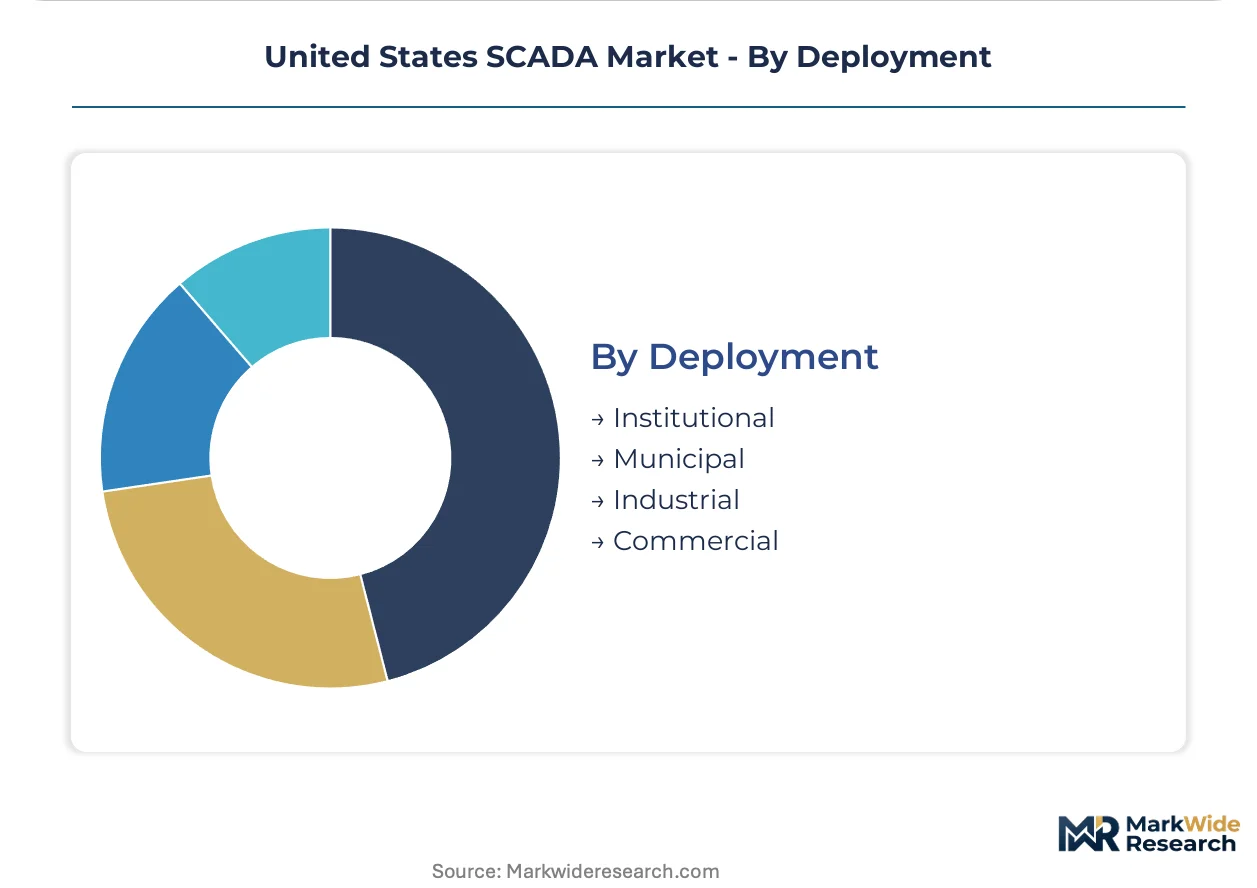
Deployment:
Volume concentration reflects public sector procurement scale against fragmented commercial opportunity.
- Municipal:City and county water districts consolidate vendor relationships to reduce integration risk across telemetry, analytics, and managed security services. California and Texas exhibit this procurement concentration most visibly.
- Industrial:Petrochemical corridors along the Gulf Coast modernize distributed control architectures for complex process safety and real-time optimization requirements.
- Institutional:Federal and state facilities follow standardized cybersecurity frameworks with dedicated compliance procurement line items.
- Commercial:Smaller-scale building automation and facility management applications deploy lighter SCADA configurations.
Industrial deployments capture the highest unit values. Municipal contracts expand most quickly under EPA directive pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA cybersecurity mandates under the Safe Drinking Water Act anchor demand concentration in the United States, with state-level procurement patterns diverging sharply based on infrastructure age profiles and industrial density.
Texas
Gulf Coast petrochemical expansions and renewable energy deployments drive dual demand streams for distributed control architectures. State utilities face compressed timelines to meet EPA cybersecurity directive deadlines for public water systems. The Houston-Beaumont-Port Arthur corridor concentrates process safety modernization investments across chemical facilities and refineries.
California
Drought-driven efficiency mandates layer onto compliance requirements for municipal water districts managing aging distribution infrastructure. The state's renewable portfolio standards accelerate edge-native SCADA adoption for grid stabilization at solar and wind assets. Los Angeles and San Diego metropolitan utilities consolidate vendor relationships for integrated telemetry and managed security services.
Midwest Rust Belt
Legacy manufacturing automation bases in Michigan, Ohio, and Illinois modernize control architectures for operational efficiency gains. NERC CIP enforcement through FERC penalty structures compels transmission owners toward audited compliance frameworks. Chicago and Detroit industrial corridors maintain extensive installed bases of hardwired programmable logic controllers despite integration friction.
Southeast
Bulk electric system operators across Georgia, Florida, and the Carolinas respond to NERC CIP audit requirements with dedicated cybersecurity procurement line items. Chemical facilities along the Gulf-facing coastlines face OSHA process safety management rules reshaping alarm rationalization protocols. Atlanta and Charlotte emerge as procurement hubs for regional utility consolidation.
Pacific Northwest
Hydropower-dominated generation portfolios require specialized control architectures for real-time grid balancing and environmental compliance monitoring. Seattle and Portland municipal utilities pioneer hybrid cloud deployments with constrained capital expenditure flexibility. The region's technology sector proximity accelerates pilot programs for containerized software stacks porting across edge and cloud environments.
United States SCADA Market Key Industry Players
Industrial automation conglomerates and specialized control system providers split the market through divergent platform strategies. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with process industry heritage, software-native challengers with subscription-centric business models, and electrical equipment specialists with infrastructure integration capabilities. Competitive positioning hardens through vertical integration into cybersecurity services and geographic anchoring in high-growth utility corridors.
Within the diversified industrial tier, Rockwell Automation and Emerson Electric exemplify contrasting platform approaches. Rockwell leverages its Logix architecture dominance across Rust Belt manufacturing deployments. Emerson sustains deep relationships with oil and gas majors through distributed control heritage. Schneider Electric occupies a hybrid position, competing for municipal water district contracts through integrated EcoStruxure offerings. Honeywell International and ABB represent additional scale anchors with cross-sector process control portfolios. Siemens and General Electric round out the multinational tier with transmission and generation sector concentration.
| Leading Market Players |
|---|
| Rockwell Automation |
| Emerson Electric |
| Honeywell International |
| Schneider Electric |
| ABB |
| Siemens |
| General Electric |
| Yokogawa Electric |
| Inductive Automation |
| Others |
Cost & Logistics Intelligence
The Houston-Beaumont-Port Arthur corridor concentrates Gulf Coast petrochemical capacity, giving integrated automation vendors pricing leverage over municipal utilities facing compressed EPA compliance timelines. Supply tightness for encrypted control hardware feeds through to premium tiering for zero-trust architectures.
Pricing Analysis
Texas and California exhibit the widest price spreads, with Gulf Coast petrochemical operators absorbing 15-20% premiums for process safety-certified systems versus standard municipal water configurations. Three-tier pricing structure across premium, standard, and economy levels separates EPA-compliant encrypted architectures from legacy serial replacements and entry-level RTU-only deployments. Pricing pressure stems from municipal budget cycles constraining capex flexibility, squeezing mid-tier software subscriptions. Water utilities in drought-stressed districts prove most price-sensitive, while NERC CIP-regulated transmission owners show lowest elasticity due to FERC penalty exposure.
Supply Chain Analysis
Export control regimes under the Department of Commerce's Entity List restrict certain programmable logic controller firmware and cryptographic modules, constraining flows to specified end-users. Manufacturing concentrates in Germany, Japan, and the United States for precision industrial controllers, with Mexico and Taiwan supplying discrete component assemblies. Semiconductor content for edge-native RTUs draws from South Korean and Taiwanese foundries, creating single-source vulnerability for automotive-grade chips. Distribution runs through authorized systems integrators with OT cybersecurity certifications, bypassing traditional industrial distribution for critical infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States SCADA market sits in early-cycle expansion as EPA cybersecurity directives force replacement waves across decades-old municipal water infrastructure. Penetration of encrypted, access-controlled architectures remains below 35% in public water systems, leaving substantial runway for compliance-driven procurement.
For Market Incumbents: Entrench platform dominance through backward integration into managed security services, capturing recurring revenue from municipal customers with constrained capex. Anchor large manufacturing deployments across the Rust Belt with Logix-architecture stickiness. Defend against software-native challengers by embedding analytics subscriptions into existing DCS maintenance contracts, reducing switching incentives for hybrid cloud migrations. For New Entrants and Emerging Players: Build out specialized OT cybersecurity practices targeting California water districts with drought-driven efficiency mandates layered onto compliance requirements. The most penetrable white-space sits in edge-native SCADA for Texas renewable energy developers managing intermittent generation profiles. Lead with containerized software stacks that port across on-premises and cloud environments, reducing integration risk for utilities consolidating vendor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with hybrid deployment capabilities spanning air-gapped legacy and cloud-native futures. Long-term viability hinges on recurring revenue attach rates from subscription analytics and managed compliance services. Acquisition targets should demonstrate certified NERC CIP frameworks and EPA-aligned cybersecurity architectures. The signal to watch is FERC penalty escalation driving transmission owners toward audited compliance frameworks, accelerating replacement cycles for encrypted Ethernet architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized software stacks porting across edge, on-premises, and hybrid environments reduce municipal integration risk. |
| Acquisition of Specialist Firm | OT cybersecurity boutiques with EPA compliance expertise capture attach rates from water utilities facing directive deadlines. |
| Strategic Partnership | Systems integrator alliances with certified NERC CIP practices open transmission owner procurement channels in the Midwest. |
| Product Launch | Edge-native SCADA platforms with embedded analytics address Texas renewable energy latency requirements for grid stabilization. |
| Geographic Expansion | California water district consolidation creates demand for integrated telemetry and managed security service bundles. |
Research Approach
A spread of perspectives from control systems engineers, municipal utility procurement officers, OT cybersecurity consultants, and petrochemical facility managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement records, FERC penalty disclosures, NERC CIP audit filings, and state-level utility capital expenditure reports. Bottom-up segment sizing triangulated against top-down infrastructure investment forecasts across water, energy, and manufacturing verticals.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by product type, end-use vertical, deployment architecture, and technology generation. CAGRs derived from infrastructure replacement cycle analysis, regulatory deadline mapping, and adoption curve projections for edge computing integration. Forecast inputs incorporated EPA directive implementation timelines, NERC CIP enforcement intensity, and renewable energy interconnection queue data.
Sensitivities concentrate around EPA rulemaking acceleration, FERC penalty recalibration, and semiconductor supply normalization for industrial controller production. Forecasts reflect documented assumptions regarding municipal budget cycle constraints and petrochemical capacity expansion schedules. Material shifts in cybersecurity mandate scope or federal infrastructure funding levels would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Operational Predictive Maintenance Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
North America Factory Automation and Industrial Controls Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Motion Control Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
North America Smart Factory Market
Industrial Automation
Industrial Automation Motion Control System Software Market
Industrial Automation
Programmable Logic Controller [PLC] Market