
 Shopping Application Market | 2026-2036
Shopping Application Market Size, Share, and Industry Trends Forecast 2026-2036
Shopping Application Market Intelligence
GDPR enforcement in Europe is hardening data localization requirements for cross-border e-commerce platforms. Amazon leverages its fulfillment infrastructure to sustain Prime delivery guarantees across fragmented regulatory environments. Alibaba anchors its competitive stance through integrated payment ecosystems that bypass traditional banking rails. Shein navigates evolving customs duties and import compliance regimes by diversifying its supplier footprint.
Shopping applications are software platforms enabling commercial transactions through digital interfaces, typically processing payments via encrypted tokenization and API-connected banking networks while maintaining inventory synchronization across distributed warehouse management systems. Their primary commercial purpose is reducing friction between product discovery and purchase completion through personalized algorithmic curation. Mobile apps currently dominate transaction volume among platform types, while progressive web apps represent the fastest-growing deployment model for emerging market penetration where storage-constrained devices limit native app adoption. Digital wallets within payment method segmentation command the most attractive margin pools through interchange fee structures and float revenue.
The EU AI Act imposes algorithmic transparency mandates on recommendation engines, directly affecting feature-set compliance costs for product suggestion modules. India's PLI scheme for electronics manufacturing indirectly supports domestic shopping application infrastructure by reducing device costs for end-users. The US FTC scrutinizes dark pattern design practices that manipulate checkout flows. Stakeholders must weigh regulatory compliance investments against the competitive advantage of preemptive transparency standards.
Market Dynamics
Algorithmic personalization engines are absorbing disproportionate platform investment as Gen Z purchasing behaviors force mobile-first architecture redesigns across merchant ecosystems.
Growth Catalysts
- EU AI Act transparency mandates:Compliance investments are accelerating explainable recommendation engine development, creating competitive differentiation for early adopters.
- India's PLI electronics scheme:Reduced smartphone production costs are expanding addressable device penetration into tier-two urban corridors.
- Progressive web app deployment:Storage-constrained emerging market devices are bypassing native app friction, opening merchant access without download barriers.
Market Restraints
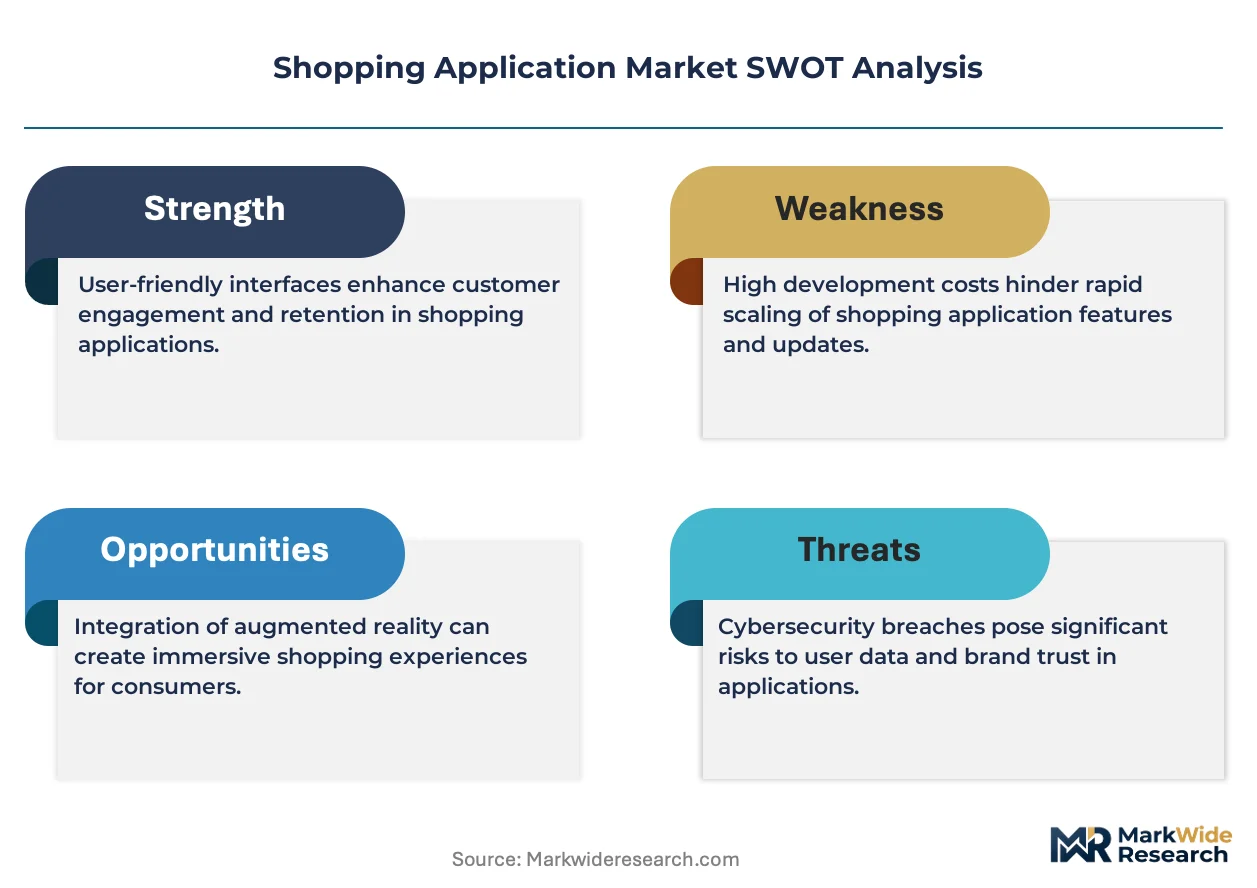
- GDPR data localization:Cross-border e-commerce platforms face hardened infrastructure duplication requirements across European jurisdictions.
- Customs duty volatility:Fast-fashion import compliance regimes are forcing supplier footprint diversification, fragmenting inventory coordination.
- Interchange fee compression:Digital wallet margin pools are facing regulatory scrutiny on payment network economics.
Strategic Opportunities
- India tier-two expansion:Smartphone deepening beyond metropolitan centers is creating first-mover advantage in underbanked consumer segments.
- API-banking convergence:Embedded finance integration is absorbing traditional banking rails into merchant checkout flows.
- FTC dark pattern enforcement:Preemptive transparent design standards are converting compliance cost into trust-based conversion rate gains.
Industry Challenges
- Algorithmic audit talent scarcity:EU AI Act compliance is requiring specialized machine learning interpretability expertise that outpaces labor market supply.
- Legacy warehouse management integration:Real-time inventory synchronization across distributed fulfillment nodes demands costly middleware redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shopping Application Market |
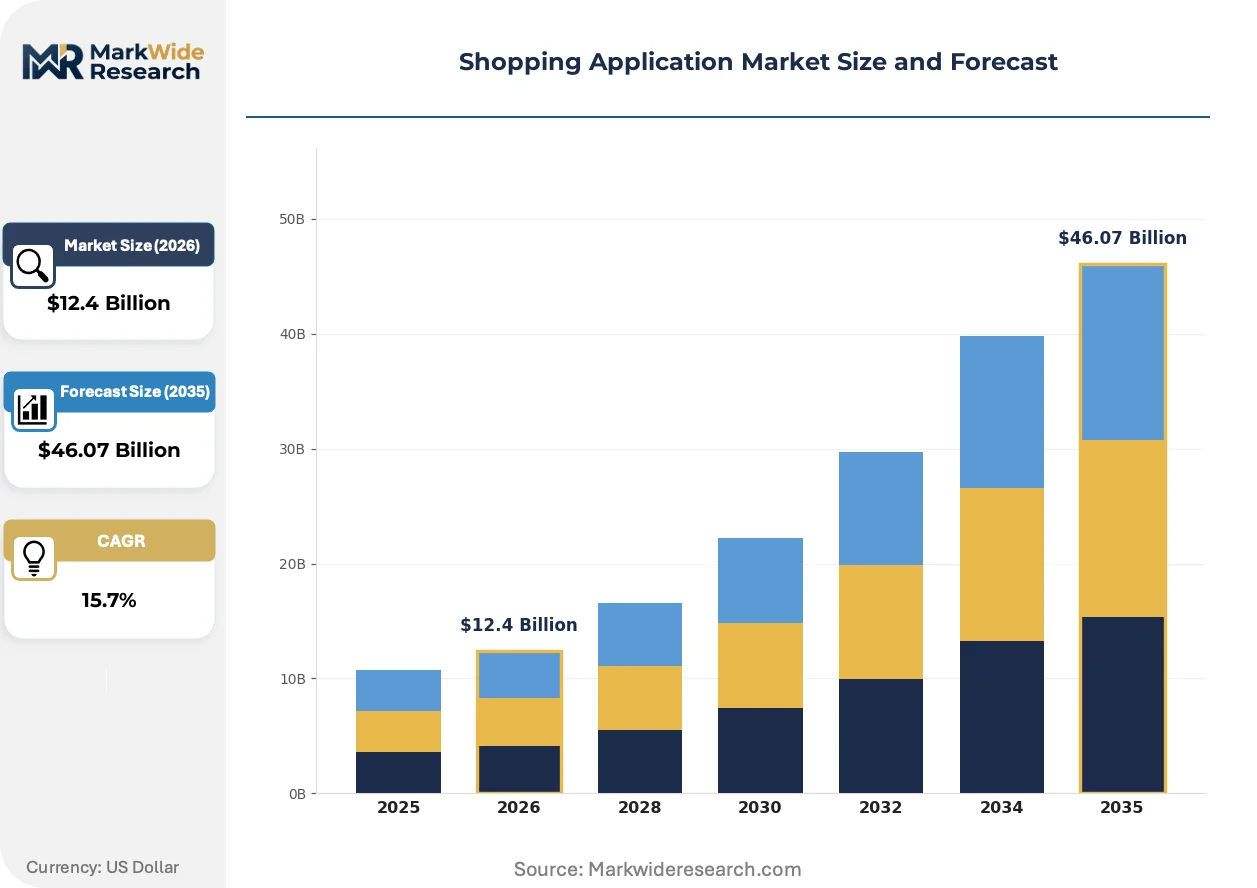
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $46.07 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Retail Consumers, Business Owners, Enterprises, Freelancers Platform: Mobile Apps, Web Apps, Hybrid Solutions, Progressive Web Apps Payment Method: Credit Card, Debit Card, Digital Wallets, Bank Transfer Feature Set: Product Recommendations, Price Comparison, User Reviews, Order Tracking |
| Companies Covered | Alibaba, Nike, Amazon, Zara, H&M, eBay, Shein, Flipkart, Walmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shopping Application Market Strategic Shifts & Innovations
Encrypted tokenization protocols are reshaping payment security architectures while regulatory frameworks fragment across jurisdictions. Platform engineering teams must now balance velocity against multi-territorial compliance obligations.
Progressive web application technology is absorbing merchant development resources previously allocated to native iOS and Android builds. Tier-two Indian cities and Southeast Asian provinces are adopting these lightweight interfaces fastest, compressing time-to-first-purchase for data-conscious users. The structural consequence is a flattening of platform distribution economics, as storage constraints no longer gate market entry.
EU AI Act algorithmic transparency requirements are mandating explainable recommendation engine documentation. Product suggestion modules face heightened compliance costs, particularly for cross-border platforms serving French and German consumer bases. Affected merchants are responding by relocating model training infrastructure to EU sovereign cloud environments.
Mobile-first purchasing behaviors are displacing desktop conversion funnels among Gen Z cohorts. Social commerce discovery channels are replacing traditional search-based product finding in Indian and Brazilian urban markets. This rotation is most visible in fashion and electronics verticals, where influencer-mediated discovery now drives majority transaction initiation.
Shopping Application Market Segmentation
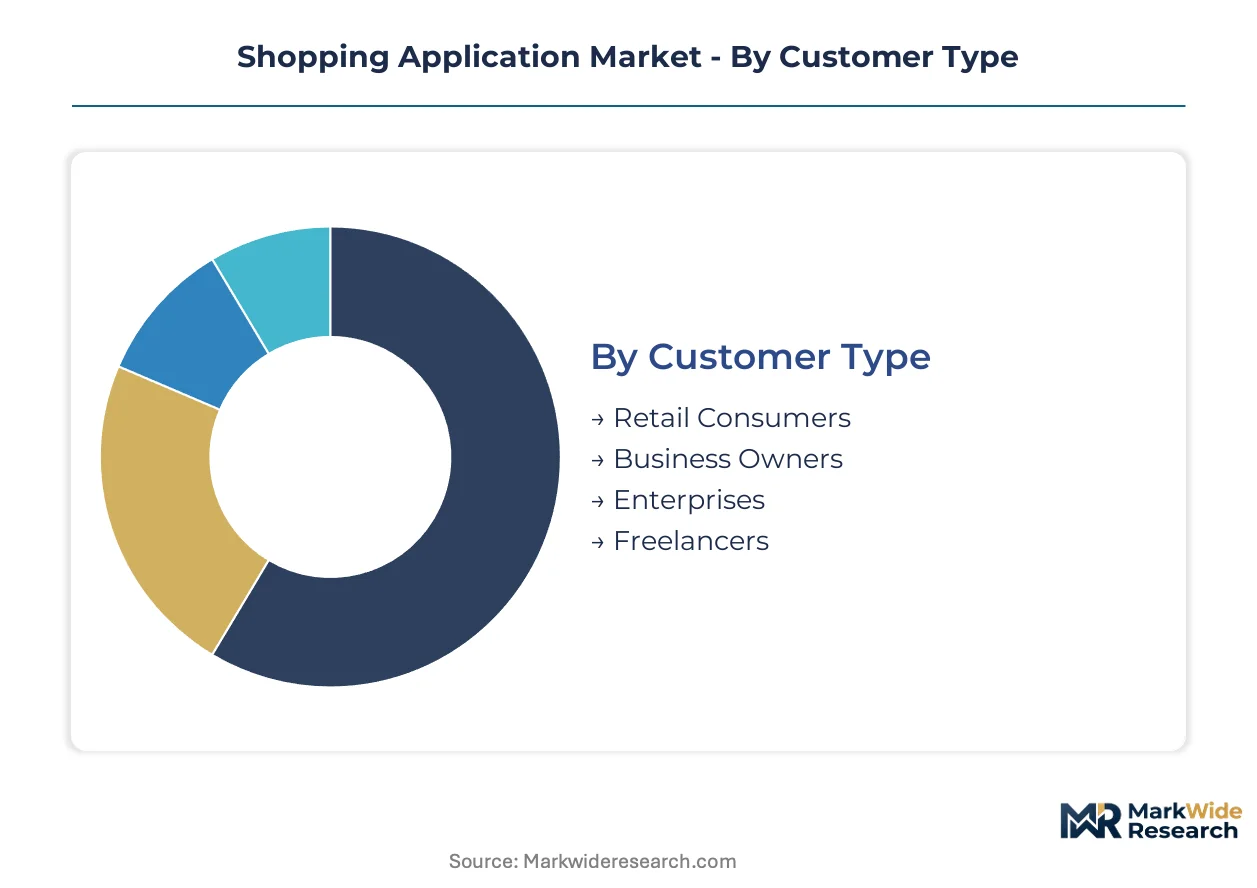
Shopping application segmentation reveals divergent monetization paths across user maturity levels and technical deployment choices. Platform architecture decisions directly determine addressable market breadth in bandwidth-constrained environments.
Customer Type:
Commercial sophistication separates buyers into distinct service tiers with escalating integration requirements.
- Retail Consumers:Individual purchasers transacting through streamlined interfaces with minimal onboarding friction. India's tier-two cities concentrate demand as smartphone penetration deepens beyond metropolitan centers, though Gen Z mobile-first behaviors force continuous UX redesigns.
- Business Owners:Small-scale merchants requiring inventory synchronization and multi-channel listing management. These users absorb disproportionate customer support resources while generating recurring SaaS subscription revenue.
- Enterprises:Large retailers demanding API-connected ERP integration and white-label customization. Procurement concentrates among Fortune 500 retail chains consolidating vendor relationships.
- Freelancers:Independent sellers operating through marketplace aggregators with limited technical infrastructure. Gig-economy expansion in Southeast Asian urban corridors sustains this segment's volume contribution.
Retail consumers lead volumes today; business owners are gaining share fastest.
Platform:
Storage constraints and connectivity quality dictate deployment economics across emerging versus mature markets.
- Mobile Apps:Native iOS and Android applications dominating transaction volume through optimized performance. Gen Z purchasing behaviors cement this platform's commercial centrality despite development cost premiums.
- Web Apps:Browser-based interfaces retaining relevance for desktop-anchored B2B procurement workflows. Enterprise buyers in regulated European jurisdictions favor these deployments for audit trail transparency.
- Hybrid Solutions:Cross-platform frameworks balancing code reuse against native feature access. Development teams facing EU AI Act compliance deadlines increasingly adopt these for faster iteration cycles.
- Progressive Web Apps:Lightweight browser-based experiences bypassing app store distribution friction. Storage-constrained devices in Indian tier-two cities and Southeast Asian provinces drive steepest expansion trajectory here.
Mobile apps anchor revenue today; progressive web apps are climbing the fastest.
Payment Method:
Interchange economics and regulatory scrutiny fragment margin structures across transaction rails.
- Credit Card:Revolving credit instruments commanding premium interchange fees in North American markets. FTC scrutiny of dark pattern design practices affects checkout flow optimization for this method.
- Debit Card:Direct bank account debiting with compressed margins but higher authorization success rates. European GDPR data localization requirements complicate cross-border routing.
- Digital Wallets:Tokenized stored-value systems capturing float revenue and network effects. RBI oversight in India and EU payment service regulations reshape competitive dynamics for wallet providers.
- Bank Transfer:Account-to-account settlement bypassing card network economics. India's UPI infrastructure demonstrates how real-time rails displace traditional payment intermediaries.
Digital wallets dominate margin pools today; bank transfer volumes are expanding most quickly.
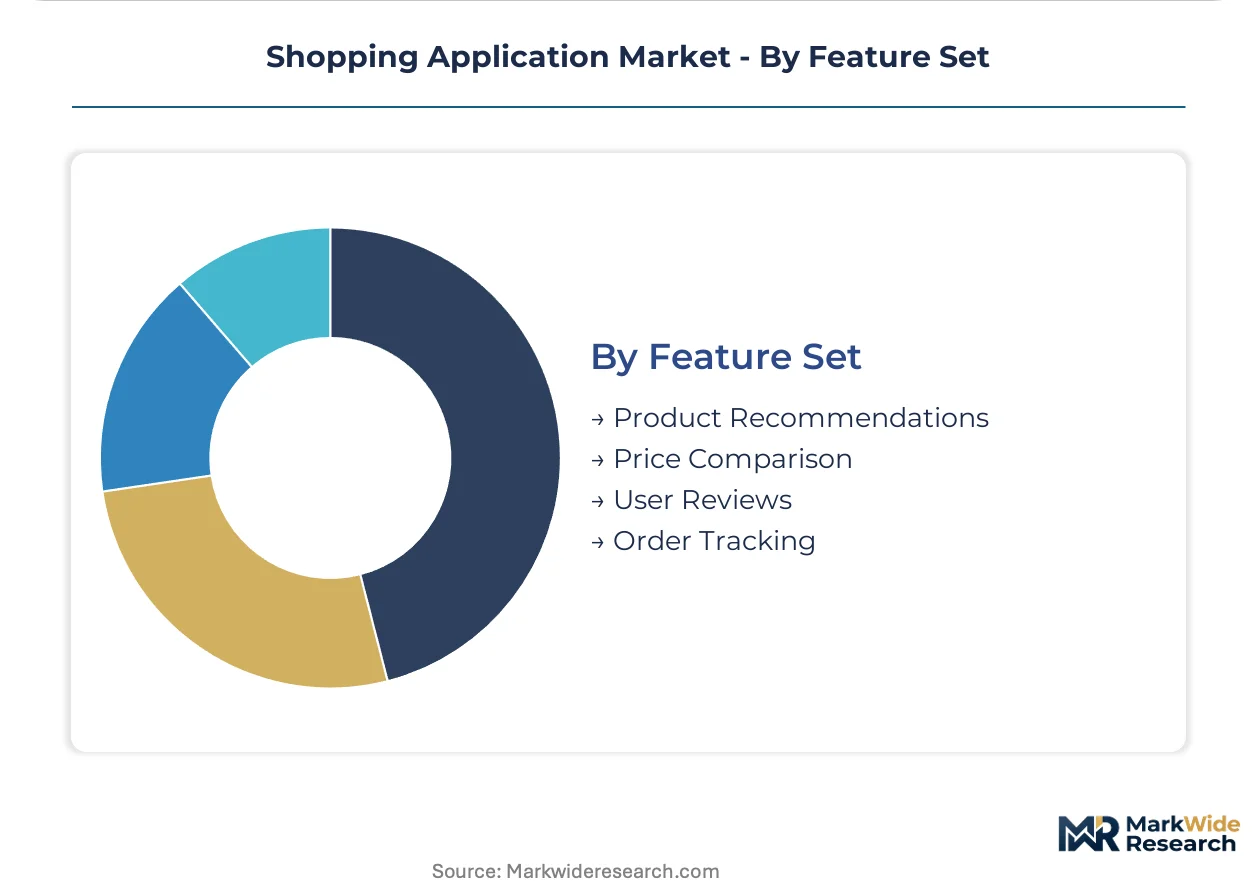
Feature Set:
Algorithmic capabilities differentiate platforms while compliance costs escalate for AI-driven modules.
- Product Recommendations:Machine learning engines curating inventory exposure based on behavioral signals. EU AI Act transparency mandates force explainable model documentation, raising development overhead.
- Price Comparison:Real-time aggregation across competing merchants enabling informed purchasing decisions. Freemium platforms deploy this feature to capture user acquisition before monetization.
- User Reviews:Social proof mechanisms reducing perceived purchase risk. FTC enforcement against manipulated review ecosystems elevates content moderation investments.
- Order Tracking:Logistics visibility integrating warehouse management systems with last-mile carriers. Amazon's fulfillment infrastructure sets baseline consumer expectations here.
Product recommendations absorb the most R&D investment today; order tracking is gaining feature priority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Bangalore, Shenzhen, and Seattle anchor platform development for shopping applications, concentrating algorithmic personalization expertise and cloud infrastructure investment in these metropolitan clusters.
United States
Gen Z mobile-first purchasing behaviors drive transaction volume concentration on the coasts, with Los Angeles and New York metro areas generating disproportionate engagement metrics. FTC scrutiny of dark pattern design practices elevates compliance investment for checkout flow optimization. Seattle's cloud infrastructure cluster hosts the dominant fulfillment and recommendation engine architectures serving North American consumers.
China
Integrated payment ecosystems bypassing traditional banking rails absorb the majority of transaction value, with Hangzhou and Shenzhen anchoring super-app development. MIIT data governance requirements reshape cross-border data routing for platforms serving international Chinese consumers. The Yangtze River Delta manufacturing corridor supplies the electronics inventory flowing through domestic shopping applications.
India
Tier-two urban corridors including Jaipur, Lucknow, and Indore concentrate smartphone penetration growth beyond saturated metropolitan markets. RBI oversight of digital wallet providers and UPI infrastructure expansion reshape payment method economics. Karnataka's Bangalore tech cluster generates the engineering talent sustaining platform development for domestic and export-oriented shopping applications.
Germany
GDPR data localization requirements force infrastructure duplication for cross-border e-commerce platforms serving French and German consumer bases. EU AI Act algorithmic transparency mandates elevate compliance costs for product recommendation modules. Berlin's startup ecosystem concentrates explainable AI development talent addressing regulatory requirements.
Brazil
Social commerce discovery channels displace traditional search-based product finding in São Paulo and Rio de Janeiro urban markets. ANVISA oversight of imported electronics affects inventory sourcing for consumer electronics verticals. The São Paulo metropolitan cluster anchors fintech integration development embedding banking rails into merchant checkout flows.
Shopping Application Market Key Industry Players
The competitive structure tilts toward platform ecosystems with integrated fulfillment and payment infrastructure. Consolidation pressures concentrate investment capacity among vertically integrated operators capable of absorbing regulatory compliance costs across multiple jurisdictions. Three archetypes dominate: super-app conglomerates with captive payment networks, fast-fashion specialists with agile supply chains, and marketplace aggregators with third-party logistics partnerships. Geographic expansion and algorithmic transparency investments represent the dominant competitive moves reshaping positioning.
Among Asia-based platform operators, Alibaba exemplifies the super-app archetype through its integrated payment and logistics ecosystem. Amazon and Walmart represent the fulfillment-heavy marketplace model with captive infrastructure investments spanning multiple continents. Shein occupies a position within the fast-fashion specialist tier, demonstrating supply chain agility in navigating customs duty volatility across fragmented regulatory environments.
| Leading Market Players |
|---|
| Alibaba |
| Nike |
| Amazon |
| Zara |
| H&M |
| eBay |
| Shein |
| Flipkart |
| Walmart |
| Others |
Cost & Logistics Intelligence
Captive fulfillment infrastructure anchors pricing power for vertically integrated platforms, compressing delivery cost premiums that would otherwise erode margin structures in cross-border commerce. Amazon's warehouse network and Alibaba's Cainiao logistics ecosystem exemplify how in-house control over last-mile execution insulates transaction economics from freight volatility.
Pricing Analysis
Platform service bundling versus unbundled SaaS tiers separates merchant pricing structures across the shopping application ecosystem. Three-tier pricing stratifies across premium API-access, standard self-service, and economy marketplace-commission levels, with differentiation driven by customization depth and dedicated support allocation. Cost compression in the economy tier intensifies because interchange fee scrutiny compresses digital wallet margins. Small-scale business owners exhibit highest price sensitivity, while Fortune 500 retail chains absorb premium tiers for ERP integration guarantees.
Supply Chain Analysis
Freight cost volatility from China, Vietnam, and Bangladesh feeds into fast-fashion platform margin pressures, particularly for Shein's agile inventory model. Raw material dependencies span synthetic textiles, semiconductor components for device manufacturing, and packaging substrates. Single-source vulnerability concentrates in Yangtze River Delta electronics assembly, where MIIT data governance restrictions complicate alternative sourcing. Distribution runs through third-party logistics partnerships for marketplace aggregators, while vertical operators maintain captive last-mile networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as Gen Z purchasing behaviors force mobile-first architecture investments that favor platforms with preemptive EU AI Act compliance and transparent algorithmic documentation.
For Market Incumbents: Deepen API-banking convergence investments to embed finance into checkout flows before regulatory fragmentation hardens competitive moats. Consolidate warehouse management system middleware to reduce legacy integration costs that emerging players avoid. Defend against progressive web app challengers by accelerating lightweight interface deployment in Indian tier-two corridors.
For New Entrants and Emerging Players: Launch via progressive web app distribution to bypass app store friction in storage-constrained Southeast Asian and Indian tier-two markets. Target underbanked consumer segments where UPI infrastructure expansion reduces payment method barriers. White-label explainable recommendation engines to convert EU AI Act compliance overhead into differentiation against algorithmically opaque incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated mid-cap specialists with captive logistics and payment infrastructure because regulatory compliance costs disproportionately burden fragmented marketplace operators. Watch algorithmic audit talent scarcity as the inflection signal—platforms securing machine learning interpretability expertise will capture pricing power as EU enforcement hardens.
| Strategic Initiative | Industry Significance |
|---|---|
| Progressive Web App Deployment | Lightweight browser-based interfaces bypass download barriers in storage-constrained Indian tier-two cities. |
| EU AI Act Compliance Investment | Explainable recommendation engine documentation converts regulatory overhead into competitive differentiation. |
| API-Banking Integration | Embedded finance absorbs traditional banking rails into merchant checkout flows, capturing interchange economics. |
| Captive Fulfillment Expansion | In-house logistics networks insulate delivery guarantees from customs duty volatility and freight cost swings. |
| Algorithmic Audit Talent Acquisition | Machine learning interpretability expertise scarcity creates defensive moats as transparency mandates harden. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Platform engineering directors, merchant SaaS procurement leads, digital wallet product managers, and logistics operations heads provided operational perspectives. Secondary sources include SEC filings, RBI payment system reports, EU regulatory filings, and customs trade databases. Bottom-up merchant adoption modeling triangulates against top-down smartphone penetration forecasts.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include platform deployment type, customer sophistication tier, payment method, and feature set complexity. CAGRs derive from installed base penetration curves and transaction frequency assumptions. Forecast inputs incorporate UPI transaction velocity trends and EU AI Act implementation timelines.
Several conditions sit outside the modeled scope, including abrupt customs regime shifts, geopolitical data routing restrictions, and hardware subsidy policy changes. Forecasts reflect assumptions about regulatory enforcement intensity and merchant technology refresh cycles. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
North Macedonia E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Apparel Market
E-Commerce Solutions
Australia E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
France E-Commerce Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Direct-To-Consumer Test Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
Cross-Border B2C E-Commerce Market
E-Commerce Solutions
India E-Commerce Warehousing Market