
 LTE Emergency Networks Market | 2026-2036
LTE Emergency Networks Market Size, Share, and Industry Trends Forecast 2026-2036
LTE Emergency Networks Market Insights
Municipal fire departments and regional emergency management offices are redrawing procurement priorities for LTE emergency networks. Motorola Solutions leverages decades of land-mobile radio integration to anchor its position in hybrid dispatch systems. Nokia competes through 3GPP-standardized mission-critical push-to-talk platforms. Samsung Electronics extends its reach via ruggedized handset ecosystems tailored for first responders.
LTE emergency networks deliver dedicated broadband connectivity over 700 MHz Band 14 spectrum with sub-50 millisecond latency for voice, video, and data transmission during catastrophic events. The technology replaces aging TETRA and P25 narrowband systems with IP-based architectures that support real-time situational awareness and geolocation services. Crisis management services dominate contract value as agencies prioritize unified command platforms, while cloud-based deployment models capture the fastest expansion trajectory among infrastructure options. Hybrid architectures retain strong positioning where agencies require local survivability with centralized analytics.
The FCC's FirstNet authority mandates interoperable standards that shape vendor certification requirements and procurement eligibility across U.S. public safety agencies. ETSI's MCPTT specifications and the 3GPP Release framework govern European and Asian equipment interoperability, filtering market access for non-compliant suppliers. Stakeholders must monitor spectrum reallocation debates and 3GPP Release evolution to align R&D roadmaps with emerging mission-critical data requirements.
Market Dynamics
The migration from narrowband TETRA and P25 systems to LTE-based mission-critical broadband is compressing procurement cycles and forcing interoperability investments across public safety agencies. This technology displacement creates simultaneous pull for new infrastructure and drag from legacy sunk costs.
Growth Catalysts
- FirstNet Mandate:The FCC's dedicated Band 14 spectrum allocation for first responders accelerates dedicated network deployment across U.S. public safety agencies.
- MCPTT Standardization:ETSI's Mission-Critical Push-to-Talk specifications enable cross-vendor interoperability, reducing procurement risk for European emergency services.
- Real-Time Video Demand:Body-worn camera and drone footage transmission requirements drive bandwidth upgrades beyond narrowband capacity limits.
Market Restraints
- Legacy System Sunk Costs:TETRA and P25 infrastructure investments create depreciation barriers to full LTE replacement for budget-constrained municipal agencies.
- Semiconductor Supply Concentration:Mission-critical chipset fabrication concentrates in Taiwan and South Korea, exposing procurement timelines to geopolitical disruption.
- Spectrum Fragmentation:Non-harmonized national spectrum allocations complicate equipment certification and cross-border mutual aid interoperability.
Strategic Opportunities
- Rural Coverage Gaps:Unserved territories in Australia and Canada present greenfield deployment potential for satellite-LTE hybrid architectures.
- AI-Enabled Analytics:Convergence of edge computing with mission-critical networks enables predictive incident routing for metropolitan fire departments.
- Cloud-Native Dispatch:Software-as-a-service models reduce upfront capital requirements for small and mid-sized emergency management offices.
Industry Challenges
- Interoperability Certification Delays:3GPP Release compliance testing extends vendor qualification timelines by 12-18 months for multi-agency deployments.
- Cybersecurity Skill Scarcity:Public sector salary constraints limit recruitment of LTE network security specialists for continuous threat monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LTE Emergency Networks Market |
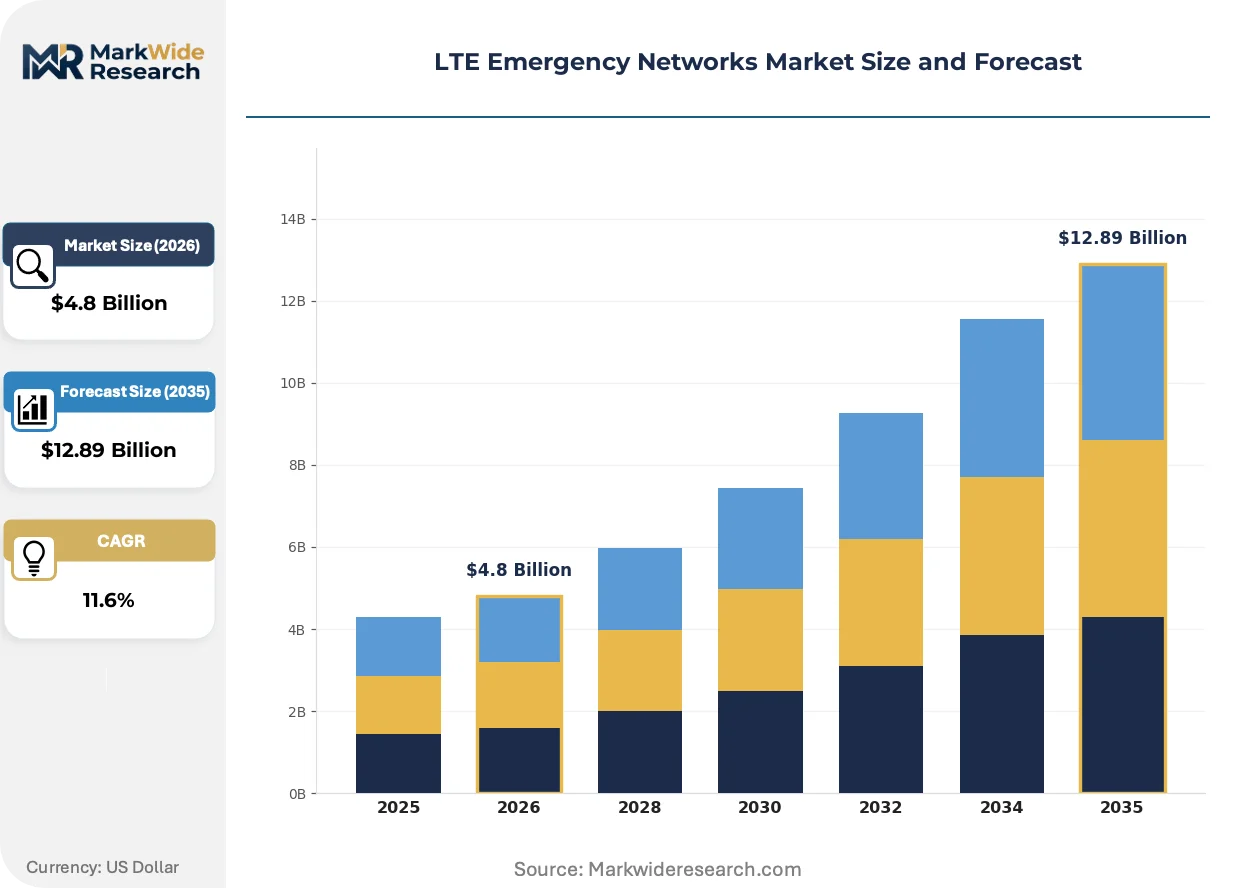
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, GSM, CDMA, WiMAX Service Type: Crisis Management, Incident Response, Rescue Operations, Public Safety End User: Government Agencies, Healthcare Providers, Emergency Services, NGOs Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Nokia, Ericsson, Motorola Solutions, AT&T, Samsung Electronics, Airbus, L3Harris Technologies, General Dynamics Mission Systems, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTE Emergency Networks Market Trends and Innovations
Network function virtualization and open RAN architectures are dissolving traditional vendor lock-in patterns. These shifts enable modular procurement and accelerate feature deployment cycles for mission-critical communications.
Multi-access edge computing is fragmenting centralized network architectures by pushing video analytics and geolocation processing closer to incident sites. State-level emergency management agencies in Texas and California are piloting distributed core networks for disaster-zone autonomy. This topology compression reduces backhaul dependency when fiber links fail during catastrophic events.
ETSI's 3GPP Release 18 framework mandates enhanced mission-critical data services, forcing infrastructure vendors to prioritize broadband data over voice-centric legacy designs. European public safety agencies in Germany and France are conditioning procurement eligibility on Release 18 compliance. Equipment manufacturers are accelerating R&D roadmaps to meet 2025 certification deadlines for next-generation dispatch consoles.
Subscription-based network-as-a-service contracts are displacing capital-intensive ownership models among budget-constrained municipal buyers. Small and mid-sized fire departments in the United Kingdom are consolidating purchasing through regional cooperative agreements. This buyer aggregation concentrates negotiating leverage and compresses vendor margins while expanding addressable market access for cloud-native providers.
LTE Emergency Networks Market Segmentation
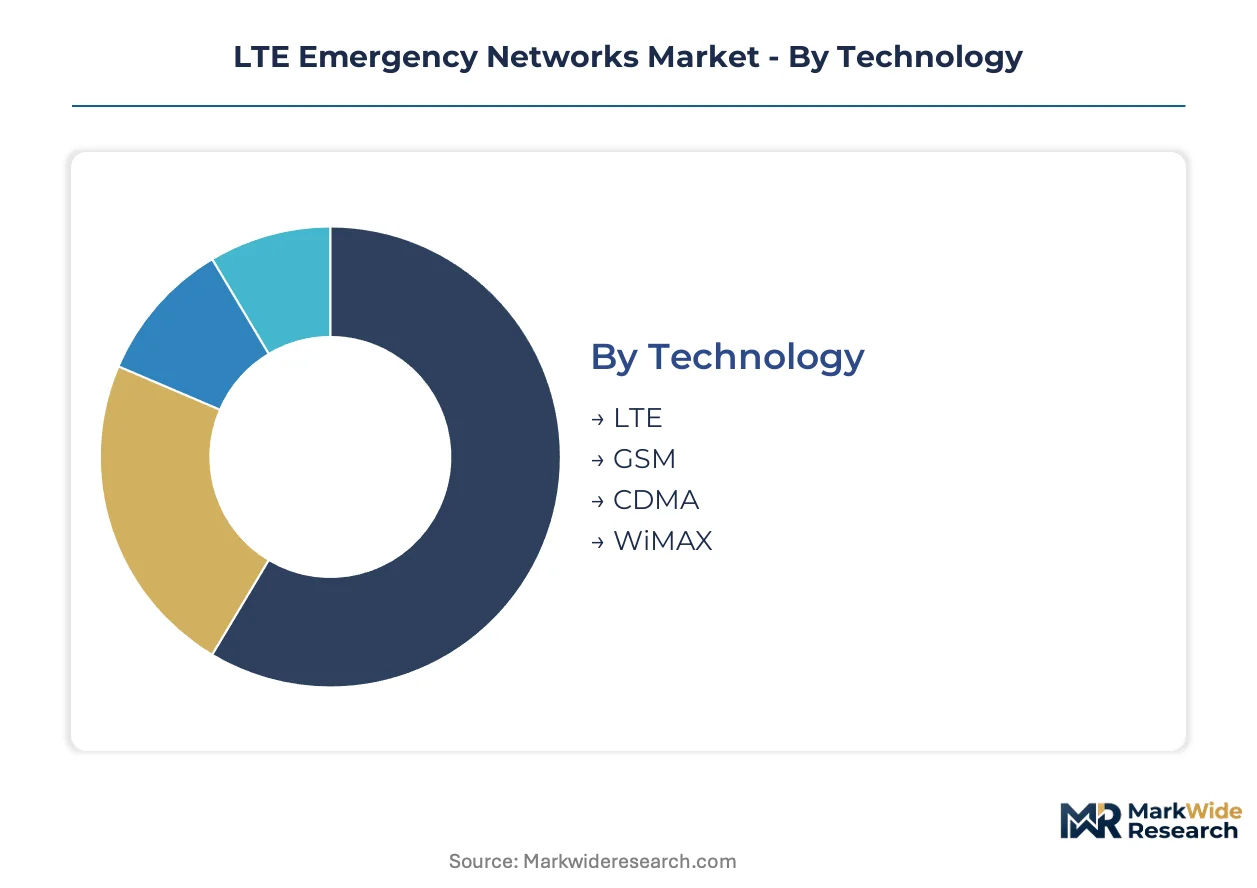
Segmentation of the LTE emergency networks market reveals how procurement priorities diverge across technology generations, operational mandates, and infrastructure ownership models. Agencies weigh legacy interoperability against broadband capability when allocating constrained public safety budgets.
Technology:
Geographic concentration varies sharply across wireless standards, with LTE dominating FirstNet deployments in the United States while GSM retains residual presence in legacy European public safety systems.
- LTE:The 700 MHz Band 14 standard delivers sub-50 millisecond latency for mission-critical push-to-talk, video streaming, and geolocation services. United States fire departments and state police agencies concentrate procurement here, driven by FCC FirstNet mandates and federal subsidy programs.
- GSM:Narrowband voice architecture persists in Eastern European municipal networks and select Asian emergency services where TETRA-to-LTE migration timelines extend. Budget constraints and equipment depreciation schedules delay replacement cycles.
- CDMA:Legacy circuit-switched infrastructure remains operational in isolated North American rural counties and select Latin American public safety networks.
- WiMAX:Fixed wireless broadband deployment characterizes early-adopter emergency management jurisdictions in South Korea and parts of the Middle East, though 3GPP standardization pressures limit new investment.
LTE commands the established base. The steepest expansion runs through hybrid LTE-satellite architectures addressing rural coverage gaps.
Service Type:
Cost tiering separates capital-intensive unified command platforms from modular, subscription-based incident tools that smaller agencies favor.
- Crisis Management:Unified command platforms integrating multi-agency dispatch, resource allocation, and predictive analytics concentrate contract value at state and federal levels. German federal police and California Office of Emergency Services anchor demand, propelled by requirements for cross-jurisdictional coordination during wildfire and flood events.
- Incident Response:Real-time situational awareness systems combining body-worn video, drone feeds, and mobile data terminals dominate municipal fire and EMS procurement in the United Kingdom and Australia.
- Rescue Operations:Search-and-rescue teams in alpine regions and coastal jurisdictions deploy specialized push-to-talk and geofencing capabilities.
- Public Safety:General-purpose broadband connectivity serves routine patrol and administrative functions across mid-sized urban police departments.
Crisis management captures the premium tier. Incident response is climbing the fastest as video-enabled field units proliferate.
End User:
Customer type determines procurement authority complexity, with federal agencies consolidating purchasing power while NGOs navigate fragmented funding streams.
- Government Agencies:Federal and state emergency management authorities in the United States, Germany, and South Korea drive standardization through centralized acquisition frameworks. Multi-year network-as-a-service contracts reduce capital exposure.
- Healthcare Providers:Hospital systems and regional health authorities deploy LTE for ambulance-to-ER prehospital communication and mass casualty triage coordination.
- Emergency Services:Municipal fire departments, police precincts, and EMS operators constitute the volume base, with procurement fragmented across thousands of independent jurisdictions.
- NGOs:International relief organizations and domestic nonprofit responders rely on portable, rapidly deployable satellite-LTE hybrid kits for disaster-zone autonomy.
Government agencies anchor procurement volume. Healthcare providers are expanding most quickly as prehospital data integration mandates tighten.
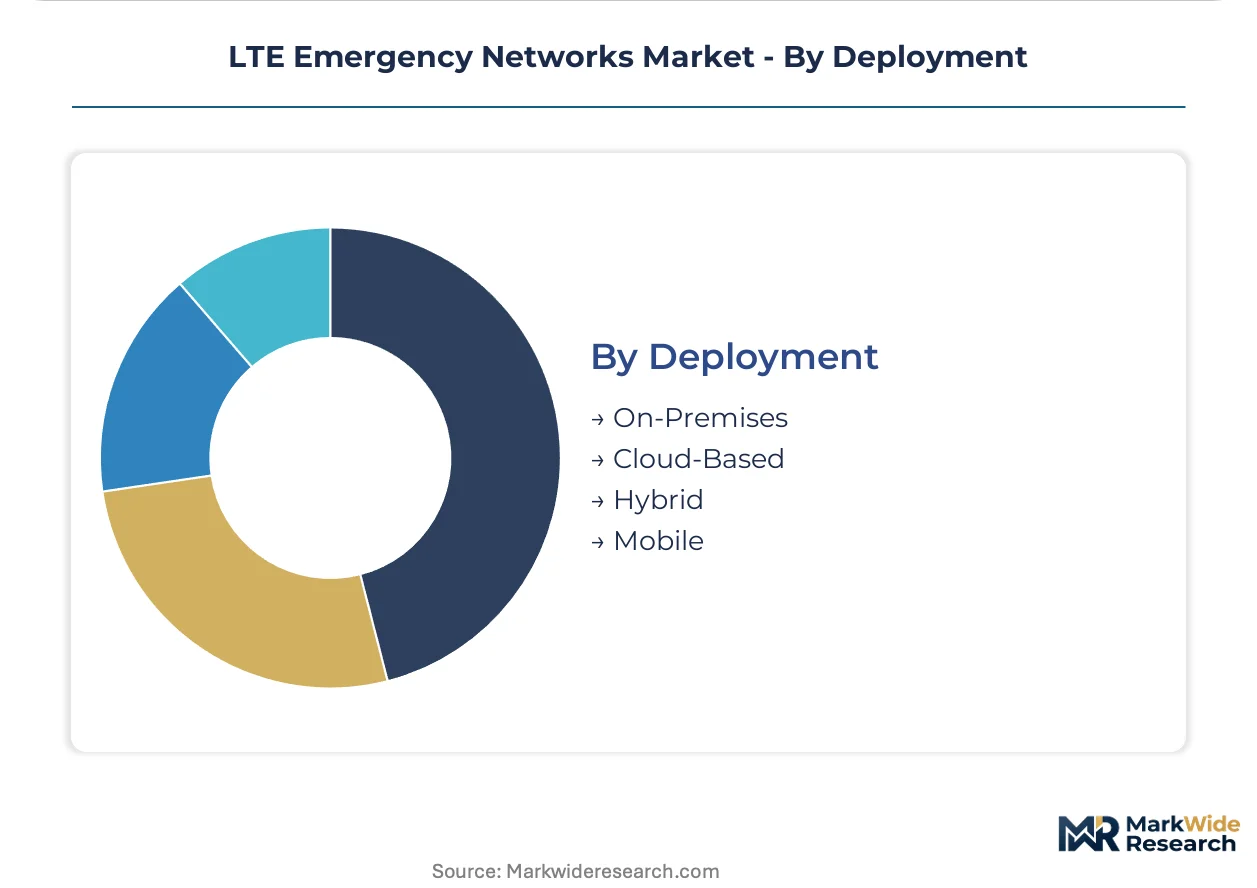
Deployment:
Maturity gradients separate legacy on-premises infrastructure from cloud-native architectures that accelerate feature deployment cycles.
- On-Premises:Dedicated hardware installations in hardened facilities provide local survivability for dispatch centers in seismically active zones and hurricane-prone coastal regions. Texas and California state agencies maintain these for fiber-failover scenarios.
- Cloud-Based:Software-as-a-service dispatch platforms enable small and mid-sized fire departments in the United Kingdom to consolidate purchasing through regional cooperative agreements, compressing vendor margins while expanding access.
- Hybrid:Local edge computing with centralized analytics balances survivability and scalability, dominating procurement among metropolitan police departments transitioning from TETRA.
- Mobile:Vehicle-mounted and portable rapid-deployment units serve wildfire incident command posts and temporary emergency operations centers.
Hybrid architectures hold the current majority. Cloud-based deployment is gaining share fastest as subscription models reduce upfront capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FirstNet Band 14 spectrum allocation underwrites the United States' position as the primary deployment jurisdiction for LTE emergency networks, with dedicated first-responder broadband infrastructure now operational across all 50 states.
United States
State police agencies and municipal fire departments drive procurement volume through FirstNet Authority contracts. The FCC mandates interoperable standards that shape vendor certification requirements nationwide. Texas and California state emergency management agencies pilot distributed core networks for disaster-zone autonomy.
Germany
Federal police and state-level emergency services prioritize unified command platforms for cross-jurisdictional coordination. ETSI's MCPTT specifications govern equipment interoperability and filter market access. The Bavarian and North Rhine-Westphalia clusters anchor R&D investment for next-generation dispatch consoles.
South Korea
National public safety agencies deploy hardened infrastructure for mission-critical push-to-talk and real-time video transmission. The MFDS and national spectrum authorities harmonize equipment certification with 3GPP Release frameworks. Seoul Capital Area metropolitan police consolidate procurement through multi-year network-as-a-service agreements.
United Kingdom
Regional fire authorities and ambulance trusts transition from TETRA to LTE-based emergency services networks. The Home Office oversees the Emergency Services Network procurement framework. Small and mid-sized fire departments in England and Wales consolidate purchasing through cooperative agreements.
Australia
Rural coverage gaps in unserved territories drive demand for satellite-LTE hybrid architectures. The national broadband and emergency management authorities coordinate spectrum allocation for first-responder networks. State-level emergency services in New South Wales and Victoria lead deployment of mobile rapid-deployment units for wildfire incident command.
LTE Emergency Networks Market Competitive Landscape
Concentration sits with diversified telecommunications equipment manufacturers and specialized public safety communications providers. The vendor base spans three tiers: infrastructure-scale network equipment suppliers, integrated land-mobile radio specialists, and cloud-native software platforms. Strategic moves center on 3GPP Release compliance certification and hybrid architecture partnerships that bridge legacy narrowband systems with broadband IP networks.
Within the infrastructure tier, Nokia and Ericsson represent the archetype of 3GPP-standardized mission-critical platform suppliers, while Motorola Solutions occupies a position exemplifying decades of land-mobile radio integration into hybrid dispatch systems. Samsung Electronics anchors the ruggedized handset ecosystem specialization for first responder field deployment.
| Leading Market Players |
|---|
| Nokia |
| Ericsson |
| Motorola Solutions |
| AT&T |
| Samsung Electronics |
| Airbus |
| L3Harris Technologies |
| General Dynamics Mission Systems |
| Huawei Technologies |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month vendor qualification timelines for multi-agency LTE deployments compress procurement flexibility and amplify pricing power for certified infrastructure suppliers. This lead-time rigidity concentrates negotiation leverage among 3GPP Release-compliant vendors while municipal agencies absorb premium pricing for mission-critical chipset security.
Pricing Analysis
Volume-discount tiering separates federal network-as-a-service contracts from fragmented municipal procurement. Three-tier pricing structure across enterprise-grade, mid-tier, and basic interoperability levels reflects certification depth and after-sales service bundling. Cost compression in mid-tier municipal segments is intensifying because regional cooperative purchasing aggregates demand. Small and mid-sized fire departments exhibit highest price sensitivity; federal emergency management authorities show lowest.
Supply Chain Analysis
Inventory buffers for mission-critical chipsets rarely exceed 90 days given concentrated fabrication capacity in Taiwan and South Korea. LTE emergency network infrastructure draws from advanced semiconductor foundries, specialized RF component manufacturers, and hardened enclosure fabricators in Germany and the United States. Single-source vulnerability for Band 14-compatible baseband processors exposes procurement timelines to geopolitical disruption. Distribution runs through authorized systems integrators with public safety certification rather than direct vendor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LTE emergency networks market sits at an inflection where 3GPP Release 18 mandates are displacing voice-centric legacy designs, creating asymmetric returns for compliant vendors.
For Market Incumbents: Secure 3GPP Release 18 certification ahead of 2025 procurement eligibility deadlines to lock out non-compliant competitors. Deepen backward integration into mission-critical chipset sourcing to mitigate Taiwan concentration risk. Anchor position through hybrid architecture partnerships that bridge TETRA legacy systems with broadband IP networks.
For New Entrants and Emerging Players: Differentiate on satellite-LTE hybrid architectures for rural coverage gaps in Australia and Canada where incumbents lack deployed infrastructure. Target cloud-native dispatch platforms for UK regional fire authorities consolidating through cooperative agreements. Pursue network-as-a-service subscription models to bypass capital-intensive ownership barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FCC FirstNet mandates and ETSI MCPTT specifications create durable certification moats. Acquisition targets should display 3GPP Release compliance progress plus established relationships with state-level emergency management agencies. Monitor 3GPP Release evolution timelines as the critical signal for R&D recalibration cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| 3GPP Release 18 Certification | ETSI procurement eligibility in Germany and France hinges on compliance deadlines. |
| Hybrid LTE-Satellite Architecture | Australian rural coverage gaps create greenfield deployment opportunities without incumbent displacement. |
| Network-as-a-Service Platform | UK regional cooperative purchasing consolidates municipal demand and compresses vendor margins. |
| Multi-Access Edge Computing Deployment | Texas and California state agencies pilot distributed core networks for disaster-zone autonomy. |
| Mission-Critical Chipset Backward Integration | Taiwan fabrication concentration exposes procurement timelines to geopolitical supply disruption. |
Research Methodology
A spread of perspectives from infrastructure procurement officers at state emergency management agencies, network equipment vendor sales directors, public safety spectrum regulators, and municipal fire department IT managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FCC FirstNet Authority filings, ETSI standardization documents, 3GPP release specifications, and public agency budget appropriations records. Bottom-up deployment projections triangulated against top-down spectrum allocation mandates.
Segmentation dimensions modeled include wireless standard generation, service type tier, end-user procurement authority, and deployment architecture across the analysis window. CAGRs derived from infrastructure investment cycles, equipment replacement timelines, and regulatory compliance deadlines. Forecast inputs incorporated FirstNet subscriber adoption curves, MCPTT standardization rollout schedules, and rural coverage gap closure investments.
The analysis sits within stated boundaries; outcomes outside sustained federal subsidy levels or harmonized spectrum allocations would require recalibration. Forecasts reflect documented assumptions about 3GPP Release adoption, semiconductor supply stability, and municipal budget continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
5G Transport Networks Market
Telecommunications
South Africa Telecom Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
Tetra Terminals Market
Telecommunications
Kenya Telecom Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
IP DECT Phones Market
Telecommunications
Thailand Telecom Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Software Defined Radio Market
Telecommunications
Denmark Telecom Market
Telecommunications
Germany Critical Communication Market
Telecommunications
Cambodia Telecom Market
Telecommunications
Russia Telecom Market
Telecommunications
Australia Telecom Market