
 Virtual CPE (Vcpe) Market | 2026-2036
Virtual CPE (Vcpe) Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual CPE (Vcpe) Market Insights
The shift from proprietary hardware appliances to multi-vendor virtualized software stacks is recalibrating how carriers provision customer premises equipment. Cisco Systems leverages decades of routing heritage to anchor enterprise trust in virtualized form factors, while Juniper Networks competes through Contrail-based orchestration tightly coupled with carrier cloud strategies. VMware extends its data center virtualization dominance into the telco edge, positioning its Telco Cloud platform as a neutral substrate for third-party VNF workloads.
Virtual Customer Premises Equipment (vCPE) replaces dedicated physical boxes at branch sites with software instances running on standard servers, typically handling routing, firewall, and WAN optimization functions through virtualized network functions (VNFs) decoupled from underlying hardware. Deployment model segmentation reveals hybrid cloud configurations capturing the strongest momentum as carriers blend on-premises control with burst capacity to public infrastructure; meanwhile NFV technology underpins the architecture but orchestration layers are where margin pools concentrate due to integration complexity and multi-vendor mediation requirements. Service type dynamics show firewall and router virtualization maturing fastest while load balancer virtualization trails, creating uneven substitution timelines across enterprise edge stacks.
FCC guidelines on network reliability and cybersecurity for communications infrastructure intersect with ETSI NFV standards and NIST cloud security frameworks to establish compliance baselines that shape vendor qualification and procurement. GDPR and emerging national data sovereignty rules in Europe and Asia-Pacific further constrain where virtualized functions may physically execute, directly influencing hybrid deployment architecture decisions. Stakeholders must monitor evolving carrier cloud certification programs and software supply chain security mandates as these will increasingly determine market access eligibility and competitive differentiation.
Market Dynamics
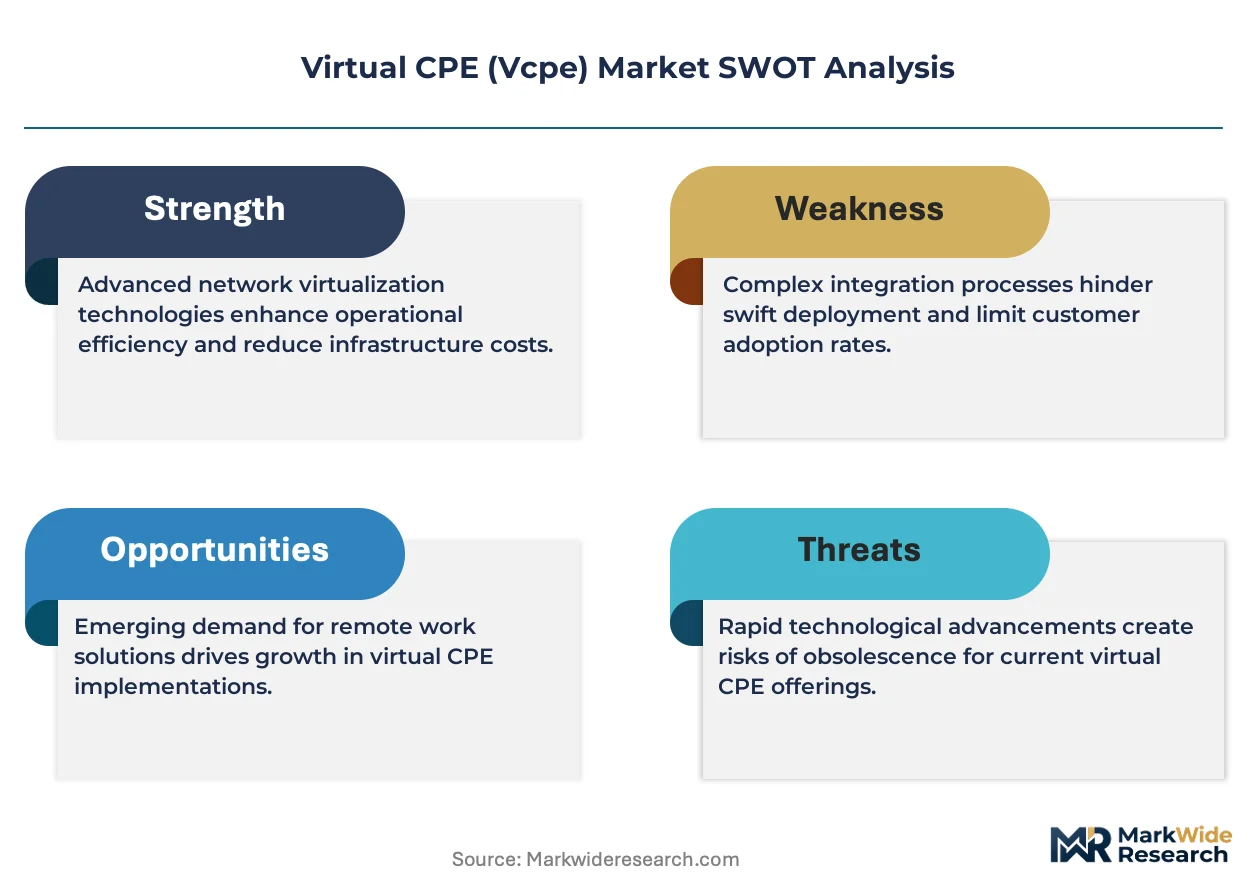
Telecom operators are dismantling proprietary hardware stacks in favor of multi-vendor NFV orchestration, forcing infrastructure procurement toward software-centric evaluation criteria that prioritize interoperability over single-source routing platforms.
Growth Catalysts
- Carrier cloud certification mandates:Tier-one service providers in the United States now require ETSI NFV-compliant orchestration layers, accelerating vendor qualification cycles for virtualized network functions.
- Hybrid edge burst capacity:German and Japanese carriers blend on-premises control planes with public cloud overflow, creating procurement pull for containerized VNF management platforms.
- GDPR data sovereignty enforcement:European operators must localize virtualized function execution, driving investment in geo-fenced edge infrastructure deployments.
Market Restraints
- Silicon supply concentration:NFV infrastructure depends on x86 server chipsets from a narrow supplier base in East Asia, exposing deployment timelines to foundry capacity constraints.
- NFV orchestration complexity:Multi-vendor VNF integration requires specialized systems integrators, inflating deployment costs beyond original hardware replacement estimates.
- Legacy MPLS substitution resistance:Enterprises with existing private circuit contracts resist forklift upgrades to SD-WAN overlays, delaying virtualization timelines.
Strategic Opportunities
- India's BharatNet rural expansion:The country's national broadband mission creates demand for low-cost virtualized CPE to serve distributed village clusters without truck-roll maintenance.
- 5G network slicing convergence:Integration of vCPE with network slice orchestration enables guaranteed SLA tiers for industrial IoT applications.
- US IRA infrastructure incentives:Tax credits for domestic telecommunications manufacturing indirectly subsidize edge server deployments hosting virtualized customer premises functions.
Industry Challenges
- NFV systems engineering scarcity:Carriers struggle to recruit engineers fluent in both telco-grade reliability requirements and cloud-native Kubernetes operations.
- ETSI MANO certification delays:Vendor platforms face extended validation cycles against evolving NFV management and orchestration standards, compressing product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual CPE (Vcpe) Market |
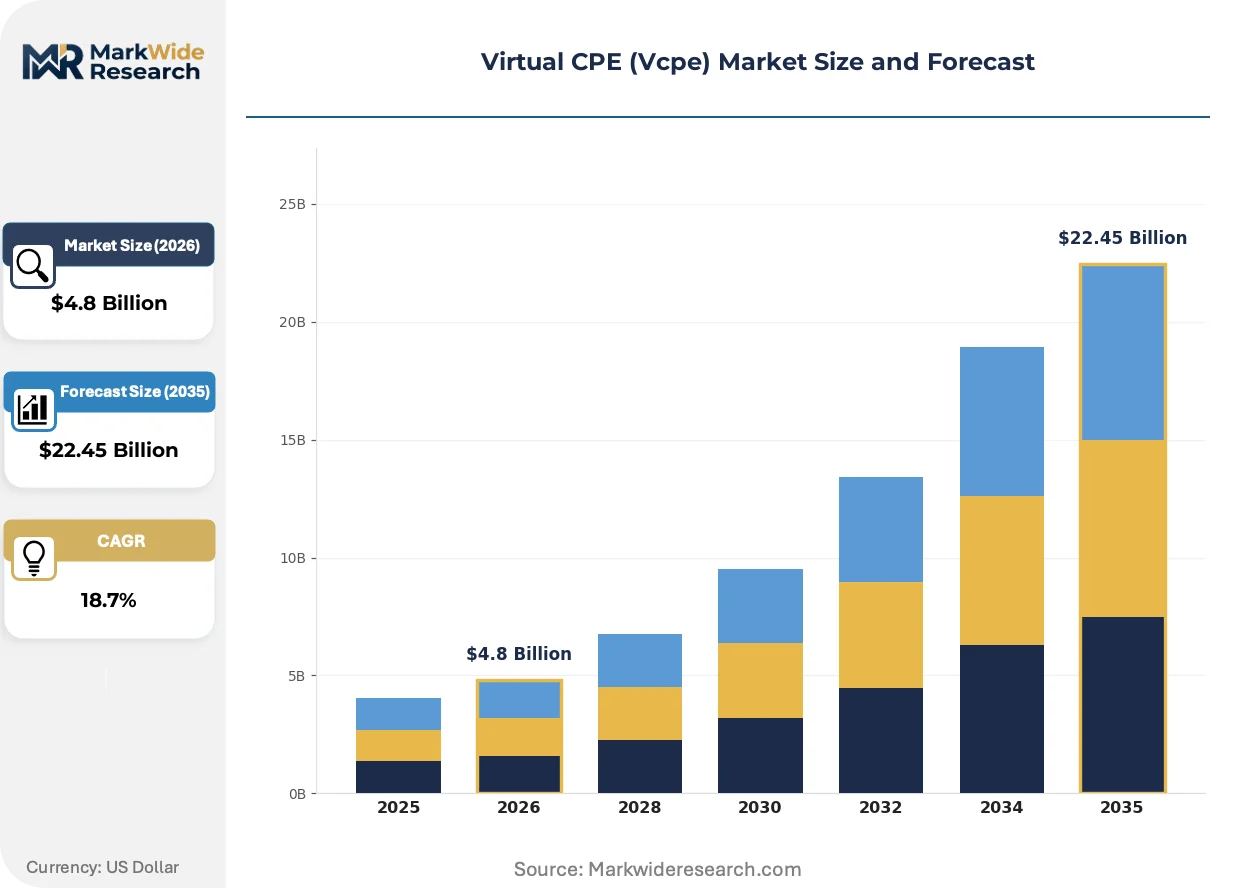
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Telecom Operators, Enterprises, Service Providers, Government Agencies Service Type: Firewall, Load Balancer, Router, Switch Technology: SDN, NFV, Virtualization, Orchestration |
| Companies Covered | Cisco Systems, Hewlett Packard Enterprise, Juniper Networks, NEC Corporation, Ericsson, Dell, Versa Networks, VMware, Arista Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual CPE (Vcpe) Market Trends and Innovations
Containerization is overtaking virtual machines as the dominant VNF packaging format, compressing deployment footprints while complicating carrier operational workflows trained on hypervisor-centric management tools.
Cloud-native network functions packaged as microservices are rewriting how carriers provision edge routing. Tier-one US operators deploy Kubernetes-orchestrated VNFs at hundreds of central office locations. This architecture collapses the distinction between network function and application workload, forcing legacy operations teams into DevOps skill acquisition.
The FCC's cybersecurity labeling program for communications infrastructure intersects with NIST cloud security frameworks to impose mandatory software supply chain attestation. Equipment vendors must now document third-party component provenance. European operators under GDPR face parallel pressure from national data protection authorities to map virtualized function data flows.
Enterprise procurement of network edge infrastructure now separates hardware acquisition from software licensing, with CIOs negotiating multi-year VNF subscriptions independent of server refresh cycles. Systems integrators and managed service providers capture margin previously retained by box vendors. This unbundling is most advanced among US financial services firms with centralized IT governance over distributed branch footprints.
Virtual CPE (Vcpe) Market Segmentation
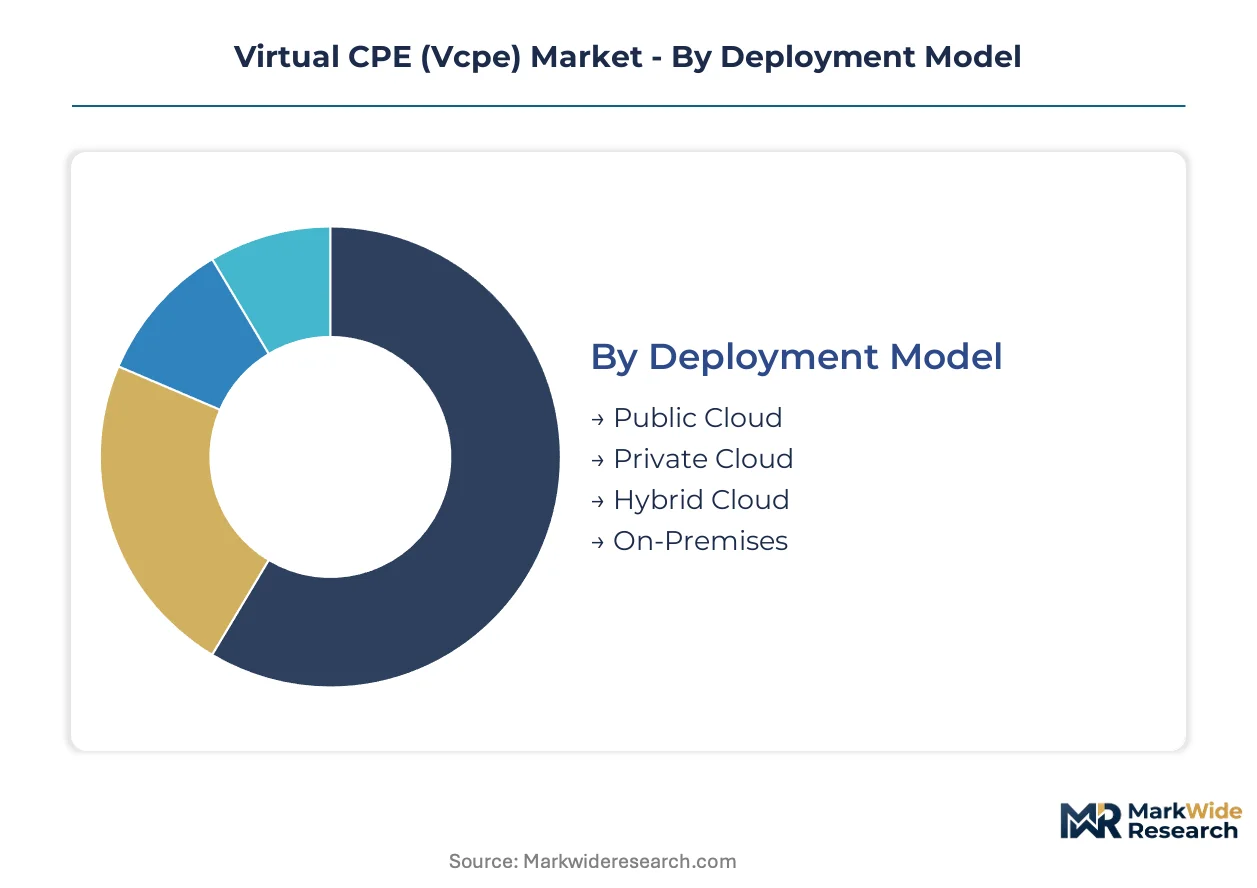
Virtual CPE market segmentation reveals how deployment architecture, customer procurement patterns, and technology packaging determine competitive positioning. Each axis carries distinct margin profiles and vendor qualification requirements that reshape go-to-market strategies.
Deployment Model:
Technology packaging dictates infrastructure ownership boundaries and operational control distribution across carrier and enterprise environments.
- Public Cloud:Carrier-hosted VNF instances run on hyperscaler infrastructure, eliminating capital expenditure for branch hardware refresh cycles. US financial services firms with centralized IT governance favor this model for rapid branch provisioning without truck-roll dependencies.
- Hybrid Cloud:Control planes anchor on-premises while burst capacity overflows to public infrastructure, blending deterministic latency with elastic scale. German and Japanese carriers drive procurement pull here due to data sovereignty requirements that mandate local execution for sensitive traffic.
- Private Cloud:Dedicated virtualized infrastructure delivers carrier-grade reliability isolation for regulated verticals. Government agencies and defense contractors specify private deployments to satisfy NIST 800-53 controls and comparable national security frameworks.
- On-Premises:Traditional server-based VNF hosting persists in markets with limited fiber backhaul or strict air-gapping mandates. Rural broadband initiatives in distributed geographies rely on this model where cloud connectivity remains intermittent.
Hybrid Cloud leads on scale; Public Cloud leads on momentum.
End User:
Customer procurement sophistication spans from centralized carrier sourcing to fragmented enterprise branch decision-making.
- Telecom Operators:Tier-one service providers deploy cloud-native edge infrastructure at hundreds of central office locations, collapsing network function and application workload distinctions. ETSI NFV-compliant orchestration layers are now mandatory in US carrier RFPs, compressing vendor qualification cycles.
- Enterprises:Distributed branch footprints drive demand for zero-touch provisioning and centralized policy management. Manufacturing and retail verticals prioritize WAN optimization virtualization to consolidate MPLS substitution timelines.
- Service Providers:Managed service offerings bundle VNF orchestration with SLA-backed network management, capturing margin previously retained by hardware vendors. Systems integrators intermediate multi-vendor integration complexity for mid-market clients lacking internal NFV engineering depth.
- Government Agencies:Procurement prioritizes FIPS 140-2 validated cryptographic modules and supply chain attestation documentation. The FCC's cybersecurity labeling program imposes mandatory software provenance mapping that extends vendor compliance obligations.
Telecom Operators anchor volume concentration; Enterprises are expanding most quickly.
Service Type:
Function virtualization maturity varies by protocol complexity and operational criticality in enterprise edge stacks.
- Router:Virtualized routing functions mature fastest due to standardized control plane protocols and extensive carrier operational experience. Cisco Systems and Juniper Networks compete through heritage protocol implementations ported to containerized form factors.
- Firewall:Security virtualization captures strong enterprise pull as perimeter dissolution demands distributed policy enforcement. GDPR data flow mapping requirements in Europe accelerate replacement of hardware appliances with software-defined security functions.
- Switch:Layer 2 virtualization trails routing adoption due to ASIC dependency for line-rate forwarding. Data center interconnect scenarios drive initial deployment before branch edge penetration accelerates.
- Load Balancer:Application delivery controller virtualization faces longest substitution timelines given specialized hardware acceleration for SSL/TLS termination. Cloud-native microservices architectures eventually displace traditional appliance form factors.
Router leads on scale; Firewall gains share fastest.
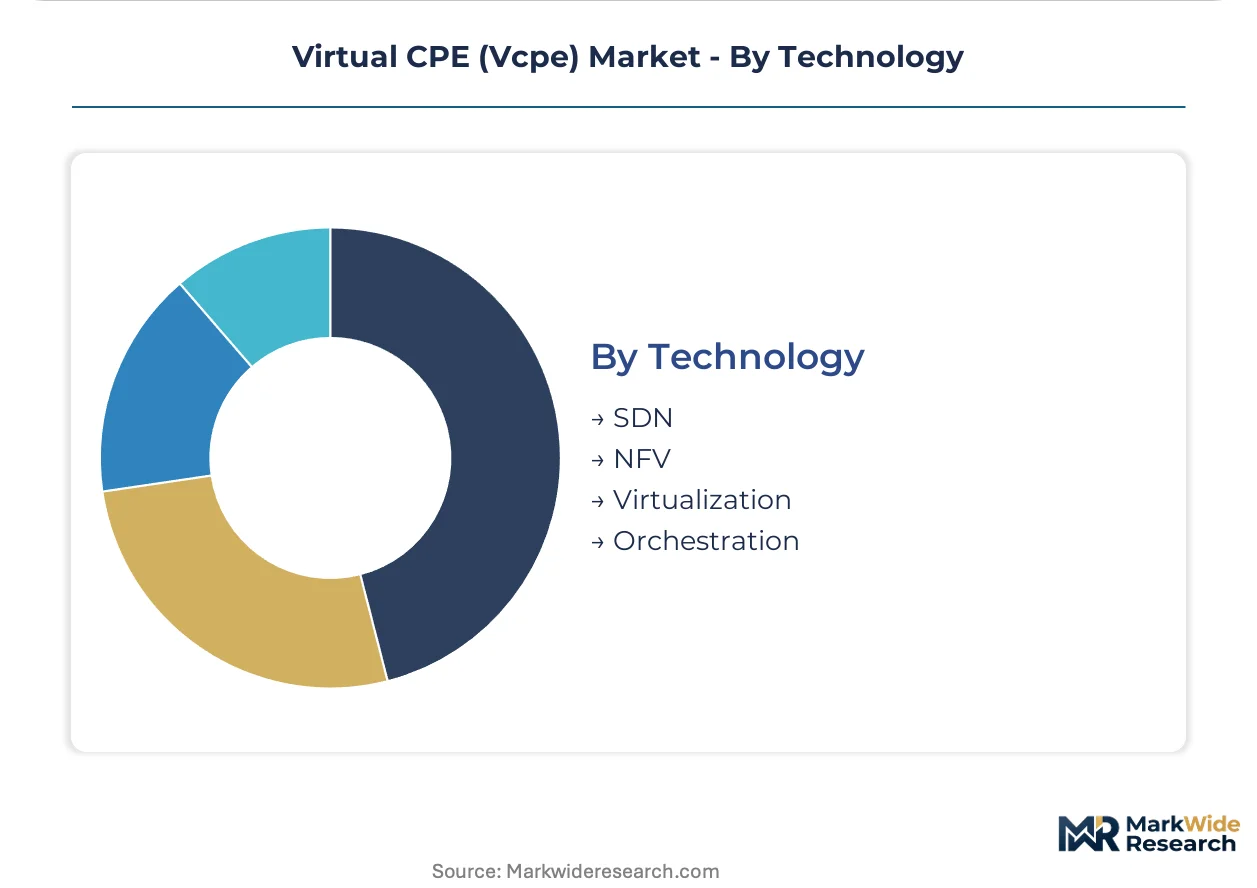
Technology:
Architecture layers determine where margin pools concentrate and vendor differentiation persists.
- NFV:ETSI standards-compliant infrastructure decouples network functions from proprietary hardware, enabling multi-vendor procurement. Carrier cloud certification programs validate VNF interoperability against evolving management and orchestration specifications.
- Orchestration:Integration complexity and multi-vendor mediation requirements concentrate value capture here. VMware extends data center virtualization dominance through Telco Cloud platform positioning as neutral substrate for third-party workloads.
- SDN:Centralized control plane abstraction enables policy-driven traffic engineering across distributed VNF instances. Kubernetes-orchestrated deployments at US central offices demonstrate production maturity.
- Virtualization:Foundational hypervisor and container runtime layers commoditize as open-source alternatives mature. Containerization overtakes virtual machines as dominant packaging format, compressing deployment footprints while complicating carrier operational workflows.
Orchestration commands premium pricing; NFV provides the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of cloud-native infrastructure vendors anchors vCPE innovation pipelines, with carrier certification programs in Germany and Japan establishing procurement benchmarks that diffuse through multinational operator groups.
United States
Tier-one operators including Verizon and AT&T drive cloud-native edge deployments across hundreds of central office locations, mandating ETSI NFV-compliant orchestration in procurement specifications. FCC cybersecurity labeling requirements impose software supply chain attestation obligations on equipment vendors. The Dallas-Fort Worth metroplex hosts concentrated carrier cloud infrastructure buildouts where Kubernetes-orchestrated VNFs achieve production scale.
Germany
Deutsche Telekom and regional carriers blend on-premises control planes with public cloud burst capacity to satisfy data localization imperatives. GDPR enforcement by national data protection authorities mandates geo-fenced virtualized function execution for sensitive traffic. The Munich-Stuttgart corridor concentrates vendor engineering centers where ETSI MANO certification testing accelerates product validation cycles.
Japan
NTT and KDDI pursue hybrid edge architectures that anchor deterministic latency functions locally while scaling compute-intensive workloads to cloud infrastructure. METI industrial policy frameworks incentivize domestic virtualization platform development alongside international standards alignment. Tokyo-Osaka metropolitan clusters demonstrate mature network slicing integration with vCPE for enterprise IoT service tiers.
India
BharatNet rural broadband expansion creates demand for low-cost virtualized CPE serving distributed village clusters without truck-roll maintenance dependencies. TRAI regulatory frameworks promote open network interface standards that reduce vendor lock-in for government-funded infrastructure. Bangalore-based systems integrators develop localized orchestration platforms addressing intermittent connectivity constraints in tier-2 and tier-3 markets.
United Kingdom
BT and Virgin Media O2 accelerate MPLS substitution timelines through managed SD-WAN services built on virtualized edge stacks. National Cyber Security Centre guidelines intersect with GDPR data flow mapping requirements to shape security function virtualization procurement. London's financial services concentration drives zero-touch provisioning demand among institutions with centralized IT governance over global branch footprints.
Virtual CPE (Vcpe) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native orchestration specialization. The vendor landscape stratifies across heritage networking equipment suppliers, hyperscaler-aligned virtualization platforms, and pure-play SD-WAN specialists. Three archetypes dominate: routing heritage vendors porting protocol stacks to containerized form factors; data center virtualization incumbents extending telco edge presence; and born-cloud challengers betting on Kubernetes-native architectures. Competitive dynamics center on carrier certification velocity and multi-vendor orchestration interoperability rather than proprietary hardware performance metrics.
Within the heritage networking tier, Cisco Systems and Juniper Networks exemplify protocol implementation advantages translated to virtualized deployments. VMware occupies a distinct position as data center virtualization incumbents extending neutral substrate positioning into telco edge infrastructure. Among pure-play challengers, Versa Networks represents cloud-native architectural bets decoupled from legacy hardware revenue dependencies. Each archetype faces distinct certification cycle pressures under evolving ETSI MANO specifications.
| Leading Market Players |
|---|
| Cisco Systems |
| Hewlett Packard Enterprise |
| Juniper Networks |
| NEC Corporation |
| Ericsson |
| Dell |
| Versa Networks |
| VMware |
| Arista Networks |
| Others |
Pricing and Supply Chain Analysis
Carrier-grade certification tiers bifurcate vCPE procurement into ETSI MANO-validated premium stacks and commodity orchestration layers, with that divergence manifesting in both subscription pricing spreads and silicon sourcing strategies that anchor premium tiers to Intel and AMD server chipsets while economy tiers explore ARM alternatives.
Pricing Analysis
Input-cost pass-through from x86 server chipsets and memory modules shapes vendor pricing, with three-tier pricing structure across premium, standard, and economy levels differentiating by ETSI certification depth and carrier cloud validation status. Price differentiation rests on orchestration interoperability guarantees and geographic deployment support tiers. Pricing pressure stems from hyperscaler-backed challengers subsidizing orchestration software to capture infrastructure attach. Enterprise branch buyers exhibit highest price sensitivity, while tier-one telecom operators prioritize certification velocity over unit cost.
Supply Chain Analysis
ETSI NFV and NIST cloud security certification gating restricts qualified component suppliers to a narrow tier of validated foundries and firmware providers. Geographic supply concentrates in Taiwan for advanced server silicon, the United States for orchestration software development, and Germany for precision manufacturing of edge server enclosures. Raw material dependencies span DDR5 memory modules, high-bandwidth networking ASICs, and carrier-grade power supply units. Single-source vulnerability in x86 server chipset fabrication exposes deployment timelines to foundry capacity allocation decisions. Distribution runs through direct carrier procurement channels and systems integrator intermediaries for mid-market enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
vCPE functions as a stable compounder anchored by irreversible carrier infrastructure virtualization mandates that guarantee replacement demand regardless of macroeconomic cyclicality.
For Market Incumbents: Anchor market position through accelerated ETSI MANO certification velocity that compresses challenger qualification windows, while deepening backward integration into Kubernetes-native orchestration stacks to neutralize born-cloud entrants. Carrier cloud certification mandates in the United States and Germany create defensive moats for validated incumbents. Priority investment in multi-vendor mediation capabilities preserves margin concentration in integration layers. For New Entrants and Emerging Players: FCC cybersecurity labeling requirements in the United States open a window for specialized compliance automation tools that reduce vendor attestation burdens. India's BharatNet rural broadband expansion presents the most penetrable geography, with intermittent connectivity constraints favoring lightweight containerized orchestration over legacy VM-based stacks. Go-to-market through Bangalore-based systems integrators addresses localization requirements without direct carrier certification delays. For Investors and Strategic Acquirers: Consolidation pressure builds where orchestration layer fragmentation exceeds enterprise procurement patience for multi-vendor integration complexity. Long-term viability favors platforms with carrier cloud certification breadth across three or more tier-one operators. Acquisition target archetype: Kubernetes-native orchestration specialists with existing ETSI validation and embedded deployments at European carriers. Signal to watch: carrier RFP language shifting from "NFV-compliant" to "cloud-native only" as inflection indicator for architectural obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| ETSI MANO Certification Acceleration | Compresses vendor qualification cycles at Deutsche Telekom and Verizon procurement gates. |
| Carrier Cloud Platform Integration | Positions VMware Telco Cloud as neutral substrate for multi-vendor VNF workloads. |
| Kubernetes-Native Orchestration Development | Aligns product architecture with tier-one US operator central office deployment patterns. |
| Geographic Expansion into India | Captures BharatNet rural broadband demand for low-touch virtualized CPE provisioning. |
| Strategic Partnership with Systems Integrators | Addresses mid-market enterprise NFV engineering scarcity through managed service bundling. |
Research Methodology
Direct dialogue with carrier network architects, NFV systems engineers, enterprise IT procurement officers, and systems integrator practice leads grounded qualitative findings, cross-referenced against ETSI standardization documents, FCC cybersecurity labeling program filings, carrier cloud certification program specifications, and hyperscaler edge infrastructure capex disclosures. Bottom-up deployment sizing at tier-one operators triangulated against top-down market aggregation from vendor revenue disclosures.
Segment-level value outputs across deployment models, end-user categories, service types, and technology layers were calibrated against carrier procurement pipeline visibility and enterprise branch refresh cycle patterns. CAGRs were derived from installed base substitution trajectories and greenfield edge infrastructure buildout schedules. Industry-specific forecast inputs included ETSI NFV release timeline adherence and national data sovereignty enforcement intensity across European and Asia-Pacific markets.
Revisions become necessary when carrier certification program requirements materially expand, hyperscaler edge platform offerings directly substitute for independent vCPE stacks, or silicon supply concentration triggers procurement preference shifts toward ARM-based server alternatives. A model refresh is warranted upon material change in ETSI MANO specification adoption velocity among tier-one operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Fixed Voice Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
GPON Equipment Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Cambodia Telecom Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
A2P Messaging Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Singapore Telecom Market
Telecommunications
Romania Telecom Market
Telecommunications
Transport Stream Switching Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Malaysia Telecom Market