
 Egypt ICT Market | 2026-2036
Egypt ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt ICT Market Analysis
Egypt's nationwide fiber-optic backbone expansion is fragmenting service delivery models across the Nile Delta and Upper Egypt. Prime Softworks leverages its Cairo-based development centers to anchor enterprise software contracts with public sector clients. FlairsTech competes through specialized fintech solutions, while NOOR Data Network controls terrestrial connectivity infrastructure linking Alexandria to Aswan.
Information and communications technology in Egypt encompasses software systems, hardware devices, network equipment, and IT services delivered through on-premises, cloud, hybrid, and managed deployment models. The technology stack integrates artificial intelligence, Internet of Things architectures, big data analytics, and blockchain protocols to enable real-time data processing and secure transactions across government, education, healthcare, and retail end users. IT Services currently dominates margin pools due to recurring maintenance contracts and cloud migration consulting, while AI and IoT represent the fastest-expanding technology segments as Egyptian enterprises modernize operational workflows. Software and cloud deployment models are gaining share against legacy hardware installations as subscription economics displace capital expenditure cycles.
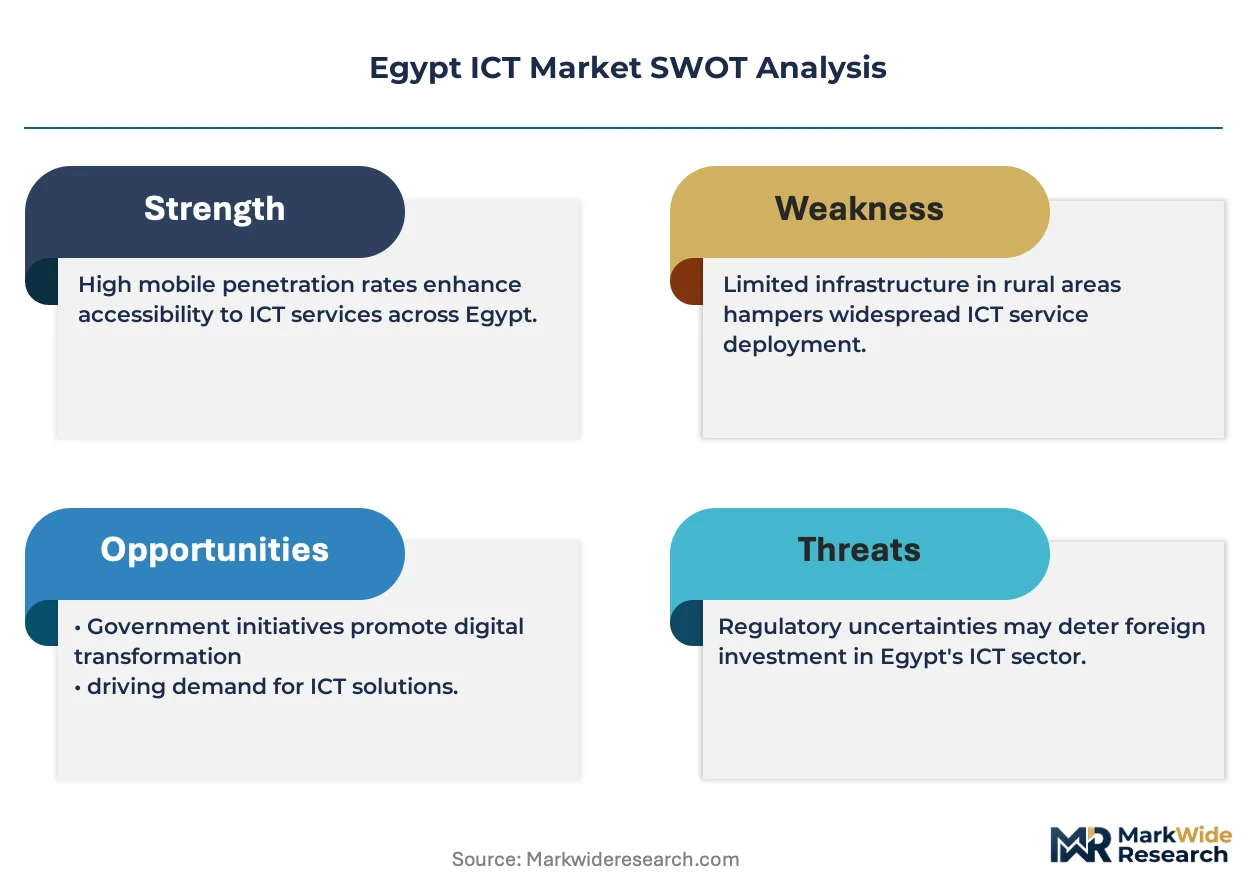
Egypt's Ministry of Communications and Information Technology, the National Telecommunications Regulatory Authority, and the Egyptian Computer Emergency Readiness Team shape market access through spectrum allocation, data localization requirements, and cybersecurity compliance mandates. The country's national regulator enforces licensing frameworks that condition foreign vendor participation on local partnership structures and workforce development commitments. Stakeholders must monitor evolving data sovereignty rules and cloud certification standards to align procurement strategies with enforcement timelines.
Market Dynamics
Egypt's fiber-optic backbone expansion is fragmenting service delivery models across the Nile Delta and Upper Egypt, forcing infrastructure providers to reconfigure territorial coverage strategies and pricing architectures.
Growth Catalysts
- Digital Egypt Strategy:The national digital transformation framework mandates cloud migration across government agencies, generating sustained demand for enterprise software and managed services procurement.
- Terrestrial connectivity infrastructure:NOOR Data Network's Alexandria-to-Aswan fiber corridor is collapsing transmission costs for data centers and financial services hubs.
- Artificial intelligence adoption:Egyptian enterprises are modernizing operational workflows through AI-enabled automation, with healthcare and retail sectors leading implementation.
Market Restraints
- Data localization mandates:Egypt's national regulator enforces strict data sovereignty requirements that condition foreign vendor participation on local partnership structures, raising compliance overhead for international cloud providers.
- Workforce development gaps:The shortage of certified cybersecurity professionals limits enterprise scaling of cloud and IoT deployments.
- Spectrum allocation bottlenecks:National Telecommunications Regulatory Authority licensing timelines delay 5G infrastructure rollout in secondary cities.
Strategic Opportunities
- Upper Egypt penetration:Fiber-optic backbone gaps in Sohag, Qena, and Aswan governorates create first-mover advantages for infrastructure-as-a-service providers.
- Fintech specialization:Central Bank of Egypt digital payment regulations are accelerating demand for blockchain-enabled transaction platforms.
- AI-IoT convergence:Smart agriculture applications in the Nile Delta combine predictive analytics with sensor networks, opening vertical-specific solution markets.
Industry Challenges
- Legacy system integration:Government agencies maintain decades-old mainframe architectures that resist API-based connectivity with modern cloud platforms.
- Cybersecurity certification timelines:Egyptian Computer Emergency Readiness Team compliance reviews extend vendor onboarding cycles by six to twelve months.
- Cloud certification standards:Evolving sovereign cloud requirements force repeated architecture redesigns for multi-tenant service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt ICT Market |
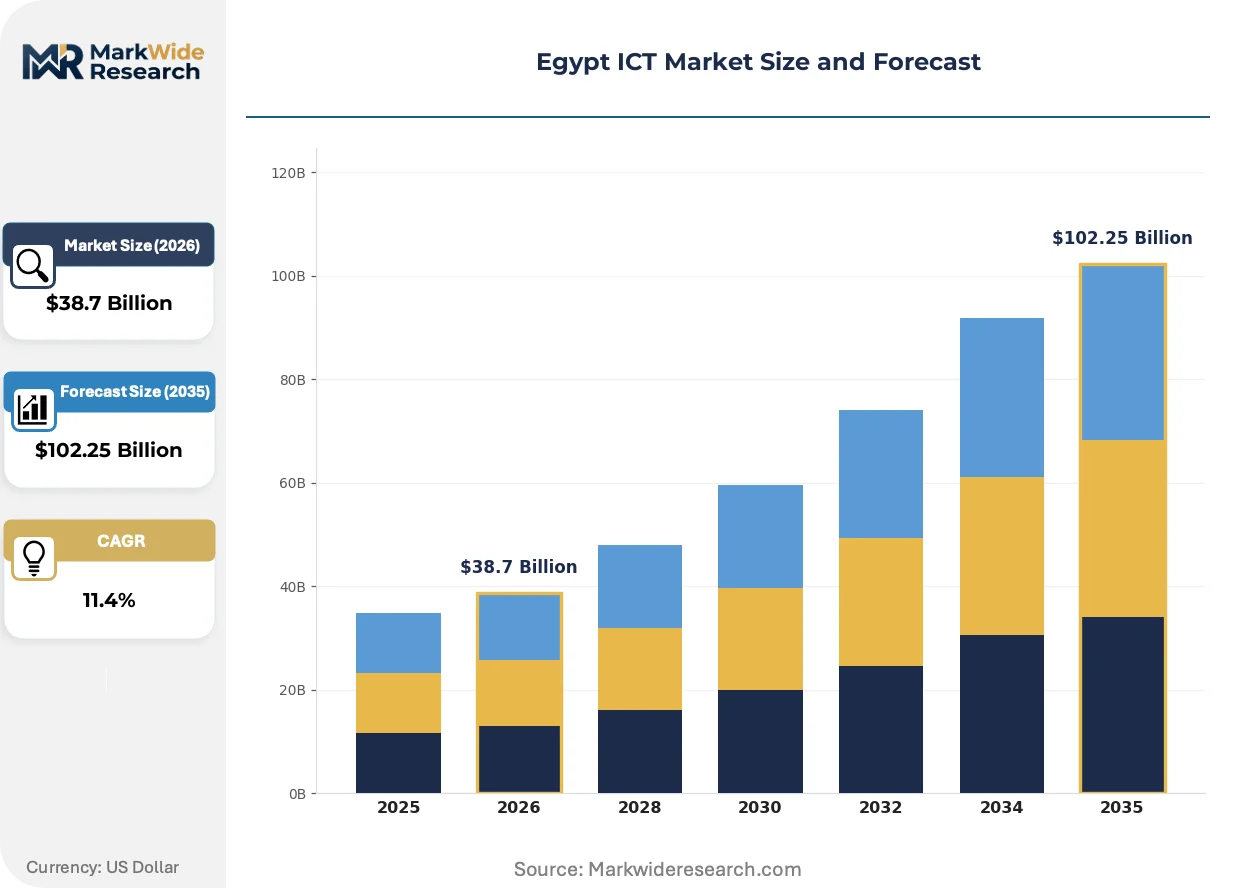
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Network Equipment, IT Services End User: Government, Education, Healthcare, Retail Deployment Model: On-premises, Cloud, Hybrid, Managed Services Technology: AI, IoT, Big Data, Blockchain |
| Companies Covered | Prime Softworks, Cupid Solutions, FlairsTech, NOOR Data Network, Inovasys, Intcore, Dot IT, Digital Planets, Mobirevo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt ICT Market Emerging Trajectories
Subscription economics are displacing capital expenditure cycles across Egyptian enterprises, compressing hardware procurement timelines while expanding recurring revenue pools for software and services vendors.
Hybrid cloud architectures are collapsing the distinction between on-premises and public infrastructure for Egyptian financial institutions. Banks in Cairo's technology corridor are adopting containerized workloads that shift seamlessly between private data centers and sovereign cloud zones. This operational flexibility is collapsing traditional procurement categories that separated hardware, software, and services into discrete budget lines.
Egypt's data localization requirements are reshaping vendor market access conditions. The Ministry of Communications and Information Technology mandates that sensitive government data reside within national borders, compelling international cloud providers to establish Cairo-based facilities. Public sector agencies are responding by prioritizing vendors with certified local infrastructure over global platforms without sovereign presence.
Enterprise buyers are consolidating vendor relationships to reduce integration complexity. Large Egyptian manufacturers and healthcare networks are replacing point solutions with unified platforms spanning ERP, CRM, and analytics functions. This preference consolidation is most visible among Suez Canal Economic Zone enterprises seeking single-accountability contracts for digital transformation programs.
Egypt ICT Market Segmentation
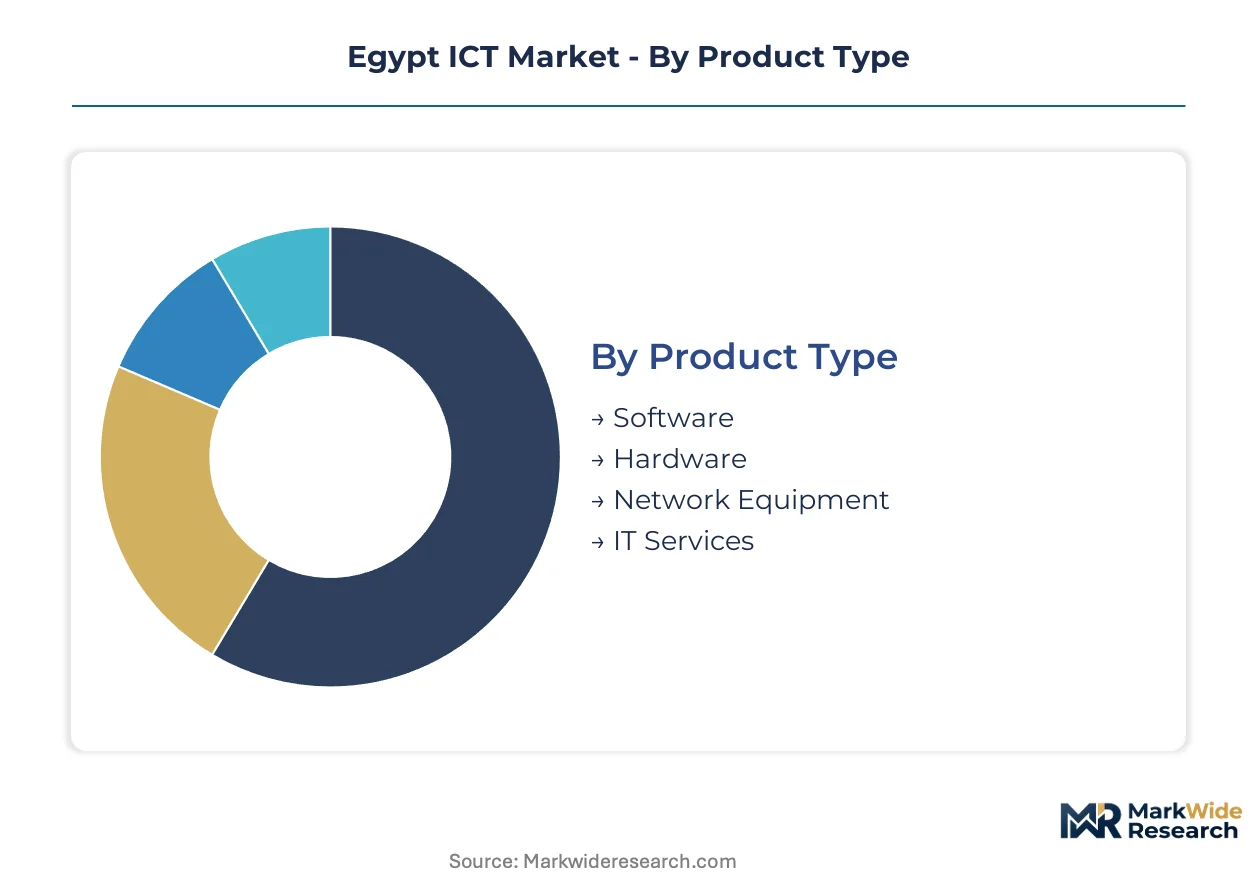
Egypt's ICT market segmentation reveals distinct procurement patterns across public and private sectors. Government digital transformation mandates reshape demand concentration within each category, while Cairo's technology corridor anchors deployment decisions for enterprise buyers.
Product Type:
Mature hardware installations coexist with emerging software-as-a-service models across Egyptian enterprises, creating tiered investment cycles.
- Software:Enterprise applications span ERP, CRM, and analytics platforms with modular architectures. Government agencies in Cairo and Alexandria drive procurement volume through Digital Egypt Strategy mandates.
- Hardware:Servers, storage arrays, and endpoint devices constitute capital-intensive procurement categories. Manufacturing facilities in the Suez Canal Economic Zone sustain demand for industrial-grade computing infrastructure.
- Network Equipment:Routers, switches, and wireless access points enabling fiber-optic backbone expansion.
- IT Services:System integration, maintenance, and consulting contracts generating recurring revenue streams.
IT Services handles the majority of throughput; Software is the fastest mover on share.
End User:
Public sector procurement volume contrasts with private sector specialization requirements across Egyptian verticals.
- Government:National ministries and governorates deploying citizen service platforms with strict data localization compliance. The Ministry of Communications and Information Technology mandates sovereign cloud migration timelines.
- Healthcare:Hospital networks and diagnostic chains adopting electronic medical records and telemedicine infrastructure. Cairo-based private hospital groups lead EMR implementation spending.
- Education:Universities and technical institutes modernizing campus networks and learning management systems.
- Retail:E-commerce platforms and point-of-sale networks requiring real-time inventory analytics.
Government absorbs the largest procurement budget; Healthcare is expanding most quickly on investment intensity.
Deployment Model:
Cost tier differentiation separates capital expenditure models from operational expenditure alternatives across Egyptian buyer segments.
- Cloud:Public and sovereign cloud instances delivering scalable compute without facility ownership. Financial institutions in Cairo's technology corridor prioritize certified local cloud zones.
- Hybrid:Containerized workloads shifting between private data centers and public infrastructure. Large manufacturers seeking operational flexibility anchor this segment's growth.
- On-premises:Legacy data center installations with full physical control over hardware stacks.
- Managed Services:Outsourced infrastructure operations with guaranteed service level agreements.
On-premises retains the largest installed base; Hybrid is climbing the fastest on new contract volume.
Technology:
Application-specific value creation distinguishes mature analytics from emerging protocol layers in Egyptian enterprise adoption.
- AI:Machine learning models automating operational workflows in predictive maintenance and customer service. Healthcare providers in Cairo deploy diagnostic imaging algorithms.
- IoT:Sensor networks monitoring agricultural conditions and industrial equipment performance. Nile Delta smart agriculture projects combine moisture sensors with automated irrigation controls.
- Big Data:Distributed processing architectures handling high-velocity transaction and telemetry streams.
- Blockchain:Distributed ledger protocols enabling transparent transaction records for financial services.
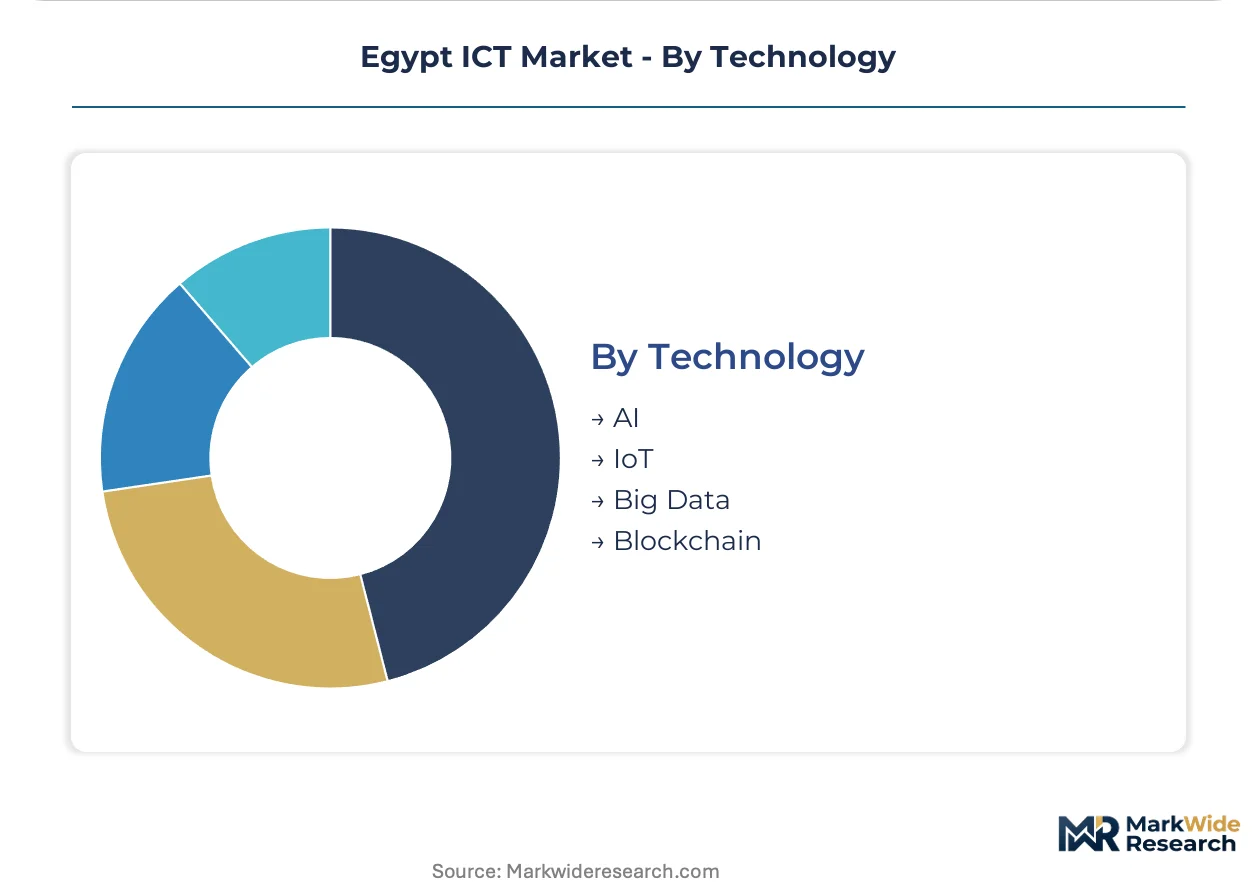
Big Data underpins the widest deployment footprint; IoT is gaining share fastest on greenfield project volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ICT infrastructure investment clusters along Egypt's Nile corridor, with Cairo's technology corridor anchoring procurement volume and Alexandria-to-Aswan fiber routes reshaping territorial coverage economics.
Greater Cairo and the Nile Delta
Enterprise software procurement concentrates in Cairo's technology corridor, where government agencies execute Digital Egypt Strategy mandates. The Ministry of Communications and Information Technology enforces sovereign cloud certification timelines for vendors serving public sector clients. Smart agriculture deployments in the Delta combine IoT sensor networks with automated irrigation systems.
Alexandria and the Mediterranean Coast
Financial services hubs along the northern coast drive demand for low-latency connectivity and hybrid cloud architectures. The National Telecommunications Regulatory Authority licenses spectrum for 5G infrastructure rollout in secondary cities. NOOR Data Network's fiber corridor terminates here, collapsing transmission costs for data center operators.
Upper Egypt Governorates
Sohag, Qena, and Aswan present infrastructure-as-a-service opportunities where fiber-optic backbone gaps persist. The Egyptian Computer Emergency Readiness Team extends cybersecurity compliance requirements to emerging digital service zones. First-mover providers are establishing edge computing nodes to serve agricultural and logistics enterprises.
Suez Canal Economic Zone
Manufacturing facilities sustain demand for industrial-grade computing infrastructure and unified ERP platforms. Data localization requirements condition foreign vendor participation on Cairo-based partnership structures. Zone enterprises prioritize single-accountability contracts spanning digital transformation programs.
Sinai Peninsula
Logistics and border security applications generate specialized demand for ruggedized network equipment and satellite backup connectivity. National regulator licensing frameworks govern cross-border data flows with neighboring territories. Limited terrestrial infrastructure creates opportunities for wireless and satellite service providers.
Egypt ICT Market Vendor Landscape
Full-stack systems integrators and specialized infrastructure operators split the market between comprehensive service contracts and targeted connectivity plays. Market concentration remains moderate, with tiered competition separating established Cairo-based vendors from emerging specialists. Two dominant archetypes prevail: development-centric software houses anchoring public sector relationships, and network-focused operators controlling terrestrial fiber assets. Competitive dynamics center on strategic partnerships with international cloud providers and workforce development commitments satisfying regulatory conditions.
Among development-centric specialists, Prime Softworks exemplifies the Cairo-based software house archetype securing enterprise contracts through localized delivery capabilities. FlairsTech occupies a position within the fintech specialization tier, while NOOR Data Network represents infrastructure operators controlling Alexandria-to-Aswan terrestrial connectivity. These three anchors illustrate how geographic concentration and regulatory compliance requirements structure competitive positioning across Egypt's ICT ecosystem.
| Leading Market Players |
|---|
| Prime Softworks |
| Cupid Solutions |
| FlairsTech |
| NOOR Data Network |
| Inovasys |
| Intcore |
| Dot IT |
| Digital Planets |
| Mobirevo |
| Others |
Supply Flow & Price Mechanics
Alexandria-to-Aswan fiber corridor freight economics compress transmission cost differentials between Cairo-based data centers and Upper Egypt edge nodes, concentrating vendor pricing power among terrestrial infrastructure operators while fragmenting procurement budgets across sovereign cloud certification tiers.
Pricing Analysis
Egypt's data localization mandates dictate the pricing tier structure across deployment models. Three-tier pricing separates sovereign-certified infrastructure from hybrid architectures and standard public cloud instances. Certification grade and local partnership depth drive price differentiation, with foreign vendors absorbing compliance overhead through Cairo facility investments. Cost compression in standard cloud tiers is intensifying because Egyptian enterprises consolidate vendor relationships. Government agencies exhibit lowest price sensitivity due to mandated procurement timelines, while mid-market manufacturers in the Suez Canal Economic Zone negotiate aggressively on per-seat SaaS economics.
Supply Chain Analysis
Contract manufacturing for Egyptian ICT hardware concentrates in China, Taiwan, and Vietnam, with server assembly and network equipment production anchored in Shenzhen and Taipei facilities. Component sourcing draws from Malaysian semiconductor packaging plants and South Korean memory foundries. Single-source vulnerability persists in specialized routing chipsets subject to export licensing reviews. Distribution runs through Dubai-based regional logistics hubs with last-mile delivery via Cairo technology corridor warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's ICT market rewards vendors who control certified talent pipelines, as workforce development gaps constrain enterprise scaling faster than infrastructure buildouts can compensate.
For Market Incumbents: Harden sovereign cloud certification moats by deepening Cairo-based data center capacity ahead of regulatory deadline acceleration. Acquire specialized cybersecurity training capabilities to offset workforce scarcity threatening managed services margin pools. Counter emerging fintech specialists through API platform consolidation that collapses point-solution procurement categories. For New Entrants and Emerging Players: Upper Egypt governorates with persistent fiber-optic backbone gaps represent the most penetrable entry point for infrastructure-as-a-service providers. Smart agriculture sensor networks in the Nile Delta offer vertical-specific solution markets with limited incumbent saturation. Partner with Alexandria-based system integrators to bypass Cairo technology corridor relationship barriers. For Investors and Strategic Acquirers: Egyptian Computer Emergency Readiness Team compliance timeline extensions reshape the acquisition landscape toward vendors with pre-certified security architectures. Long-term viability hinges on regulatory relationship depth rather than technology differentiation alone. Monitor National Telecommunications Regulatory Authority spectrum allocation announcements as inflection signals for 5G infrastructure valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | Ministry of Communications and Information Technology mandates condition vendor market access on Cairo facility presence. |
| Workforce Development Partnership | Egyptian Computer Emergency Readiness Team certification gaps limit scaling; captive training pipelines secure recurring services contracts. |
| Vertical Fintech Platform | Central Bank of Egypt digital payment regulations accelerate blockchain-enabled transaction infrastructure procurement. |
| Upper Egypt Edge Expansion | Sohag and Qena fiber gaps create first-mover infrastructure-as-a-service opportunities for agricultural and logistics enterprises. |
| Hybrid Cloud Integration | Containerized workload portability between private data centers and sovereign zones collapses traditional procurement silos. |
Methodological Framework
A spread of perspectives from enterprise software procurement officers, telecommunications infrastructure planners, system integration specialists, and regulatory compliance directors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against National Telecommunications Regulatory Authority licensing databases, Ministry of Communications and Information Technology policy circulars, hyperscaler capex disclosures, and enterprise IT spending surveys. Bottom-up contract aggregation and top-down macroeconomic alignment anchored the triangulation framework.
Demand-supply balance dynamics across software, hardware, network equipment, and services categories informed the analytical framework over the projection horizon. Segmentation dimensions modeled include deployment model complexity, organization size tier, vertical industry, technology protocol layer, and regional adoption pattern. CAGRs derived from installed base evolution and replacement cycle acceleration. Forecast inputs incorporated sovereign cloud certification timelines and fiber-optic backbone expansion schedules.
Practitioners should monitor regulatory enforcement cadence and spectrum allocation announcements for early signals of forecast revision. Forecasts reflect assumptions about Digital Egypt Strategy implementation pacing and data localization compliance adherence. Quarterly review of Ministry procurement award disclosures and cybersecurity certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Poland Telecom Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
5G Equipment Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Austria Telecom Market
Telecommunications
Singapore Telecom Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Vietnam ICT Market
Telecommunications
Cambodia ICT Market
Telecommunications
IP PBX Market
Telecommunications
Tetra Terminals Market
Telecommunications
Utility Communications Market