
 Spain ICT Market | 2026-2036
Spain ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Spain ICT Market Analytics
A chronic shortage of cloud-certified systems engineers is unwinding project timelines across Spanish enterprise deployments. Indra Sistemas, SA dominates public-sector digital transformation contracts through its deep relationships with Madrid and regional governments. Amadeus IT Group, SA anchors travel technology infrastructure, leveraging proprietary reservation platforms that sustain pricing power across airline and hospitality clients. Izertis SA specializes in agile software delivery, competing for mid-market modernization programs where speed-to-deployment differentiates vendor selection.
Information and communications technology in Spain spans hardware infrastructure, software platforms, telecommunications networks, and associated services operating at data transmission speeds exceeding 100 Gbps in backbone fiber deployments. Its primary commercial purpose centers on enabling enterprise workflow automation, consumer digital service delivery, and government administrative modernization. Cloud Computing leads technology investment as enterprises migrate legacy workloads, while Cybersecurity commands premium margins following NIS2 transposition into Spanish law. Smart Cities application spending concentrates in Barcelona and Madrid, where municipal IoT sensor networks and traffic management platforms absorb substantial public IT budgets.
Spain's national AI strategy and the EU AI Act impose algorithmic transparency requirements on vendors serving financial and healthcare clients. BIS-equivalent standards for data center energy efficiency, alongside GDPR enforcement by the Spanish Data Protection Agency, constrain facility location and design choices. Stakeholders must monitor how Madrid's regional government procurement rules and EU chip sovereignty initiatives reshape domestic semiconductor access and server hardware supply chains.
Market Dynamics
Spanish banks and insurance groups are accelerating digital infrastructure procurement under pressure from the EU AI Act's algorithmic transparency mandates, while chronic shortages of cloud-certified systems engineers unwind project timelines across enterprise deployments.
Growth Catalysts
- EU AI Act compliance:Financial and healthcare clients in Spain face mandatory algorithmic transparency requirements, forcing procurement of explainable AI infrastructure and audit-ready software platforms.
- Smart city deployments:Barcelona and Madrid municipal governments are absorbing substantial public IT budgets through IoT sensor networks and intelligent traffic management platforms.
- NIS2 transposition:Spanish cybersecurity providers command premium margins as enterprises scramble to meet the directive's incident reporting and risk management obligations.
Market Restraints
- Semiconductor supply concentration:EU chip sovereignty initiatives have not yet reduced Spanish dependence on Asian foundry output for server hardware and networking equipment.
- Data center energy standards:BIS-equivalent efficiency requirements constrain facility location choices, limiting expansion to regions with renewable energy surplus and cooling capacity.
- GDPR enforcement intensity:The Spanish Data Protection Agency's active sanctioning regime elevates compliance costs and extends vendor onboarding timelines for cloud migrations.
Strategic Opportunities
- Andalusian logistics corridor:Underpenetrated enterprise cloud adoption in southern Spain offers first-mover advantages for edge computing deployments serving port and distribution operations.
- 5G private networks:Manufacturing clusters in the Basque Country and Catalonia present emerging demand for industrial automation and predictive maintenance applications.
- Green data center incentives:Spain's national energy transition framework provides tax advantages for facilities achieving carbon-neutral operations through renewable power purchase agreements.
Industry Challenges
- Cloud certification scarcity:The chronic shortage of AWS, Azure, and Google Cloud certified systems engineers extends project timelines and inflates labor costs for Spanish system integrators.
- Legacy system integration complexity:Mainframe-dependent banks and insurers face protracted modernization cycles as core banking platforms resist containerization and API abstraction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain ICT Market |
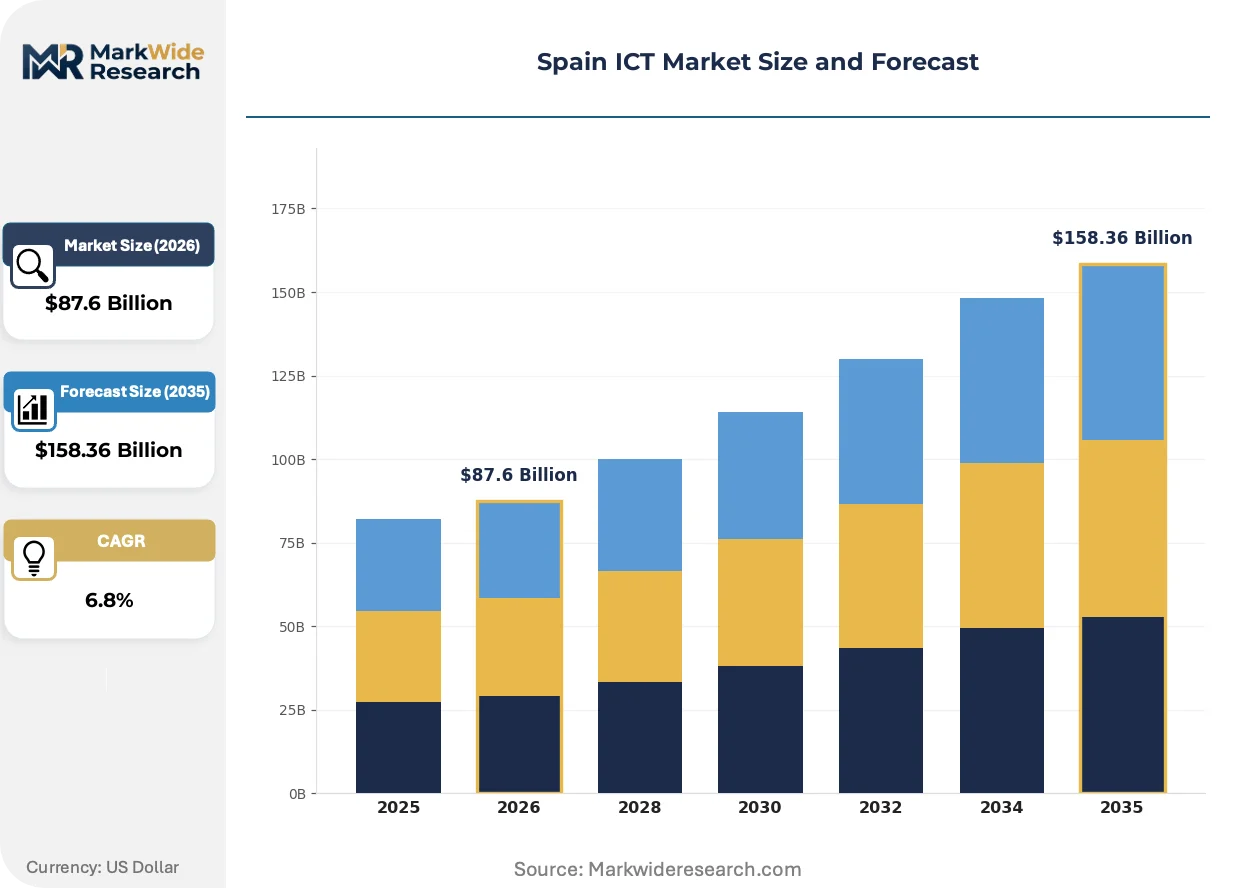
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, Artificial Intelligence, Cybersecurity, IoT Application: Healthcare IT, E-Learning, E-Commerce, Smart Cities End User: SMEs, Large Enterprises, Government, Educational Institutions Service Type: Consulting, Managed Services, System Integration, Software Development |
| Companies Covered | Altia Consultores SA, Amper, SA, Amadeus IT Group, SA, Agile Content SA, Gigas Hosting SA, Indra Sistemas, SA, Izertis SA, Arteche Lantegi Elkartea SA, Global Dominion Access, SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain ICT Market Evolving Landscape
Cloud-native architectures are actively displacing monolithic legacy systems across Spanish financial services, while sovereign cloud requirements and edge computing proliferation reshape vendor selection criteria.
Hybrid cloud infrastructure is bifurcating the Spanish enterprise market. Large banks and telecommunications operators maintain private cloud estates for sensitive workloads while bursting to hyperscale public clouds for analytics and development. Mid-market manufacturers increasingly favor managed sovereign cloud offerings from domestic providers to satisfy data residency requirements without capital-intensive facility builds.
The EU AI Act's risk-based classification system is forcing Spanish healthcare and financial software vendors to reengineer algorithmic decision systems. High-risk applications now require conformity assessments, human oversight protocols, and comprehensive documentation trails. Vendors serving Madrid's hospital networks and Barcelona's insurance clusters are prioritizing explainable machine learning frameworks to preempt regulatory friction.
Enterprise buying committees in Spain are consolidating vendor relationships around integrated platform providers. Discrete point-solution procurement is giving way to multi-year framework agreements with single-source accountability. This concentration is most visible among Madrid-based financial services groups, where procurement teams favor established system integrators with proven public-sector delivery track records over emerging specialists.
Spain ICT Market Segmentation
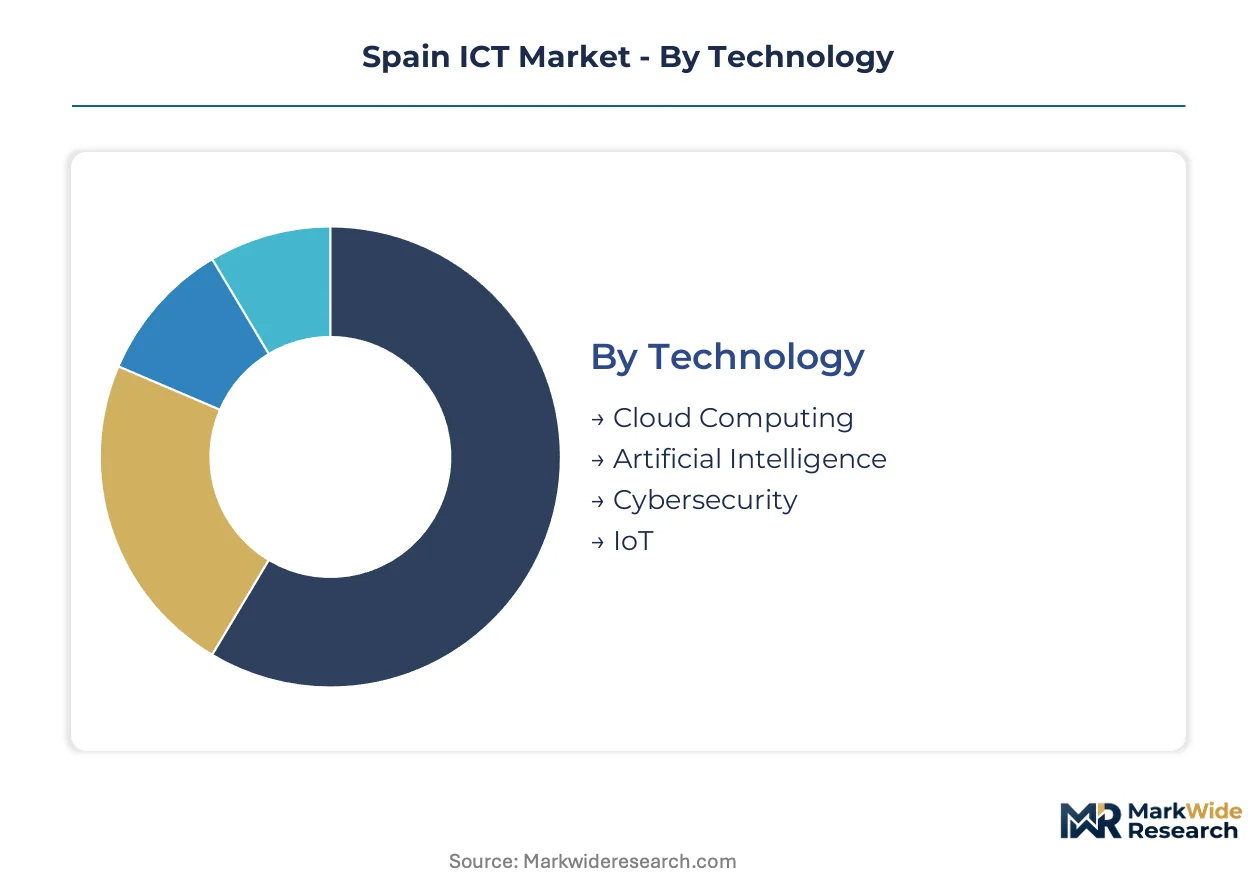
Technology procurement patterns in Spain diverge sharply between regulated sectors demanding compliance-ready infrastructure and cost-sensitive mid-market buyers prioritizing deployment speed. Understanding these segment fault lines exposes where vendor pricing power concentrates and where procurement consolidation reshapes competitive dynamics.
Technology:
Premium margins pool in segments where regulatory mandates force enterprise buyers toward certified, audit-ready platforms rather than commodity alternatives.
- Cloud Computing:Hybrid and multi-cloud architectures dominate enterprise roadmaps as Madrid-based financial groups migrate core banking workloads while maintaining private infrastructure for GDPR-sensitive data. Barcelona's smart city deployments and Andalusian logistics corridors absorb substantial hyperscale capacity through sovereign cloud partnerships.
- Cybersecurity:NIS2 transposition into Spanish law has elevated demand for managed detection and response services, with Basque Country manufacturing clusters and Catalan pharmaceutical operations driving premium pricing for incident response retainers. Spanish providers command margin expansion as breach notification deadlines compress procurement cycles.
- Artificial Intelligence:EU AI Act risk classifications are reshaping vendor selection, with high-risk healthcare diagnostic tools and credit scoring algorithms requiring conformity assessments.
- IoT:Municipal sensor networks in Madrid and Barcelona absorb public IT budgets for traffic management and environmental monitoring.
The dominant share belongs to Cloud Computing, while Cybersecurity is closing the gap fastest.
Application:
Public procurement volume concentrates in segments where municipal and regional governments deploy multi-year framework agreements.
- Smart Cities:Barcelona's superblock urban redesign and Madrid's digital twin initiatives anchor substantial infrastructure spending, with IoT sensor density and edge computing nodes expanding across traffic, waste, and energy management systems. EU cohesion funds and national recovery plan allocations sustain project pipelines through municipal technology departments.
- Healthcare IT:Hospital networks in Madrid and autonomous community health services are modernizing electronic health record systems under interoperability mandates, with telemedicine platforms and AI-assisted diagnostic tools absorbing capital budgets. The EU AI Act's high-risk classification for medical devices is forcing reengineering of algorithmic decision support.
- E-Learning:Regional education ministries and university consortiums are consolidating learning management platforms.
- E-Commerce:Retail technology spending concentrates in Madrid and Barcelona logistics hubs.
Smart Cities captures the largest procurement volume, though Healthcare IT is expanding most quickly as regional health authorities accelerate digitalization timelines.
End User:
Contract value and vendor stickiness diverge between long-cycle government frameworks and transactional SME relationships.
- Large Enterprises:Madrid-based banking groups and Barcelona insurance clusters dominate technology spending, with multi-year transformation programs spanning core system replacement and regulatory compliance infrastructure. These buyers favor established system integrators with proven public-sector delivery records over emerging specialists.
- Government:Central administration and regional governments in Madrid, Catalonia, and Andalusia deploy substantial budgets through framework agreements, with procurement rules favoring vendors with deep institutional relationships. Digital transformation contracts for tax administration and social services sustain incumbent positioning.
- SMEs:Mid-market manufacturers favor managed sovereign cloud offerings to satisfy data residency without capital-intensive facility builds.
- Educational Institutions:University technology procurement concentrates in research computing and administrative modernization.
Large Enterprises maintain the deepest vendor relationships, while Government procurement is consolidating fastest around integrated platform providers.
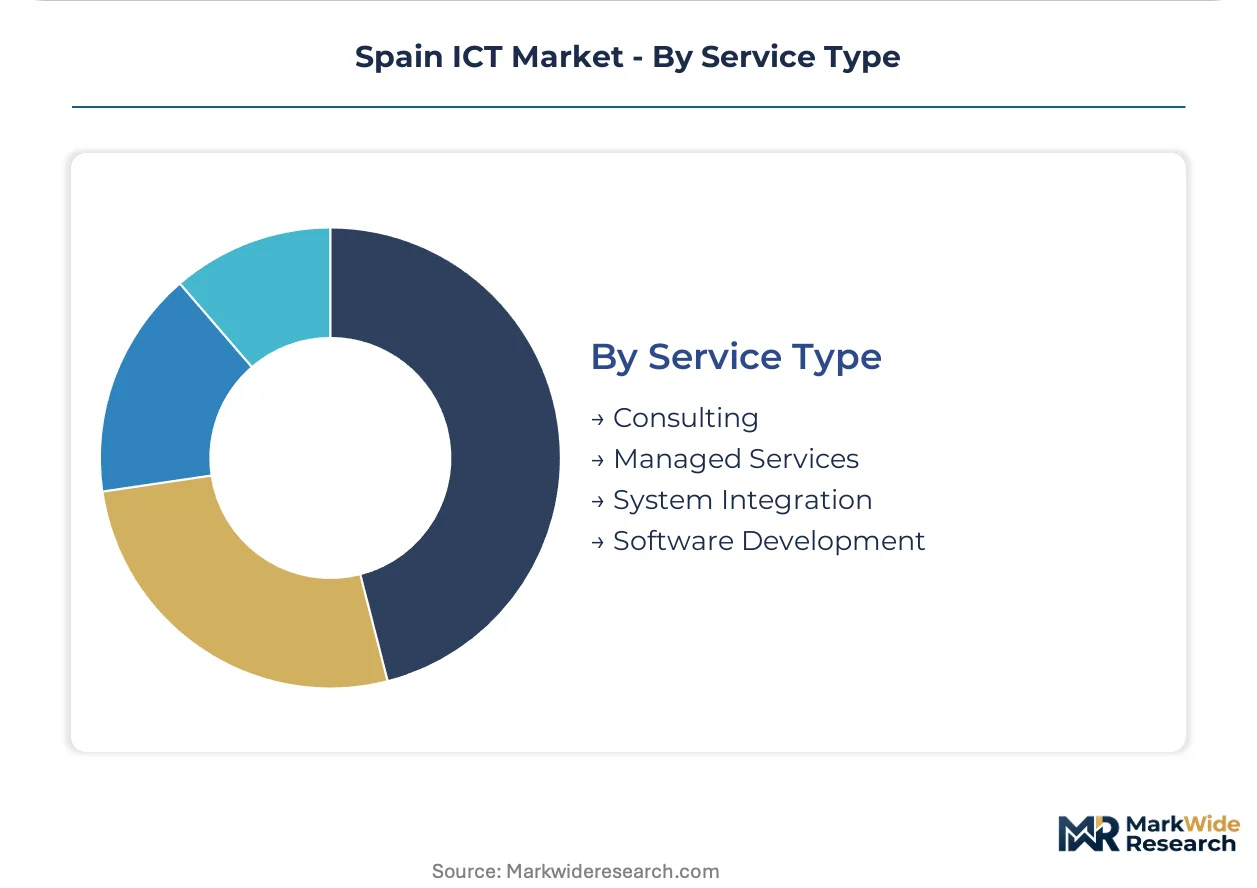
Service Type:
Margin compression affects commoditized delivery models while specialized compliance and integration services sustain pricing power.
- System Integration:Legacy mainframe modernization for Spanish banks and insurers demands specialized expertise in containerization and API abstraction, with chronic cloud certification scarcity inflating project costs and extending timelines. Indra Sistemas anchors public-sector integration through regional government relationships.
- Managed Services:Cybersecurity operations centers and cloud management platforms are absorbing enterprise outsourcing demand, with 24/7 monitoring and NIS2-aligned incident response commanding premium retainers. Basque Country manufacturing clusters favor industrial IoT managed services for predictive maintenance.
- Consulting:EU AI Act readiness assessments and GDPR compliance audits sustain advisory demand.
- Software Development:Agile delivery competes for mid-market modernization where speed-to-deployment differentiates vendor selection.
System Integration holds the established revenue base, though Managed Services is climbing the fastest as outsourcing accelerates across security and cloud operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ICT deployment patterns across Spain diverge sharply between Madrid's financial services concentration and Barcelona's municipal innovation clusters, with southern logistics corridors and northern industrial zones presenting distinct infrastructure requirements.
Madrid
The capital region absorbs the lion's share of enterprise cloud migration spending as banking groups modernize core platforms. GDPR enforcement by the Spanish Data Protection Agency shapes vendor selection criteria for hyperscale deployments. The Madrid technology corridor concentrates system integration contracts and sovereign cloud partnerships serving financial and administrative clients.
Catalonia
Barcelona anchors smart city infrastructure investment through municipal IoT networks and digital twin initiatives. EU cohesion funds sustain multi-year framework agreements for traffic management and environmental monitoring systems. The metropolitan area hosts specialized software vendors competing for mid-market agile delivery contracts.
Basque Country
Manufacturing clusters in this northern region drive demand for industrial 5G private networks and predictive maintenance platforms. NIS2-aligned cybersecurity requirements command premium pricing from managed detection providers. Bilbao and San Sebastián concentrate IoT managed services for automotive and machine tool producers.
Andalusia
The southern logistics corridor presents underpenetrated enterprise cloud adoption around Málaga and Algeciras port operations. Spain's national energy transition framework provides tax advantages for carbon-neutral data center builds. Seville and Cádiz municipalities are expanding digital administrative services through regional government procurement channels.
Valencia
This eastern region balances port logistics technology with emerging health tech clusters around biomedical research institutions. The EU AI Act's high-risk classification requirements reshape procurement for diagnostic algorithm vendors. Valencia's smart city programs absorb public IT budgets for mobility and waste management sensor networks.
Spain ICT Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with contract scale and regulatory compliance capabilities determining vendor positioning. Public-sector framework agreements favor established system integrators with proven delivery records across Madrid and regional administrations. Specialist archetypes include agile software delivery firms competing on deployment velocity and cybersecurity providers commanding premium margins under NIS2 mandates. Competitive moves concentrate on strategic partnerships with hyperscale cloud platforms and portfolio diversification into sovereign cloud offerings.
Within the integrated tier, Indra Sistemas, SA and Amadeus IT Group, SA exemplify divergent positioning strategies. Indra occupies a position anchored in public-sector digital transformation through deep institutional relationships with central and regional governments. Amadeus represents the travel technology infrastructure archetype, sustaining pricing power through proprietary reservation platforms. Izertis SA sits within the agile delivery specialist tier, competing for mid-market modernization programs where speed-to-deployment differentiates vendor selection.
| Leading Market Players |
|---|
| Altia Consultores SA |
| Amper, SA |
| Amadeus IT Group, SA |
| Agile Content SA |
| Gigas Hosting SA |
| Indra Sistemas, SA |
| Izertis SA |
| Arteche Lantegi Elkartea SA |
| Global Dominion Access, SA |
| Others |
Value Network & Pricing Analysis
Hyperscale data center capacity utilization above 85 percent in Madrid and Barcelona creates scale economies that compress unit costs for cloud infrastructure while elevating price floors for mid-market buyers lacking volume leverage. This concentration of compute capacity simultaneously tightens supply availability for specialized hardware and reinforces premium pricing for NIS2-compliant cybersecurity services across Spanish enterprise procurement.
Pricing Analysis
Long-term framework agreements dominate procurement for Madrid-based banking groups and regional government digital transformation programs, locking in multi-year pricing with established system integrators. Three-tier pricing structure across premium certified, standard compliant, and economy unmanaged levels differentiates vendors serving GDPR-sensitive workloads from commodity cloud resellers. Cost compression in the economy tier is intensifying because hyperscale providers are absorbing mid-market share through direct sovereign cloud partnerships. SMEs demonstrate highest price sensitivity, while financial services groups prioritize audit-ready platforms over unit cost minimization.
Supply Chain Analysis
Server hardware lead times extending 16-20 weeks from Asian foundries constrain Spanish enterprise deployment schedules and inflate carrying costs for system integrators holding buffer inventory. Taiwan, South Korea, and China anchor semiconductor supply for networking equipment and AI accelerators, while German and Dutch facilities supply specialized industrial IoT components. Spanish ICT infrastructure rests on memory modules, high-bandwidth interconnects, and custom ASICs vulnerable to single-source concentration in Taiwan's advanced packaging ecosystem. Distribution runs through Madrid-based value-added distributors serving regional system integrators, with direct hyperscale procurement bypassing traditional channels for large enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Madrid-based financial services procurement committees consolidating vendor relationships around integrated platform providers, fragmenting pricing leverage for discrete point-solution vendors.
For Market Incumbents: Consolidate around sovereign cloud certification investments and deepen API abstraction capabilities for legacy mainframe modernization. The EU AI Act's conformity assessment requirements threaten margin erosion for vendors lacking explainable AI frameworks. Prioritize vertical integration into edge computing infrastructure for Basque Country manufacturing clusters to preempt hyperscale encroachment. For New Entrants and Emerging Players: Differentiate on deployment velocity for Andalusian logistics corridor cloud migrations, where first-mover advantages persist in underpenetrated southern Spain. Target municipal IoT managed services in secondary cities bypassed by Indra's public-sector dominance. Lead with sovereign cloud partnerships emphasizing GDPR-aligned data residency without capital-intensive facility builds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized cybersecurity providers with NIS2-aligned incident response capabilities and recurring revenue bases. Long-term viability hinges on regulatory compliance moats deepening through EU AI Act enforcement expansion. Acquisition targets should demonstrate contracted recurring revenue from Basque Country manufacturing or Catalan healthcare networks. Watch hyperscale sovereign cloud partnership announcements as inflection indicators for domestic provider margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | GDPR-aligned data residency locks in Madrid financial services procurement without hyperscale dependency. |
| NIS2 Compliance Certification | Managed detection services command premium retainers from Basque Country manufacturing clusters. |
| Edge Computing Deployment | Andalusian port logistics creates first-mover positioning in underpenetrated southern enterprise cloud. |
| EU AI Act Conformity Assessment | Explainable machine learning frameworks preempt regulatory friction for Barcelona healthcare diagnostics. |
| Legacy Modernization Platform | API abstraction capabilities unlock protracted core banking transformation cycles for Spanish insurers. |
Research Methodology
Operator-level perspectives from CTOs at Madrid banking groups, Catalan hospital network IT directors, Basque Country manufacturing plant engineers, and Andalusian logistics procurement leads anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings of listed Spanish ICT providers, hyperscaler capex disclosures, EU Digital Economy and Society Index datasets, and Spanish Data Protection Agency sanction registers. Bottom-up project pipeline analysis across regional government procurement portals triangulated against top-down macroeconomic scenario modeling.
Sensitivity analysis tested demand elasticity across cloud migration intensity scenarios and regulatory enforcement variance assumptions over the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, compliance complexity level, and regional adoption pattern. CAGRs derived from volume trajectory reconciliation against value expansion through premium service mix shifts. Forecast inputs incorporated EU cohesion fund allocation schedules and NIS2 transposition implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU recovery plan disbursement or accelerated GDPR enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding hyperscale market entry patterns and sovereign cloud partnership proliferation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
Global Virtual PBX Market
Telecommunications
MVNO Market
Telecommunications
Virtualized RAN (Vran) Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Telecommunication Service Market
Telecommunications
Thailand Telecom Market
Telecommunications
5G Remote Radio Head Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Indonesia ICT Market
Telecommunications
Argentina ICT Market
Telecommunications
Global Policy Management in Telecom Market