
 Middle East Distribution Meter Market | 2026-2036
Middle East Distribution Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Distribution Meter Market Insights
Advanced metering infrastructure is fragmenting across multiple communication protocols and deployment models across the Middle East. Schneider Electric SE leverages its integrated energy management portfolio to anchor large-scale utility tenders in the Gulf. Landis+Gyr Group AG specializes in RF mesh ecosystems suited to harsh desert climates where line-of-sight transmission dominates. Honeywell International Limited extends its building automation expertise into commercial and industrial metering segments where sub-metering requirements intensify.
Distribution meters are electromechanical or solid-state devices that measure electricity consumption at grid edge points, typically rated between 5-100 amperes with accuracy classes of 0.5S to 2.0 under IEC 62052-11 standards, and serve to enable billing reconciliation, load profiling, and outage detection for utility operators. Smart meters command the dominant product position as Gulf utilities phase out electromechanical units, while prepaid meters represent the fastest-growing configuration among residential consumers seeking consumption visibility and budget control. Cellular technology leads the communication layer due to mature 4G infrastructure across Saudi Arabia and the UAE, though RF mesh systems compete aggressively in dense urban clusters where peer-to-peer relay reduces carrier dependency.
Saudi Arabia's Electricity and Cogeneration Regulatory Authority mandates AMI compatibility standards that shape procurement specifications for new meter deployments. The UAE's Federal Electricity and Water Authority enforces accuracy and cybersecurity certification requirements that filter market access for foreign suppliers. Stakeholders must monitor how national renewable integration targets reshape meter functionality requirements around bidirectional energy flow measurement and distributed generation accounting.
Market Dynamics
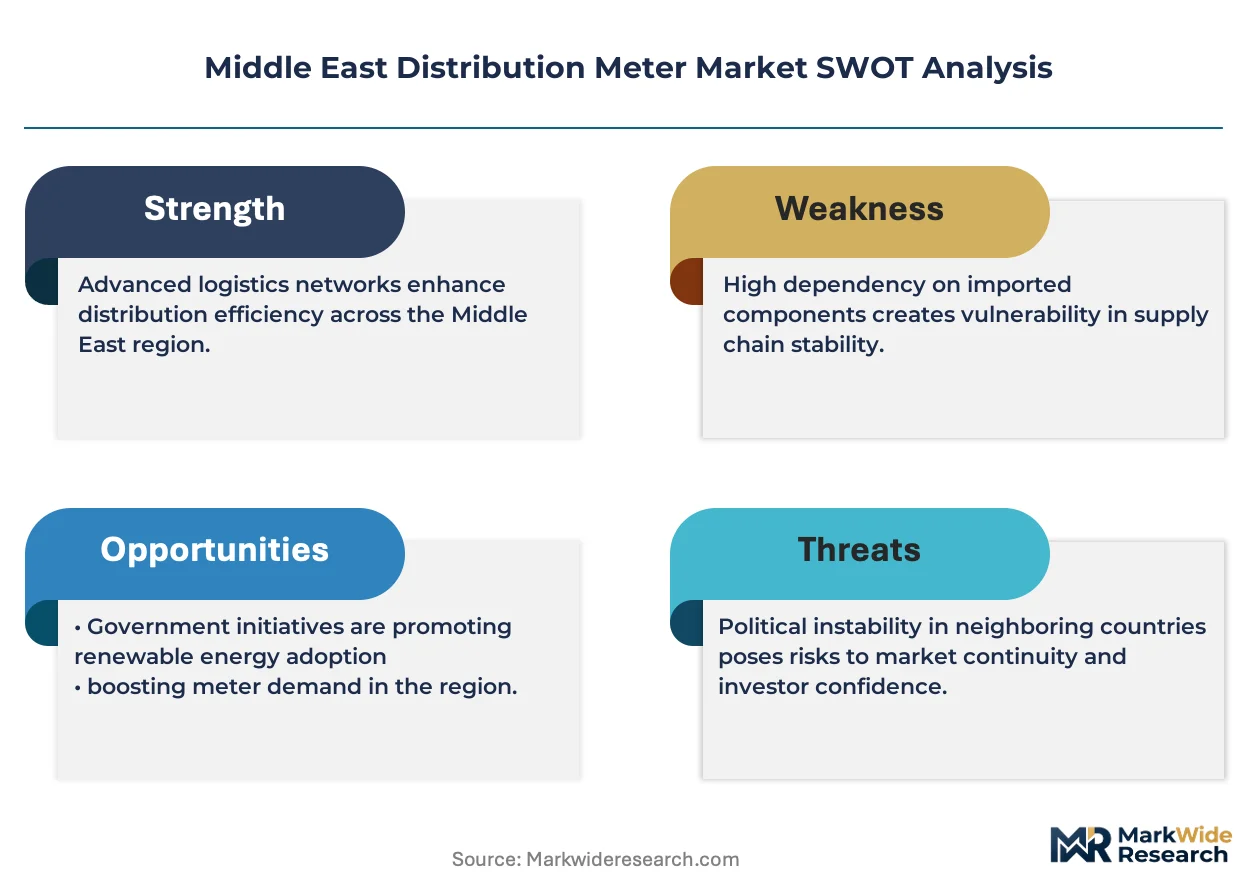
Gulf utilities are replacing electromechanical meters with solid-state AMI units under national efficiency mandates, creating procurement concentration around integrated communication modules and cybersecurity-certified hardware platforms.
Growth Catalysts
- Saudi Arabia's ECRA mandates:The Electricity and Cogeneration Regulatory Authority requires AMI compatibility for all new meter deployments, forcing utilities into accelerated replacement cycles.
- RF mesh technology:Desert line-of-sight conditions favor peer-to-peer relay systems over power line carrier in dense urban clusters across the UAE and Qatar.
- Prepaid residential demand:Budget-conscious consumers in Oman and Bahrain drive fastest configuration growth as visibility tools replace traditional billing reconciliation.
Market Restraints
- Semiconductor input volatility:Meter ASICs and communication chipsets face supply concentration risk from East Asian foundry capacity constraints.
- Technical interoperability limits:Fragmented communication protocols between cellular and RF mesh ecosystems force utilities into single-vendor lock-in or expensive gateway investments.
- UAE cybersecurity certification friction:FEWA's mandatory hardware security module requirements extend procurement timelines for foreign suppliers lacking regional testing facilities.
Strategic Opportunities
- Kuwait's underpenetrated AMI base:Slower deployment relative to Saudi Arabia and UAE creates white space for turnkey infrastructure providers.
- Bidirectional metering for solar integration:Distributed generation accounting capabilities align with Saudi and UAE renewable capacity targets.
- Sub-metering convergence:Building automation integration creates channel expansion into commercial real estate management platforms.
Industry Challenges
- Field technician scarcity:Specialized skills for AMI commissioning and RF network optimization outpace vocational training pipeline output across the GCC.
- Legacy electromechanical coexistence:Parallel meter fleets force utilities into dual maintenance systems and data reconciliation complexity during transition phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Distribution Meter Market |
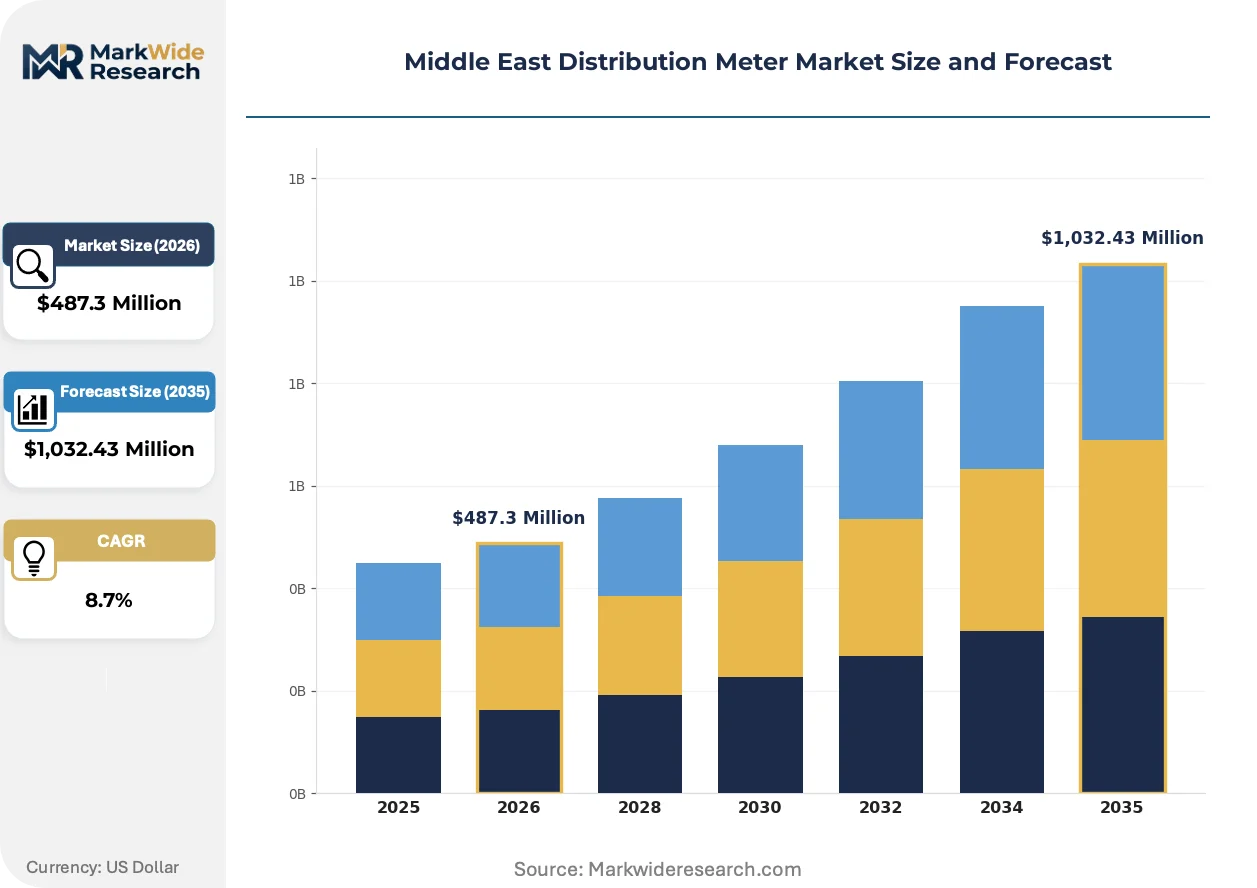
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Analog Meters, Prepaid Meters, Time-of-Use Meters Technology: RF Mesh, Power Line Communication, Cellular, Ethernet End User: Utilities, Commercial, Industrial, Residential Installation Type: Overhead, Underground, Pole-Mounted, Wall-Mounted |
| Companies Covered | Schneider Electric SE, Iskraemeco d.d., Landis+Gyr Group AG, Honeywell International Limited, Wasion Holdings Limited, Itron Inc., Siemens AG, Diehl Metering, Kamstrup A/S, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Distribution Meter Market Trends and Innovations
Edge computing capabilities and communication module miniaturization are compressing hardware footprints while expanding real-time analytics scope for distribution network operators.
Software-defined meter firmware is virtualizing functionality previously locked in dedicated ASICs. Saudi utilities are piloting over-the-air feature activation for demand response and tariff restructuring without hardware swaps. This architecture is virtualizing the traditional five-year replacement cycle into continuous capability upgrades.
Saudi ECRA's interoperability standards are mandating open application programming interfaces for meter data management systems. The regulation forces incumbent vendors to decouple hardware from software licensing. AMI platform providers are responding with modular service architectures that separate communication layer from metrology core.
Consumption visibility apps are displacing traditional utility billing portals among residential buyers. Younger demographics in Dubai and Riyadh expect real-time usage alerts and budget forecasting tools. This behavioral shift is most visible in prepaid meter configurations where mobile wallet integration has become a procurement evaluation criterion.
Middle East Distribution Meter Market Segmentation
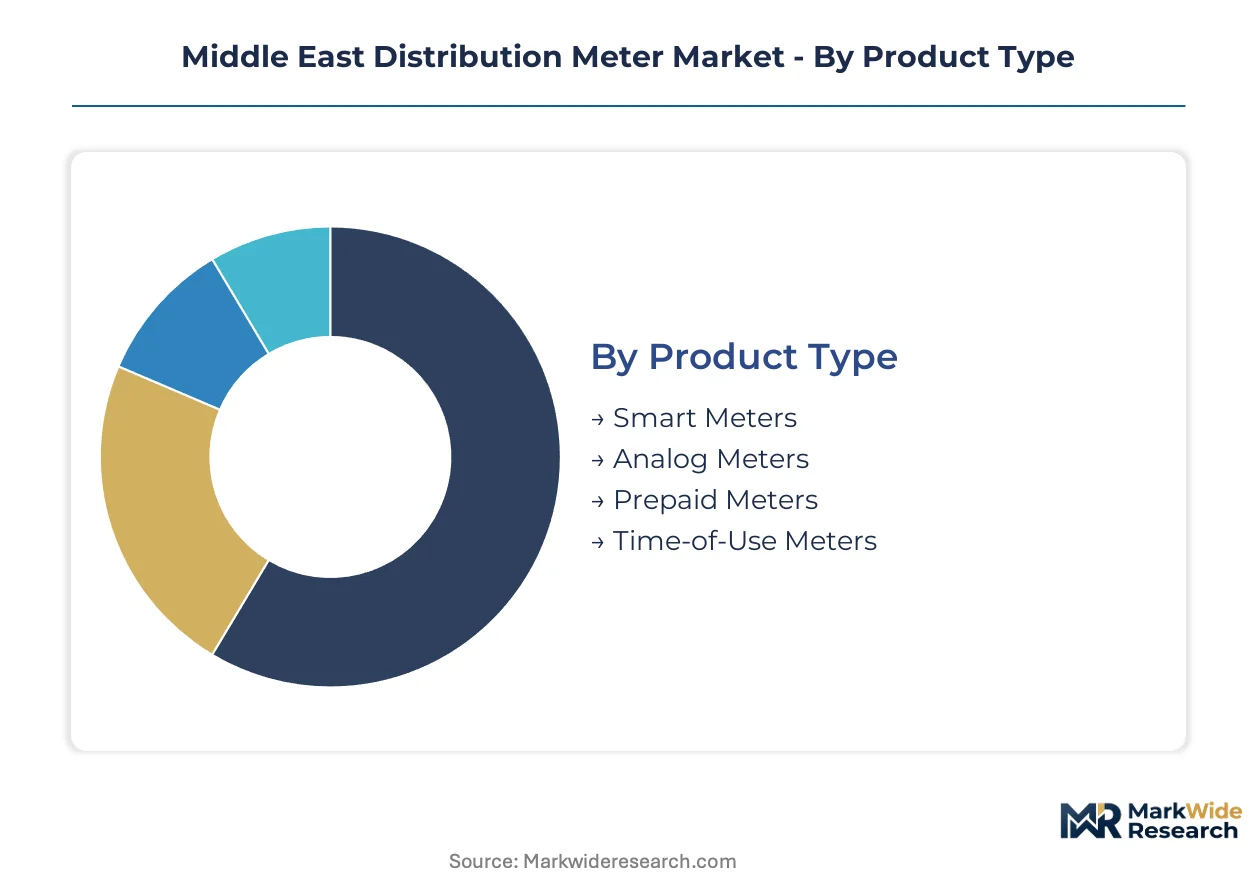
Distribution meter procurement across the Middle East fragments across four structural dimensions. Each segmentation layer carries distinct margin profiles and aftermarket service intensities that reshape vendor positioning strategies.
Product Type:
After-sales service intensity varies sharply across meter categories, with smart platforms demanding continuous firmware management and prepaid configurations requiring payment ecosystem integration.
- Smart Meters:Solid-state devices with integrated communication modules enable real-time consumption monitoring and remote disconnect capabilities. Saudi Arabia's ECRA mandates are concentrating utility procurement volumes here as electromechanical replacement cycles accelerate. Firmware update obligations and cybersecurity patch management create recurring service revenue streams for vendors.
- Prepaid Meters:Units with embedded payment token systems or mobile wallet interfaces allow residential consumers to purchase energy credits in advance. Demand concentrates in Oman and Bahrain where budget-conscious households prioritize consumption visibility over traditional billing reconciliation. Mobile wallet integration has become a mandatory procurement evaluation criterion in Dubai and Riyadh.
- Analog Meters:Electromechanical induction-type devices with rotating aluminum discs measure consumption without digital communication capabilities.
- Time-of-Use Meters:Solid-state units with multiple tariff registers record consumption across peak, off-peak, and shoulder periods for demand response programs.
Smart meters hold the largest share; momentum sits with prepaid configurations.
Technology:
Communication protocol selection determines total cost of ownership through infrastructure deployment requirements and ongoing carrier dependency.
- Cellular:4G/LTE modules leverage mature operator infrastructure across Saudi Arabia and the UAE for wide-area coverage without proprietary network investment. Mature tower density in Riyadh and Jeddah eliminates relay infrastructure costs, though carrier subscription fees accumulate over deployment lifecycles.
- RF Mesh:Peer-to-peer radio frequency networks exploit desert line-of-sight conditions for reliable urban coverage without cellular dependency. Dense clusters in Doha and Abu Dhabi favor this architecture where peer relay reduces carrier subscription exposure.
- Power Line Communication:Modulated data transmission over existing medium-voltage distribution lines.
- Ethernet:Wired IP connectivity for high-density commercial and industrial substations with existing LAN infrastructure.
Cellular technology leads current deployments; RF mesh systems are gaining share fastest in dense urban clusters.
End User:
Customer type segmentation aligns procurement specifications with billing complexity and data granularity requirements.
- Utilities:State-owned distribution companies across the GCC require AMI-certified hardware with centralized meter data management integration and cybersecurity module compliance.
- Commercial:Real estate operators and facility managers demand sub-metering capabilities for tenant billing reconciliation and building automation system integration.
- Industrial:Heavy manufacturing and petrochemical facilities require high-accuracy Class 0.5S meters with power quality monitoring and harmonics analysis.
- Residential:Individual household deployments concentrate in villa compounds and apartment blocks with varying density across Kuwait City and Manama.
Utilities dominate procurement volumes; commercial applications are expanding most quickly through building automation convergence.
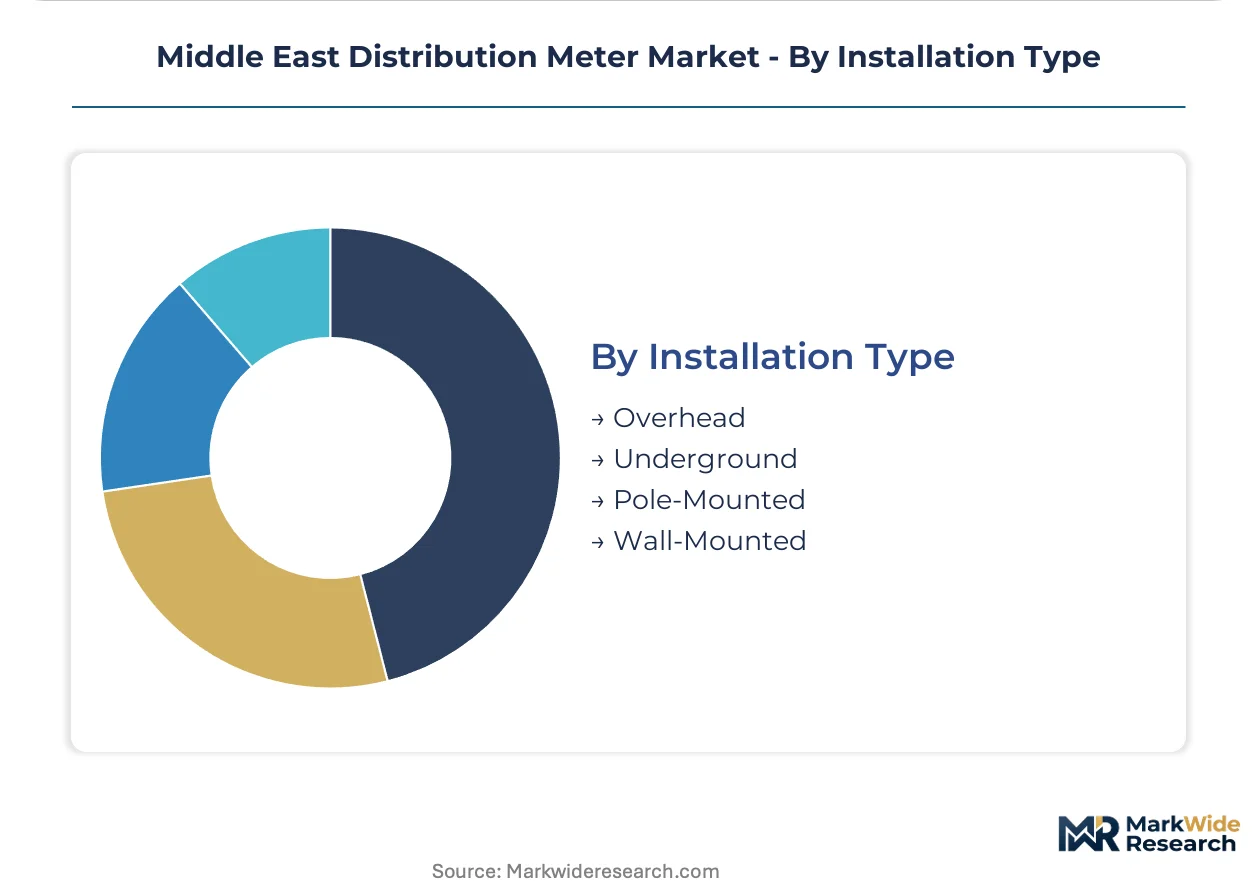
Installation Type:
Physical mounting configuration responds to distribution network topology and urban density patterns across Gulf cities.
- Overhead:Aerial mounting on low-voltage distribution poles serves established neighborhoods with legacy aerial conductor networks.
- Underground:Pad-mounted or vault-installed units accommodate new developments with buried cable infrastructure across master-planned communities in Dubai and Riyadh.
- Pole-Mounted:Dedicated meter poles in rural and semi-urban areas with limited building attachment options.
- Wall-Mounted:Direct building facade installation for dense urban residential blocks and commercial structures.
Underground installations hold the largest share in new construction; overhead configurations retain dominance in retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned utilities across the Gulf Cooperation Council dominate procurement volumes, with regulatory mandates from Saudi Arabia's Electricity and Cogeneration Regulatory Authority and the UAE's Federal Electricity and Water Authority shaping vendor qualification requirements and deployment timelines.
Saudi Arabia
Riyadh and Jeddah utilities are accelerating electromechanical meter replacement cycles under ECRA's AMI compatibility mandates. The national energy efficiency program requires bidirectional measurement capabilities for distributed solar integration. Eastern Province petrochemical complexes are piloting Class 0.5S meters with power quality monitoring for harmonics analysis.
United Arab Emirates
Dubai's master-planned communities favor underground meter installations with building automation system integration. FEWA enforces hardware security module certification that extends procurement timelines for foreign suppliers lacking regional testing facilities. Abu Dhabi's dense urban clusters are deploying RF mesh networks to reduce cellular carrier dependency.
Qatar
Doha's infrastructure investment wave is concentrating prepaid meter demand among residential compounds seeking mobile wallet integration. The national utility is evaluating AMI platforms with open APIs to avoid single-vendor lock-in. Lusail City's smart city development is serving as a testbed for software-defined meter firmware with over-the-air feature activation.
Kuwait
Slower AMI penetration relative to Saudi Arabia and the UAE creates white space for turnkey infrastructure providers. Kuwait City's established neighborhoods retain overhead aerial networks requiring pole-mounted retrofit configurations. The Ministry of Electricity and Water is assessing cybersecurity frameworks aligned with Gulf standardization initiatives.
Oman
Budget-conscious households in Muscat and Salalah are driving prepaid meter adoption for consumption visibility and budget control. Rural and semi-urban areas require dedicated meter poles where building attachment options remain limited. The Authority for Electricity Regulation is harmonizing technical specifications with neighboring Gulf markets to streamline vendor qualification.
Middle East Distribution Meter Market Competitive Landscape
Channel-controlling players compete with product-specialist players across integrated energy management portfolios and RF mesh ecosystems. The vendor base clusters around three strategic archetypes: integrated industrial conglomerates with utility-scale project execution capabilities, communication-technology specialists optimizing desert line-of-sight transmission, and metrology-focused manufacturers emphasizing accuracy certification. Dominant competitive moves include strategic partnerships with regional system integrators and portfolio diversification into sub-metering for commercial building automation.
Within the integrated industrial tier, Schneider Electric SE and Siemens AG represent channel-controlling players leveraging broad energy infrastructure portfolios. Landis+Gyr Group AG and Honeywell International Limited exemplify product-specialist positioning, with the former anchoring RF mesh expertise and the latter extending building automation capabilities into metering segments. Itron Inc. and Kamstrup A/S occupy positions emphasizing metrology precision and open-API platform architectures.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Iskraemeco d.d. |
| Landis+Gyr Group AG |
| Honeywell International Limited |
| Wasion Holdings Limited |
| Itron Inc. |
| Siemens AG |
| Diehl Metering |
| Kamstrup A/S |
| Others |
Pricing and Supply Chain Analysis
The Jebel Ali-Dammam freight corridor compresses logistics costs for meter manufacturers serving Saudi and UAE utilities, concentrating supply power among East Asian foundries while forcing downstream price differentiation between AMI-certified and legacy hardware tiers.
Pricing Analysis
Cost-plus contracts with copper and semiconductor price indexation dominate utility procurement agreements across the GCC. Pricing stratifies across premium, standard, and economy tiers based on IEC 62052-11 accuracy class and cybersecurity certification grade. Cost compression in standard-tier cellular modules is intensifying because of foundry capacity expansion in Taiwan and South Korea. State-owned utilities exhibit lowest price sensitivity due to mandated replacement cycles, while commercial real estate operators in Dubai demonstrate highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Upstream feedstock for meter ASICs and communication chipsets draws from Taiwan, South Korea, and China, with polycarbonate enclosures and copper winding wire sourced from regional petrochemical complexes in Saudi Arabia and the UAE. Critical dependencies include silicon wafers, RF transceiver modules, and hardware security modules certified to FEWA standards. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through authorized regional system integrators holding ECRA and FEWA pre-qualification status.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East distribution meter market sits in a cyclical recovery phase driven by Saudi Arabia's national energy efficiency program mandating complete electromechanical meter replacement.
For Market Incumbents: Pre-empt emerging competition from Chinese meter manufacturers by deepening backward integration into regional cybersecurity testing facilities and securing exclusive channel partnerships with Kuwait's Ministry of Electricity and Water. Accelerate firmware virtualization roadmaps to lock in recurring service revenue streams before open-API mandates commoditize hardware margins. For New Entrants and Emerging Players: Pursue Kuwait's underpenetrated AMI infrastructure and Oman's prepaid meter segments where incumbent presence remains thin. Target commercial sub-metering applications in Dubai's master-planned communities through building automation system integration partnerships. Lead with mobile wallet-enabled prepaid configurations to differentiate against legacy billing-focused incumbents. For Investors and Strategic Acquirers: RF mesh communication specialists with proven desert climate deployments represent the most attractive acquisition archetype for portfolio exposure to Gulf utility digitization. Long-term viability hinges on software-defined meter firmware capabilities enabling continuous feature upgrades without hardware replacement. Watch for Saudi ECRA interoperability standard enforcement as the inflection signal accelerating vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | FEWA hardware security module compliance filters market access for foreign suppliers lacking regional testing infrastructure. |
| RF Mesh Network Deployment | Peer-to-peer relay systems exploit desert line-of-sight conditions in dense Doha and Abu Dhabi urban clusters. |
| Software-Defined Firmware Development | Over-the-air feature activation virtualizes replacement cycles into continuous capability upgrades for Saudi utilities. |
| Mobile Wallet Integration | Prepaid meter procurement evaluations in Dubai and Riyadh now mandate digital payment ecosystem connectivity. |
| Turnkey Infrastructure Partnerships | Kuwait's slower AMI penetration creates white space for integrated deployment and commissioning service providers. |
Research Methodology
The analysis maps smart meter, prepaid meter, and sub-metering sub-sectors, each validated through utility procurement officers, EPC contractors, and regional system integrators across Saudi Arabia, UAE, Qatar, Kuwait, and Oman. Secondary sources include ECRA regulatory filings, FEWA certification databases, GCC customs trade data, and IEC standard documentation. Bottom-up unit deployment estimates triangulate against top-down utility capex disclosures.
Assumptions around Saudi replacement cycle acceleration and UAE cybersecurity enforcement timelines remained fixed, while cellular infrastructure maturity and RF mesh adoption rates varied across sensitivity scenarios. Segmentation dimensions span product type, communication technology, end-user category, and installation configuration. CAGRs derive from regression analysis against historical deployment trajectories and regulatory mandate schedules, with inputs from semiconductor supply lead times and utility budget allocation patterns.
Macroeconomic conditions sit as an overlay; deviation in oil-price-linked government spending and construction activity would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and foundry capacity expansion. Cross-checking against utility-published procurement tender volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Global Digital Power Meter Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Europe Smart Meters Market
Smart Meters
Smart Meters Market
Smart Meters
Power Metering Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Power Quality Meter Market
Smart Meters
Digital Water Meters Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
United States Smart Meter Market
Smart Meters
Smart Meter Data Management Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Power Monitoring System Market
Smart Meters
Gas Meters Market
Smart Meters
Single-Phase Anti-Theft Meter Market