
 Asia-Pacific Smart Meter Data Management Market | 2026-2036
Asia-Pacific Smart Meter Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Meter Data Management Market Analytics
Platform licensing revenue is rewriting margin economics across the value chain. Itron Inc. leverages its RF mesh architecture to dominate firmware-to-cloud integration. Siemens AG anchors large-scale deployments through its hybrid deployment expertise. Oracle Corporation competes on analytics depth, sustaining recurring revenue from utility data lakes.
Asia-Pacific Smart Meter Data Management encompasses the collection, validation, storage, and analytics infrastructure for interval consumption data transmitted from advanced metering infrastructure, typically processing 15-minute to hourly reads across millions of endpoints. The primary purpose is enabling utilities to execute time-of-use pricing, detect non-technical losses, and balance distributed energy resources in real time. RF mesh technology occupies the largest installed base due to its self-healing topology in dense urban environments, while cloud deployment models represent the fastest-expanding segment as state-owned utilities outsource capital-intensive infrastructure. Edge computing is emerging as a margin-rich niche for latency-critical applications such as outage management and demand response orchestration.
China's MIIT enforces GB standards for data interoperability and cybersecurity in national smart grid programs, while India's CEA mandates AMI integration under the National Electricity Policy. Australia's national regulator requires interval data accessibility for retail competition under the National Energy Retail Law. Stakeholders must monitor how fragmented standards across ASEAN jurisdictions affect platform portability and compliance costs.
Market Dynamics
AMI deployment mandates from China's MIIT and India's CEA are compressing procurement timelines, forcing utilities to outsource platform architecture rather than build proprietary stacks. This regulatory pressure is concentrating vendor relationships around hybrid cloud-edge configurations.
Growth Catalysts
- RF mesh standardization:China's GB standards for interoperability eliminate proprietary lock-in, accelerating multi-vendor AMI rollouts in dense urban corridors.
- India's Smart Cities Mission:Municipal corporations bundle smart metering with streetlight automation and EV charging infrastructure, creating integrated data platform demand.
- Time-of-use pricing mandates:Australia's National Energy Retail Law requires interval data accessibility, compelling retailers to invest in real-time analytics engines.
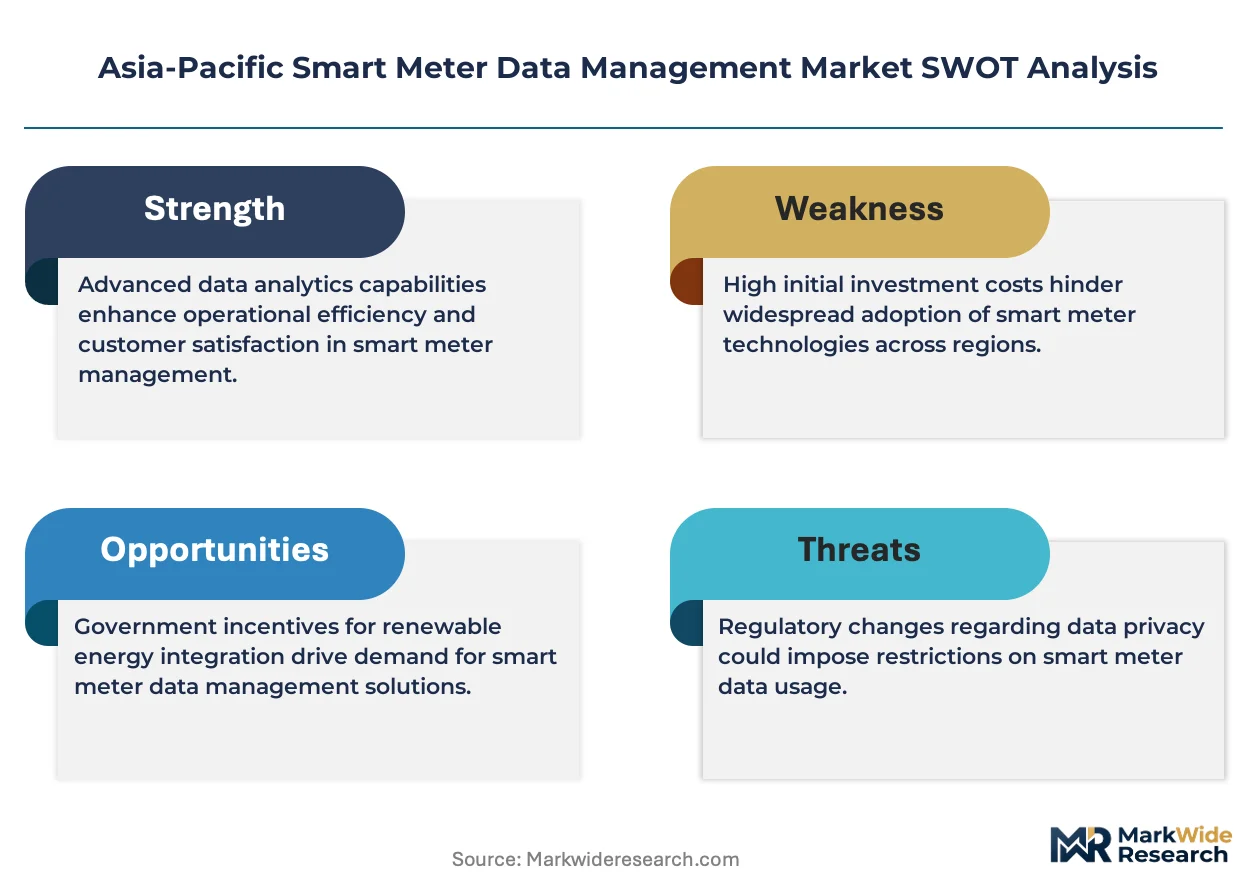
Market Restraints
- Semiconductor supply concentration:RF chip fabrication concentrates in Taiwan and South Korea, exposing AMI hardware procurement to geopolitical supply shocks.
- Cybersecurity compliance layering:China's MIIT GB standards and Australia's CDR framework impose overlapping certification requirements, extending platform validation cycles.
- Legacy SCADA integration:Proprietary protocols from 1990s-era grid automation systems resist API-based connectivity, forcing expensive middleware development.
Strategic Opportunities
- Vietnam and Indonesia grid modernization:State utilities in these markets lack indigenous platform vendors, creating first-mover advantages for established AMI integrators.
- Edge-AI convergence:Latency-critical applications including outage prediction and transformer load balancing demand localized inference, opening premium hardware-software bundles.
- Japan's carbon neutrality roadmap:METI incentives for demand response aggregation require distributed energy resource orchestration platforms with sub-second control loops.
Industry Challenges
- Data science talent scarcity:Utilities struggle to hire machine learning engineers capable of deploying predictive models on encrypted meter streams without exposing PII.
- Multi-jurisdiction compliance:Platform vendors serving ASEAN markets must maintain separate audit trails for Thailand's PEA standards, Malaysia's ST regulations, and Philippines' ERC rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Meter Data Management Market |
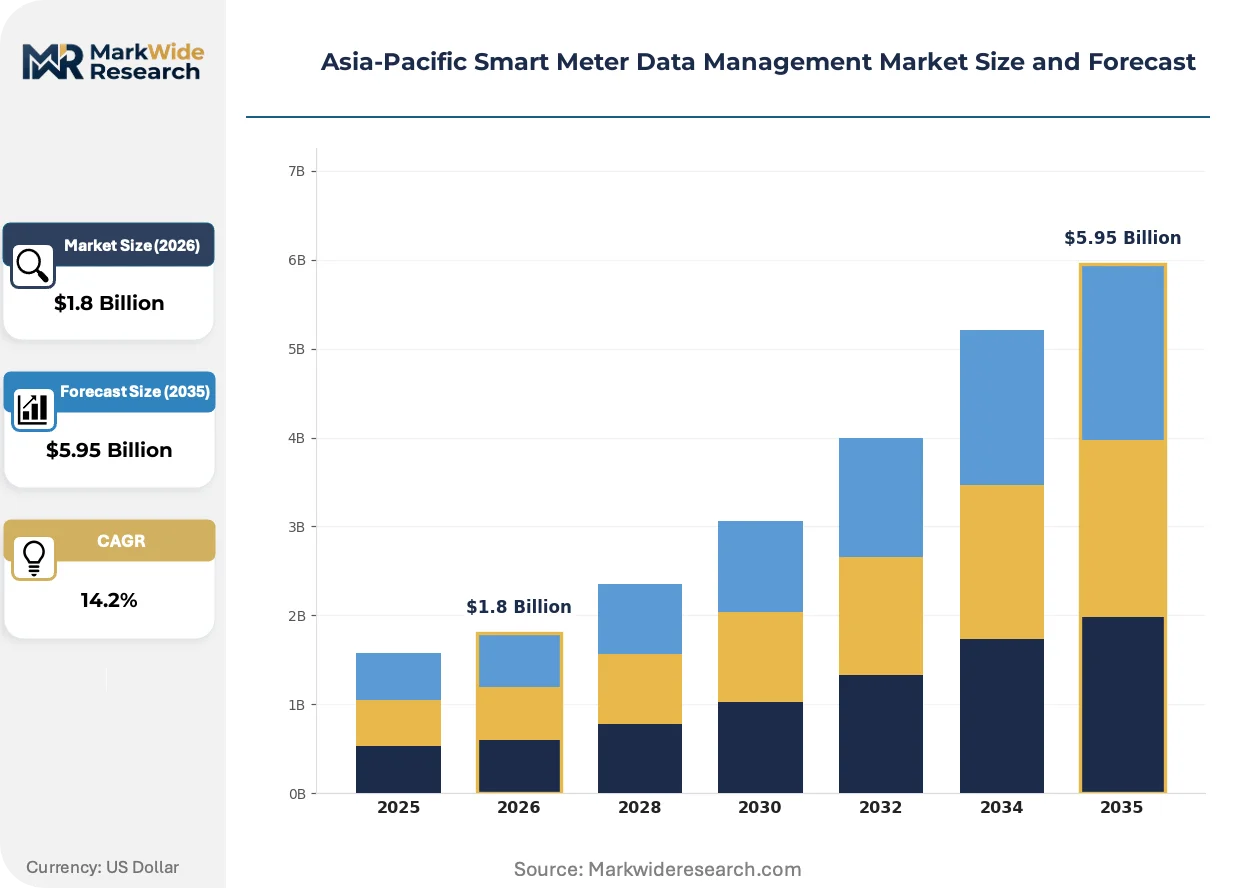
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RF Mesh, Cellular, PLC, LoRaWAN Application: Utilities, Industrial, Residential, Commercial Deployment Model: On-Premises, Cloud, Hybrid, Edge Service Type: Installation, Maintenance, Consulting, Support |
| Companies Covered | Oracle Corporation, Itron Inc., Siemens AG, ABB Group, Honeywell International, Trilliant Holdings, Landis+Gyr Group, Hubbell Incorporated, Hansen Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Meter Data Management Market Evolving Landscape
Edge computing architectures are displacing centralized cloud processing for latency-sensitive grid applications. This shift is compressing the traditional three-tier data flow into localized inference clusters, rewiring vendor competitive positioning around hardware-software integration depth.
Digital twin technology is digitizing physical distribution network behavior through real-time meter data ingestion and physics-based simulation. State Grid Corporation of China and Tata Power are deploying these models for predictive asset management, reducing transformer failure response from hours to minutes. The technology is digitizing maintenance scheduling by correlating interval consumption patterns with thermal loading profiles.
India's CEA has mandated AMI integration under the National Electricity Policy, requiring DISCOMs to publish standardized data APIs for third-party aggregators. This regulatory pressure is fragmenting platform procurement, with state utilities now evaluating modular architectures against monolithic legacy stacks. The mandate most affects rural electrification zones where meter density remains below urban thresholds.
Subscription-based platform licensing is replacing perpetual software purchases among mid-sized Australian retailers. These buyers now prioritize operational expenditure models that bundle analytics, cybersecurity updates, and regulatory compliance patches into single contracts. The shift is most visible in Victoria and South Australia, where retail competition has intensified price sensitivity and compressed technology refresh cycles.
Asia-Pacific Smart Meter Data Management Market Segmentation
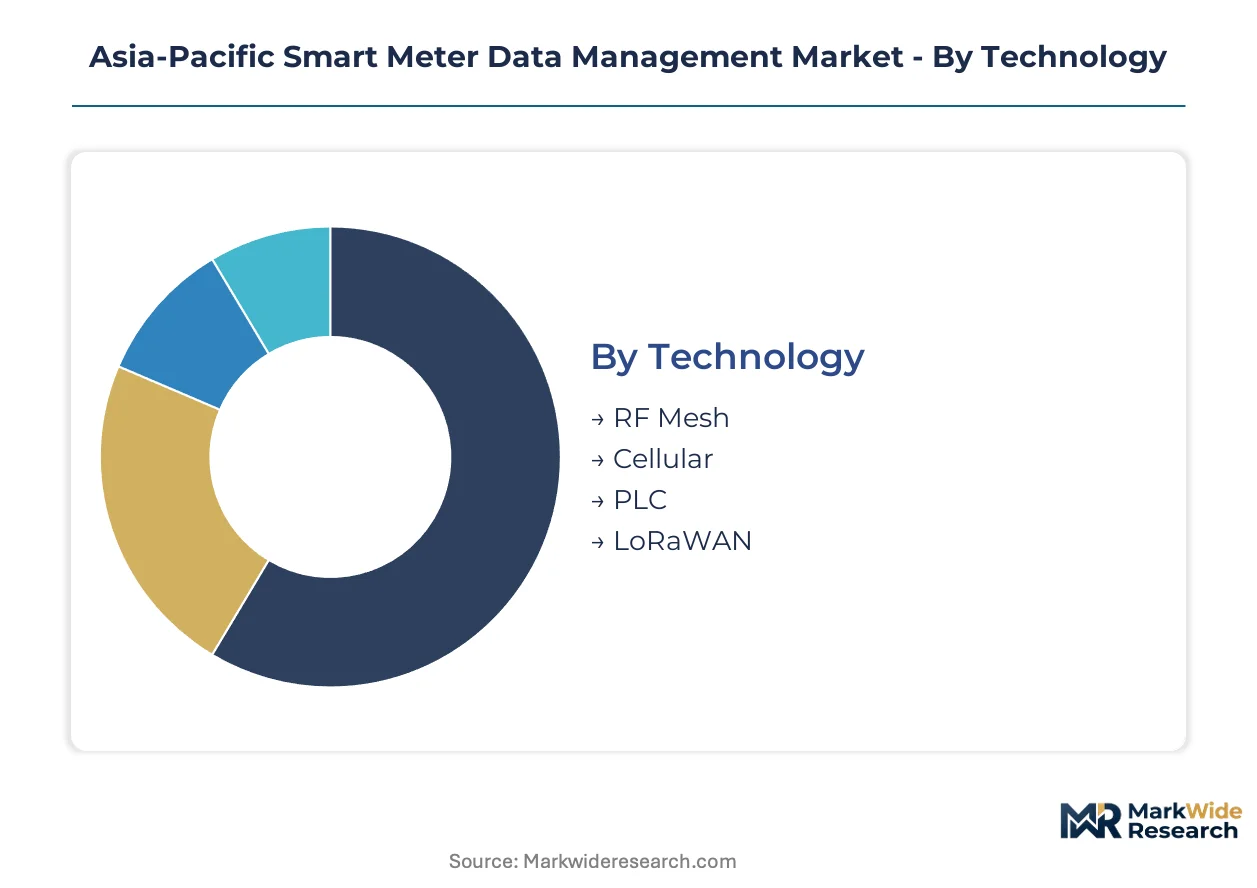
Segmentation in Asia-Pacific smart meter data management reveals how procurement priorities diverge across connectivity architectures and operational contexts. Technology choices determine hardware refresh cycles, while deployment models dictate capital structure and vendor lock-in duration.
Technology:
RF mesh and cellular platforms operate on fundamentally different replacement rhythms, with mesh infrastructure turning over every 12-15 years versus cellular modules requiring 5-7 year upgrades as cellular generations evolve.
- RF Mesh:Self-healing network topology using proprietary or standards-based radio frequencies to relay meter data through neighboring nodes. Dense urban deployments in China and India favor this architecture for its resilience against single-point failures and minimal recurring carrier fees. State Grid Corporation of China mandates GB-standard interoperability, eliminating vendor lock-in that previously slowed procurement decisions.
- Cellular:Direct-to-tower connectivity leveraging existing mobile operator infrastructure. Australian utilities prefer LTE-M and NB-IoT modules for rapid deployment in sparse regional networks where mesh density proves uneconomical. Telstra and Optus coverage maps directly influence rollout sequencing.
- PLC:Power line communication transmits data across existing electrical wiring, avoiding radio spectrum licensing entirely. Rural electrification zones in India deploy PLC where cellular towers remain distant and mesh node density cannot achieve critical mass.
- LoRaWAN:Unlicensed spectrum protocol enabling long-range, low-power transmission for isolated endpoints. Emerging deployments in Indonesian archipelago utilities leverage LoRaWAN for island grids where submarine fiber or cellular backhaul remains prohibitively expensive.
RF Mesh anchors the volume base while LoRaWAN gains share at the steepest rate as archipelago utilities seek connectivity without carrier dependency.
Application:
Customer type determines data granularity requirements and platform pricing tiers, with industrial accounts commanding 10x the per-endpoint software licensing fees of residential deployments due to complex tariff structures and sub-15-minute interval demands.
- Utilities:State-owned and privatized distribution companies managing millions of endpoints across generation, transmission, and retail functions. China's State Grid and Southern Power Grid operate the world's largest AMI backends, processing petabyte-scale interval streams for time-of-use pricing enforcement and non-technical loss detection.
- Industrial:Heavy manufacturing, data centers, and process industries requiring sub-minute metering for demand charge optimization and power quality monitoring. Japanese automotive plants under METI carbon mandates deploy dedicated data management instances with real-time transformer load balancing.
- Residential:Single-family and multi-unit dwellings with standardized 15-minute or hourly read intervals. India's Ujwal DISCOM Assurance Yojana (UDAY) reforms push state utilities toward residential AMI as a loss-reduction mechanism, though meter density in rural Bihar and Uttar Pradesh remains below urban thresholds.
- Commercial:Office buildings, retail chains, and hospitality properties with heterogeneous load profiles requiring tenant-level submetering. Singapore's Green Mark certification program drives commercial building owners toward granular consumption visibility for sustainability reporting.
Utilities dominate absolute endpoint counts while industrial applications generate the highest per-license revenue concentration.
Deployment Model:
Capital availability and cybersecurity risk tolerance segment procurement between ownership structures, with state-owned enterprises in China favoring on-premises control while Australian retailers outsource to operational expenditure models.
- On-Premises:Dedicated hardware and software stacks operated within utility-owned data centers. China's MIIT cybersecurity mandates for critical infrastructure operators reinforce preference for air-gapped systems in national grid programs.
- Cloud:Multi-tenant SaaS platforms hosted by hyperscale providers or specialized AMI vendors. Victorian retailers in Australia have migrated rapidly to cloud analytics engines as retail competition compresses technology refresh cycles and prioritizes opex flexibility.
- Hybrid:Split architectures retaining sensitive operational data on-premises while pushing analytics and regulatory reporting to cloud tiers. India's CEA-mandated DISCOMs increasingly evaluate hybrid configurations to balance data sovereignty with cost efficiency.
- Edge:Localized compute clusters at substation or feeder level for latency-critical applications. METI-funded demand response pilots in Japan deploy edge inference for sub-second distributed energy resource orchestration.
Hybrid configurations capture the largest new-contract share as utilities seek middle-ground risk postures.
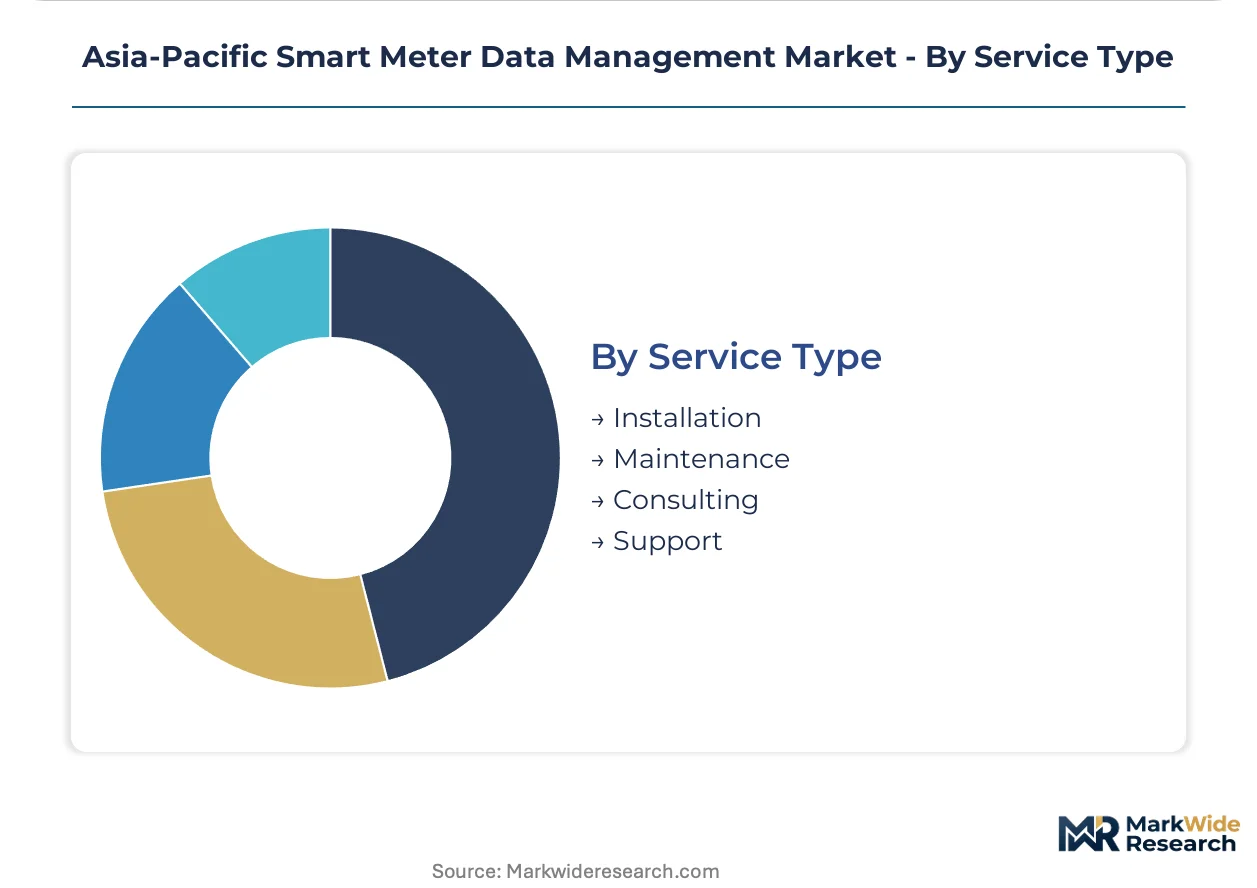
Service Type:
Revenue recurrence and margin profile vary sharply across the service spectrum, with consulting engagements delivering one-time fees and maintenance contracts generating multi-year recurring streams tied to endpoint counts.
- Installation:Physical meter deployment, network commissioning, and initial data validation. Large-scale AMI rollouts in Vietnam and Indonesia create surge demand for installation services as state utilities lack indigenous field deployment capacity.
- Maintenance:Ongoing firmware updates, network health monitoring, and hardware replacement programs. Australian interval metering mandates under the National Energy Retail Law institutionalize maintenance as a regulatory compliance function with defined service level agreements.
- Consulting:Platform architecture design, regulatory compliance mapping, and integration planning. India's Smart Cities Mission generates consulting demand for bundled metering, streetlight automation, and EV charging data platform design.
- Support:Help desk operations, cybersecurity patch management, and API maintenance for third-party aggregator access. CEA-mandated standardized data APIs in India transform support services into ongoing compliance obligations.
Maintenance contracts anchor recurring revenue stability while consulting engagements expand most quickly around new market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian retailers exhibit the sharpest price sensitivity, compressing procurement timelines to capture opex flexibility, while Chinese state-owned utilities absorb capital-intensive deployments with minimal budget elasticity. This demand-elasticity contrast shapes vendor pricing architectures across the region.
China
State Grid Corporation and Southern Power Grid process petabyte-scale interval streams for time-of-use pricing enforcement and non-technical loss detection. MIIT enforces GB standards for data interoperability and cybersecurity in national smart grid programs. Yangtze River Delta utilities deploy hybrid cloud-edge configurations to balance data sovereignty with analytics scalability.
India
DISCOMs under UDAY reforms push residential AMI as a loss-reduction mechanism, though meter density in rural Bihar and Uttar Pradesh remains below urban thresholds. CEA mandates AMI integration under the National Electricity Policy, requiring standardized data APIs for third-party aggregators. Maharashtra and Gujarat utilities lead platform procurement for bundled metering with streetlight automation.
Australia
Victorian and South Australian retailers migrate rapidly to cloud analytics engines as retail competition compresses technology refresh cycles. The National Energy Retail Law requires interval data accessibility, compelling investment in real-time analytics engines. Sydney and Melbourne distribution networks prioritize LTE-M and NB-IoT modules for sparse regional deployment.
Japan
Automotive plants under METI carbon mandates deploy dedicated data management instances with real-time transformer load balancing. METI incentives for demand response aggregation require distributed energy resource orchestration platforms with sub-second control loops. Kanto region utilities pilot edge inference for latency-critical grid applications.
Vietnam
State utility EVN lacks indigenous platform vendors, creating first-mover advantages for established AMI integrators. National grid modernization programs accelerate procurement of foreign-hosted cloud analytics. Ho Chi Minh City and Hanoi distribution zones concentrate early deployment of hybrid deployment architectures.
Asia-Pacific Smart Meter Data Management Market Competitive Landscape
Capability concentration sits with specialized firmware-to-cloud integrators; scale advantage sits with diversified industrial conglomerates with hybrid deployment expertise. The vendor base stratifies into three tiers: RF mesh specialists commanding dense urban corridors, analytics-heavy software vendors capturing recurring revenue from utility data lakes, and full-stack industrial groups bundling hardware with managed services. Dominant competitive moves include strategic partnerships between meter manufacturers and hyperscale cloud providers, plus portfolio diversification into edge-AI hardware-software bundles.
Within the analytics-tier, Oracle Corporation and Itron Inc. exemplify divergent positioning strategies. Oracle Corporation occupies a position emphasizing database depth and recurring licensing revenue from utility data lake architectures. Itron Inc. anchors the RF mesh integration segment, representing the firmware-to-cloud convergence archetype. Siemens AG sits within the industrial conglomerate tier, exemplifying hybrid deployment expertise across large-scale national grid programs. These three entities collectively illustrate how vendor archetypes map to distinct procurement priorities across state-owned, privatized, and competitive retail utility structures.
| Leading Market Players |
|---|
| Oracle Corporation |
| Itron Inc. |
| Siemens AG |
| ABB Group |
| Honeywell International |
| Trilliant Holdings |
| Landis+Gyr Group |
| Hubbell Incorporated |
| Hansen Technologies |
| Others |
Value Network & Pricing Analysis
The Shanghai-Singapore maritime corridor's container cost volatility directly shapes procurement economics for AMI hardware flowing into Southeast Asian utilities, compressing margins for system integrators while amplifying price differentiation between cloud-native and on-premises deployment tiers.
Pricing Analysis
Maintenance and firmware-update subscriptions generate lifetime value multiples exceeding initial license fees by factors of three to five across utility contracts. Three-tier pricing structure across premium, standard, and economy levels segments buyers by data latency requirements and cybersecurity certification depth. Pricing pressure stems from Australian retailers demanding opex flexibility under retail competition stress, forcing vendors toward subscription compression. State-owned Chinese utilities exhibit minimal price sensitivity, absorbing capital-intensive deployments with sovereign budget backing.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for RF chipset procurement, pushing vendors toward dual-vendor qualification. Semiconductor fabrication concentrates in Taiwan and South Korea, with RF module assembly drawing from Chinese contract manufacturers. Legacy SCADA protocol dependencies and proprietary middleware development cycles constitute the primary supply chain vulnerability. Distribution runs through direct utility procurement channels for national grid programs, supplemented by systems integrator intermediaries for mid-market municipal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face substitution pressure from hyperscale cloud providers bundling analytics infrastructure, demanding defensive architecture investments that deepen customer switching costs.
For Market Incumbents: Build data lake interoperability moats by embedding proprietary analytics APIs into utility operational workflows, neutralizing Oracle's database depth advantage. Deepen edge-AI hardware-software bundles to capture premium pricing in Japan's METI-funded demand response pilots. Anchor large-scale deployments through hybrid cloud-edge configurations that exploit Siemens' industrial integration expertise.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where Green Mark certification requirements in Singapore and Malaysia outpace incumbent platform customization capacity. Vietnam's EVN grid modernization lacks indigenous vendor relationships, creating first-mover procurement advantages. Target consulting-led platform architecture engagements that precede long-term maintenance contracts.
For Investors and Strategic Acquirers: Firmware-to-cloud integration specialists with proven GB-standard interoperability credentials command scarcity premiums as China's AMI procurement accelerates. Long-term viability hinges on recurring revenue concentration exceeding sixty percent of total bookings. Monitor CEA-mandated API standardization enforcement in India as inflection signal for modular platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Hardware-Software Bundle Development | Captures premium pricing in Japan's METI-funded sub-second demand response orchestration pilots. |
| GB-Standard Interoperability Certification | Unlocks State Grid Corporation procurement eligibility under MIIT cybersecurity mandates. |
| Hybrid Cloud-Edge Deployment Architecture | Balances data sovereignty requirements with analytics scalability for India's CEA-mandated DISCOMs. |
| Subscription-Based Platform Licensing | Aligns with Australian retailer opex preferences under National Energy Retail Law interval data mandates. |
| RF Mesh Network Commissioning Partnership | Addresses Vietnam and Indonesia's indigenous field deployment capacity gaps in national grid programs. |
Research Methodology
The analysis maps AMI platform vendors, utility procurement officers, and systems integrators, each validated through primary interviews with utility planning officers, AMI platform engineers, EPC contractors, and regulatory compliance specialists. Secondary sources include CEA circulars, MIIT GB standard documentation, Australian Energy Regulator determinations, and utility annual procurement disclosures. Bottom-up endpoint deployment tracking triangulates against top-down market sizing from national smart grid program budgets.
Assumptions held fixed include regulatory mandate enforcement timelines and cellular generation evolution cycles, while variables included DISCOM fiscal health indices and semiconductor supply normalization trajectories. Segmentation modeled deployment model, connectivity architecture, customer type, and regional regulatory framework clusters. CAGRs derived from utility capital expenditure forecasts and platform licensing renewal rates, with edge-AI hardware attach rates and cloud migration velocity as industry-specific sensitivity inputs.
Practitioners should monitor CEA API standardization enforcement delays and ASEAN cybersecurity regulation fragmentation for early signals of platform procurement timeline compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Asia Pacific Water Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Home Energy Monitor Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Digital Water Meters Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
US Water Meter Market
Smart Meters
AMI Smart Water Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
South and Central America Smart Metering Market