
 Smart Meter Data Management Market | 2026-2036
Smart Meter Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Meter Data Management Market Analysis
Commercial and industrial energy buyers are reorganizing procurement priorities around real-time visibility, pulling investment away from legacy residential-only deployments. Itron leverages its end-to-end AMI platform to anchor large-scale utility rollouts across multiple continents. Oracle Corporation competes through cloud-native data architectures that integrate billing and grid analytics. Landis+Gyr specializes in RF mesh communication modules that sustain high-volume meter data throughput.
Smart Meter Data Management encompasses the software, communication infrastructure, and analytics platforms that collect, validate, store, and process interval-level consumption data from advanced metering infrastructure. Core systems must handle 15-minute to hourly read frequencies across millions of endpoints while ensuring data integrity for billing settlement and grid operations. Data analytics software and cloud solutions command the strongest margin pools as utilities shift from on-premise servers to scalable architectures. Energy management and demand response applications are expanding fastest as distributed energy resources and time-of-use tariffs proliferate.
FERC Order 2222 in the US, the EU Green Deal framework, and GDPR data-handling requirements collectively shape product roadmaps and market access conditions for platform vendors. Compliance with FERC's distributed resource aggregation mandates forces MDMS providers to embed real-time dispatch interfaces, while GDPR constrains cross-border data residency architectures. Stakeholders must decide whether to build in-house analytics stacks or outsource to specialized platform vendors as meter data volumes and regulatory complexity intensify.
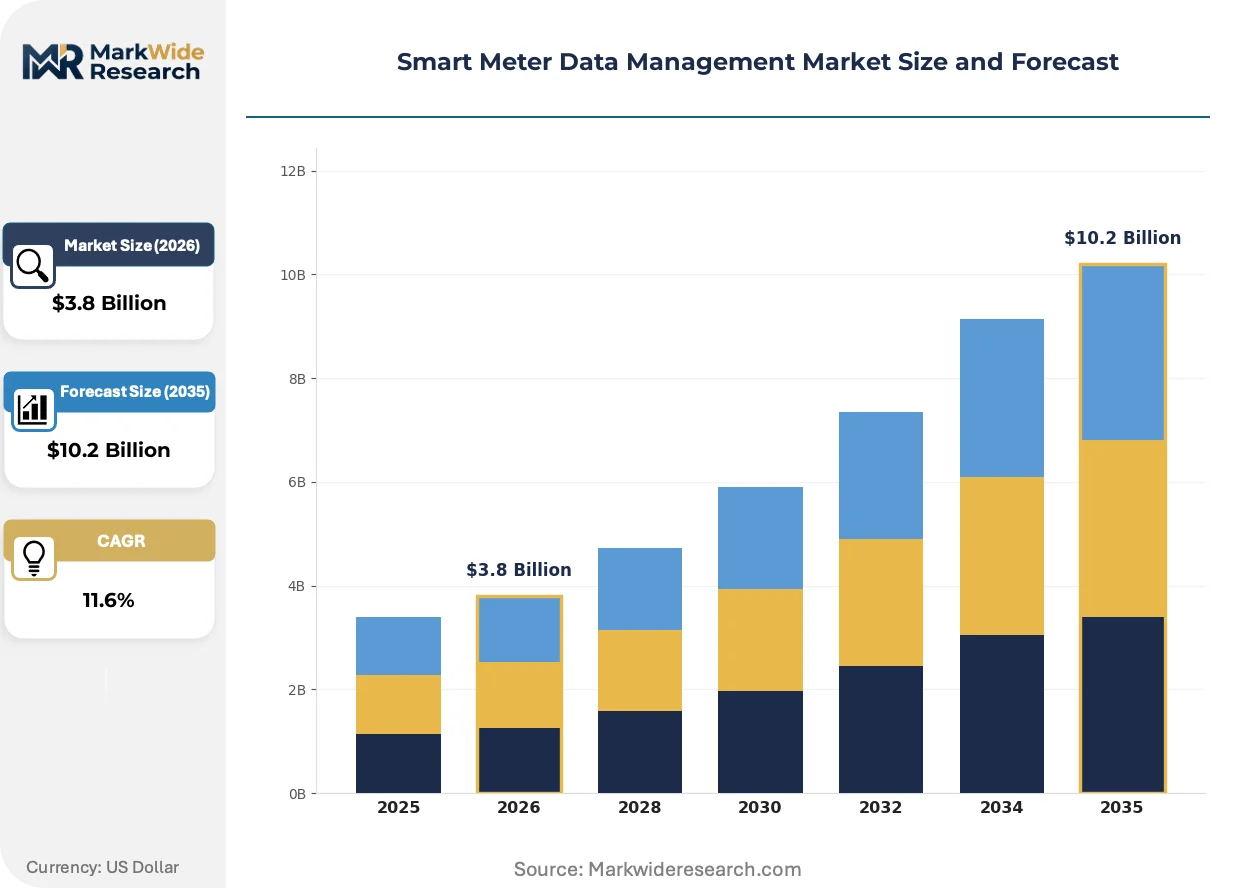
Market Dynamics
Cloud-native data architectures are compressing deployment timelines for utilities while fragmenting vendor competitive positions between legacy on-premise incumbents and API-first challengers.
Growth Catalysts
- FERC Order 2222:US utilities must enable distributed resource aggregation interfaces, forcing MDMS upgrades that embed real-time dispatch capabilities for battery and solar fleets.
- Industrial energy buyers:Manufacturing and data center operators now mandate sub-hourly consumption visibility to optimize time-of-use tariffs and demand charge avoidance.
- RF mesh throughput gains:Second-generation communication modules sustain 15-minute interval reads across dense urban endpoint populations without cellular backhaul dependency.
Market Restraints
- Semiconductor supply concentration:RF transceiver and power management chip sourcing remains concentrated among Taiwanese and South Korean foundries, exposing deployment schedules to foundry allocation cycles.
- GDPR data residency:Cross-border meter data replication between EU member states requires jurisdictional storage partitioning that inflates cloud infrastructure costs.
- Legacy billing system entrenchment:Utilities with 1990s-era CIS platforms face API incompatibility that blocks native MDMS integration without middleware investments.
Strategic Opportunities
- India smart grid acceleration:The country's national smart grid mission targets 250 million smart meters by 2026, creating greenfield deployment opportunities without legacy system drag.
- EV charging load forecasting:Converging MDMS data with EV telematics enables distribution utilities to predict transformer-level congestion before capacity violations trigger outages.
- EU Green Deal carbon accounting:Granular interval data becomes mandatory input for Scope 2 emissions reporting, expanding MDMS addressable market into enterprise sustainability software budgets.
Industry Challenges
- Data engineering talent scarcity:Utilities compete with technology firms for pipeline architects capable of processing petabyte-scale time-series streams with sub-second latency requirements.
- Cybersecurity certification timelines:IEC 62351 compliance for cryptographic key management adds 12-18 month validation cycles to product release schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Meter Data Management Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Data Analytics Software, Communication Modules, Cloud Solutions End User: Utilities, Residential Users, Commercial Users, Industrial Users Technology: IoT, RFID, Zigbee, Wi-Fi Application: Energy Management, Billing Automation, Demand Response, Data Visualization |
| Companies Covered | Schneider Electric, Honeywell International (Elster Group), Itron, General Electric, ABB Ltd., Landis+Gyr, Oracle Corporation, Aclara Technologies, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Meter Data Management Market Emerging Trajectories
Edge computing architectures are redistributing analytics workloads from centralized cloud servers to substation-level gateways, altering latency economics and vendor value capture points.
Apache Kafka and time-series databases are supplanting traditional relational data warehouses as the ingestion layer for interval meter streams. Mid-size municipal utilities in Germany and Australia have migrated 80% of operational analytics to these platforms. The shift is compressing total cost of ownership for data infrastructure by eliminating per-core licensing fees.
EU CSRD sustainability reporting mandates now require auditable energy consumption trails at facility level. Industrial facility operators in France and Italy are retrofitting MDMS connections to automate Scope 2 emissions calculations. Software vendors are embedding carbon intensity APIs that map grid marginal emissions to 15-minute consumption intervals.
Energy retailers are unbundling analytics services from commodity supply contracts, selling consumption insights as standalone subscriptions. Large commercial buyers in Spain and the UK now procure visibility dashboards separately from electrons. This channel shift is squeezing integrated utility margins while expanding pure-play software vendor addressable market.
Smart Meter Data Management Market Segmentation
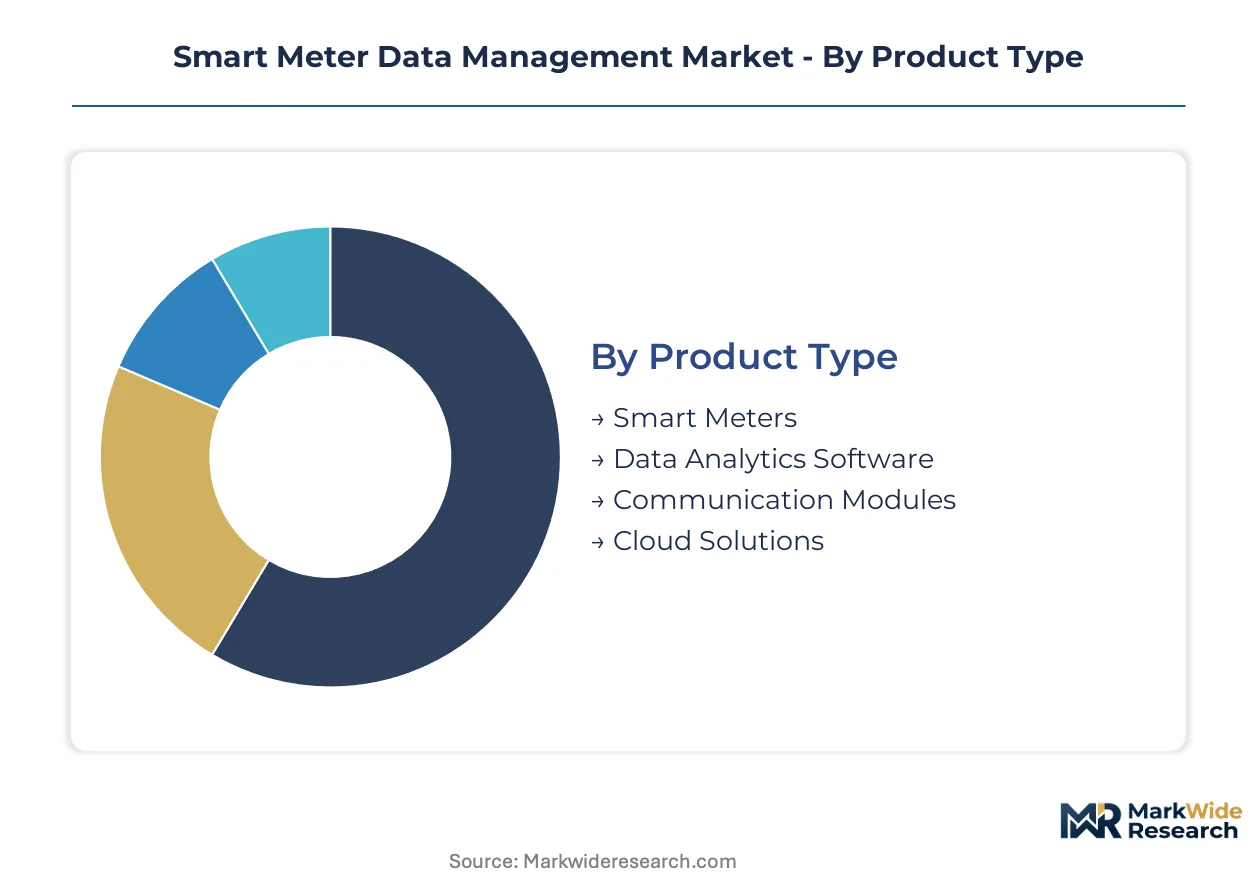
Segmentation in Smart Meter Data Management reflects divergent regulatory pressures across jurisdictions and the technical requirements imposed by interval read frequencies. Product architecture choices cascade through deployment economics and compliance posture.
Product Type:
FERC Order 2222 and EU CSRD disclosure mandates create divergent hardware-software investment priorities for utilities operating under each regime.
- Smart Meters:Interval-capable endpoints with 15-minute to hourly read frequencies form the physical data source layer. US utilities under FERC jurisdiction prioritize meters with embedded distributed resource aggregation interfaces for battery and solar fleet dispatch. European deployments emphasize GDPR-compliant local data processing to minimize cross-border residency violations.
- Data Analytics Software:Platforms that validate, cleanse, and transform raw interval streams into billing-grade and operational datasets. German municipal utilities and Australian distributors have migrated 80% of operational workloads to Apache Kafka and time-series databases, eliminating per-core licensing costs. Industrial energy buyers in Spain and the UK now procure visibility dashboards as standalone subscriptions separate from commodity supply.
- Communication Modules:RF mesh and cellular backhaul hardware sustaining endpoint-to-headend data throughput.
- Cloud Solutions:Scalable architectures replacing on-premise server infrastructure for meter data management.
Data analytics software handles the majority of throughput; cloud solutions are gaining share fastest as utilities exit capital-intensive server ownership.
End User:
Procurement authority and data granularity requirements split the market between regulated utilities and unbundled energy buyers.
- Utilities:Vertically integrated and distribution-only operators responsible for AMI deployment, data custody, and regulatory compliance. US investor-owned utilities face FERC Order 2222 upgrade mandates requiring real-time dispatch interfaces. European utilities navigate GDPR jurisdictional storage partitioning that inflates cloud infrastructure costs across member states.
- Residential Users:Household consumers receiving interval data through utility portals or third-party energy service companies. Time-of-use tariff proliferation and distributed solar net metering create demand for consumption visibility in California, Italy, and Australia.
- Commercial Users:Office buildings, retail chains, and institutional facilities optimizing demand charges and sustainability reporting.
- Industrial Users:Manufacturing and data center operators mandating sub-hourly visibility for tariff optimization and Scope 2 emissions automation.
Utilities retain custody of the endpoint population; industrial users are expanding their share of analytics software spend most rapidly.
Technology:
Communication protocol selection determines coverage economics, latency performance, and cybersecurity certification burden.
- IoT:IP-based connectivity stacks enabling direct cloud integration and over-the-air firmware management. Cellular IoT modules bypass RF mesh infrastructure requirements in sparse rural deployments across the US Great Plains and Australian Outback. IEC 62351 cryptographic compliance adds validation cycles that extend product release timelines.
- RFID:Legacy passive tagging systems for asset tracking and field inventory management.
- Zigbee:Mesh networking protocol for dense urban endpoint populations with low power requirements.
- Wi-Fi:High-bandwidth connectivity for commercial and industrial gateway aggregation points.
IoT carries the deployment volume in greenfield markets; Zigbee maintains installed base dominance in mature European urban networks.
Application:
Functional use cases align with regulatory mandates and tariff structure evolution.
- Energy Management:Real-time consumption monitoring and automated load control for demand charge minimization. EU CSRD sustainability reporting mandates now require auditable energy consumption trails at facility level, driving retrofit MDMS connections in France and Italy. Carbon intensity APIs map grid marginal emissions to 15-minute intervals for automated Scope 2 calculations.
- Billing Automation:Settlement-grade data validation and time-of-use tariff calculation. Legacy 1990s-era CIS platforms in US municipal utilities block native MDMS integration without middleware investment.
- Demand Response:Automated load curtailment and distributed resource dispatch for grid stability.
- Data Visualization:Dashboard and reporting interfaces for operational and customer-facing analytics.
Billing automation processes the transaction volume; energy management is climbing the fastest on software vendor revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Baltic electricity interconnectors and North Sea offshore grid infrastructure position Germany as the data throughput hub for European smart meter aggregation, while the Texas ERCOT grid's islanded architecture drives US investment in real-time dispatch systems.
United States
Data center load growth in Northern Virginia and Arizona is forcing utilities to deploy sub-15-minute interval metering for transformer-level congestion forecasting. FERC Order 2222 mandates distributed resource aggregation interfaces that embed battery and solar fleet dispatch capabilities into MDMS platforms. Investor-owned utilities across Texas and California are retrofitting legacy CIS installations to comply.
Germany
Municipal utilities in Bavaria and North Rhine-Westphalia have migrated 80% of operational analytics to Apache Kafka and time-series databases, eliminating per-core licensing costs. The EU CSRD disclosure framework requires auditable energy consumption trails at facility level, driving retrofit MDMS connections in industrial clusters around Stuttgart and Munich. GDPR jurisdictional storage partitioning inflates cloud infrastructure costs across federal states.
India
The national smart grid mission targets 250 million smart meters by 2026, creating greenfield deployment opportunities without legacy system drag in Maharashtra and Gujarat. Central Electricity Authority mandates for interval metering in commercial and industrial segments are accelerating procurement in the Delhi-Mumbai Industrial Corridor. State distribution companies in Karnataka and Tamil Nadu are issuing tenders for cloud-native MDMS platforms.
United Kingdom
The Data Communications Company infrastructure underwrites nationwide smart meter connectivity, with energy retailers unbundling analytics services from commodity supply contracts in London and the Southeast. Industrial facility operators in the Midlands are retrofitting MDMS connections to automate Scope 2 emissions calculations under evolving sustainability disclosure requirements. Scottish Power and other vertically integrated utilities are expanding AMI deployments across urban endpoint populations.
Australia
The National Electricity Market's five-minute settlement rule is compressing interval read frequencies across Victoria and New South Wales, driving demand for high-throughput RF mesh modules. AEMO's distributed energy resource integration frameworks require real-time dispatch interfaces for battery and solar fleet aggregation. Mid-size municipal utilities in Queensland have migrated operational analytics to cloud-native architectures, compressing total cost of ownership.
Smart Meter Data Management Market Vendor Landscape
Listed leaders compete with private specialists across platform architecture choices, with publicly traded technology conglomerates facing pressure from API-first challengers that bypass traditional on-premise licensing models. The vendor base stratifies between legacy infrastructure incumbents with embedded utility relationships and cloud-native entrants targeting greenfield deployments. Three archetypes dominate: end-to-end AMI platform providers, specialized data analytics software vendors, and communication module manufacturers with RF mesh expertise. Competitive moves concentrate on strategic partnerships with cloud hyperscalers and vertical integration into edge computing hardware.
Within the end-to-end platform tier, Itron and Landis+Gyr exemplify integrated providers that anchor large-scale utility rollouts across multiple continents, while Oracle Corporation occupies a position among cloud-native specialists competing through scalable data architectures that integrate billing and grid analytics. These three entities represent divergent strategic postures—hardware-centric integration versus software-centric service unbundling—that are reshaping competitive positioning as utilities exit capital-intensive server ownership.
| Leading Market Players |
|---|
| Schneider Electric |
| Honeywell International (Elster Group) |
| Itron |
| General Electric |
| ABB Ltd. |
| Landis+Gyr |
| Oracle Corporation |
| Aclara Technologies |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Twenty-four-week lead times for RF transceiver silicon concentrate procurement leverage among Taiwanese foundries, compressing margin pools for meter manufacturers while amplifying pricing power among semiconductor suppliers serving the MDMS ecosystem.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the MDMS landscape, with premium tiers capturing utilities demanding FERC Order 2222-compliant real-time dispatch interfaces and economy tiers serving municipal utilities with basic interval billing needs. Price differentiation hinges on certification grade—IEC 62351 cryptographic compliance adds substantial validation costs—and volume scale, with multi-utility procurement consortia securing steep discounts. Pricing pressure stems from cloud-native entrants undercutting legacy on-premise licensing models with API-first subscription economics. Industrial energy buyers exhibit the highest price sensitivity, while vertically integrated utilities with captive IT budgets demonstrate the least.
Supply Chain Analysis
Inventory buffers for power management integrated circuits and RF modules have compressed to six-to-eight weeks across Tier 1 meter manufacturers, exposing deployment schedules to foundry allocation volatility. Component sourcing draws from Taiwan, South Korea, and China for RF transceivers, power management chips, and cellular modems. Supply chain risk centers on single-source vulnerability for advanced RF mesh chipsets where Qualcomm and Silicon Labs dominate. Distribution runs through direct OEM relationships with utilities and energy retailers, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart Meter Data Management represents a high-growth disruption as cloud-native architectures displace capital-intensive on-premise deployments, with FERC Order 2222 mandating real-time distributed resource aggregation interfaces that legacy platforms cannot satisfy.
For Market Incumbents: Fortify embedded utility relationships through backward integration into edge computing hardware, capturing substation-level analytics workloads that API-first challengers cannot reach. Prioritize IEC 62351 certification investment to extend validation timelines as a defensive moat against cloud-native entrants. Consolidate around AMI platform stickiness while cloud competitors struggle with CIS integration complexity.
For New Entrants and Emerging Players: IEC 62351 fast-track certification programs open immediate addressability among US municipal utilities facing FERC upgrade mandates with limited internal cybersecurity expertise. Target India's greenfield smart grid mission in Maharashtra and Gujarat, where legacy system drag is absent and cloud-native architectures face no incumbent displacement burden. Lead with consumption-insight subscriptions unbundled from commodity supply, mirroring Spanish and UK energy retailer channel shifts.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with stranded AMI hardware divisions lacking cloud analytics software capabilities. Long-term viability favors vendors controlling both RF mesh communication modules and data analytics software layers. Watch for AEMO distributed energy resource integration framework adoption in Australia as signal of real-time dispatch interface standardization spreading beyond US FERC jurisdiction.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Apache Kafka and time-series database adoption eliminates per-core licensing costs for German municipal utilities. |
| Edge Computing Hardware Integration | Substation-level gateway deployment captures latency-sensitive analytics workloads from centralized cloud servers. |
| IEC 62351 Certification Investment | Cryptographic key management compliance extends product release timelines while blocking unvalidated competitors. |
| RF Mesh Module Capacity Expansion | Second-generation communication hardware sustains 15-minute interval reads across dense urban endpoint populations. |
| Carbon Intensity API Development | EU CSRD Scope 2 automation requirements expand MDMS addressable market into enterprise sustainability software budgets. |
Methodological Framework
A spread of perspectives from utility planning officers, AMI platform engineers, energy retailer procurement leads, and grid operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against FERC filings, EIA smart grid deployment databases, EU Green Deal implementation trackers, and IEC standardization committee documentation. Bottom-up triangulation of meter deployment pipelines and top-down reconciliation against national smart grid mission targets anchored volume estimates.
Segmentation dimensions modeled span product type, end user archetype, communication technology protocol, and functional application across the projection horizon. CAGRs derive from utility capital expenditure trajectories and cloud infrastructure spend patterns. Forecast inputs incorporate interval read frequency compression timelines and distributed energy resource penetration curves by grid operator territory.
Decision-makers should treat outputs as directional under base assumptions of sustained FERC Order 2222 implementation and EU CSRD disclosure enforcement; material deviation in regulatory timelines or semiconductor supply normalization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
North America Gas Meter Market
Smart Meters
Smart Metering Systems Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
LNG Metering Skids Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Gas Meters Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Water Meter Market
Smart Meters
US Water Meter Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
Power Metering Market
Smart Meters
Global Digital Power Meter Market