
 Water Meter Market | 2026-2036
Water Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Water Meter Market Intelligence
Subscription-based data analytics for water management is hardening the value proposition beyond the initial hardware sale. Itron leverages its extensive software platforms to secure recurring revenue streams from utilities. Sensus differentiates with its FlexNet communication network for reliable data transmission. Meanwhile, Badger Meter competes by offering integrated solutions combining meters, software, and network infrastructure.
A water meter is a device that measures the volume of water used by consumers, operating on principles like electromagnetic induction or ultrasonic transit time. Its primary purpose is to provide accurate flow data for billing and resource management, with precision governed by standards like ISO 4064. While Mechanical meters maintain a large installed base, new deployments favor Ultrasonic and Smart meter types for their superior accuracy and remote reading capabilities. Municipal Water Supply applications constitute the largest segment, driven by utility-led non-revenue water reduction programs.
The European Union's Measuring Instruments Directive (MID) mandates specific accuracy standards, shaping product design for market access in Europe. Concurrently, regulations from bodies like the U.S. EPA influence utility procurement by promoting water conservation and accurate billing. The ability to navigate these varied international standards, including ISO 4064, is critical for market participants. Ultimately, vendor success is contingent on integrating hardware with secure, interoperable data platforms that meet diverse regulatory requirements.
Market Dynamics
The fundamental shift from one-time hardware sales to recurring revenue from data analytics services is the central force shaping the water meter market. This transition is driven by municipal adoption of smart metering infrastructure for enhanced operational efficiency and resource management.
Growth Catalysts
- Non-Revenue Water Reduction Mandates:Government initiatives like India's Jal Jeevan Mission compel utilities to install accurate meters for leak detection and conservation, driving large-scale deployments in rapidly urbanizing regions.
- Ultrasonic Technology Advancement:Solid-state ultrasonic meters offer superior accuracy, no moving parts, and longer lifespans compared to mechanical counterparts, encouraging their adoption in new residential and commercial projects.
- Urban Infrastructure Modernization:Aging water supply networks in developed nations and new construction in developing economies necessitate upgrades, creating sustained demand for advanced metering solutions that support smart city frameworks.
Market Restraints
- High Initial Capital Outlay:The significant upfront investment required for Advanced Metering Infrastructure (AMI), including meters, communication networks, and software, deters budget-constrained municipalities and smaller utilities.
- Long Replacement Cycles:The extensive installed base of functional mechanical meters, which have operational lifespans of 15-20 years, slows the adoption rate of newer, smarter technologies.
- Network Interoperability Issues:A lack of standardization across communication protocols and data platforms creates integration challenges for utilities attempting to use equipment and software from multiple vendors.
Strategic Opportunities
- Agricultural Water Management:Developing ruggedized, large-volume meters for irrigation applications presents a significant growth avenue, particularly in water-scarce agricultural regions seeking to optimize water use.
- AI-Powered Predictive Analytics:Offering software-as-a-service platforms that use artificial intelligence for predictive leak detection and demand forecasting creates new, high-margin recurring revenue streams beyond hardware.
- Expansion in Southeast Asia:Markets like Vietnam and Indonesia, facing rapid urbanization and increasing water stress, represent underpenetrated regions for smart water metering deployments.
Industry Challenges
- Skilled Technician Scarcity:A shortage of technicians trained in radio frequency network installation, data analytics, and smart meter maintenance impedes the efficient rollout of large-scale AMI projects.
- Legacy System Integration:Integrating modern meter data management platforms with older utility billing and customer information systems is complex, costly, and a frequent source of project delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Meter Market |
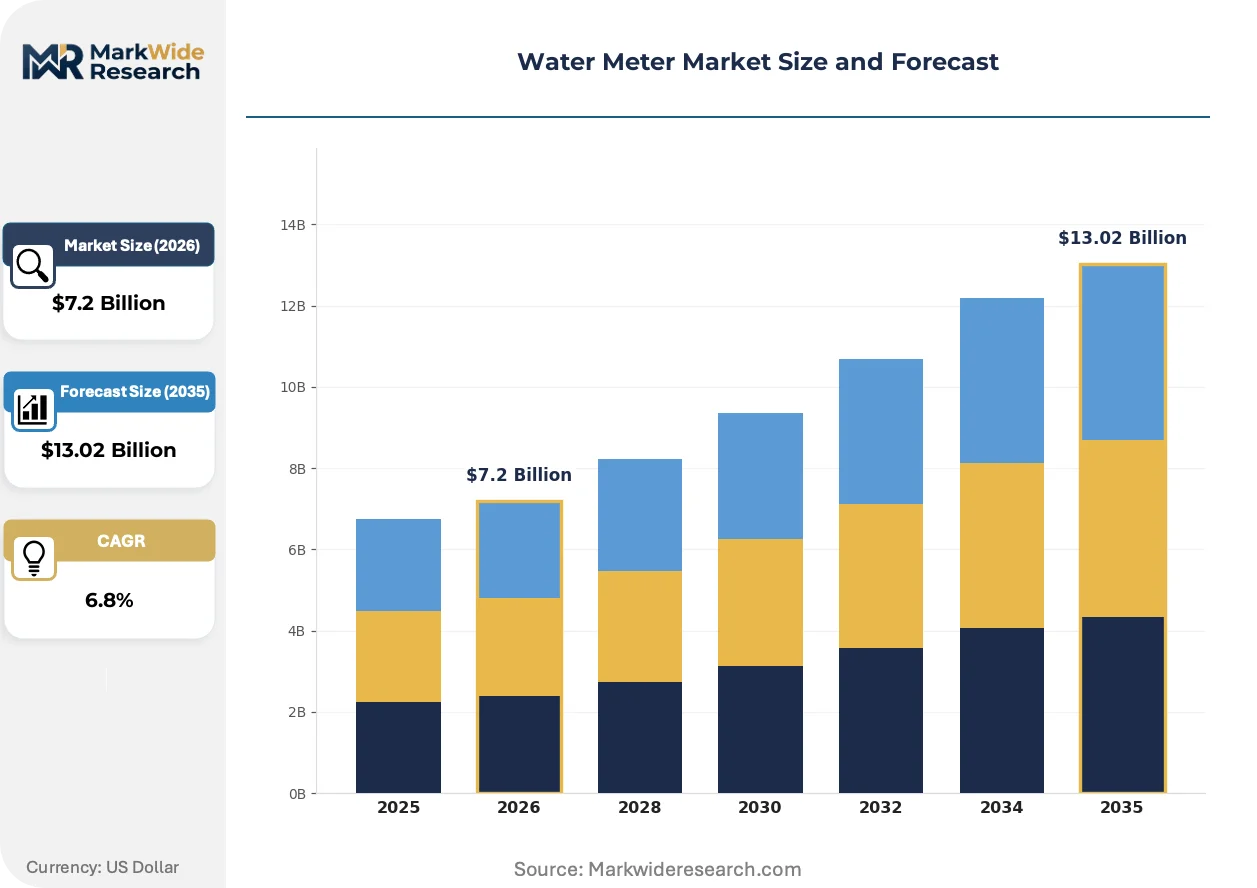
| Market Size in 2026 | $7.2 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Ultrasonic, Mechanical, Smart, Static Technology: Analog, Digital, Remote Reading, IoT Enabled, Wireless Application: Residential Buildings, Commercial Facilities, Irrigation Systems, Municipal Water Supply, Industrial Plants End User: Water Utilities, Property Managers, Agricultural Producers, Manufacturing Units, Infrastructure Developers |
| Companies Covered | Badger Meter, Diehl Metering, Sensus, Itron, Neptune Technology Group, Honeywell International, Landis+Gyr, Kamstrup, Mueller Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Meter Market Strategic Shifts & Innovations
Intelligence infused into hardware and the subsequent creation of data-centric business models defines the market's evolution. This transforms the meter from a simple measurement device into an active node within a broader digital utility network, enabling proactive resource management.
Edge computing integrates data processing capabilities directly within the smart water meter itself. Utilities are adopting this technology to analyze flow data locally, reducing the need to transmit vast amounts of raw data to a central server. This onboard intelligence is automating real-time alerts for leaks, backflow, and potential tampering, enabling faster utility response without constant cloud communication.
Regulatory frameworks like the European Union’s Measuring Instruments Directive (MID) impose strict accuracy and reliability standards that all meters used for billing must meet. This regulation forces manufacturers to invest in advanced calibration and long-term performance testing to secure CE marking for market access. Ultrasonic and electromagnetic meter designs are particularly impacted, as they must prove their measurement stability over their entire operational lifespan.
A notable behavioral shift involves utilities moving toward subscription-based procurement for data and network management services. This model unbundles the hardware sale from ongoing analytics, allowing utilities to pay a recurring fee for software updates, network maintenance, and data security. This trend is gaining traction primarily in North American and European markets where operational expenditure models are favored over large capital outlays.
Water Meter Market Segmentation
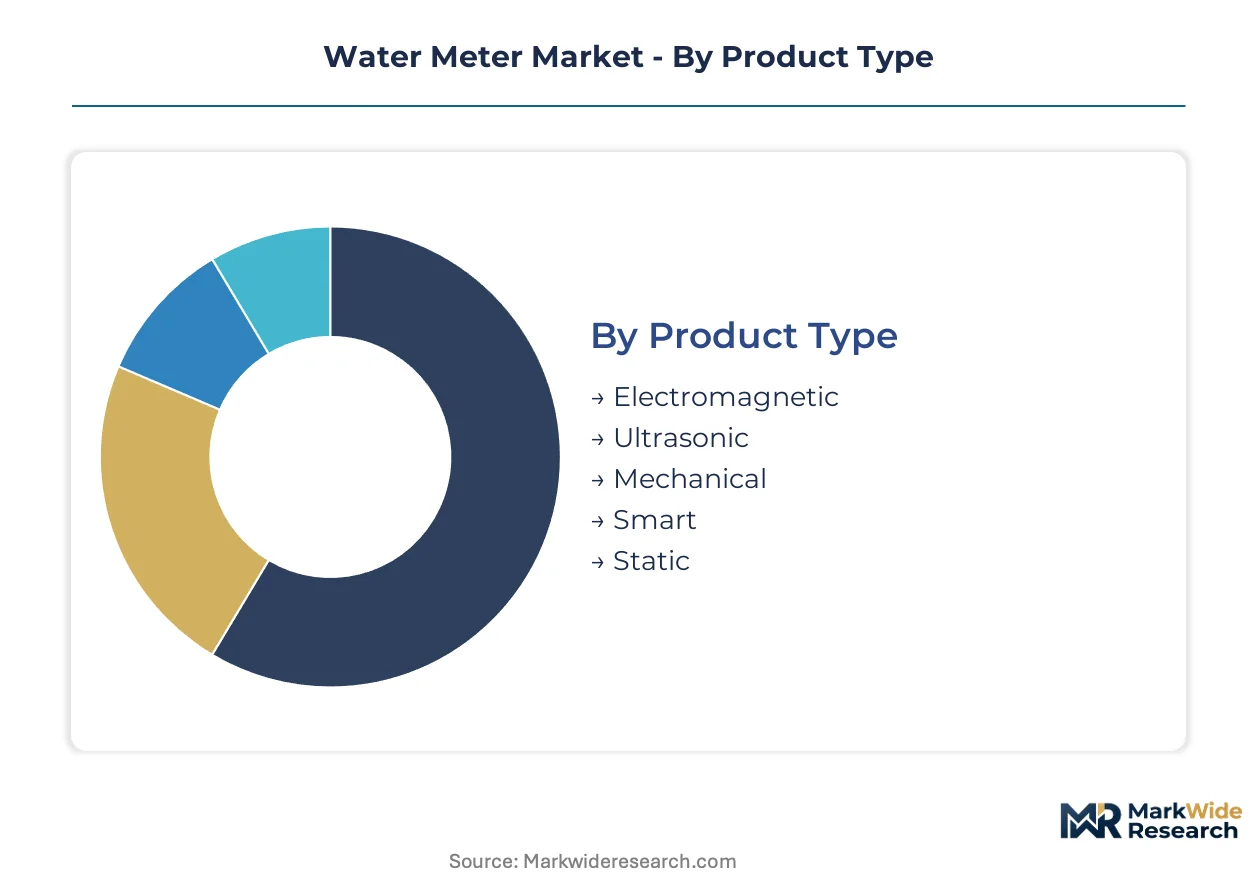
Understanding the diverse segments within the water meter market is crucial for identifying precise growth avenues and tailoring product development. This detailed segmentation highlights how different meter types, technologies, applications, and end-users influence market dynamics. Pinpointing specific areas of concentration allows for targeted strategic planning.
Product Type:
The product type segmentation reveals a spectrum from standalone measurement devices to deeply integrated smart network components.
- Ultrasonic:These meters utilize sound waves to measure water flow, offering high accuracy and no moving parts, which reduces wear and tear. Demand concentrates in new residential and commercial projects, driven by the need for precise billing and long-term reliability.
- Smart:Smart meters integrate advanced communication modules for remote data transmission, often forming part of an Advanced Metering Infrastructure (AMI). Utility-led non-revenue water reduction programs in rapidly urbanizing areas are driving significant deployments.
- Electromagnetic:Electromagnetic meters measure flow by detecting voltage induced in water passing through a magnetic field, primarily used in industrial and large-volume applications.
- Mechanical:Mechanical meters use impellers or turbines to measure water volume, representing a vast installed base, particularly in older residential and commercial properties.
- Static:Static meters, including ultrasonic and electromagnetic types, lack moving parts, providing enhanced durability and consistent measurement accuracy over time.
Mechanical meters lead volumes today; Smart meters are gaining share fastest.
Technology:
Technology segmentation illustrates the evolution from traditional measurement methods to advanced, interconnected systems.
- IoT Enabled:These technologies embed meters with sensors and communication modules that connect to the internet, enabling real-time data collection and predictive analytics. Demand is concentrating in smart city initiatives and large utility networks seeking comprehensive water management solutions.
- Remote Reading:Remote reading technologies allow utilities to collect meter data without physical site visits, significantly improving operational efficiency and billing accuracy. This capability is crucial for utility modernization projects across North America and Europe.
- Digital:Digital meters convert flow measurements into electronic signals, providing greater precision and compatibility with modern data processing systems than analog counterparts.
- Wireless:Wireless technologies facilitate data transmission from meters to collection points using various radio protocols, reducing infrastructure costs for utilities.
- Analog:Analog meters represent older technology, typically requiring manual readings and offering basic mechanical measurement of water consumption.
The market is witnessing a fundamental shift from Analog to IoT Enabled technologies.
Application:
Application segmentation highlights varying demand scales and specific operational requirements across different end-use environments.
- Municipal Water Supply:This application involves meters deployed by public utilities for billing and managing water distribution networks to entire communities. Non-revenue water reduction mandates, particularly in India, are driving substantial investments in this segment.
- Residential Buildings:Meters are installed in individual homes and multi-unit dwellings to measure household water consumption for billing and conservation efforts. Urbanization and housing development in Southeast Asia are creating significant new installation opportunities.
- Commercial Facilities:Meters in commercial properties like offices, retail spaces, and hotels enable precise billing and water usage monitoring for operational efficiency.
- Industrial Plants:Meters in manufacturing and processing facilities manage water intake and discharge, crucial for regulatory compliance and operational cost control.
- Irrigation Systems:These applications involve robust meters designed for agricultural settings to optimize water usage in crop production, particularly in water-stressed regions.
Municipal Water Supply remains the dominant segment; Irrigation Systems are gaining emerging importance for resource optimization.
End User:
End user segmentation delineates distinct procurement drivers and operational priorities shaping meter adoption.
- Water Utilities:These public and private entities are the primary purchasers, implementing large-scale metering programs for billing, leak detection, and network management. Regulatory pressures from bodies like the U.S. EPA compel utilities to invest in accurate metering for conservation.
- Infrastructure Developers:Developers integrate water meters into new residential, commercial, and industrial projects, often favoring smart meter technology for modern building standards. Rapid urbanization in markets like Vietnam is a key driver for this segment.
- Property Managers:Property managers deploy meters in multi-tenant buildings for sub-metering, enabling individual billing and monitoring of water consumption.
- Manufacturing Units:Manufacturing units procure meters to monitor water usage in production processes, ensuring efficiency and compliance with environmental regulations.
- Agricultural Producers:Agricultural producers utilize specialized meters to manage irrigation water, optimizing crop yield while minimizing water waste in farming operations.
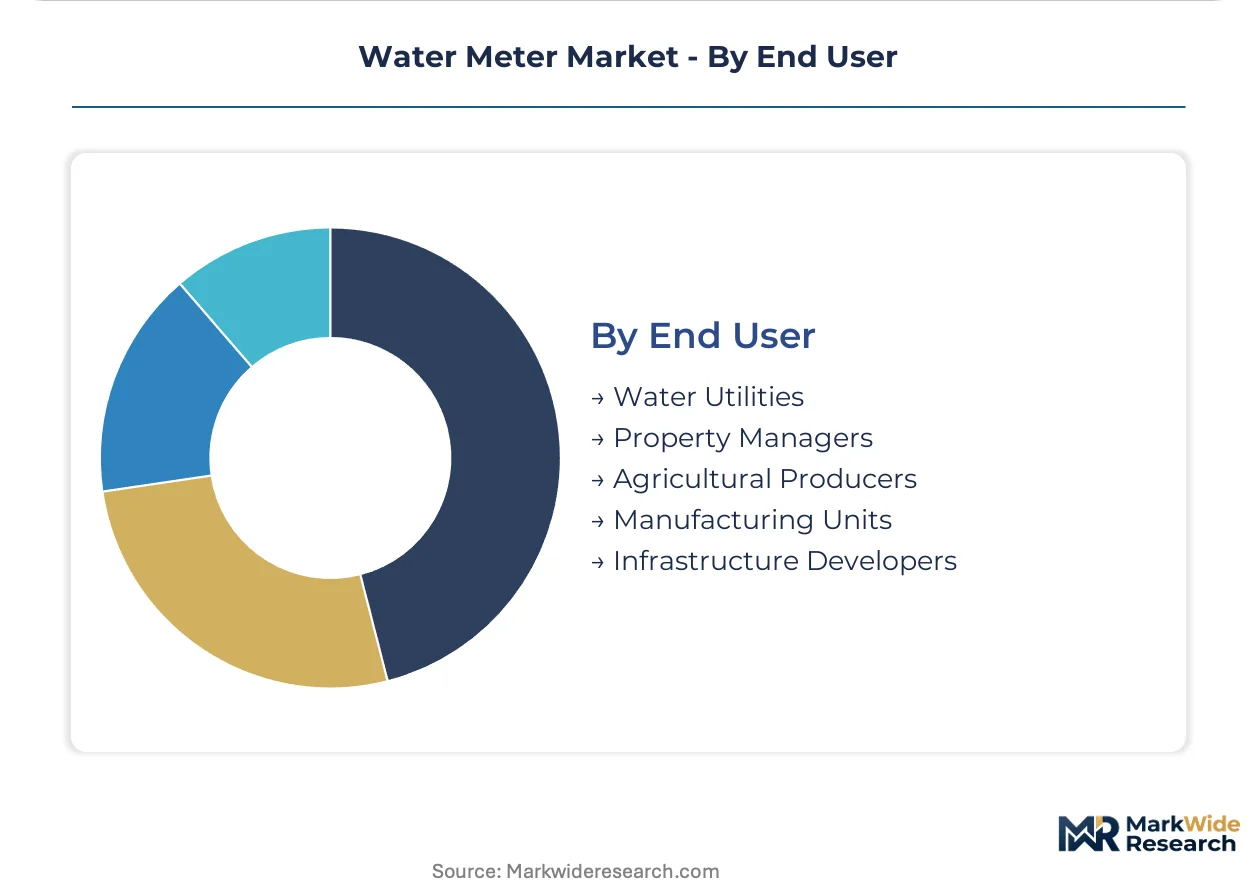
Water Utilities represent the largest consumer base; Infrastructure Developers are expanding their needs with new constructions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's aggressive push for water infrastructure upgrades contrasts with the United States' focus on modernizing aging networks. The former emphasizes new deployments for basic access, while the latter prioritizes smart technologies for efficiency. Both countries, however, share a common goal of reducing non-revenue water through advanced metering solutions.
India
Demand for water meters in India stems from rapid urbanization and the expansion of piped water supply to rural areas. The Jal Jeevan Mission, a government initiative, drives large-scale installations across the country. Major deployments are concentrating in rapidly developing urban centers like Delhi-NCR and Mumbai, where new infrastructure projects are underway.
United States
The United States market is characterized by the replacement and upgrade of aging water infrastructure, particularly in established municipal systems. Regulations from the U.S. EPA promote water conservation and accurate billing, compelling utilities to adopt modern metering. Utility-led modernization programs are prominent in states like California and Texas, focusing on smart meter integration.
Germany
Germany exhibits strong demand for high-accuracy and long-lifecycle water meters, aligning with stringent European standards. The European Union's Measuring Instruments Directive (MID) mandates specific accuracy for billing, influencing product design for manufacturers. Industrial clusters in Bavaria and North Rhine-Westphalia are key areas for advanced meter adoption in commercial and industrial settings.
Vietnam
Rapid urbanization and new construction projects in Vietnam are creating substantial opportunities for water meter deployments. Government initiatives to improve public utility services are driving investment in metering infrastructure. Major cities such as Ho Chi Minh City and Hanoi are experiencing significant new installations in residential and commercial developments.
China
China's market for water meters is propelled by extensive smart city initiatives and government mandates for efficient resource management. Large-scale infrastructure projects across urban and industrial zones necessitate advanced metering solutions. The Yangtze River Delta region and other industrial hubs are seeing widespread adoption of smart and ultrasonic meters for precise flow measurement.
Water Meter Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with a clear distinction between hardware-centric players and those offering integrated software solutions. The market exhibits a tiered structure, from large diversified conglomerates to niche technology innovators. Companies are increasingly pursuing strategic partnerships for technology co-development and portfolio diversification to capture recurring revenue streams.
Integrated solution providers such as Badger Meter exemplify the trend towards combining meters, software, and network infrastructure. Sensus, with its proprietary FlexNet communication network, represents a specialist in reliable data transmission. Itron, conversely, anchors the segment of companies leveraging extensive software platforms to secure recurring revenue streams from utilities.
| Leading Market Players |
|---|
| Badger Meter |
| Diehl Metering |
| Sensus |
| Itron |
| Neptune Technology Group |
| Honeywell International |
| Landis+Gyr |
| Kamstrup |
| Mueller Systems |
| Others |
Cost & Logistics Intelligence
The scarcity of skilled technicians for smart meter installation in North America creates labor cost differentials that influence the premium pricing tiers for advanced metering infrastructure projects.
Pricing Analysis
Capacity additions in China are reshaping price floors for mechanical and basic smart meter hardware, intensifying competition. Pricing for advanced water meters and associated software follows a hybrid model, combining per-unit transactional hardware sales with subscription-based data analytics services. Price differentiation stems from adherence to standards like ISO 4064 and the depth of after-sales service integration. Pricing pressure stems from the commoditization of mechanical meters, while software services command higher margins. Budget-constrained municipalities represent the most price-sensitive buyer segment.
Supply Chain Analysis
Regional distribution centers facilitate the efficient delivery of water meters, operating on a hub-and-spoke model to serve diverse geographies. Supply concentration for advanced meters and components is centered in China, Germany, and the United States. The production of these meters draws from specialized microcontrollers, communication modules, and precision-engineered plastics. Geopolitical tensions impacting semiconductor supply chains represent a structural risk. Distribution primarily runs through direct sales channels to large water utilities and specialized channel partners for smaller municipal and infrastructure developer projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water meter market presents a margin-expansion story, driven by the shift from one-time hardware sales to recurring revenue from data analytics software.
For Market Incumbents: To counter the threat of niche innovators and hardware price erosion, established incumbents must deepen vertical integration into software platforms. Strategic acquisitions of specialized analytics firms can expand their recurring revenue base. Investing in R&D for AI-powered predictive maintenance and edge computing capabilities reinforces their technological lead. Protecting intellectual property around communication protocols is critical.
For New Entrants and Emerging Players: The European Union’s Measuring Instruments Directive (MID) in Europe opens a window for new entrants offering certified, high-accuracy static meters. Targeting underpenetrated agricultural water management applications in water-stressed regions presents a significant white-space opportunity. A go-to-market strategy focusing on outcome-based contracting for leak detection and conservation services can differentiate offerings.
For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirers in this space, seeking to integrate water management into broader smart infrastructure portfolios. Long-term viability rests on essential infrastructure upgrades and the digital transformation of utilities. Acquisition targets should include software-centric analytics firms and specialized communication module developers. The signal to watch is utility procurement shifts towards OpEx models for network management.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Software-as-a-Service Offerings | Secures recurring revenue streams and deepens utility relationships beyond initial hardware sales. |
| Invest in Edge Computing R&D | Enables real-time data processing and reduces reliance on constant cloud communication for utilities. |
| Target Agricultural Irrigation Systems | Addresses water scarcity and optimizes resource use in a growing, underpenetrated application segment. |
| Acquire AI/Analytics Specialists | Integrates advanced predictive capabilities for leak detection and demand forecasting into portfolios. |
| Deepen Regulatory Compliance Expertise | Ensures market access and product acceptance, particularly under stringent standards like EU's MID. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the market analysis. Primary interviews included utility procurement officers, smart city planners, meter manufacturers' R&D heads, and infrastructure developers. Secondary validation drew from U.S. EPA reports, EU Measuring Instruments Directive guidelines, ISO 4064 standards, and national water agency publications. Bottom-up and top-down triangulation ensured data accuracy.
Market dimensions were modeled at granular levels, including product type, technology, application, end-user, and regional adoption rates, across the analysis window. The analytical framework integrated macroeconomic indicators with industry-specific drivers. Compound Annual Growth Rates were derived through regression analysis and expert consensus. Forecast inputs included urbanization rates, non-revenue water reduction targets, and smart city investment budgets.
Revisions become necessary when major policy shifts in water conservation or significant technological breakthroughs in sensing materialize. Forecasts reflect assumptions regarding regulatory stability and investment trends. Supply chain disruptions or shifts in utility funding models represent key risk factors. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Home Energy Monitor Market
Smart Meters
Smart Metering Systems Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
North America Smart Meters Market
Smart Meters
Power Monitoring System Market
Smart Meters
Smart Electric Meter Market
Smart Meters
Power Quality Meter Market
Smart Meters
Smart Water Metering Market
Smart Meters
Single-Phase Anti-Theft Meter Market
Smart Meters
Europe Smart Meter Data Management Market
Smart Meters
Smart Meters Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Solar Meter Market
Smart Meters
Middle East Distribution Meter Market
Smart Meters
United States Smart Meter Market