
 Airway Management Market | 2026-2036
Airway Management Market Size, Share, and Industry Trends Forecast 2026-2036
Airway Management Market Analysis
North American silicone molding capacity is realigning as medical device converters expand dedicated cleanroom lines for airway device production. Medtronic leverages its vertically integrated polymer compounding operations to secure supply continuity for endotracheal tube cuffs. Teleflex Incorporated anchors its position through proprietary blade geometry patents in video laryngoscopy. Ambu A/S differentiates via single-use device portfolios that reduce cross-contamination liability for hospital systems.
Airway management encompasses the instruments, techniques, and adjuncts employed to establish and maintain patent gas exchange pathways during anesthesia induction, respiratory failure, or trauma resuscitation, with modern systems integrating pressure-limited ventilation circuits and subglottic suction ports to mitigate ventilator-associated pneumonia. The primary commercial purpose centers on preventing hypoxic brain injury during perioperative care and critical illness. Supraglottic devices command widening share in ambulatory surgery centers where rapid insertion and minimal hemodynamic disturbance offset intubation complexity. Video laryngoscopy technology leads R&D expenditure as optical sensor miniaturization enables disposable cost parity with reusable metal blades. Emergency care applications generate premium pricing for pre-hospital kits designed to withstand temperature extremes and limited sterilization infrastructure.
FDA 510(k) clearance pathways govern Class II airway device introductions in the United States, while the EU MDR and ISO 13485 quality system requirements impose clinical evidence thresholds that filter smaller manufacturers from European distribution. The EPA regulates volatile anesthetic gas scavenging systems that interface with airway circuits in operating suites. Stakeholders must monitor FDA draft guidance on reusable device reprocessing validation as the agency weighs enhanced cleaning verification mandates that could accelerate single-use adoption across hospital networks.
Market Dynamics
Video laryngoscopy is electrifying hospital procurement patterns as optical sensor miniaturization collapses the cost gap between disposable and reusable blades, forcing manufacturers to reconfigure production footprints around single-use economics.
Growth Catalysts
- Difficult airway algorithm updates:Anesthesia societies in the United States have issued revised clinical guidelines that elevate video laryngoscopy to first-line status in anticipated difficult intubations, accelerating device replacement cycles in tertiary care centers.
- Ambulatory surgery center expansion:Supraglottic airway devices capture volume in freestanding surgical facilities where rapid turnover and minimal hemodynamic disturbance justify premium positioning over endotracheal intubation.
- Subglottic suction integration:Ventilator-associated pneumonia prevention protocols now mandate suction port-equipped endotracheal tubes, expanding the addressable device market beyond basic airway maintenance.
Market Restraints
- Silicone polymer supply concentration:North American medical-grade silicone compounding capacity remains concentrated among a limited set of suppliers, exposing cuff and seal manufacturers to input volatility and allocation risk.
- EU MDR clinical evidence thresholds:The European Medical Device Regulation's expanded requirements for biocompatibility and clinical performance data filter smaller manufacturers from European distribution, consolidating shelf presence among well-capitalized incumbents.
- Reusable blade reprocessing validation costs:FDA draft guidance on enhanced cleaning verification for reusable laryngoscope blades threatens to inflate operational costs for hospitals maintaining metal instrument programs.
Strategic Opportunities
- Pre-hospital emergency kits:Temperature-extreme packaging and limited sterilization infrastructure designs command premium pricing in emergency medical services, with municipal procurement opening outside traditional hospital supply chains.
- ISO 13485 quality system automation:Cloud-based document control and audit trail platforms reduce compliance overhead for mid-tier manufacturers seeking European market access without proportional headcount expansion.
- India surgical volume growth:Government-funded health insurance expansion and private hospital chain development create import substitution opportunities for airway device suppliers establishing local technical service presence.
Industry Challenges
- Polymer compounding technical talent:Medical device-grade silicone formulation expertise concentrates among aging specialists, constraining new entrant capacity expansion and quality system implementation timelines.
- Cleanroom infrastructure capex:Dedicated ISO Class 7 production lines for airway device assembly require substantial upfront investment, limiting contract manufacturing flexibility for product line extensions.
- FDA 510(k) predicate device navigation:Substantial equivalence determinations for novel blade geometries or cuff materials face heightened scrutiny, extending regulatory timelines and burning development runway.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airway Management Market |
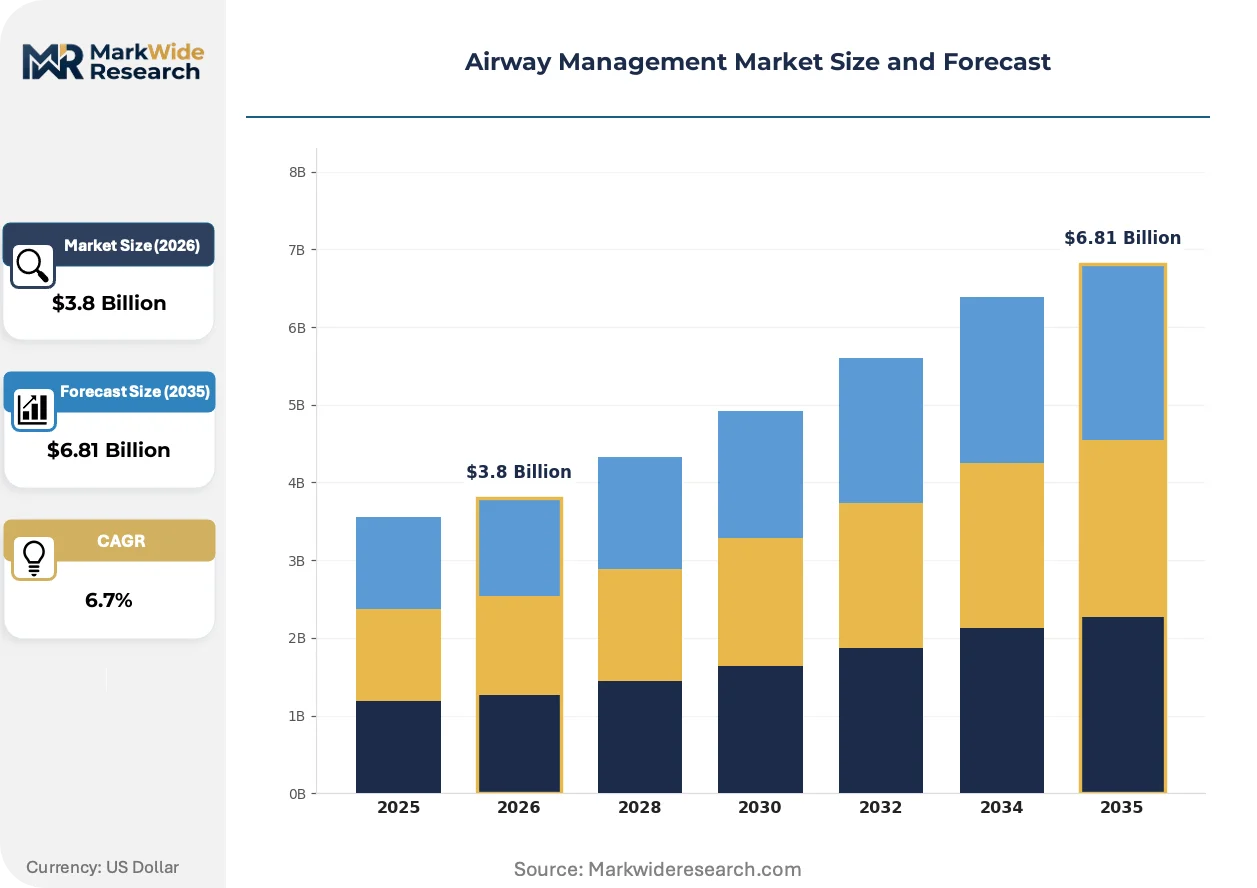
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
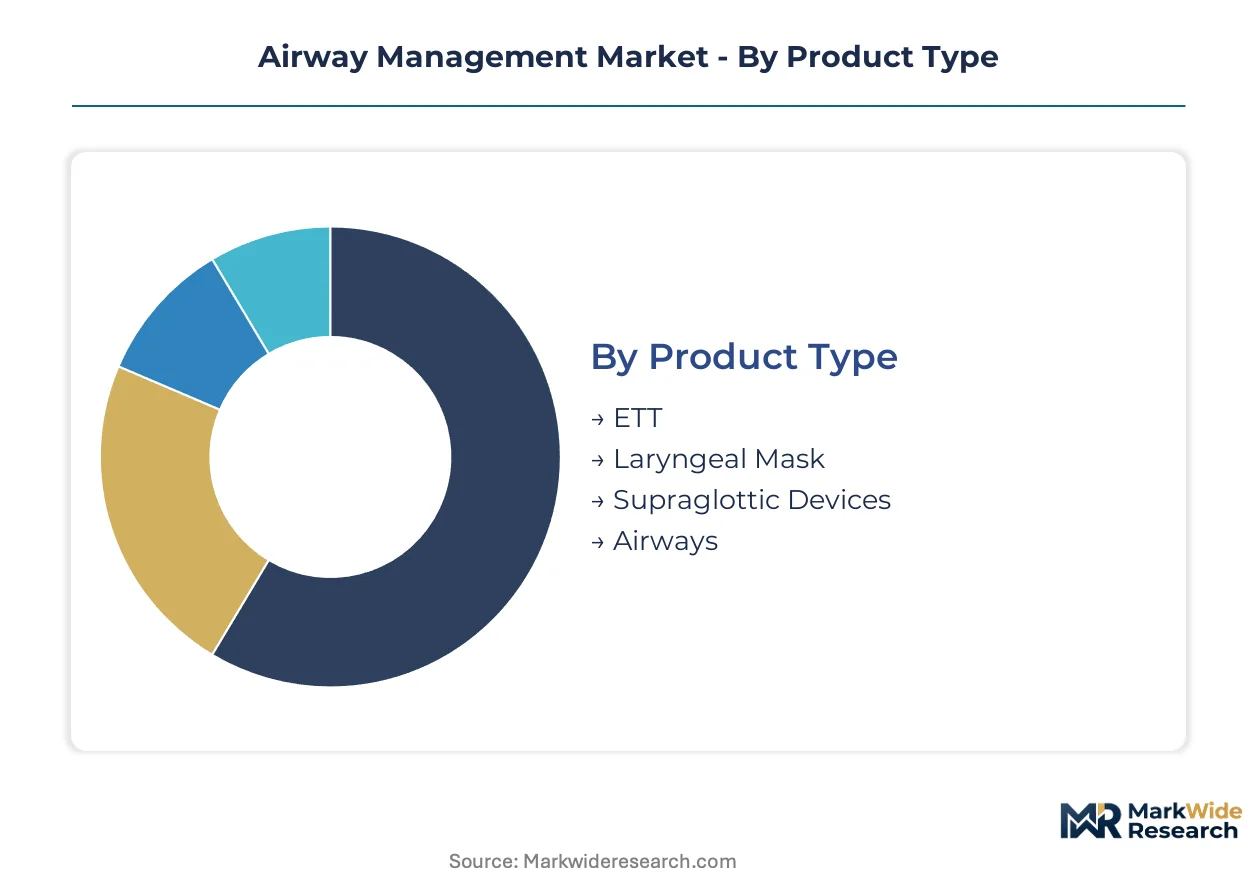
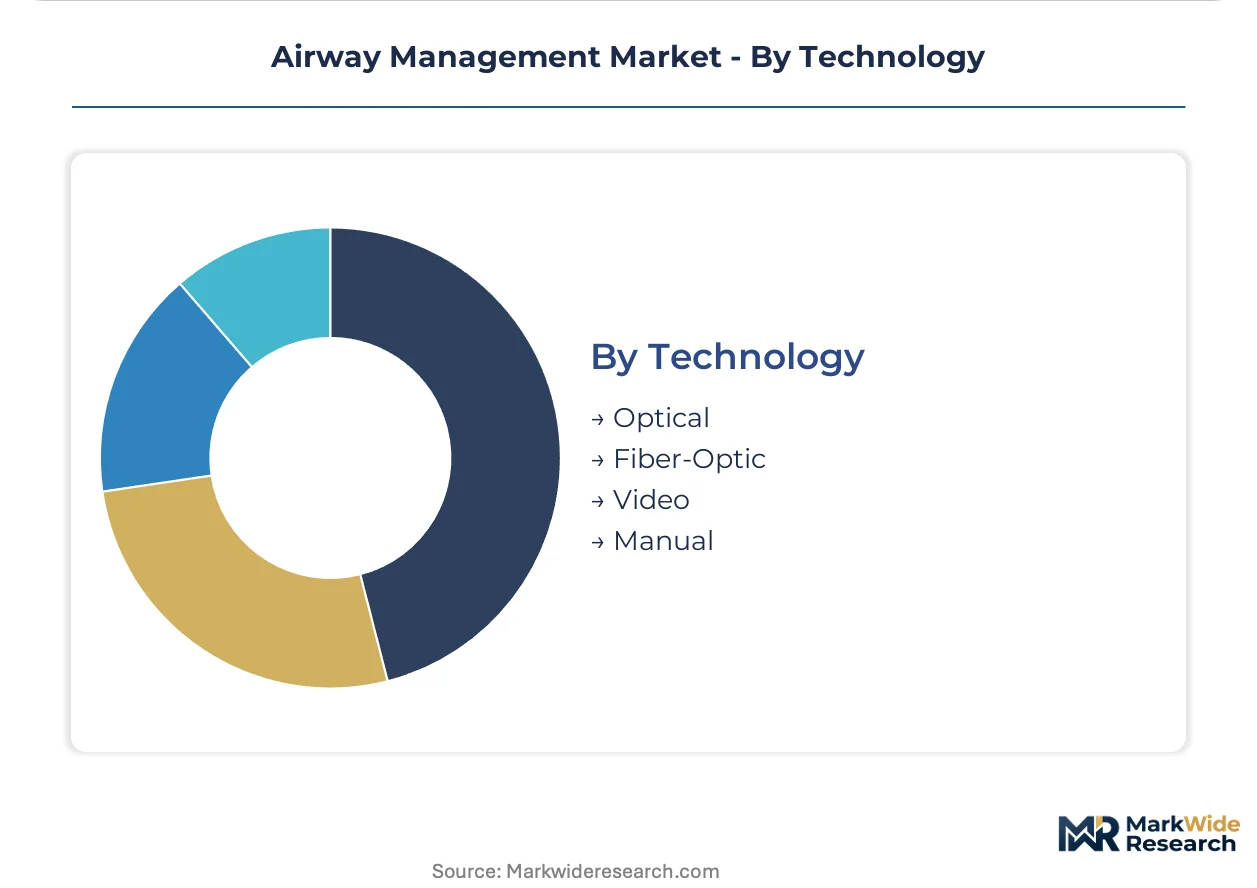
| Segmentation | Product Type: ETT, Laryngeal Mask, Supraglottic Devices, Airways End User: Hospitals, Emergency Services, Clinics, Home Care Application: Emergency Care, Anesthesia, Critical Care, Respiratory Support Technology: Optical, Fiber-Optic, Video, Manual |
| Companies Covered | Medtronic, Teleflex Incorporated, Ambu A/S, ICU Medical, Inc., Stryker Corporation, Smiths Medical, Fisher & Paykel Healthcare Limited, ConvaTec Group Plc, Mercury Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airway Management Market Emerging Trajectories
Optical sensor miniaturization, regulatory evidence escalation, and procurement model fragmentation are simultaneously compressing production economics and expanding clinical indication boundaries for airway management systems.
Disposable video laryngoscope blades are electrifying the cost structure of difficult airway management. CMOS sensor arrays and LED illumination packages now embed within single-use plastic housings at manufacturing cost parity with reusable metal blade sterilization cycles. Ambulatory surgery centers and emergency departments are adopting these devices to eliminate cross-contamination liability and reprocessing labor. This technology is electrifying competitive positioning by collapsing the service revenue model that historically sustained reusable blade manufacturers.
EU MDR Article 10 clinical evaluation requirements are reshaping European market access pathways for supraglottic devices. Manufacturers must now generate or source clinical performance data beyond predicate equivalence, elevating documentation costs and extending notified body review timelines. Class IIa airway devices face particular scrutiny as notified bodies apply conservative interpretations of biocompatibility and mechanical performance evidence. Mid-tier suppliers without captive clinical affairs capacity are exiting European distribution or seeking private-label partnerships with established certificate holders.
Hospital system procurement consolidation is fragmenting vendor relationships into tiered supply agreements. Integrated delivery networks now negotiate enterprise-wide airway device contracts that bundle video laryngoscopy systems, disposable blades, and supraglottic devices under single-source arrangements with price-volume commitments. This behavior concentrates purchasing power among three to five national distributors while marginalizing regional suppliers lacking capital to support consignment inventory and clinical training programs. The United States exhibits the most pronounced concentration, with anesthesia department standardization committees driving compliance to contracted portfolios across multihospital systems.
Airway Management Market Segmentation
Airway device procurement patterns diverge sharply across clinical settings, with hospital system consolidation favoring integrated technology platforms while emergency services prioritize ruggedized portability. Understanding these segment boundaries reveals where manufacturers must configure distinct supply chains and regulatory strategies.
Product Type:
Supply concentration in polymer compounding and cleanroom molding capacity shapes competitive positioning across airway device categories.
- ETT:Endotracheal tubes incorporate subglottic suction ports and pressure-limited cuffs to address ventilator-associated pneumonia protocols. United States tertiary care centers drive specification upgrades as anesthesia departments standardize on suction-equipped designs.
- Laryngeal Mask:These supraglottic devices seal the perilaryngeal space without tracheal penetration, enabling rapid insertion with minimal hemodynamic disturbance. Ambulatory surgery centers in Western Europe favor disposable variants to eliminate reprocessing labor and cross-contamination liability.
- Supraglottic Devices:Advanced designs feature gastric access channels and bite-resistant construction for extended anesthesia cases.
- Airways:Oropharyngeal and nasopharyngeal adjuncts serve rescue oxygenation and basic airway maintenance.
ETT absorbs the bulk of installed capacity; Supraglottic Devices are expanding most quickly.
End User:
Customer procurement sophistication varies from enterprise contract negotiation to municipal bid processes, dictating sales force structure and service bundling requirements.
- Hospitals:Integrated delivery networks negotiate bundled contracts spanning video laryngoscopy systems, disposable blades, and airway adjuncts with volume-price commitments and clinical training obligations. United States anesthesia department standardization committees enforce compliance to contracted portfolios across multihospital systems.
- Emergency Services:Pre-hospital kits must withstand temperature extremes and limited sterilization infrastructure, commanding premium pricing for ruggedized packaging and extended shelf life. Municipal procurement opens distribution outside traditional hospital supply chains.
- Clinics:Freestanding surgical facilities prioritize rapid turnover and minimal capital equipment.
- Home Care:Tracheostomy tube maintenance and non-invasive ventilation interfaces serve chronic respiratory failure patients.
Hospitals anchor the revenue base; Emergency Services present the steepest expansion trajectory.
Application:
Clinical indication boundaries determine regulatory classification, reimbursement coding, and evidence generation requirements for market access.
- Emergency Care:Difficult airway algorithms now elevate video laryngoscopy to first-line status in anticipated difficult intubations, accelerating device replacement cycles. United States trauma centers and emergency departments drive adoption of disposable optical systems to eliminate reprocessing delays.
- Anesthesia:Perioperative airway management demands precise control of ventilation parameters and protection against aspiration. Western Europe's ambulatory surgery expansion favors supraglottic devices that enable rapid emergence and minimal postoperative airway complications.
- Critical Care:Prolonged mechanical ventilation requires subglottic suction capability and pressure ulcer prevention features.
- Respiratory Support:Non-invasive interfaces bridge patients between intubation and spontaneous breathing.
Anesthesia commands the deepest installed base; Emergency Care is gaining share fastest.
Technology:
Manufacturing cost curves and sensor commoditization are collapsing the economic distinction between reusable and disposable platforms.
- Video:CMOS sensor arrays and LED illumination packages embed within single-use plastic housings at manufacturing cost parity with reusable metal blade sterilization cycles. North American hospital procurement is accelerating as optical miniaturization eliminates cross-contamination liability and reprocessing labor.
- Optical:Conventional direct laryngoscopy with Macintosh or Miller blade geometries persists in resource-constrained settings and training programs.
- Fiber-Optic:Flexible bronchoscopic intubation remains essential for anticipated difficult airways and awake fiber-optic techniques.
- Manual:Direct laryngoscopy without video augmentation serves backup scenarios and cost-sensitive procurement.
Video technology captures the dominant share of new capital expenditure; Fiber-Optic maintains specialized clinical utility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone compounding capacity in the United States anchors supply continuity for airway device manufacturers serving North American hospital systems.
United States
Tertiary care centers in the United States drive specification upgrades for subglottic suction-equipped endotracheal tubes as anesthesia departments standardize on VAP prevention protocols. FDA 510(k) clearance pathways govern Class II device introductions with heightened scrutiny on predicate equivalence for novel blade geometries. The Minneapolis medical technology corridor concentrates polymer compounding operations and cleanroom molding infrastructure for cuff and seal production.
Germany
German ambulatory surgery centers favor disposable supraglottic devices to eliminate reprocessing labor and cross-contamination liability amid rapid turnover requirements. EU MDR Article 10 clinical evaluation requirements filter smaller manufacturers from European distribution through expanded biocompatibility and performance data mandates. The Baden-Württemberg industrial region hosts notified body operations and polymer formulation expertise serving continental device suppliers.
India
Government-funded health insurance expansion and private hospital chain development in India create import substitution opportunities for airway device suppliers establishing local technical service presence. CDSCO medical device regulations impose quality system requirements that parallel ISO 13485 standards for market authorization. Maharashtra's Mumbai-Pune pharmaceutical corridor attracts contract manufacturers seeking to serve domestic surgical volume growth.
Japan
Japanese emergency medical services command premium pricing for ruggedized pre-hospital kits designed to withstand temperature extremes and limited sterilization infrastructure. PMDA regulatory frameworks align with international standards while maintaining distinct documentation requirements for novel optical systems. The Kansai region around Osaka concentrates precision molding capacity for disposable blade housings and sensor integration.
United Kingdom
United Kingdom anesthesia societies have issued revised difficult airway algorithm guidelines that elevate video laryngoscopy to first-line status in anticipated difficult intubations. MHRA post-Brexit regulatory autonomy maintains EU MDR alignment while streamlining notified body interactions for domestic manufacturers. The Cambridge-Oxford-London life sciences triangle anchors R&D operations for optical sensor miniaturization and CMOS array development.
Airway Management Market Vendor Landscape
Global majors compete with regional champions across regulatory compliance capacity and polymer supply chain control. The vendor base stratifies into three tiers: diversified conglomerates with captive silicone compounding, mid-tier specialists with single-use disposable portfolios, and regional contract manufacturers serving price-sensitive procurement. Structural consolidation favors incumbents with vertical integration into polymer supply and established notified body relationships under EU MDR. Competitive moves center on cleanroom capacity expansion for ISO Class 7 production lines and strategic partnerships to secure medical-grade silicone allocation.
Within the diversified conglomerate tier, Medtronic exemplifies backward integration into polymer compounding operations that secure supply continuity for endotracheal tube cuff manufacturing. Teleflex Incorporated occupies a position anchored by proprietary intellectual property in video laryngoscopy blade geometries. Ambu A/S represents the single-use disposable archetype, reducing cross-contamination liability for hospital systems through comprehensive single-portfolio positioning.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex Incorporated |
| Ambu A/S |
| ICU Medical, Inc. |
| Stryker Corporation |
| Smiths Medical |
| Fisher & Paykel Healthcare Limited |
| ConvaTec Group Plc |
| Mercury Medical |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up medical device specialists have consolidated North American silicone molding capacity, tightening supply discipline and supporting premium pricing for video laryngoscopy systems and single-use airway adjuncts. Their capital structures demand margin protection, translating into selective customer allocation and bundled service contracts that resist spot-market discounting.
Pricing Analysis
Warranty and training service bundling separates premium video laryngoscopy vendors from unbundled blade suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier and ISO 13485 certification depth. Pricing pressure stems from CMOS sensor commoditization collapsing disposable blade costs toward reusable sterilization parity. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraints; tertiary care anesthesia departments prioritize liability reduction over unit cost.
Supply Chain Analysis
Reverse logistics for reusable metal blade refurbishment creates complexity that single-use manufacturers avoid entirely. Medical-grade silicone compounding concentrates in the United States, Germany, and Japan, drawing from specialized polymer formulation expertise. Supply chain risk centers on single-source vulnerability for optical sensor arrays sourced from East Asian foundries. Distribution runs through integrated delivery network consignment agreements and emergency services municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade silicone compounding capacity constraints prop pricing discipline, as cleanroom infrastructure expansion lags surgical volume growth across North American hospital systems.
For Market Incumbents: Cement polymer supply security through backward integration into compounding operations or long-term offtake agreements with Minnesota and Baden-Württemberg suppliers. FDA draft guidance on reusable blade reprocessing validation threatens service revenue models; accelerate single-use portfolio conversion to capture replacement cycles. Priority lever: ISO Class 7 capacity addition in low-cost manufacturing zones. For New Entrants and Emerging Players: The mid-tier price-point gap between Teleflex premium systems and economy direct laryngoscopy creates white-space for CMOS-enabled disposable platforms. Target Indian private hospital chains and ASEAN ambulatory surgery centers where FDA predicate equivalence requirements are less stringent than EU MDR. Go-to-market angle: cloud-based quality system automation reducing compliance headcount for European market access. For Investors and Strategic Acquirers: Notified body queue elongation under EU MDR is the leading indicator that clinical affairs capacity scarcity will consolidate European distribution among certificate-rich incumbents. Five-to-ten year viability favors mid-tier specialists with captive silicone supply and established notified body relationships. Signal to monitor: CDSCO regulatory harmonization accelerating import substitution in Indian government insurance expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO Class 7 lines in Maharashtra and Minneapolis secure cuff manufacturing continuity for hospital contracts. |
| FDA 510(k) Predicate Navigation | Substantial equivalence pathways for novel blade geometries determine competitive entry timing. |
| EU MDR Certificate Holding | Notified body relationships filter market access and consolidate shelf presence among capitalized players. |
| Pre-Hospital Kit Ruggedization | Temperature-extreme packaging opens municipal procurement outside traditional hospital supply chains. |
| Silicone Compounding Backward Integration | Captive polymer supply insulates margin from medical-grade allocation volatility. |
Methodological Framework
SEC 10-K filings, FDA 510(k) clearance databases, and EU MDR notified body documentation formed the secondary backbone, combined with primary interviews across anesthesia department heads, hospital GPO contract managers, biomedical engineers, and silicone compounding technical directors. Bottom-up and top-down triangulation validated segment-level estimates against customs trade flows and hospital procurement database benchmarks.
Bottom-up modeling anchored volume projections to installed base replacement cycles and ambulatory surgery center expansion trajectories, while top-down cross-checks applied macro healthcare expenditure patterns. Segmentation across product type, end user, application, and technology dimensions informed CAGR derivation through differential adoption curve analysis. Forecast inputs incorporated optical sensor cost curves and regulatory timeline probability distributions.
Inputs from FDA premarket notification records and EU MDR technical documentation were available through the study window; gaps in private hospital chain procurement data introduce uncertainty bands in emerging market estimates. Forecasts reflect assumptions regarding silicone supply continuity and notified body capacity expansion. Practitioners should monitor CDSCO regulatory harmonization progress and EPA anesthetic gas scavenging enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Phoropters Market
Medical Devices
Urology Guidewires Market
Medical Devices
Slip Disc Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Global Electronic Drug Delivery Systems Market
Medical Devices
Global Sphygmomanometer Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
Bovine Pericardial Valve Market
Medical Devices
Global Doppler Ultrasound Systems Market