
 Orthodontic Retainers Market | 2026-2036
Orthodontic Retainers Market Size, Share, and Industry Trends Forecast 2026-2036
Orthodontic Retainers Market Outlook
The orthodontic retainers category is recalibrating around a widening split between digitally manufactured premium devices and conventional commodity alternatives. Align Technology leverages its intraoral scanning ecosystem to control patient workflow from aligner therapy through retention. American Orthodontics anchors its position with specialized fixed retainer systems for orthodontic practices. Henry Schein competes through extensive dental distribution networks that reach independent clinics.
Orthodontic retainers are removable or fixed dental appliances, typically fabricated from thermoplastic polymers, stainless steel wire, or acrylic resin, designed to stabilize tooth position following active orthodontic treatment. Clear aligner-derived retainers and Hawley retainers represent the dominant product categories, with polycarbonate variants gaining traction for durability. Plastic materials lead volume production due to thermoforming compatibility, while metal wire components sustain demand for fixed lingual retention where compliance is uncertain. Dental practices remain the primary end-user channel, though home care impressions are reshaping distribution through online portals.
The FDA regulates retainer materials as Class II medical devices under 510(k) premarket notification, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for clear retainer polymers entering European markets. ISO 13485 quality management standards govern manufacturing consistency across both jurisdictions. Stakeholders must monitor evolving biocompatibility testing protocols and direct-to-consumer regulatory boundaries that could reshape channel economics.
Market Dynamics
Digital intraoral scanning is compressing traditional dental laboratory workflows, forcing retainer manufacturers to rebuild production around chairside manufacturing ecosystems and cloud-connected design platforms.
Growth Catalysts
- Direct-to-consumer aligner retention protocols:Large patient bases from teledentistry platforms now require standardized retention regimens, creating predictable volume demand for replacement retainers.
- FDA 510(k) clearance streamlining:The premarket notification pathway for clear thermoplastic materials reduces regulatory friction for new polymer entrants seeking dental device classification.
- Polymer durability advances:Next-generation polycarbonate and PETG formulations extend retainer lifespan from months to years, reducing per-patient lifetime costs and improving compliance.
Market Restraints
- Raw material concentration:Medical-grade thermoplastic pellet supply concentrates among German and US specialty chemical producers, exposing fabricators to input cost volatility.
- Biocompatibility testing burden:ISO 10993 cytotoxicity and sensitization protocols for intraoral polymers add months to product development timelines.
- DIY impression kit substitution:Home-molded boil-and-bite retainers threaten professional fabrication volumes in price-sensitive patient segments.
Strategic Opportunities
- Subscription retention models:Automated replacement schedules for clear retainers capture recurring revenue from orthodontic practices managing post-treatment compliance.
- AI-driven treatment monitoring:Smartphone-based wear-time tracking and fit assessment tools integrate with retainer dispensing to reduce chairside follow-up.
- EU MDR compliance services:Clinical evidence consulting for clear polymer biocompatibility documentation addresses manufacturer gaps in European market entry.
Industry Challenges
- CAD/CAM technician scarcity:Dental laboratory workforce shortages constrain digital design throughput for custom retainer production.
- Cross-border teledentistry liability:Jurisdictional ambiguity around remote retainer dispensing complicates direct-to-consumer expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthodontic Retainers Market |
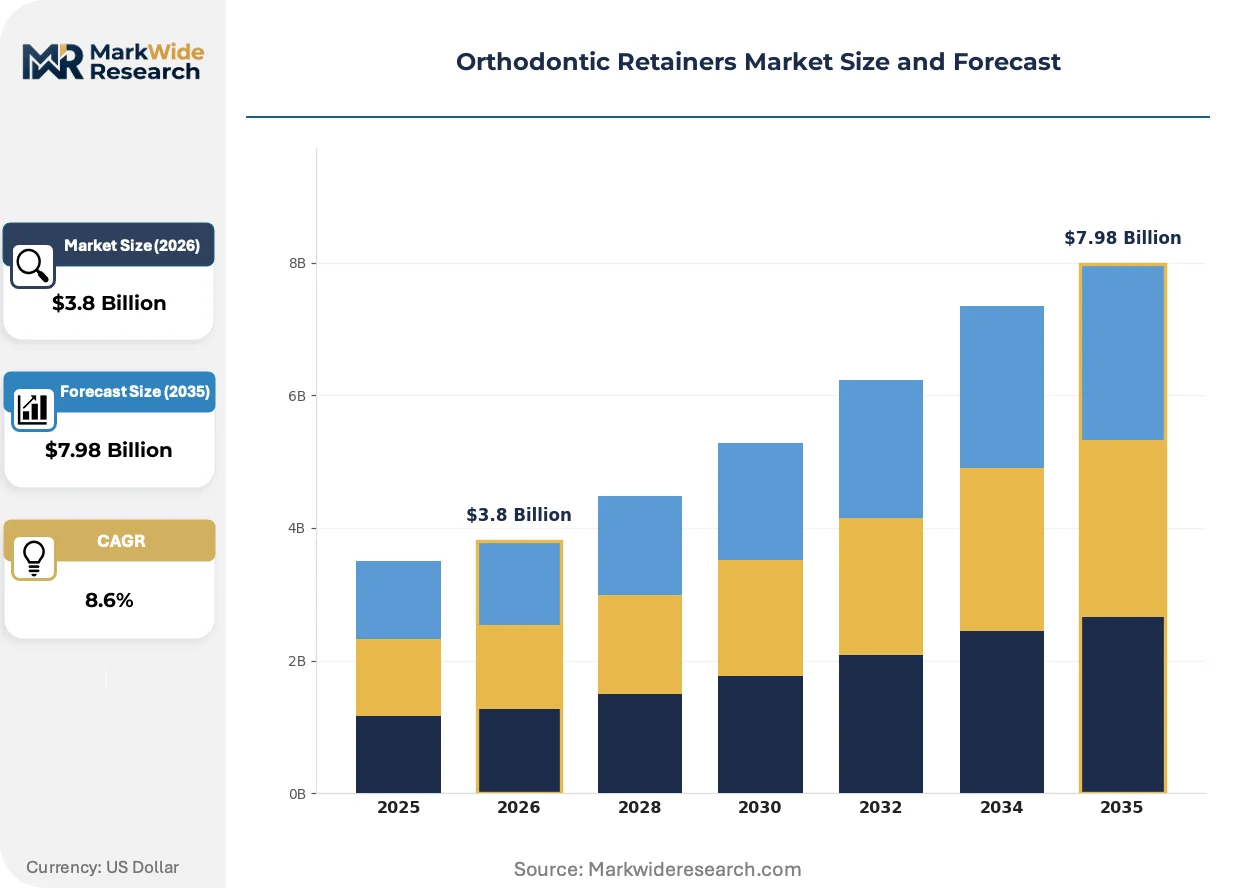
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Aligners, Fixed Retainers, Hawley Retainers, Polycarbonate Retainers Material: Plastic, Metal, Composite, Acrylic End User: Clinics, Hospitals, Dental Practices, Home Care Distribution Channel: Online, Direct Sales, Retail, Dental Distributors |
| Companies Covered | Align Technology, American Orthodontics, 3M, G&H Orthodontics, TP Orthodontics, Dentsply Sirona, Henry Schein, Great Lakes Dental Technologies, Ormco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthodontic Retainers Market Strategic Shifts
Chairside manufacturing systems are collapsing the traditional separation between orthodontic diagnosis and retainer delivery, compressing what required weeks into same-appointment workflows.
Intraoral scanning combined with in-office 3D printing is decentralizing retainer production from centralized dental laboratories to individual practice locations. General dentists and orthodontic specialists are adopting desktop thermoforming and resin-printing systems at accelerating rates. This shift is decentralizing market power toward equipment vendors and software platforms that control the digital workflow stack.
The EU Medical Device Regulation's clinical evidence requirements for polymer-based dental devices are tightening market access for non-European manufacturers. Substantial equivalence pathways have narrowed, forcing additional biocompatibility studies. Small and mid-sized retainer brands without dedicated regulatory affairs capacity are withdrawing from European distribution or seeking notified body partnerships.
Patients who began orthodontic treatment through direct-to-consumer aligner platforms are now aging into retention phases with distinct service expectations. These buyers favor remote monitoring, automated reordering, and transparent pricing over traditional recall appointments. The United States exhibits the strongest concentration of this behavioral shift, where teledentistry penetration has normalized digital-first dental relationships.
Orthodontic Retainers Market Segmentation
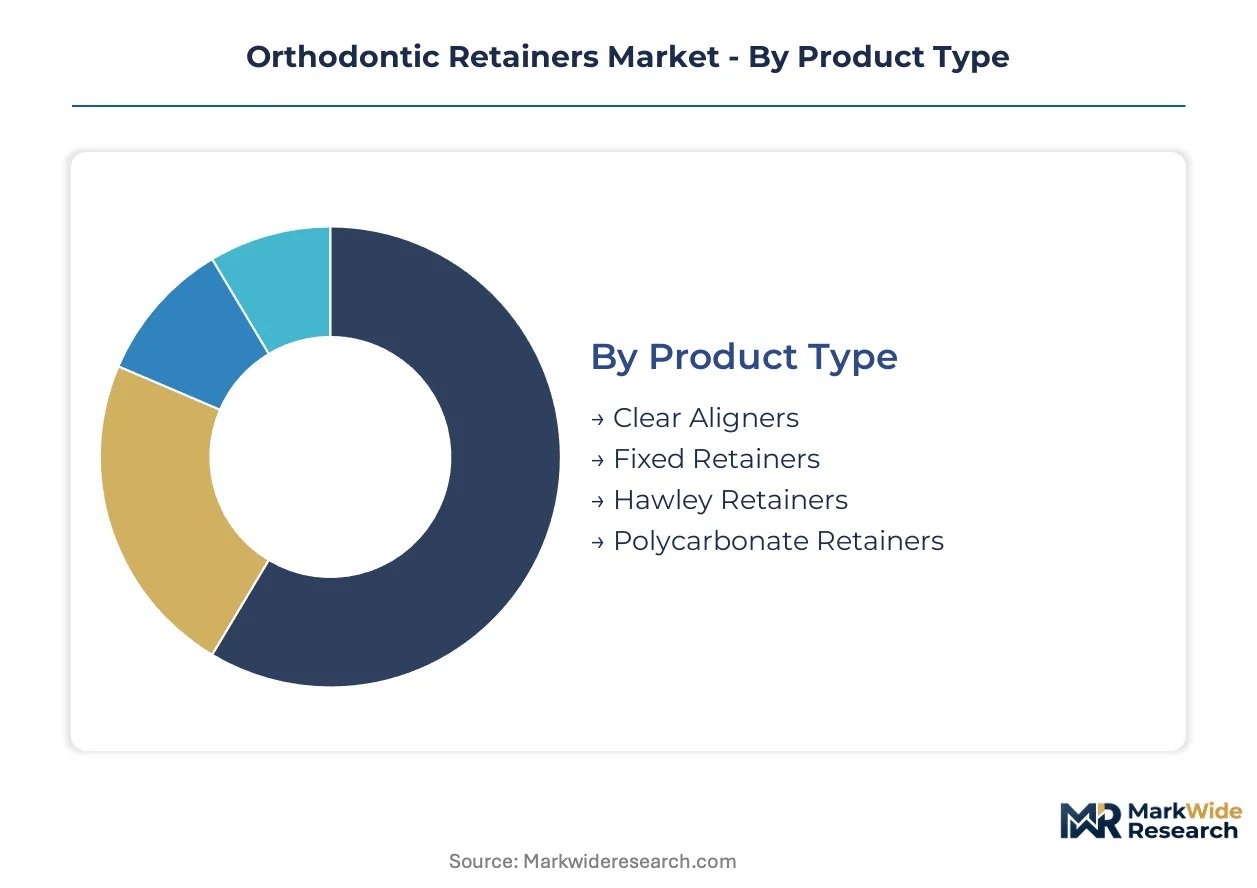
Orthodontic retainer segmentation reveals how manufacturing scale, regulatory pathways, and patient compliance patterns fragment commercial opportunity across distinct product architectures and channel configurations. Supply-side capabilities in digital fabrication versus conventional laboratory methods create divergent margin structures within each category.
Product Type:
Supply concentration in thermoplastic polymer extrusion and precision wire bending determines which product architectures dominate regional production clusters.
- Clear Aligners:Fabricated from medical-grade polyethylene terephthalate glycol (PETG) or proprietary multilayer polymers through pressure-thermoforming over 3D-printed models. Demand concentrates among direct-to-consumer aligner graduates in the United States, where retention protocol standardization drives replacement volume. The FDA 510(k) clearance pathway for clear materials accelerates product iteration cycles.
- Fixed Retainers:Bonded lingual appliances constructed from braided stainless steel or fiber-reinforced composite ribbons, requiring chairside placement by orthodontic specialists. European dental practices favor fixed systems for adolescent compliance cases, with EU MDR biocompatibility documentation raising entry barriers for imported wire components.
- Hawley Retainers:Removable acrylic-and-wire designs with labial bows and palatal plates, produced through conventional dental laboratory workflows. Japanese orthodontic practices maintain substantial Hawley adoption for post-surgical retention.
- Polycarbonate Retainers:High-impact thermoplastic variants engineered for extended wear durability beyond standard PETG lifespans. German specialty chemical producers supply medical-grade polycarbonate pellets to precision thermoforming operations.
Today's leader: Clear Aligners. Tomorrow's challenger: Polycarbonate Retainers.
Material:
Raw material sourcing geography and polymer processing sophistication create tiered cost structures that reshape competitive positioning across fabrication scales.
- Plastic:Thermoplastic polymers including PETG, polyethylene, and polycarbonate dominate volume production through vacuum and pressure thermoforming. United States-based clear aligner platforms source plastic sheeting from domestic extrusion facilities to minimize supply chain risk.
- Metal:Stainless steel wire and cobalt-chromium alloys sustain fixed retainer fabrication, with wire drawing concentration in Germany and Japan determining regional cost differentials.
- Composite:Fiber-reinforced polymer ribbons and aesthetic tooth-colored materials command premium positioning for visible anterior retention.
- Acrylic:Polymethyl methacrylate (PMMA) resins anchor conventional Hawley baseplate production, with laboratory-grade acrylic supply fragmenting across regional chemical distributors.
Plastic commands present volume. Composite materials are climbing the fastest as aesthetic standards intensify.
End User:
Channel economics and patient relationship duration vary dramatically between institutional settings and emerging direct-to-consumer alternatives.
- Clinics:Outpatient orthodontic and general dental facilities managing mixed aligner and retention caseloads, with chairside digital scanning enabling same-appointment retainer delivery. United States clinic networks leverage volume purchasing agreements with national dental distributors.
- Hospitals:Academic medical centers and craniofacial surgery units handling complex post-surgical retention, where interdisciplinary coordination between orthodontists and oral surgeons extends treatment timelines.
- Dental Practices:Independent and group practices representing the traditional fabrication channel, with laboratory outsourcing relationships determining retainer markup structures.
- Home Care:Direct-to-consumer impression kits and remote monitoring platforms, with teledentistry regulation in the United States creating jurisdictional complexity for interstate retainer dispensing.
Dental Practices anchor current revenue. Home Care presents the steepest expansion trajectory as teledentistry normalizes.
Distribution Channel:
Channel control and margin capture diverge between manufacturer-direct relationships and intermediary-dependent architectures.
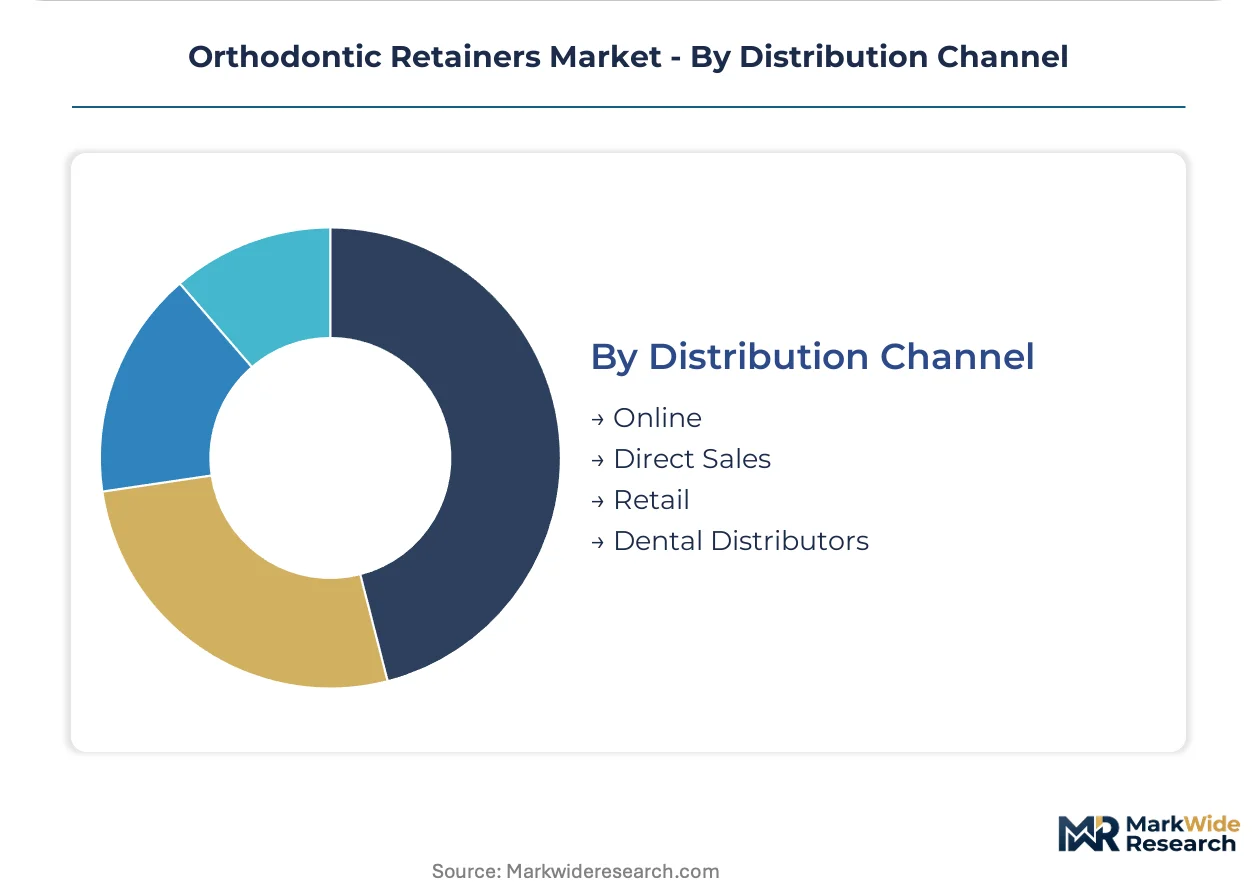
- Online:E-commerce portals and subscription platforms enabling automated retainer replacement scheduling, with patient data integration supporting compliance monitoring.
- Direct Sales:Manufacturer field forces calling on large dental service organizations and aligner platform partnerships, bypassing distributor markups for high-volume accounts.
- Retail:Limited pharmacy and big-box retail presence for over-the-counter boil-and-bite alternatives, with product quality variability constraining professional endorsement.
- Dental Distributors:Henry Schein and regional wholesalers maintaining inventory positions for same-day practice fulfillment, with logistics networks determining rural market access.
Dental Distributors defend incumbent position. Online channels are gaining share fastest through subscription model economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States direct-to-consumer aligner platforms generate replacement retainer volume that German precision polymer suppliers struggle to match at equivalent scale. Japan maintains distinctive Hawley fabrication traditions while China builds thermoforming capacity for regional export markets.
United States
Teledentistry platforms have normalized digital-first dental relationships, creating predictable demand for automated retainer replacement schedules. The FDA's 510(k) clearance pathway for clear thermoplastic materials accelerates product iteration cycles for domestic manufacturers. Dallas-Fort Worth and Phoenix dental service organizations deploy chairside 3D printing systems that compress laboratory turnaround from weeks to hours.
Germany
Medical-grade polycarbonate and PETG pellet production concentrates among specialty chemical producers serving precision thermoforming operations. The EU Medical Device Regulation imposes stricter clinical evidence requirements for clear retainer polymers than FDA equivalents, extending approval timelines. Munich and Stuttgart industrial clusters house dental laboratory equipment manufacturers exporting CAD/CAM systems throughout Europe.
Japan
Orthodontic practices maintain substantial Hawley retainer adoption for post-surgical retention cases requiring adjustable labial bow mechanics. The country's national pharmaceutical regulator applies biocompatibility protocols aligned with ISO 10993 standards for intraoral polymer devices. Osaka and Nagoya dental laboratories preserve conventional acrylic-and-wire fabrication expertise alongside incremental digital adoption.
China
Domestic clear aligner brands are building captive patient bases that will transition into retention phases requiring standardized replacement protocols. The National Medical Products Administration classifies retainer materials as Class II medical devices with substantial equivalence pathways for imported polymer formulations. Shenzhen and Guangzhou manufacturing zones produce thermoplastic sheeting for regional dental laboratory networks and export markets.
Brazil
Expanding middle-class access to orthodontic treatment is creating downstream retention demand that outpaces specialized laboratory capacity. ANVISA regulates dental devices through risk-based classification systems that align with Mercosur technical standards. São Paulo state concentrates dental service organization expansion and imported equipment distribution for chairside manufacturing adoption.
Orthodontic Retainers Market Competitive Environment
Top-tier vendors anchor integrated digital workflow ecosystems, while mid-tier fabricators compete on laboratory outsourcing relationships and regional distribution density. The market structure reflects consolidation around aligner-to-retainer patient data continuity versus fragmentation among conventional dental laboratory suppliers. Three strategic archetypes dominate: intraoral scanning platform owners, specialized fixed retainer system manufacturers, and dental distribution conglomerates with logistics scale. Competitive moves concentrate on M&A for digital design software capabilities and strategic partnerships with direct-to-consumer aligner platforms for retention protocol lock-in.
Within the platform-integrated tier, Align Technology exemplifies patient workflow control from aligner therapy through retention phases. American Orthodontics occupies a position among specialized fixed system manufacturers serving orthodontic specialist practices. Henry Schein anchors the distribution-centric archetype through extensive dental supply networks reaching independent clinics nationwide.
| Leading Market Players |
|---|
| Align Technology |
| American Orthodontics |
| 3M |
| G&H Orthodontics |
| TP Orthodontics |
| Dentsply Sirona |
| Henry Schein |
| Great Lakes Dental Technologies |
| Ormco |
| Others |
Value Chain & Pricing Dynamics
Clear-to-fixed retainer bifurcation separates premium digitally manufactured devices from commodity laboratory alternatives, concentrating margin capture among chairside equipment vendors while compressing traditional dental laboratory economics through centralized thermoplastic pellet sourcing and decentralized fabrication adoption.
Pricing Analysis
Capacity additions in China's thermoforming equipment sector are reshaping price floors for entry-level clear retainers, pressuring mid-tier fabricators in Southeast Asia. Three-tier pricing structure across premium chairside systems, standard laboratory outsourcing, and economy boil-and-bite alternatives dominates, with FDA 510(k) certification tier and polymer durability grade as primary price differentiation drivers. Cost compression in standard laboratory tiers is intensifying because DIY impression kit substitution erodes professional fabrication volumes. Price-sensitive independent dental practices in rural United States markets exhibit highest elasticity, while orthodontic specialist networks with captive patient workflows demonstrate lowest sensitivity.
Supply Chain Analysis
Domestic-content mandates in China's medical device procurement are reshaping sourcing patterns for European and American retainer brands seeking hospital channel access. Medical-grade thermoplastic pellet supply concentrates among German and United States specialty chemical producers, with braided stainless steel wire drawing anchored in Japan and Germany. Fabrication draws from PETG sheeting, cobalt-chromium alloys, and fiber-reinforced composite ribbons as critical inputs. Single-source vulnerability in medical-grade polycarbonate pellet supply exposes fabricators to input cost volatility. Distribution runs through Henry Schein and regional dental distributors maintaining inventory positions for same-day practice fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The orthodontic retainers market functions as a stable compounder, with direct-to-consumer aligner retention protocols generating predictable replacement volume that sustains manufacturer revenue visibility across economic cycles.
For Market Incumbents: Acquire CAD/CAM software capabilities to secure digital workflow control from aligner therapy through retention phases. Consolidate position through exclusive partnerships with direct-to-consumer aligner platforms for retention protocol lock-in, countering DIY impression kit substitution threats. Invest in ISO 13485 certification infrastructure to defend European market access against EU MDR compliance barriers. For New Entrants and Emerging Players: Capture underserved fixed retainer segments in European adolescent compliance cases where EU MDR documentation requirements deter non-European competitors. Target polycarbonate durability tier as fastest-climbing product category with premium positioning potential. Deploy teledentistry-enabled remote monitoring platforms to access United States direct-to-consumer aligner graduates seeking automated replacement scheduling. For Investors and Strategic Acquirers: Asymmetric upside sits with chairside manufacturing equipment vendors controlling decentralized production adoption curves. Five-to-ten year viability rests on polymer durability advances extending retainer replacement intervals while subscription models capture recurring revenue. Monitor FDA 510(k) clearance velocity for clear thermoplastic materials as inflection indicator for new entrant competitive pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Chairside Manufacturing Equipment Deployment | Dallas-Fort Worth dental service organizations compress laboratory turnaround from weeks to hours through in-office 3D printing adoption. |
| FDA 510(k) Clearance Acceleration | Domestic manufacturers leverage streamlined premarket notification pathways to iterate clear thermoplastic formulations faster than EU MDR counterparts. |
| Subscription Retention Model Launch | Automated replacement scheduling captures recurring revenue from orthodontic practices managing post-aligner compliance across large patient bases. |
| EU MDR Compliance Service Partnership | Clinical evidence consulting addresses manufacturer gaps in European market entry for clear polymer biocompatibility documentation. |
| AI-Driven Treatment Monitoring Integration | Smartphone-based wear-time tracking tools reduce chairside follow-up burden while differentiating premium retainer dispensing platforms. |
Study Parameters
Coverage spans United States, Germany, Japan, China, and Brazil, with primary inputs from each market informing demand calibration and regulatory pathway mapping. The analysis combines structured interviews with orthodontic practice owners, dental laboratory technicians, regulatory affairs specialists at polymer manufacturers, and procurement managers at dental service organizations with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, National Medical Products Administration device classifications, and ANVISA risk-based registration data. Bottom-up patient volume modeling and top-down dental expenditure triangulation anchor market size estimation.
Granularity-level modeling distinguishes clear aligner-derived retainers, fixed lingual systems, Hawley designs, and polycarbonate variants by material composition, end-user channel, and distribution architecture across the projection horizon. CAGRs derive from patient cohort aging analysis, replacement protocol standardization trends, and chairside manufacturing adoption curves. Forecast inputs incorporate direct-to-consumer aligner platform retention phase transitions, polymer durability testing data, and teledentistry regulatory evolution.
Raw material cost volatility, biocompatibility testing timeline extensions, and direct-to-consumer regulatory boundary shifts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding patient compliance rates, replacement frequency protocols, and regulatory clearance velocities. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
Global Transdermal Skin Patches Market
Medical Devices
Global Capnography Market
Medical Devices
Arthroscopy Market
Medical Devices
Global Non Fusion Spinal Devices Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Incontinence Devices and Ostomy Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Temporary Pacing Leads Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Global Trauma Devices Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Embryo Transfer Catheters Market
Medical Devices
Buccal Cavity Devices Market