
 Digital Ureteroscopes Market | 2026-2036
Digital Ureteroscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Ureteroscopes Market Insights
CMOS sensor miniaturization is reshaping how digital ureteroscopes achieve high-definition visualization within sub-millimeter outer diameters. Olympus Corporation leverages its proprietary image-processing architectures to sustain technical leadership in flexible platforms. Karl Storz SE & Co. KG anchors its competitive stance through backward integration into precision optics manufacturing. Boston Scientific Corporation differentiates via broad urology portfolio breadth that spans diagnostic and therapeutic workflows.
A digital ureteroscope is an endoscopic instrument incorporating a distal digital image sensor—typically CMOS or CCD—transmitting real-time video to an external processor, enabling minimally invasive visualization and intervention within the urinary collecting system. These devices employ working channels of 1.2–3.6 French diameter to accommodate lithotripsy fibers, biopsy forceps, or irrigation while maintaining outer diameters below 9.5 French for ureteral navigation. Flexible product variants command the dominant share of procedure volume due to their capacity to navigate the renal pelvis and calyceal anatomy, though rigid platforms retain cost advantages in straightforward distal ureteral cases. The ambulatory surgical center end-user segment represents the fastest-expanding demand pool as same-day discharge protocols proliferate across urology service lines.
The FDA's 510(k) pathway governs market entry for digital ureteroscopes in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for reusable endoscopic devices. ISO 13485 quality management certification functions as a baseline predicate for supplier qualification across OECD procurement frameworks. Stakeholders must monitor how sustainability mandates and reprocessing validation standards reshape total cost-of-ownership calculations for capital-intensive endoscopy platforms.
Market Dynamics
CMOS sensor miniaturization is compressing device footprints while amplifying resolution demands, forcing manufacturers to recalibrate R&D priorities around sub-millimeter optical architectures without sacrificing image fidelity.
Growth Catalysts
- Ambulatory surgical center expansion:Same-day discharge protocols in urology service lines are pulling capital equipment purchases toward outpatient-compatible platforms. United States integrated health networks prioritize these configurations.
- FDA 510(k) pathway clarity:Predictable premarket notification requirements for digital imaging endoscopes accelerate product iteration cycles. Manufacturers leverage this framework to compress time-to-market for sensor upgrades.
- Single-use device penetration:Cross-contamination risk mitigation in reusable endoscopy is redirecting procurement toward disposable ureteroscope platforms. Hospital infection control committees drive this specification shift.
Market Restraints
- Precision optics supply concentration:German and Japanese optical component suppliers control critical lens and fiber supply. Disruption to these sources propagates through assembly timelines.
- EU MDR clinical evidence burdens:Strengthened post-market surveillance and clinical data requirements for reusable endoscopic devices extend certification timelines. Small manufacturers face disproportionate compliance costs.
- Capital intensity of CMOS sensor platforms:High-definition image sensor procurement and calibration require specialized cleanroom infrastructure. This input cost structure elevates minimum viable scale for market entry.
Strategic Opportunities
- Artificial intelligence convergence with endoscopic imaging:Real-time stone detection and tissue characterization algorithms are integrating with digital ureteroscope video feeds. Academic medical centers pilot these augmented visualization workflows.
- India urology infrastructure buildout:Underpenetrated tertiary care capacity in tier-2 cities creates equipment demand as domestic procedure volumes rise. CDSCO regulatory harmonization facilitates import substitution.
- Reprocessing-as-a-service models:Third-party sterilization and maintenance subscriptions are displacing in-house biomedical engineering functions. Ambulatory surgical centers adopt these arrangements to eliminate fixed overhead.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified quality management system assessors for active medical device manufacturing concentrate in established regulatory hubs. Emerging market manufacturers face extended certification queue times.
- Legacy video processor integration:Health system capital refresh cycles lag behind digital ureteroscope sensor generations. Procurement committees grapple with backward compatibility requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Ureteroscopes Market |
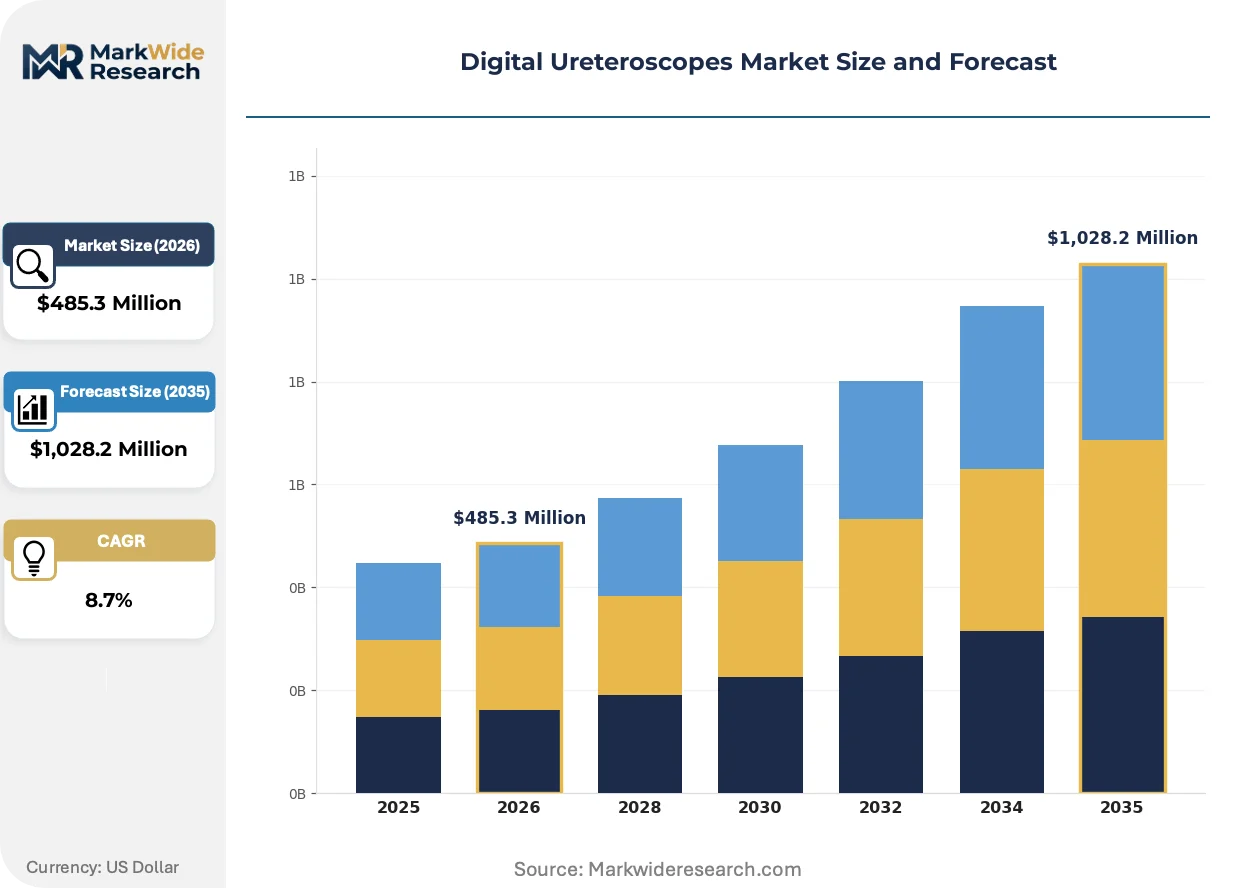
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,028.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, Semi-Rigid, Ultra-Flexible End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Technology: Digital, Analog, Robotic, Laser-Assisted Application: Kidney Stones, Ureteral Stricture, Tumor Removal, Urinary Tract Disorders |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Karl Storz SE & Co. KG, Stryker Corporation, Richard Wolf GmbH, PENTAX Medical, Dornier Medtech, ELMED Medical Systems, NeoScope Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Ureteroscopes Market Trends and Innovations
Three interconnected developments are compressing product lifecycles and redrawing competitive boundaries: sensor architecture migration, regulatory evidence escalation, and procurement model unbundling.
Distal CMOS sensors are migrating from 1.2 megapixel specifications toward 4K-resolution platforms capable of resolving sub-millimeter calculi fragments. Academic medical centers in the United States and Germany pilot these configurations during complex renal pelvis navigation. The technology is migrating from research protocols into standard-of-care procurement specifications within three-year replacement windows.
Europe's Medical Device Regulation imposes annual safety update reporting and expanded clinical investigation requirements for reusable endoscopic equipment. Manufacturers must maintain post-market clinical follow-up registries that track device-specific adverse events across multiple member states. Flexible ureteroscope suppliers with established notified body relationships capture disproportionate certification bandwidth.
Hospital purchasing consortia are consolidating procurement authority for capital endoscopy platforms, displacing individual facility autonomy. These entities unbundle device acquisition from service contracts and reprocessing agreements. United States metropolitan health systems demonstrate this concentration most visibly, with integrated delivery networks standardizing across dozens of ambulatory sites.
Digital Ureteroscopes Market Segmentation
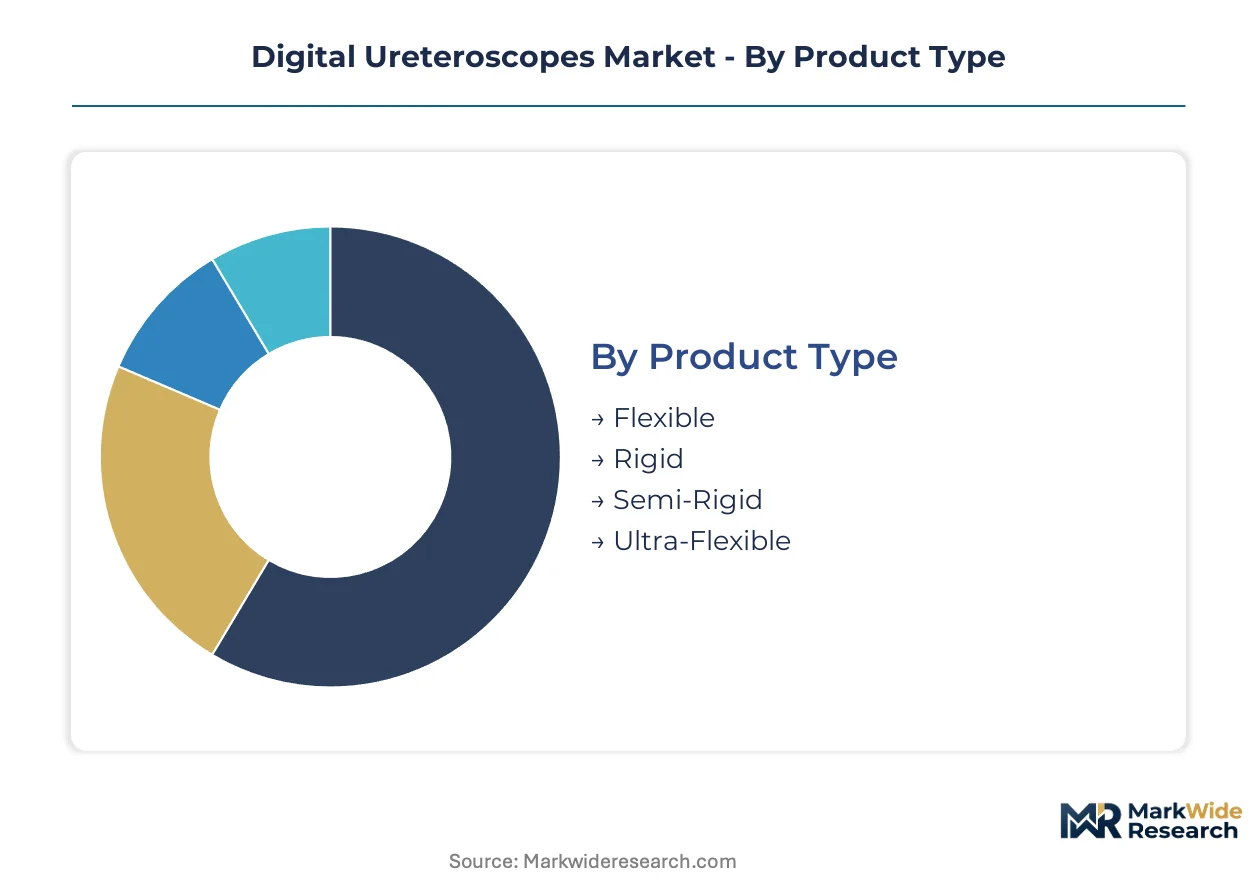
Digital ureteroscope procurement patterns diverge sharply across clinical settings, with flexible platforms dominating complex renal navigation while rigid variants retain cost advantages in straightforward distal ureteral interventions. Technology selection hinges on reimbursement pathways, capital refresh cycles, and infection control protocols that reshape total cost-of-ownership calculations.
Product Type:
Flexible ureteroscopes span a continuum from standard articulating shafts to ultra-narrow platforms optimized for lower pole calyceal access, with each tier commanding distinct pricing and service contract structures.
- Flexible:Articulating distal tips with 270-degree deflection enable complete renal pelvis visualization. United States academic medical centers specify these for complex stone burdens, though capital intensity and repair frequency elevate five-year ownership costs substantially.
- Ultra-Flexible:Sub-7 French outer diameters with enhanced torque response navigate tight infundibular angles. Ambulatory surgical centers in Germany and Japan are expanding procurement of these platforms as same-day discharge protocols proliferate.
- Rigid:Fixed-shaft instruments deliver optical clarity without articulation complexity. These serve distal ureteral strictures where straight-line access suffices.
- Semi-Rigid:Hybrid platforms combine proximal shaft rigidity with limited distal flexibility. Community hospitals specify these for mixed diagnostic-therapeutic caseloads.
Established volume favors Flexible; emerging adoption favors Ultra-Flexible.
End User:
Capital allocation authority concentrates differently across facility types, with integrated delivery networks standardizing specifications across hospital campuses while ambulatory sites prioritize equipment mobility and rapid turnaround.
- Hospitals:Tertiary centers maintain diverse ureteroscope inventories spanning flexible, rigid, and laser-integrated platforms. These facilities absorb higher capital depreciation schedules in exchange for comprehensive service line coverage.
- Ambulatory Surgical Centers:Outpatient-focused sites demand compact footprints and streamlined reprocessing workflows. United States metropolitan health systems are consolidating procurement authority across dozens of these facilities.
- Specialty Clinics:Urology-focused practices concentrate on high-throughput stone procedures. Equipment specifications prioritize throughput over versatility.
- Research Institutes:Academic protocols drive early adoption of 4K-resolution sensor platforms and AI-augmented visualization. These sites function as technology validation gatekeepers.
Capital depreciation schedules favor Hospitals; steepest expansion trajectory belongs to Ambulatory Surgical Centers.
Technology:
Image acquisition architectures determine regulatory pathway complexity, with digital platforms requiring FDA 510(k) clearance for sensor upgrades while analog systems face obsolescence pressure from procurement committees.
- Digital:Distal CMOS sensors transmit real-time video to external processors. These platforms are displacing fiberoptic alternatives as health systems refresh endoscopy suites.
- Laser-Assisted:Integrated holmium or thulium fiber channels enable single-device diagnosis and lithotripsy. Stone treatment efficiency drives specification in high-volume centers.
- Analog:Fiberoptic image bundles transmit through eyepiece or camera attachment. Repair economics and image degradation limit remaining procurement.
- Robotic:Motorized articulation with haptic feedback remains in investigational protocols. Regulatory validation timelines extend commercialization horizons.
Procurement momentum favors Digital; investigational positioning favors Robotic.
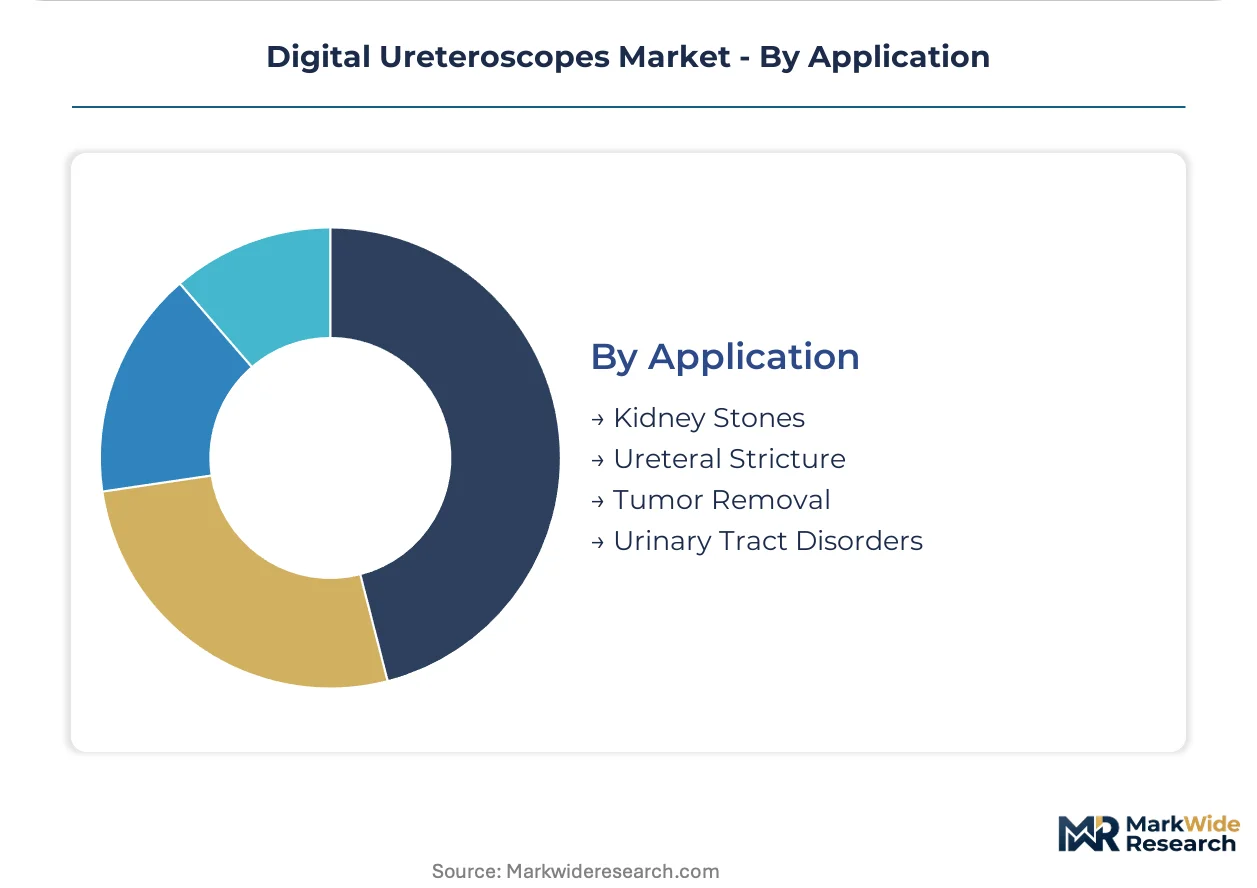
Application:
Procedure complexity and reimbursement differential shape equipment specification, with kidney stone interventions commanding dedicated platform investments while tumor applications demand enhanced imaging fidelity.
- Kidney Stones:Renal calculi extraction represents the dominant procedure volume. Flexible ureteroscopes with integrated laser fibers serve fragmented stone burdens across calyceal distributions.
- Tumor Removal:Urothelial lesion resection demands high-definition tissue differentiation. 4K-resolution platforms are gaining specification in oncology-focused service lines.
- Ureteral Stricture:Benign or iatrogenic narrowing requires graduated dilation and stent placement. Rigid and semi-rigid platforms suffice for distal strictures.
- Urinary Tract Disorders:Diagnostic cystoscopy and retrograde pyelography utilize lower-specification instruments. These procedures tolerate older platform generations.
Procedure volume concentration favors Kidney Stones; imaging fidelity requirements favor Tumor Removal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated health networks in the United States concentrate procurement authority for digital ureteroscopes, while Germany and Japan anchor precision optics supply chains. Ambulatory surgical center expansion in metropolitan clusters drives capital equipment demand across North America and Western Europe.
United States
Academic medical centers in Boston and New York specify 4K-resolution platforms for complex renal pelvis navigation. The FDA's 510(k) pathway provides predictable premarket notification timelines for sensor upgrades. Integrated delivery networks in Texas and California consolidate procurement across dozens of ambulatory sites, standardizing specifications for outpatient-compatible platforms.
Germany
Tertiary urology centers in Munich and Heidelberg pilot AI-augmented visualization workflows for stone detection. The EU Medical Device Regulation imposes strengthened clinical evidence requirements for reusable endoscopic devices. Precision optics manufacturing clusters in Baden-Württemberg and Bavaria supply critical lens components to global assembly lines.
Japan
Metropolitan hospitals in Tokyo and Osaka prioritize ultra-flexible platforms for same-day discharge protocols. METI oversees medical device quality standards that align with international harmonization frameworks. The Nagoya medical technology corridor hosts specialized cleanroom infrastructure for CMOS sensor calibration.
India
Tier-2 city hospitals in Maharashtra and Karnataka expand urology infrastructure as domestic procedure volumes rise. CDSCO regulatory harmonization facilitates import substitution for capital endoscopy equipment. The Delhi-NCR medical device cluster attracts assembly operations targeting price-sensitive procurement committees.
United Kingdom
NHS integrated care systems in London and Manchester evaluate reprocessing-as-a-service models for ambulatory networks. MHRA post-Brexit regulatory pathways diverge from EU MDR timelines for certain device categories. The Cambridge-Oxford medical technology corridor hosts early adopters of robotic-assisted ureteroscope platforms.
Digital Ureteroscopes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The market structure consolidates around diversified medical technology conglomerates with broad urology portfolios, while mid-scale specialists retain share in regional markets. Three archetypes dominate: precision optics integrators, full-spectrum urology platform suppliers, and disposable-device pure-plays. Competitive moves center on backward integration into sensor manufacturing and strategic partnerships with academic medical centers for clinical validation.
Among diversified conglomerates, Boston Scientific Corporation and Olympus Corporation exemplify scale-driven platform strategies, while Karl Storz SE & Co. KG anchors the precision-optics-specialist archetype through captive manufacturing capabilities. These three entities occupy positions across the premium and standard procurement tiers, with their geographic footprints reflecting established regulatory relationships in the United States, Germany, and Japan.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| Richard Wolf GmbH |
| PENTAX Medical |
| Dornier Medtech |
| ELMED Medical Systems |
| NeoScope Inc. |
| Others |
Pricing and Supply Chain Analysis
Frankfurt-Nagoya air freight corridors carry precision optical assemblies and CMOS sensor substrates, with per-kilogram rates directly indexing into landed costs for German and Japanese manufacturers. This logistics cost structure amplifies pricing power for optics suppliers while compressing margins for device assemblers lacking backward integration into sensor fabrication.
Pricing Analysis
Cost-plus contracts with CMOS wafer price indexation dominate procurement between sensor foundries and ureteroscope OEMs. Pricing stratifies across premium 4K-resolution platforms, standard high-definition tiers, and economy fiberoptic alternatives based on image sensor grade and FDA 510(k) clearance tier. Pricing pressure stems from hospital purchasing consortia consolidating procurement authority across ambulatory networks. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize imaging fidelity over unit cost.
Supply Chain Analysis
Upstream feedstock for distal image sensors draws from Taiwan semiconductor foundries, German precision glass manufacturers, and Japanese optical coating specialists. Critical inputs span CMOS wafers, gradient-index lenses, and flexible polymer sheaths. Single-source vulnerability concentrates in sub-millimeter lens grinding capacity located in Baden-Württemberg. Distribution runs through authorized dealer networks serving integrated delivery networks and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital ureteroscopes sit at an inflection where CMOS sensor migration and EU MDR clinical evidence requirements simultaneously accelerate product obsolescence and extend certification timelines. This compression rewards manufacturers with captive sensor supply and punishes pure-play assemblers.
For Market Incumbents: Pre-empt disposable ureteroscope entrants by accelerating single-use platform launches before infection control committees finalize procurement specifications. Lock in multi-year sensor supply agreements with Taiwan foundries to neutralize allocation risk during capacity crunches. Deepen backward integration into precision optics manufacturing to defend margin position against German and Japanese component suppliers. For New Entrants and Emerging Players: Build out reprocessing-as-a-service capabilities targeting ambulatory surgical centers seeking to eliminate fixed biomedical engineering overhead. India's tier-2 city hospital buildout offers the most penetrable geography as CDSCO harmonization reduces import friction. Lead with laser-integrated digital platforms rather than competing on flexible articulation where Olympus and Karl Storz hold technical moats. For Investors and Strategic Acquirers: Disposable-device pure-plays with FDA-cleared single-use platforms represent the highest-conviction acquisition archetype as hospital infection control mandates harden. Long-term viability hinges on sustained R&D throughput to match sensor generation cycles. Watch for FDA 510(k) clearance velocity as the signal distinguishing scalable platforms from stranded technology bets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses time-to-market for CMOS sensor upgrades against regulatory bandwidth constraints. |
| CE Marking Pathway Investment | Secures notified body relationships ahead of EU MDR clinical evidence requirement intensification. |
| Hospital System Partnership | Locks in ambulatory surgical center procurement specifications across integrated delivery networks. |
| Software Companion Development | Integrates AI-augmented stone detection algorithms with 4K-resolution platform video feeds. |
| Reimbursement Strategy | Aligns device coding with same-day discharge protocol expansion in urology service lines. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with urology department heads, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers informed demand-side dynamics. Secondary sources encompass FDA 510(k) clearance databases, EU MDR notified body registers, hospital procurement transaction records, and ISO 13485 certification registries. Bottom-up procedure volume estimates triangulate against top-down capital equipment depreciation schedules.
Calibration against historical sensor upgrade cycles and replacement window patterns shapes the analytical framework across the projection horizon. Segmentation dimensions span product flexibility tier, end-user facility type, image acquisition technology, and target application. CAGRs derive from installed base growth rates and average selling price trajectory assumptions. Forecast inputs incorporate ambulatory surgical center expansion timelines and FDA premarket notification velocity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by single-use disposable entrants or AI-integrated platform specialists would shift outcomes. Cross-checking against hospital capital expenditure survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Coronary Guidewires Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Syringe Filling Machine Market
Medical Devices
Lactation Massager Market
Medical Devices
Nasal Implant Market
Medical Devices
Europe Ventilator Market
Medical Devices
Oxygen Therapy Devices Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Global Foley Catheters Market
Medical Devices
Hybrid Microcirculation Detector Market
Medical Devices
Mexico Respiratory Devices Market
Medical Devices
Endoscopic Mucosal Resection Device Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Europe Breast Implant Market