
 Brazil Nuclear Imaging Market | 2026-2036
Brazil Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Nuclear Imaging Market Outlook
ANVISA's Good Manufacturing Practice requirements for radiopharmaceuticals is hardening compliance thresholds for imported imaging agents. GE Healthcare leverages its cyclotron network to sustain domestic isotope supply reliability. Siemens Healthineers anchors its position through R&D intensity in PET-CT detector arrays. Koninklijke Philips N.V. competes on hybrid imaging platforms that integrate functional and anatomical scanning protocols.
Brazil nuclear imaging encompasses diagnostic systems utilizing gamma-emitting radiotracers to visualize metabolic and physiological processes, with SPECT and PET technologies detecting gamma ray emissions through sodium iodide crystal detectors or lutetium-based scintillators to reconstruct tomographic images. PET scanners command premium positioning due to fluorodeoxyglucose-based oncology protocols requiring cyclotron-produced isotopes with half-lives under two hours. Diagnostic Centers represent the fastest-growing end user segment as outpatient imaging chains expand fluorine-18 capacity outside hospital procurement frameworks. Oncology applications concentrate margin pools through theranostic pairing of diagnostic tracers with lutetium-177 radioligand therapies.
ANVISA governs radiopharmaceutical licensing and facility certification, while the Brazilian National Nuclear Energy Commission oversees radioactive material transport and waste disposal protocols. ISO 13485 compliance shapes quality management expectations for imported gamma camera and PET system components. Stakeholders must monitor cyclotron infrastructure investments against import dependency for molybdenum-99 generators.
Market Dynamics
ANVISA's Good Manufacturing Practice requirements for radiopharmaceuticals are hardening compliance thresholds and forcing domestic cyclotron investments to reduce import dependency for short-half-life isotopes.
Growth Catalysts
- ANVISA Streamlined Import Protocols:The regulatory body has accelerated radiopharmaceutical clearance timelines, enabling tertiary hospitals in São Paulo to expand PET-CT procurement cycles.
- Theranostic Pairing:Oncology departments are integrating diagnostic tracers with lutetium-177 radioligand therapies, creating bundled revenue streams across diagnostic and therapeutic workflows.
- Southeast Corridor Concentration:Diagnostic networks in São Paulo and Rio de Janeiro states are consolidating fluorine-18 production capacity outside traditional hospital procurement frameworks.
Market Restraints
- Molybdenum-99 Import Dependency:Brazil lacks domestic technetium-99m generator production, exposing imaging centers to supply disruptions from foreign reactor facilities.
- Cyclotron Capital Intensity:Each fluorine-18 production facility requires substantial upfront investment in particle acceleration infrastructure and shielded vault construction.
- ANVISA Licensing Friction:Facility certification timelines for new nuclear medicine centers often extend eighteen to twenty-four months, delaying market entry for independent operators.
Strategic Opportunities
- Northeast Region Underpenetration:Bahia and Pernambuco states currently host minimal PET-CT density, presenting first-mover advantages for outpatient imaging chains.
- Hybrid Imaging Convergence:PET-MRI systems are penetrating cardiology departments seeking simultaneous functional and soft-tissue assessment without sequential scanning protocols.
- Diagnostic Center Channel Expansion:Fleury and DASA flagship networks are unbundling imaging services from hospital admissions, creating standalone fluorodeoxyglucose referral pathways.
Industry Challenges
- Radiopharmacist Talent Scarcity:Brazilian universities produce insufficient cyclotron operators and radiopharmaceutical chemists to staff expanding production facilities.
- Legacy SPECT Integration Complexity:Hospital IT departments struggle to merge sodium iodide gamma camera data streams with modern PACS architectures.
- Radioactive Waste Handling Certification:The Brazilian National Nuclear Energy Commission mandates specialized transport protocols that extend operational training cycles for new technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Nuclear Imaging Market |
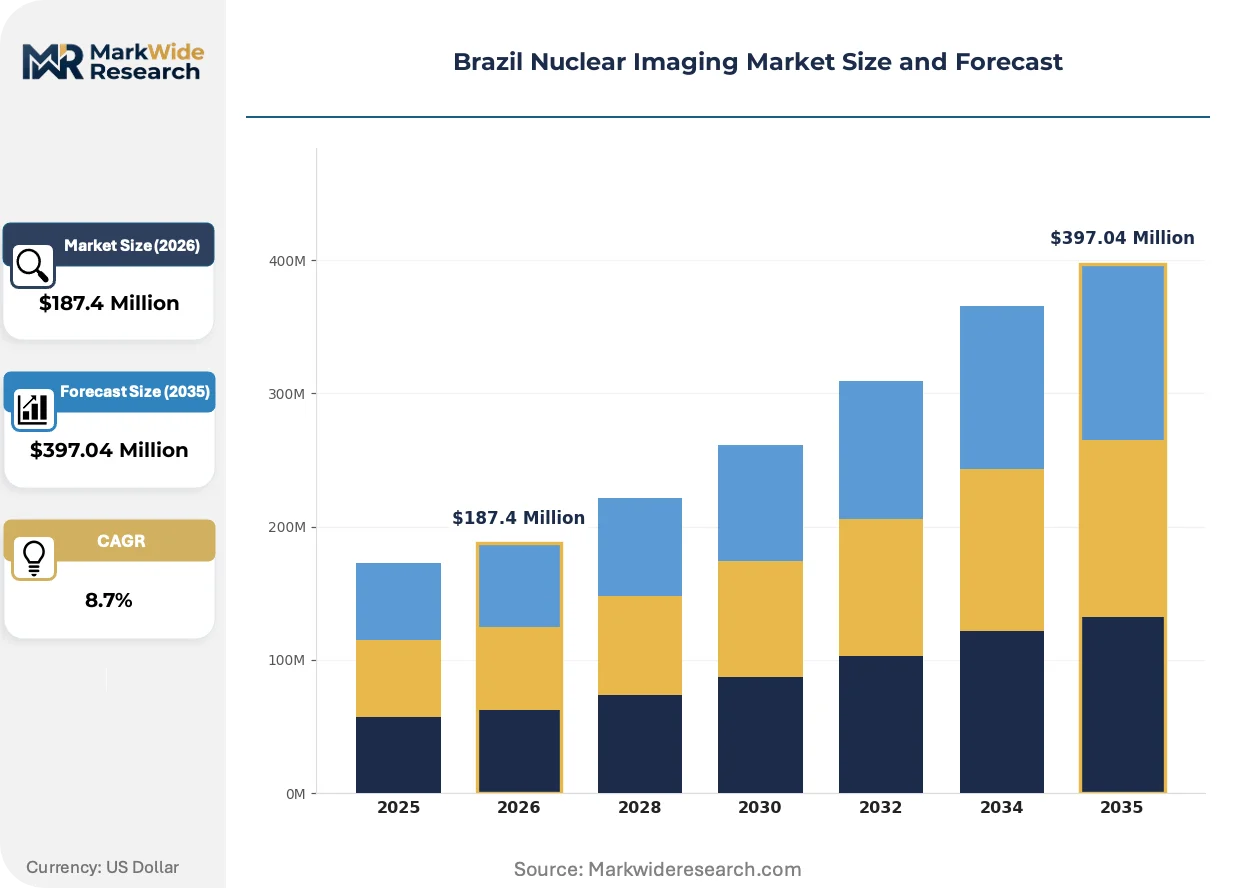
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Cameras, SPECT Systems, PET Scanners, Radiopharmaceuticals End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Technology: Single Photon Emission Computed Tomography, Positron Emission Tomography, Hybrid Imaging, Advanced Detectors Application: Oncology, Cardiology, Neurology, Infectious Diseases |
| Companies Covered | GE Healthcare, Siemens Healthineers AG, Koninklijke Philips N.V., Canon Inc., Grupo RPH, Bayer AG, Fujifilm Holdings Corporation, DASA, Fleury, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Nuclear Imaging Market Strategic Shifts
Digital detector arrays and artificial intelligence reconstruction algorithms are compressing scan times while improving lesion detectability, fundamentally altering throughput economics for high-volume imaging centers.
Lutetium-based scintillators are replacing traditional sodium iodide crystals in SPECT systems, delivering superior energy resolution for technetium-99m and iodine-123 protocols. Cardiology departments in Belo Horizonte and Curitiba are adopting these detectors to reduce myocardial perfusion imaging acquisition times. This hardware transition is converging with AI-powered motion correction software to enable stress-rest protocols in single-session appointments.
ANVISA's updated Resolution RDC 304/2019 imposes serialization requirements on imported radiopharmaceutical batches, mandating end-to-end traceability from foreign manufacturing sites to Brazilian administration. Imaging centers must now maintain chain-of-custody documentation spanning temperature logging and radiation dose verification. Diagnostic networks in the Southeast corridor are responding by consolidating supplier relationships with cyclotron-equipped multinationals capable of integrated compliance reporting.
Outpatient imaging chains are disintermediating traditional hospital-based referral networks through direct-to-oncologist marketing and bundled pricing for staging protocols. Fleury and DASA flagship centers now contract directly with oncology practices in São Paulo's Brooklin and Vila Olímpia districts, bypassing hospital radiology departments entirely. This channel fragmentation is most visible in private insurance segments where prior authorization requirements are less restrictive than public reimbursement pathways.
Brazil Nuclear Imaging Market Segmentation
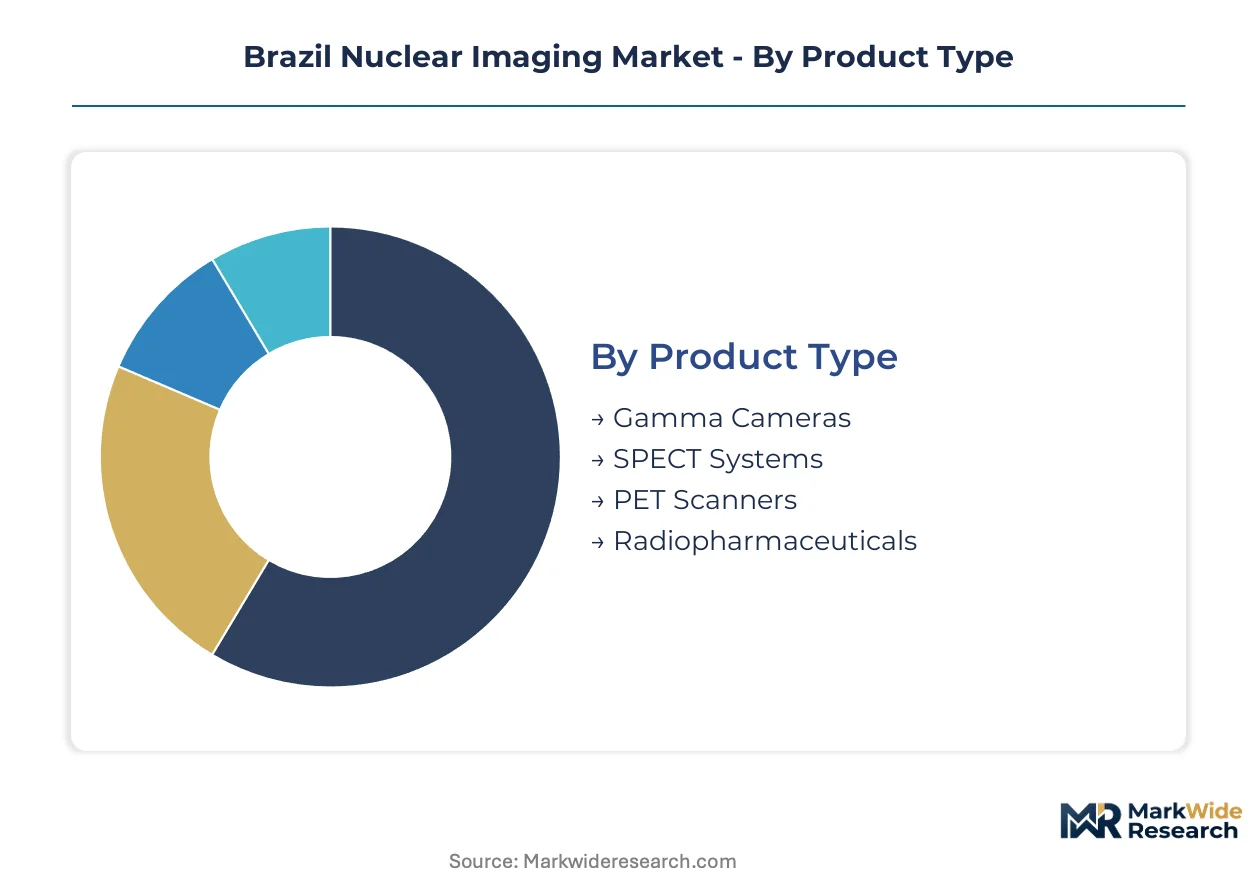
Brazil's nuclear imaging segmentation reflects a bifurcation between capital-intensive hardware procurement and consumable radiopharmaceutical supply chains. Product and end-user categories reveal distinct margin profiles, with diagnostic centers capturing volume growth while hospitals retain premium technology access. Technology and application segments track the migration from standalone SPECT toward integrated PET-CT and theranostic protocols.
Product Type:
Gamma cameras operate as embedded workhorses within hospital nuclear medicine departments, while PET scanners demand standalone infrastructure investments with cyclotron tethering.
- Gamma Cameras:Sodium iodide crystal detectors mounted on rotating gantries deliver planar and limited tomographic imaging for technetium-99m protocols. Demand concentrates in São Paulo's public hospital networks where procurement budgets favor refurbishment over replacement cycles.
- PET Scanners:Lutetium-based scintillator rings with coincidence detection electronics reconstruct fluorodeoxyglucose distribution for oncology staging. Tertiary hospitals in Rio de Janeiro and São Paulo anchor placements, driven by ANVISA's streamlined radiopharmaceutical import protocols that reduce isotope delivery uncertainty.
- SPECT Systems:Dual-head gamma camera configurations with CT attenuation correction enable myocardial perfusion and bone scintigraphy. Diagnostic centers in Belo Horizonte and Curitiba favor these systems for their lower shielding requirements and operational simplicity.
- Radiopharmaceuticals:Cyclotron-produced fluorine-18 fluorodeoxyglucose and generator-derived technetium-99m constitute the consumable backbone. Fleury and DASA networks are consolidating captive production capacity to bypass import dependency for short-half-life isotopes.
Volume placements concentrate in SPECT Systems; the faster expansion belongs to PET Scanners.
End User:
Cost tier stratification separates capital-rich hospital procurement from leaner diagnostic center operating models focused on throughput economics.
- Hospitals:Tertiary and quaternary institutions with on-site cyclotron infrastructure or dedicated radiopharmacy partnerships. São Paulo's Hospital das Clínicas and Albert Einstein anchor the premium segment through academic research alignment and complex case referral.
- Diagnostic Centers:Standalone outpatient facilities unbundling imaging from hospital admissions. Brooklin and Vila Olímpia districts in São Paulo host the densest concentration, with direct-to-oncologist contracting bypassing traditional radiology department gatekeeping.
- Research Institutions:University hospitals and CNPq-funded centers conducting clinical trials for novel radiotracers. These sites operate under distinct ANVISA licensing frameworks for investigational compounds.
- Outpatient Facilities:Smaller imaging suites within medical office buildings serving insured populations. These sites typically lease SPECT capacity rather than owning equipment, minimizing capital exposure.
Hospital infrastructure dominates current installed base; diagnostic centers are climbing the fastest as outpatient channel fragmentation accelerates.
Technology:
Maturity gradients separate legacy single-photon systems from convergent hybrid platforms requiring fused hardware-software integration.
- Single Photon Emission Computed Tomography:Gamma camera-based tomography using technetium-99m and iodine-123 tracers. Remains prevalent in Northeast Brazil where capital constraints delay PET adoption.
- Positron Emission Tomography:Coincidence detection of positron annihilation photons from fluorine-18 and carbon-11 labeled compounds. Southeast corridor concentration reflects cyclotron proximity requirements and isotope logistics optimization.
- Hybrid Imaging:PET-CT and emerging PET-MRI systems combining functional and anatomical data acquisition. Cardiology departments in Curitiba are piloting PET-MRI for simultaneous myocardial perfusion and tissue characterization without sequential scanning.
- Advanced Detectors:Lutetium-yttrium oxyorthosilicate and lutetium-based scintillators replacing sodium iodide crystals. These detectors reduce acquisition times and improve energy resolution for high-volume centers.
Single Photon Emission Computed Tomography retains the largest installed footprint; hybrid imaging platforms show the steepest expansion trajectory.
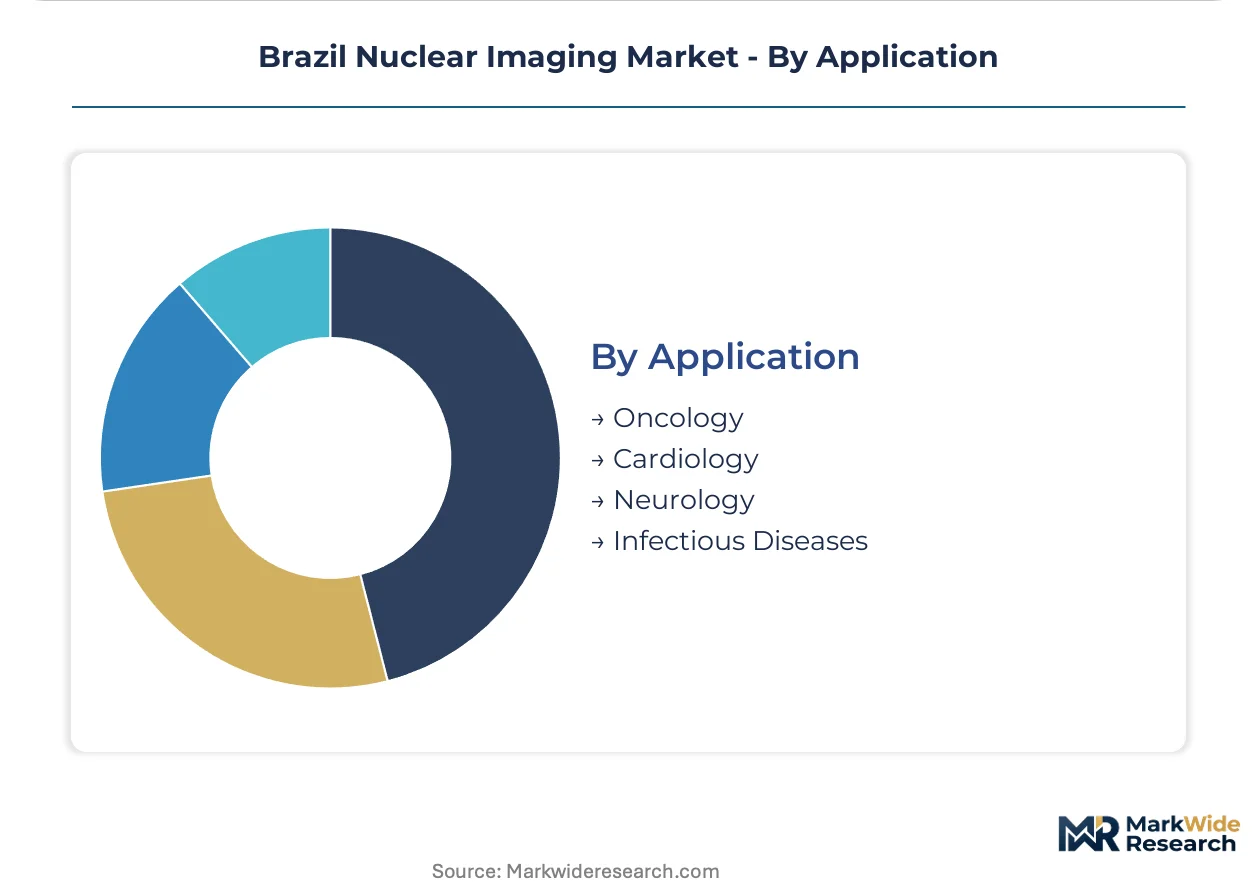
Application:
Margin concentration follows oncology's theranostic pairing potential, while cardiology and neurology operate on more commoditized reimbursement schedules.
- Oncology:Staging and restaging of solid tumors through FDG-PET, with emerging lutetium-177 radioligand therapy integration. São Paulo's private oncology practices drive the highest scan volumes per machine.
- Cardiology:Myocardial perfusion imaging for coronary artery disease assessment using stress-rest technetium-99m protocols. Belo Horizonte's cardiology-focused diagnostic chains specialize in same-day appointment completion.
- Neurology:Dementia differential diagnosis through fluorodeoxyglucose hypometabolism patterns and Parkinson's disease imaging with dopaminergic tracers. Academic medical centers concentrate this lower-volume, higher-complexity segment.
- Infectious Diseases:White blood cell labeling for osteomyelitis and fever of unknown origin workups. Limited to reference hospitals with specialized radiopharmacy capabilities.
Oncology commands the premium pricing tier; diagnostic centers are gaining share fastest in cardiology through streamlined outpatient protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Brazil's nuclear imaging infrastructure through its dense concentration of tertiary hospitals and outpatient diagnostic networks in Brooklin and Vila Olímpia districts.
São Paulo
Hospital das Clínicas and Albert Einstein drive PET-CT procurement cycles through academic research alignment. ANVISA's streamlined radiopharmaceutical import protocols reduce isotope delivery uncertainty for these institutions. Fleury and DASA operate flagship diagnostic networks that consolidate fluorine-18 production capacity outside traditional hospital frameworks.
Rio de Janeiro
Tertiary hospitals in Rio de Janeiro state expand hybrid imaging procurement as private oncology practices drive staging protocol volumes. The Brazilian National Nuclear Energy Commission oversees radioactive material transport through the state's port facilities. Diagnostic chains concentrate in Barra da Tijuca and Centro districts, bypassing hospital radiology departments through direct-to-specialist contracting.
Minas Gerais
Belo Horizonte's cardiology-focused diagnostic chains specialize in same-day myocardial perfusion imaging appointments using SPECT systems. ANVISA facility certification timelines extend market entry for independent operators in this state. The city hosts specialized centers adopting lutetium-based scintillators to reduce acquisition times for technetium-99m protocols.
Paraná
Curitiba's cardiology departments pilot PET-MRI systems for simultaneous myocardial perfusion and tissue characterization without sequential scanning. ISO 13485 compliance shapes quality management expectations for imported system components entering through the state's logistics corridors. Diagnostic centers favor SPECT-CT configurations for their lower shielding requirements and operational simplicity.
Bahia
Salvador and surrounding municipalities present first-mover advantages for outpatient imaging chains given minimal existing PET-CT density. ANVISA licensing friction delays facility certification for new nuclear medicine centers by eighteen to twenty-four months. The state's public hospital networks rely on refurbished gamma camera systems rather than replacement cycles.
Brazil Nuclear Imaging Market Competitive Environment
The competitive structure tilts toward multinational imaging system manufacturers with cyclotron-equipped supply networks. Three archetypes dominate: integrated hardware-radiopharmaceutical conglomerates, standalone diagnostic service networks, and regional radiopharmaceutical distributors. Consolidation pressures favor players with captive isotope production capacity. Competitive moves center on cyclotron infrastructure investments and direct-to-oncologist channel expansion.
Among the integrated conglomerates, GE Healthcare, Siemens Healthineers AG, and Koninklijke Philips N.V. represent the dominant hardware archetype. These manufacturers anchor market positioning through detector array R&D and hybrid imaging platform development. DASA and Fleury exemplify the diagnostic service network model, unbundling imaging from hospital admissions through standalone fluorodeoxyglucose referral pathways.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Canon Inc. |
| Grupo RPH |
| Bayer AG |
| Fujifilm Holdings Corporation |
| DASA |
| Fleury |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up diagnostic networks in Brazil's Southeast corridor wield consolidated purchasing power to extract volume discounts from cyclotron-equipped multinationals, while their captive fluorine-18 production insulates them from import-driven price volatility that squeezes independent imaging centers. This ownership concentration translates into tiered procurement leverage where scale determines access to shielded isotope supply and bundled hardware-software pricing.
Pricing Analysis
Outcome-based pricing anchored to scan throughput per machine hour dominates the Brazilian market, with diagnostic centers negotiating per-procedure rates tied to guaranteed minimum volumes. Price differentiation rests on cyclotron proximity and ANVISA certification tier, as facilities with captive isotope production command premium positioning over import-dependent operators. Pricing pressure intensifies in the SPECT segment as refurbished gamma cameras flood public hospital procurement, while PET-CT placements resist compression due to fluorodeoxyglucose supply scarcity. Hospital systems exhibit lowest price sensitivity given academic research budgets and complex case premiums, whereas outpatient imaging chains in São Paulo's Brooklin district face acute margin scrutiny from direct-to-oncologist contracting.
Supply Chain Analysis
Refurbishment flows for sodium iodide gamma cameras originate from São Paulo's tertiary hospital networks and redistribute to Bahia's public facilities, creating a secondary equipment market that delays new system procurement. Primary supply concentrates in the United States, Germany, and the Netherlands for PET detector arrays and cyclotron components, while molybdenum-99 generators draw from Canadian and European reactor facilities. Raw material dependencies span lutetium-based scintillators, high-purity sodium iodide crystals, and specialized shielding alloys. Single-source vulnerability pervades the technetium-99m generator channel, where aging foreign reactors expose Brazilian imaging centers to supply interruptions. Distribution runs through authorized dealer networks with ANVISA-licensed radiopharmacy partnerships, bypassing direct manufacturer-to-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's nuclear imaging market operates under supply-constrained conditions where cyclotron infrastructure scarcity props pricing power for incumbent diagnostic networks. Fluorine-18 production capacity bottlenecks in the Northeast and Central-West regions sustain premium capture for Southeast-based operators with captive isotope supply.
For Market Incumbents: Acquire cyclotron-equipped production facilities in underpenetrated states to preempt import dependency risks and consolidate radiopharmaceutical supply control. DASA and Fleury should deepen backward integration into lutetium-177 radioligand therapy manufacturing to capture theranostic margin pools, while defending against emerging outpatient chains through exclusive oncology practice contracting in São Paulo's Vila Olímpia district.
For New Entrants and Emerging Players: Begin with SPECT-CT deployments in Bahia and Pernambuco where PET-CT density remains minimal and ANVISA licensing timelines create incumbent protection. The diagnostic center channel in Salvador offers lowest competitive intensity, with direct contracting to private oncology practices in Recife providing a viable go-to-market angle bypassing hospital radiology gatekeepers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cyclotron-equipped mid-cap specialists in Minas Gerais and Paraná where capital constraints delay independent facility certification. Long-term viability hinges on theranostic integration capabilities across the next decade, with acquisition targets requiring demonstrated radiopharmaceutical chemistry expertise. Monitor ANVISA Resolution RDC amendments for early signals of import protocol liberalization that would erode captive production premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Infrastructure Expansion | Captive fluorine-18 production insulates margins from foreign reactor supply disruptions. |
| Theranostic Platform Development | Lutetium-177 radioligand therapy pairing creates bundled diagnostic-therapeutic revenue streams. |
| Direct-to-Oncologist Channel Buildout | Bypassing hospital radiology departments accelerates patient throughput in private insurance segments. |
| ANVISA Certification Investment | Accelerated facility licensing reduces eighteen-month market entry delays for independent operators. |
| Hybrid Imaging System Procurement | PET-MRI convergence in Curitiba cardiology departments enables single-session functional assessment. |
Study Parameters
ANVISA regulatory filings, Brazilian National Nuclear Energy Commission transport permits, and hospital procurement databases formed the secondary backbone for market sizing and competitive positioning. Primary interviews with cyclotron operations managers, nuclear medicine department heads at Hospital das Clínicas and Albert Einstein, diagnostic center network procurement directors, and radiopharmaceutical distribution specialists validated installed base estimates and pricing dynamics. Bottom-up triangulation across equipment shipment records and top-down reconciliation against healthcare expenditure flows ensured segmentation integrity.
Historical trendline analysis of PET-CT and SPECT system placements across São Paulo, Rio de Janeiro, Minas Gerais, Paraná, and Bahia established baseline penetration rates. The analytical framework modeled technology migration from standalone gamma cameras toward hybrid imaging platforms, end-user shift from hospital-based to diagnostic center channels, and application concentration in oncology staging protocols. CAGRs derived from regression-adjusted growth curves incorporating cyclotron capacity expansion timelines and ANVISA regulatory velocity. Forecast inputs included radiopharmacist graduation rates from Brazilian universities and import dependency ratios for molybdenum-99 generators.
Underlying measurement precision varies by segment; PET scanner placements and fluorodeoxyglucose production volumes carry tighter precision than refurbished SPECT system flows in public hospital networks. Forecasts reflect assumptions regarding ANVISA licensing efficiency and foreign reactor reliability that could shift materially with regulatory amendments or supply chain disruptions. Practitioners should monitor cyclotron commissioning announcements in the Northeast region and ANVISA Resolution RDC revision cycles for early signals of competitive intensity changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
South America MRI Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
North America Digital Radiology Market