
 India Digital X-Ray Market | 2026-2036
India Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
India Digital X-Ray Market Foresight
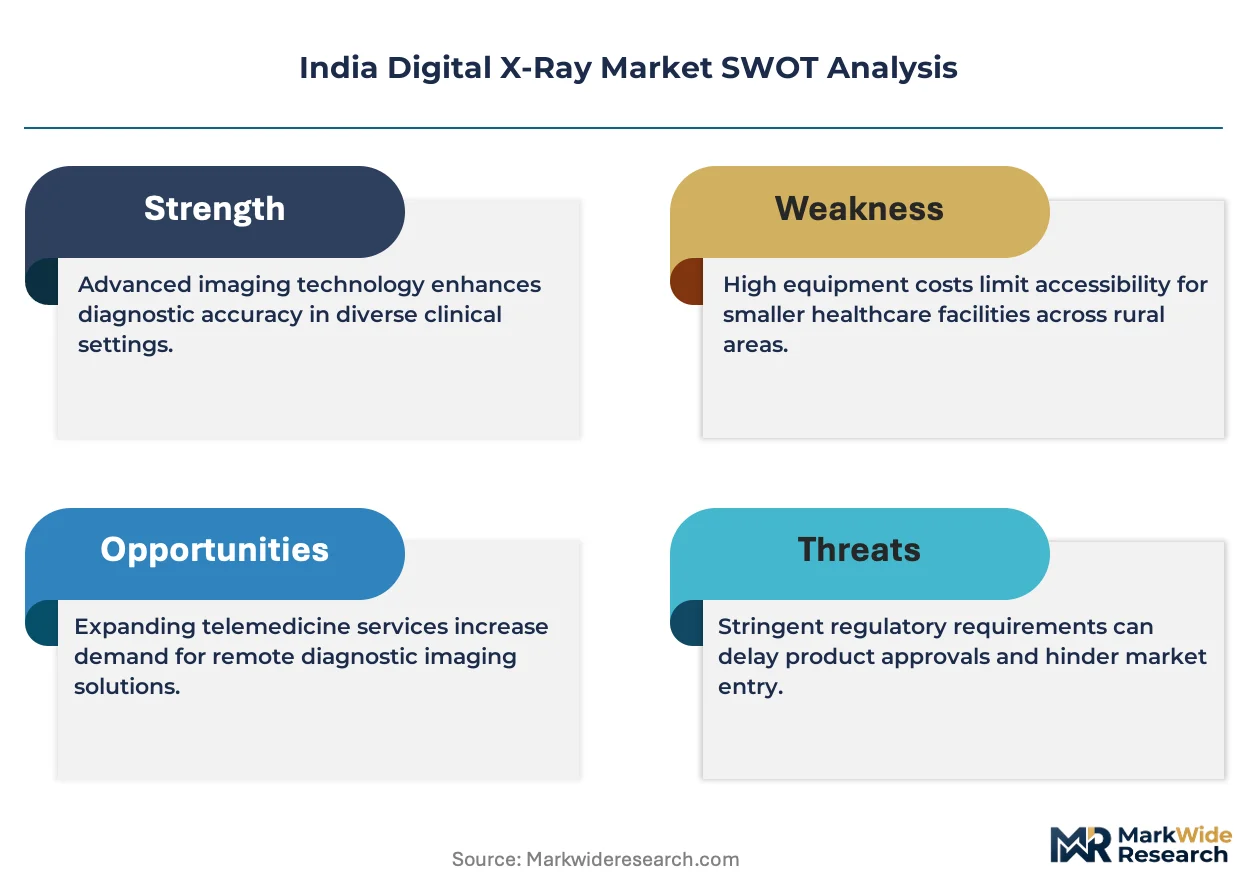
India's PLI scheme for medical devices is realigning capital allocation across the radiology supply chain, pushing domestic assembly of digital detector panels and reducing import dependence on Korean and Japanese sensor suppliers. Siemens Healthcare Private Limited leverages its Bengaluru engineering center to sustain R&D localization for mid-range digital radiography systems tailored to Indian price points. Allengers Medical Systems Limited anchors its position through backward integration into high-voltage generator production, while Canon India Pvt Ltd competes on channel density across tier-three cities.
Digital X-ray systems employ flat-panel detectors with cesium iodide or gadolinium oxysulfide scintillator layers coupled to thin-film transistor arrays, converting X-ray photons directly into digital images for immediate display and archival. Portable X-Ray systems lead volume shipments as India's Ayushman Bharat health infrastructure expands bed capacity in semi-urban facilities, while Direct Radiography captures the fastest technology trajectory due to superior dose efficiency and workflow speed. Fixed X-Ray installations dominate margin pools in tertiary-care settings where cardiovascular and interventional applications require ceiling-suspended tube stands and automated positioning.
CDSCO governs device licensing under the Medical Device Rules, while BIS certification mandates electromagnetic compatibility and radiation safety standards for all domestically sold radiography equipment. The CEA regulates installation safety protocols for high-kilovoltage equipment in hospital settings, creating compliance barriers that favor established suppliers with dedicated Indian regulatory affairs teams. Stakeholders must monitor how India's proposed medical device pricing authority intersects with PLI-linked local value-addition requirements to determine viable sourcing strategies for detector assemblies.
Market Dynamics
India's PLI scheme for medical devices is compressing import dependence on Korean and Japanese flat-panel detector suppliers by incentivizing domestic assembly of digital imaging components. This policy lever is redirecting capital toward Bengaluru and Chennai manufacturing clusters while realigning procurement patterns across Maharashtra and Tamil Nadu hospital networks.
Growth Catalysts
- Ayushman Bharat infrastructure rollout:Bed capacity expansion in semi-urban facilities is generating volume demand for portable digital radiography systems.
- CDSCO licensing streamlining:The Medical Device Rules framework is reducing regulatory friction for Class B and C radiography equipment registrations.
- Orthopedic trauma care concentration:Corporate hospital chains are consolidating imaging procurement around digital X-ray for musculoskeletal diagnostics.
Market Restraints
- Flat-panel detector import concentration:Cesium iodide and gadolinium oxysulfide scintillator layers remain dominated by Korean and Japanese component suppliers.
- CEA installation protocols:High-kilovoltage equipment safety mandates create compliance barriers favoring established vendors with dedicated regulatory affairs teams.
- Computed radiography substitution:Legacy phosphor plate systems persist in cost-constrained district hospitals, delaying full digital migration.
Strategic Opportunities
- Tier-three city channel penetration:Density gaps in Uttar Pradesh and Bihar imaging infrastructure create whitespace for portable system distributors.
- Direct radiography technology convergence:Thin-film transistor array improvements are enabling dose-efficient retrofit kits for existing analog installations.
- PLI-linked local value-addition:Backward integration into high-voltage generator production qualifies manufacturers for enhanced incentive tiers.
Industry Challenges
- Biomedical engineering talent scarcity:Thin-film transistor array calibration and detector maintenance skills concentrate in Bengaluru and Hyderabad, constraining rural service coverage.
- BIS electromagnetic compatibility certification timelines:Testing bottlenecks at designated laboratories extend product launch cycles for new radiography system entrants.
- Legacy analog workflow integration:PACS connectivity standards vary across corporate hospital chains, complicating enterprise-wide digital imaging deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Digital X-Ray Market |
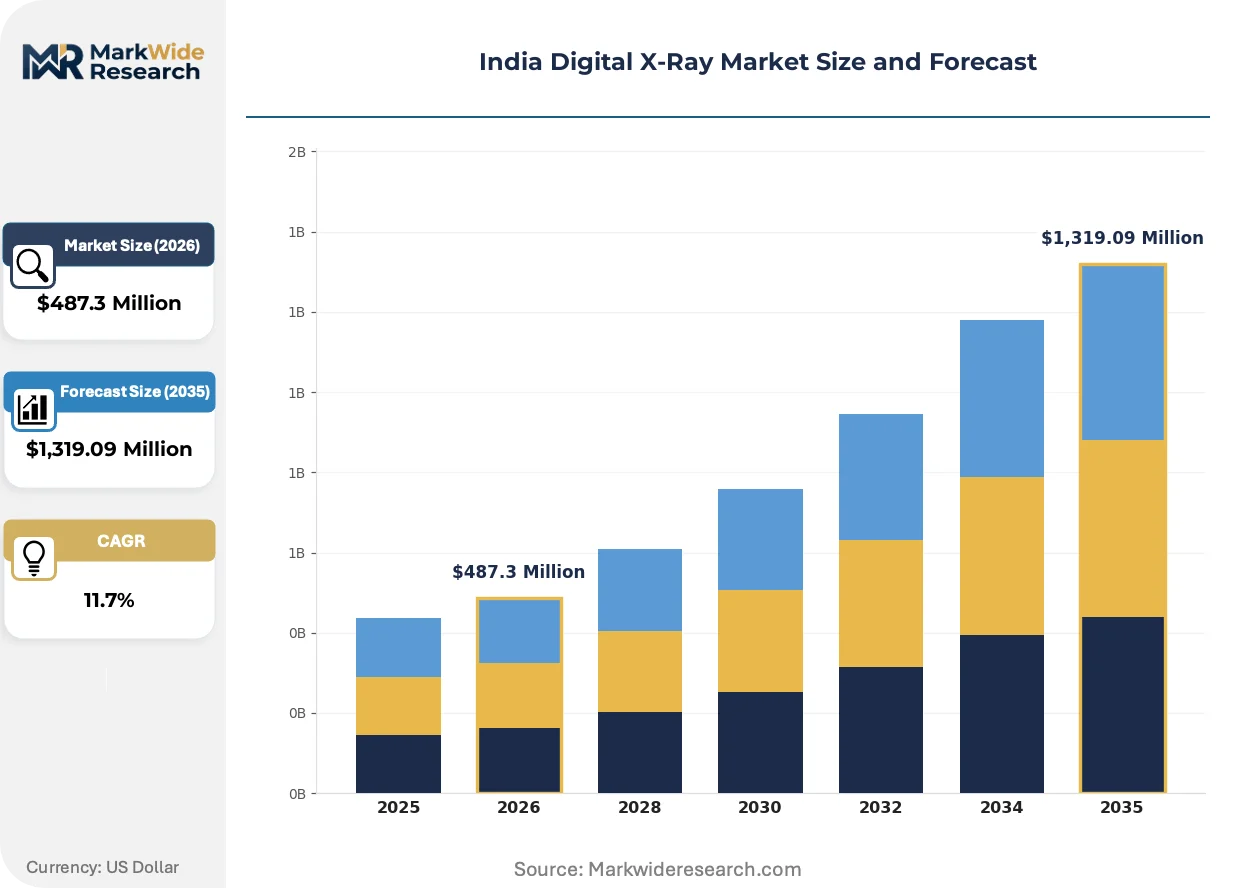
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable X-Ray, Fixed X-Ray, Handheld X-Ray, Analog X-Ray Technology: Computed Radiography, Direct Radiography, Digital Imaging, Wireless Technology End User: Hospitals, Diagnostic Centers, Clinics, Research Laboratories Application: Orthopedics, Dental, Cardiovascular, Surgical |
| Companies Covered | Carestream Health Inc., Canon India Pvt Ltd, Siemens Healthcare Private Limited, Allengers Medical Systems Limited, Shimadzu Medical (India) Pvt. Ltd., GE HealthCare Technologies Inc., FUJIFILM India Private Limited, Agfa-Gevaert Group, Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Digital X-Ray Market Shifts & Advancements
Artificial intelligence inference engines are embedding directly into digital radiography acquisition workstations, automating exposure parameter selection and preliminary image quality assessment. This convergence is compressing radiographer training requirements while elevating diagnostic consistency across high-throughput screening programs.
Wireless flat-panel detectors with integrated battery systems are integrating into mobile C-arm configurations for intraoperative imaging. Orthopedic surgical centers in Mumbai and Delhi are adopting these configurations for trauma and joint replacement workflows. The technology is integrating surgical and diagnostic imaging into unified equipment procurement decisions, blurring traditional capital budget categories.
BIS certification mandates for electromagnetic compatibility and radiation safety are tightening testing protocols for all domestically sold radiography equipment. The standards are elevating compliance costs for imported systems while creating preference pull toward domestically assembled units with pre-certified component architectures. Tier-two hospital procurement committees are prioritizing BIS-marked equipment to preempt CEA installation approval delays.
Corporate hospital chains are consolidating imaging equipment purchasing through centralized tender processes, displacing decentralized department-level procurement. Radiology heads at Apollo, Max, and Fortis networks are negotiating enterprise-wide service contracts with single-source vendors. This concentration is most visible in Karnataka and Telangana, where hospital chain density enables volume-based pricing leverage.
India Digital X-Ray Market Segmentation
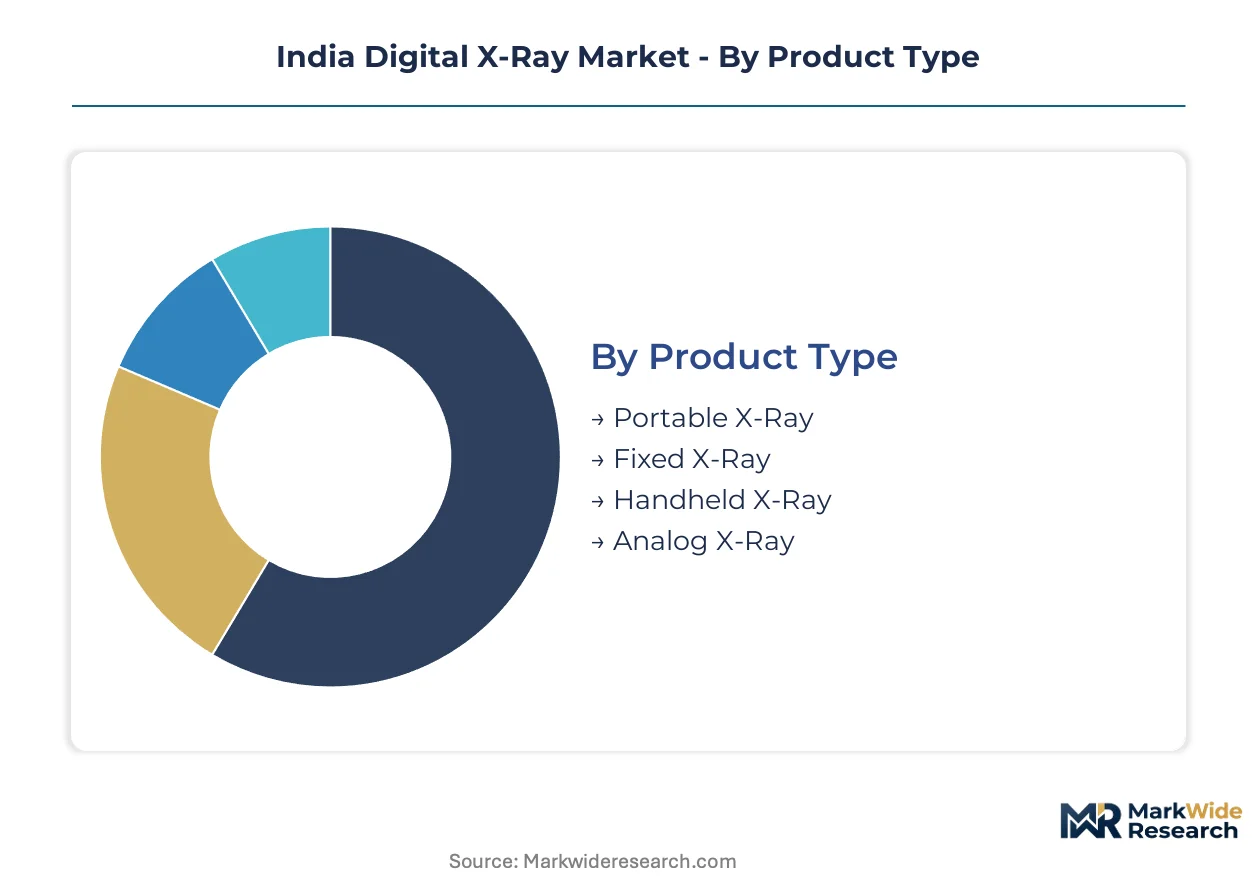
Digital X-ray segmentation in India reflects divergent procurement logics across facility tiers, with technology choices directly tied to infrastructure maturity and patient throughput requirements. Understanding these axes clarifies where capital deployment concentrates and which specifications command pricing premiums.
Product Type:
System mobility defines procurement priorities across India's hospital network, with bed capacity expansion and workflow efficiency driving divergent equipment selections.
- Portable X-Ray:Battery-powered mobile units with wireless detector panels enable bedside imaging in crowded wards and emergency settings. Maharashtra and Tamil Nadu district hospitals are accelerating orders as Ayushman Bharat infrastructure expands semi-urban bed capacity.
- Fixed X-Ray:Ceiling-suspended tube stands with automated positioning dominate tertiary-care installations where cardiovascular and interventional applications require sub-millimeter precision. Corporate hospital chains in Karnataka and Telangana consolidate procurement around these configurations for high-throughput radiology departments.
- Handheld X-Ray:Compact battery-operated units serve point-of-care screening in remote clinics with unreliable grid power.
- Analog X-Ray:Film-based systems persist in cost-constrained facilities awaiting digital upgrade cycles.
Fixed systems lead on scale; portable systems lead on momentum.
Technology:
Imaging modality selection hinges on dose efficiency, workflow speed, and compatibility with existing PACS infrastructure across Indian healthcare networks.
- Direct Radiography:Flat-panel detectors with cesium iodide scintillator layers convert X-ray photons directly into digital signals, eliminating intermediate processing steps. Corporate hospital chains favor this technology for orthopedic trauma workflows where rapid image availability compresses treatment timelines.
- Computed Radiography:Photostimulable phosphor plate systems offer lower capital entry points for district hospitals transitioning from analog film. Uttar Pradesh and Bihar facilities delay full digital migration due to budget constraints and legacy technician training.
- Digital Imaging:Software-defined acquisition and post-processing suites integrate with hospital information systems for enterprise-wide archival.
- Wireless Technology:Detector-to-workstation transmission via secure protocols reduces cabling infrastructure in retrofit installations.
Direct Radiography commands margin premiums; Computed Radiography retains volume share in cost-sensitive segments.
End User:
Facility type determines equipment specifications, service contract structures, and financing mechanisms across India's fragmented provider landscape.
- Hospitals:Multi-department installations require enterprise-grade PACS integration and 24-hour service response guarantees. Tier-two and district hospitals in Maharashtra and Tamil Nadu are accelerating procurement of digital radiography systems under government health infrastructure programs.
- Diagnostic Centers:High-throughput standalone imaging chains prioritize rapid patient turnaround and teleradiology connectivity for remote reporting.
- Clinics:Single-physician practices favor compact footprint systems with minimal shielding requirements.
- Research Laboratories:Specialized preclinical imaging configurations support pharmaceutical and materials science applications.
Hospitals absorb the largest capital allocation; diagnostic centers are expanding most quickly in tier-three cities.
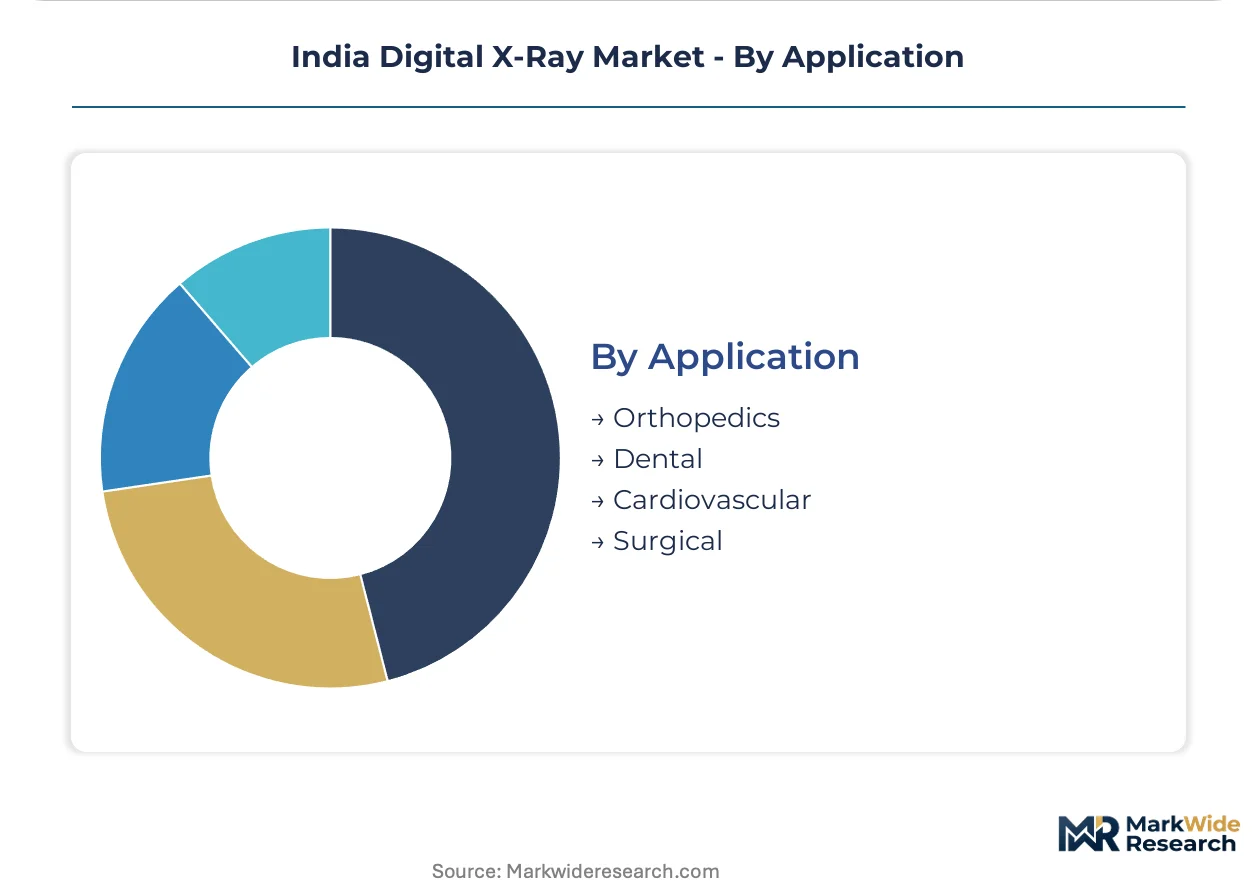
Application:
Clinical use case shapes detector specifications, software algorithms, and reimbursement pathways within India's mixed public-private payment environment.
- Orthopedics:Weight-bearing extremity views and trauma protocols demand high-resolution detectors with musculoskeletal-specific image processing. Mumbai and Delhi surgical centers are adopting mobile C-arm configurations for intraoperative imaging during joint replacement procedures.
- Cardiovascular:Rapid sequence acquisition and ECG-gating capabilities support catheterization lab workflows where ceiling-mounted tube stands enable multi-angle projections.
- Dental:Intraoral sensors and panoramic units serve high-volume outpatient settings with compact installation footprints.
- Surgical:C-arm fluoroscopy integrates diagnostic and interventional imaging into unified equipment procurement decisions.
Orthopedics concentrates procurement volume; cardiovascular applications command the highest per-unit pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent for detector calibration and TFT array maintenance concentrates in Bengaluru and Hyderabad, constraining service coverage expansion into rural districts and tier-three cities.
Maharashtra
Mumbai's orthopedic surgical centers drive demand for mobile C-arm configurations in trauma and joint replacement workflows. The state's district hospitals accelerate digital radiography procurement under Ayushman Bharat infrastructure expansion. Pune and Nagpur manufacturing clusters host assembly operations for high-voltage generator components serving western India.
Tamil Nadu
Chennai's corporate hospital chains consolidate enterprise-wide imaging equipment purchasing through centralized tender processes. CDSCO licensing requirements for Class B and C radiography equipment shape regulatory compliance strategies for equipment suppliers. Coimbatore and Madurai medical device manufacturing zones attract PLI-linked investments for flat-panel detector assembly.
Karnataka
Bengaluru anchors domestic R&D localization for mid-range digital radiography systems calibrated to Indian price points. BIS electromagnetic compatibility certification mandates elevate compliance costs for imported systems while favoring pre-certified domestic assemblies. The city's engineering centers concentrate thin-film transistor array calibration expertise that rural service networks struggle to replicate.
Telangana
Hyderabad's diagnostic center chains expand high-throughput standalone imaging infrastructure with teleradiology connectivity for remote reporting. CEA installation safety protocols for high-kilovoltage equipment create compliance barriers that favor established vendors with dedicated regulatory affairs teams. The city's hospital network density enables volume-based pricing leverage in enterprise procurement negotiations.
Delhi-NCR
Cardiovascular and interventional applications in tertiary-care settings demand ceiling-suspended tube stands with sub-millimeter positioning precision. The Central Electricity Authority regulates installation safety protocols across National Capital Region hospital campuses. Noida and Gurgaon medical equipment distribution hubs channel fixed X-ray systems into northern India corporate hospital chains.
India Digital X-Ray Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across India's digital X-ray supply chain. The market structure fragments across three tiers: multinational OEMs with full imaging portfolios, domestic assemblers leveraging PLI incentives for local value-addition, and regional distributors retrofitting analog installations with wireless detector kits. Siemens Healthcare Private Limited and Canon India Pvt Ltd exemplify the multinational archetype, while Allengers Medical Systems Limited represents domestic backward integration into high-voltage generator production. Competitive moves concentrate on channel density expansion in tier-three cities and PLI-linked manufacturing localization in Bengaluru and Chennai clusters.
Among multinational OEMs with Indian engineering centers, Siemens Healthcare Private Limited anchors R&D localization for mid-range systems, while Canon India Pvt Ltd competes on distribution reach across Uttar Pradesh and Bihar whitespace. Allengers Medical Systems Limited exemplifies the domestic integrator archetype through captive high-voltage generator production qualifying for enhanced PLI incentive tiers. These three companies represent distinct strategic positions: technology transfer with local adaptation, channel penetration in underpenetrated districts, and backward integration for policy-compliant manufacturing.
| Leading Market Players |
|---|
| Carestream Health Inc. |
| Canon India Pvt Ltd |
| Siemens Healthcare Private Limited |
| Allengers Medical Systems Limited |
| Shimadzu Medical (India) Pvt. Ltd. |
| GE HealthCare Technologies Inc. |
| FUJIFILM India Private Limited |
| Agfa-Gevaert Group |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Corporate hospital chains in Karnataka and Telangana operate on volume-based enterprise procurement contracts that compress per-unit pricing while demanding 24-hour service response guarantees. This buyer concentration forces suppliers to bundle after-sales support into capital equipment quotes, eroding standalone margin pools.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ceiling-suspended fixed systems from portable wireless units and retrofit CR kits. Price differentiation hinges on BIS electromagnetic compatibility certification grade and detector resolution specifications. Cost compression in the economy tier intensifies because legacy analog facilities delay digital migration. District hospitals under Ayushman Bharat programs exhibit highest price sensitivity; tertiary-care cardiovascular labs show lowest.
Supply Chain Analysis
BIS electromagnetic compatibility certification and CDSCO Class C licensing create gating barriers that extend product launch cycles for new radiography entrants. Component supply draws from Japan and South Korea for cesium iodide scintillator layers, from Taiwan for thin-film transistor arrays, and from Germany for high-voltage generator subassemblies. Single-source vulnerability concentrates in flat-panel detector sensor supply. Distribution runs through Noida and Gurgaon medical equipment hubs channeling into northern India hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India Digital X-Ray Market operates as a geographic-arbitrage play where PLI-linked domestic assembly incentives in Bengaluru and Chennai offset Korean and Japanese component import costs against Chinese manufacturing alternatives.
For Market Incumbents: Acquire biomedical engineering talent pools in Hyderabad and Bengaluru to secure detector calibration capabilities that rural service networks cannot replicate. Defend against portable system distributors by embedding AI inference engines into acquisition workstations, compressing radiographer training requirements that emerging entrants lack resources to match.
For New Entrants and Emerging Players: Begin with wireless detector retrofit kits for analog installations in Uttar Pradesh and Bihar district hospitals where budget constraints delay full DR migration. Target tier-three city diagnostic center chains with teleradiology-ready portable configurations, leveraging lower CEA compliance overhead versus fixed high-kilovoltage installations.
For Investors and Strategic Acquirers: Domestic medical device integrators with captive high-voltage generator production are the most active acquirer in this space, seeking PLI qualification through backward integration. Long-term viability hinges on regulatory affairs team depth navigating CDSCO licensing streamlines. Watch for India's proposed medical device pricing authority intersecting with local value-addition requirements as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| PLI-Linked Manufacturing Localization | Domestic assembly of flat-panel detectors in Bengaluru and Chennai clusters reduces import dependence on Korean suppliers. |
| AI-Enabled Acquisition Workstation Development | Automated exposure parameter selection compresses radiographer training gaps across high-throughput screening programs. |
| Wireless Detector Retrofit Kit Launch | Battery-integrated panels enable digital migration for cost-constrained district hospitals without infrastructure overhaul. |
| Enterprise Service Contract Consolidation | Apollo, Max, and Fortis networks negotiate single-source vendor relationships displacing decentralized procurement. |
| BIS Pre-Certification Component Architecture | Pre-certified electromagnetic compatibility designs accelerate CEA installation approvals for tier-two hospital committees. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineering heads, radiology department directors, and GPO contracts managers grounded qualitative findings. Secondary validation drew from CDSCO medical device registration databases, BIS certification records, hospital procurement tender documents, and PLI scheme disbursement filings. Bottom-up equipment shipment estimates triangulated against top-down healthcare infrastructure budget allocations.
Bottom-up modeling segmented volume and value across the analysis window by product mobility class, imaging technology modality, end-user facility tier, and clinical application. CAGRs derived from polynomial curve-fitting of historical procurement trajectories adjusted for Ayushman Bharat bed expansion targets and corporate hospital chain capital expenditure cycles. Forecast inputs incorporated thin-film transistor array cost decline curves and detector panel import substitution timelines.
Several conditions sit outside the modeled scope, including unforeseen regulatory delays at BIS testing laboratories, abrupt PLI incentive tier modifications, and geopolitical disruptions to Korean and Japanese sensor supply chains. Deviation in India's proposed medical device pricing authority implementation timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
X-Ray Film Market
Medical Imaging
Contrast Media Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
C-Arms Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Australia Digital Radiology Market