
 Digital Banking Platform Market | 2026-2036
Digital Banking Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Banking Platform Market Intelligence
Subscription-based SaaS pricing for core banking infrastructure is narrowing the competitive field to vendors with balance-sheet depth. Temenos leverages its multi-tenant cloud architecture to serve tier-one institutions across multiple continents. nCino sustains dominance in commercial lending workflows through deep Salesforce integration. Mambu anchors the mid-market with a composable banking engine that reduces implementation timelines for digital-first lenders.
A digital banking platform is a software layer that orchestrates account origination, transaction processing, and customer engagement through API-connected microservices, typically deployed on cloud infrastructure with sub-second latency requirements for payment authorization. Its primary commercial purpose is to replace monolithic legacy cores with modular, scalable systems that reduce operational cost per account. Retail customer deployments generate the largest revenue pool, though SME-focused configurations are expanding fastest as embedded finance partnerships multiply. Public cloud deployment now captures the majority of new implementations, while private cloud retains preference among institutions with stringent data residency requirements. AI analytics within service layers is deepening margin pools as banks monetize real-time risk scoring and personalized product recommendations.
FDA guidelines on software as a medical device do not apply here; rather, banking regulators including the OCC, Federal Reserve, and CFPB in the United States impose operational resilience and consumer protection standards that shape platform procurement criteria. The EU's PSD2 and forthcoming PSD3 frameworks mandate open API access, directly stimulating demand for API integration technology segments. Stakeholders must monitor how divergent national data localization laws reshape deployment model preferences across jurisdictions.
Market Dynamics
Cloud-native core banking systems are virtualizing legacy infrastructure, compressing implementation timelines from years to months and forcing incumbent vendors to rearchitect around API-first microservices or cede tier-one accounts to composable alternatives.
Growth Catalysts
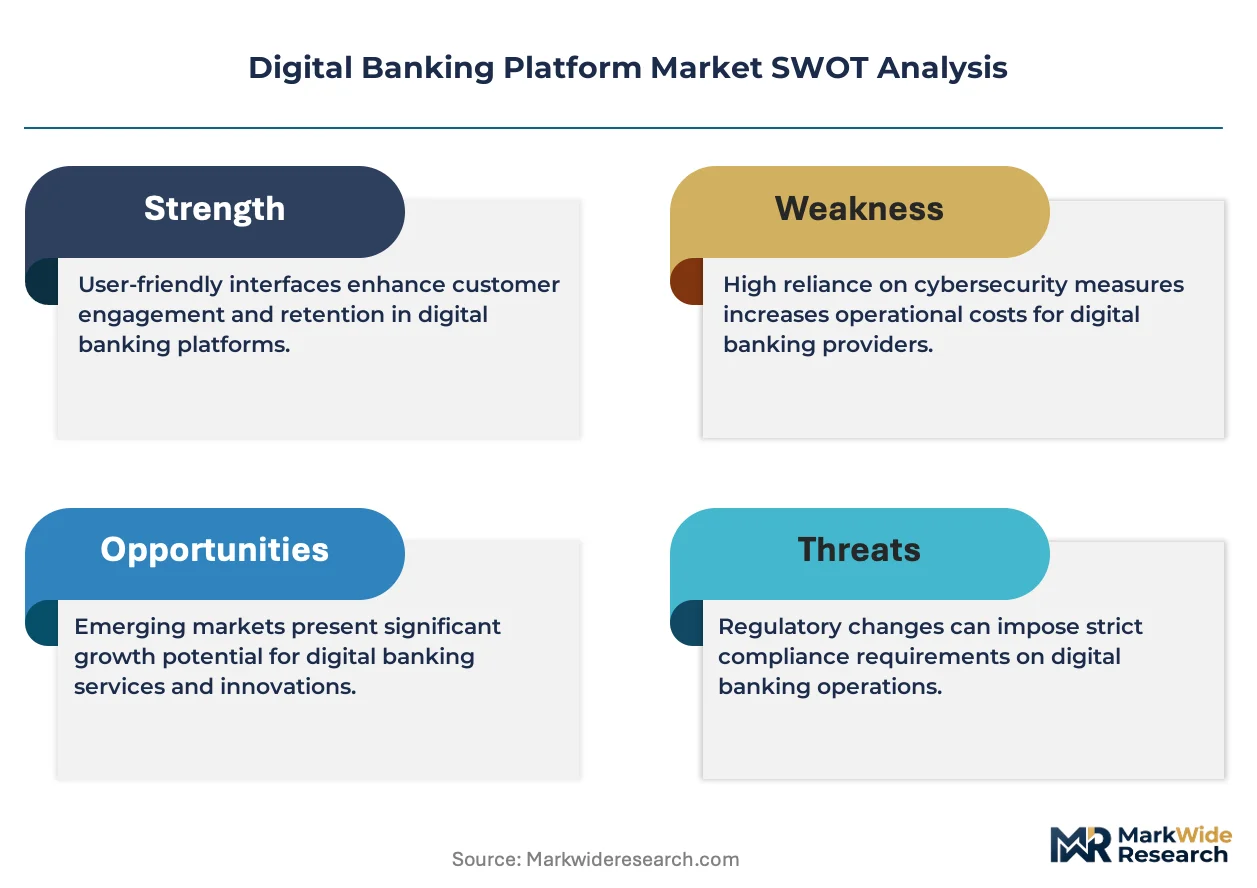
- PSD2 Open Banking Mandates:European regulations compel banks to expose customer data through standardized APIs, creating mandatory demand for integration middleware and consent management layers.
- Real-Time Payment Rails:FedNow in the United States and SEPA Instant in Europe require sub-second transaction processing, driving replacement of batch-oriented legacy cores with event-driven architectures.
- Embedded Finance Partnerships:Non-bank retailers and SaaS platforms in Brazil and Southeast Asia are white-labeling banking services, expanding addressable market beyond traditional financial institutions.
Market Restraints
- Data Residency Requirements:Russia, China, and Indonesia mandate local server presence, fragmenting cloud deployment models and raising operational complexity for multinational platform vendors.
- Core Banking Migration Risk:The technical debt of decades-old COBOL systems at tier-one institutions creates path dependency that slows replacement cycles despite functional limitations.
- Specialized Talent Scarcity:Shortage of engineers fluent in both financial services compliance and cloud-native development constrains implementation velocity across all vendor tiers.
Strategic Opportunities
- SME Banking Digitization:Underpenetrated segments in Mexico, Nigeria, and Vietnam lack tailored platforms, creating whitespace for purpose-built lending and treasury solutions.
- AI-Driven Risk Analytics:Convergence of machine learning models with real-time transaction streams enables dynamic credit scoring and fraud detection as premium service tiers.
- Carbon Accounting Integration:EU CSRD disclosure requirements position banking platforms as data aggregators for corporate sustainability reporting, extending platform stickiness.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Institutions demanding redundancy across AWS, Azure, and Google Cloud face integration overhead that delays production deployments.
- Certification Timeline Compression:SOC 2 Type II and PCI DSS audits for new platform releases extend sales cycles, particularly for vendors targeting regulated deposit-taking institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Banking Platform Market |
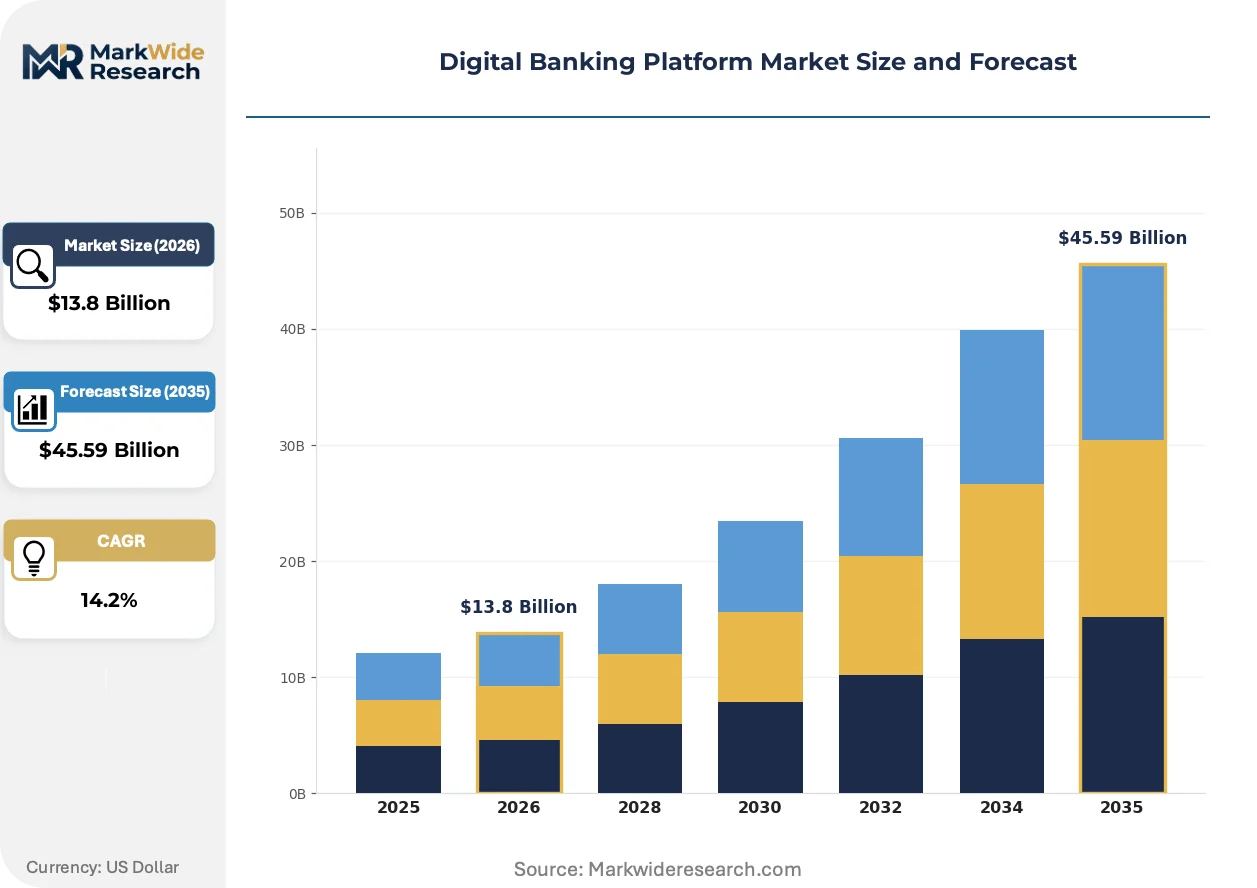
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $45.59 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Retail Customers, SMEs, Corporates, Institutions Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Account Management, Payment Processing, Lending Solutions, Wealth Management Technology: API Integration, AI Analytics, Blockchain, Mobile Technologies |
| Companies Covered | Thought Machine, nCino, Temenos, Finacle, Oracle, Mambu, SDK.finance, Fiserv, Finastra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Banking Platform Market Strategic Shifts & Innovations
Containerized deployment and event streaming architectures are compressing the competitive moat of established core banking vendors, enabling mid-tier challengers to match functional depth with superior agility and lower total cost of ownership.
Event-sourced ledger technology is virtualizing traditional database architectures for transaction recording. Tier-two banks and digital-first lenders in Poland and Singapore are adopting this pattern to achieve horizontal scalability. The approach is virtualizing the historical advantage of mainframe-class throughput, democratizing access to real-time processing capabilities.
EU PSD3 proposals strengthen consumer rights and third-party access requirements, extending regulatory pressure on API standardization. Banks must upgrade consent frameworks and liability protocols before implementation deadlines. German and Dutch institutions are accelerating procurement of compliance modules to preempt enforcement action.
Subscription-based commercial models are displacing perpetual license arrangements across procurement functions at North American credit unions and community banks. Vendors now compete on annual recurring revenue metrics rather than upfront implementation fees. This shift is most pronounced among institutions with under $10 billion in assets seeking predictable operational expenditure profiles.
Digital Banking Platform Market Segmentation
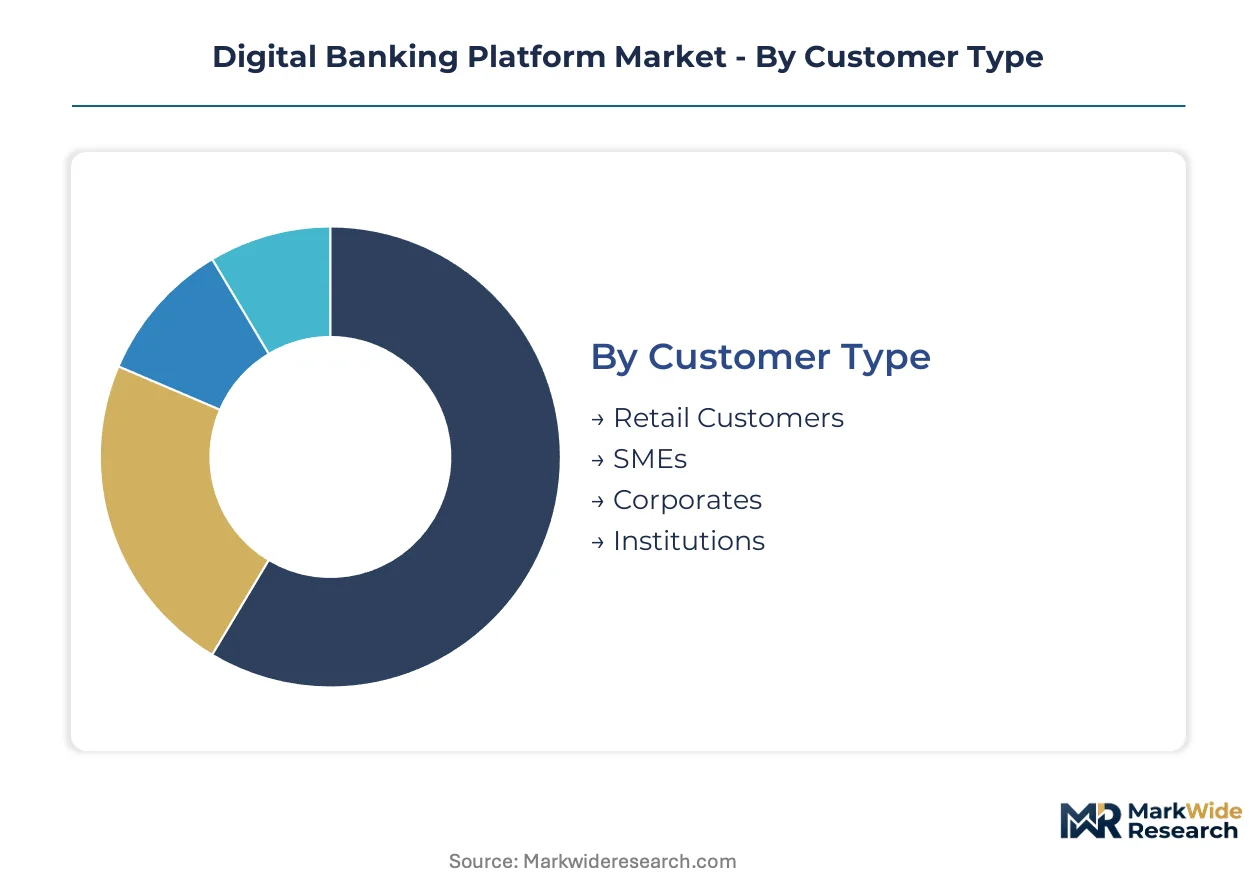
Platform procurement patterns diverge sharply across customer scale and technical architecture. Deployment choices increasingly reflect jurisdictional data mandates rather than pure cost optimization. Service bundling and technology stack decisions determine vendor stickiness and margin capture.
Customer Type:
Retail workflows demand high-volume, low-margin automation. SME and corporate segments prioritize configurable treasury tools and multi-entity account structures.
- Retail Customers:Mass-market account origination and transaction processing dominate platform workloads. Tier-one banks in the United States and United Kingdom deploy these solutions to defend against neobank customer acquisition campaigns.
- SMEs:Embedded finance partnerships in Brazil and Nigeria are accelerating demand for white-labeled lending and payment acceptance modules. Revenue per seat exceeds retail by multiples due to cross-sell complexity.
- Corporates:Multi-currency liquidity management and real-time cash visibility requirements drive procurement at European multinational treasuries.
- Institutions:Custody, securities lending, and collateral management integrations dominate this segment's platform specifications.
Established volume favors Retail Customers; emerging adoption favors SMEs.
Deployment Model:
Regulatory fragmentation is fragmenting cloud strategy across borders. Cost efficiency and data sovereignty pull procurement in opposite directions.
- Public Cloud:AWS, Azure, and Google Cloud infrastructure delivers elastic scaling for digital-first lenders. Majority of new implementations in North America and Western Europe default to this model.
- Private Cloud:Dedicated tenant environments satisfy Russia, China, and Indonesia data localization mandates. German and Swiss institutions favor this architecture for GDPR-sensitive workloads.
- Hybrid Cloud:Transaction processing on private infrastructure with analytics workloads burst to public cloud. Australian banks use this pattern to balance latency with compute economics.
- On-Premises:Legacy mainframe coexistence persists at Japanese megabanks and US money center institutions with decades of COBOL technical debt.
Procurement momentum concentrates in Public Cloud; compliance constraints sustain Private Cloud.
Service Type:
Core banking modules are unbundling into specialized microservices. Vendors compete on integration depth rather than functional breadth alone.
- Account Management:KYC orchestration and identity verification layers consume disproportionate implementation resources. Indian and Indonesian platforms prioritize video-based customer onboarding.
- Payment Processing:FedNow and SEPA Instant compliance requires event-driven architectures with sub-second authorization latency.
- Lending Solutions:Automated credit decisioning engines with alternative data ingestion are climbing the fastest in Southeast Asian markets.
- Wealth Management:Robo-advisory and portfolio rebalancing modules serve high-net-worth segments in Singapore and Switzerland.
Payment Processing anchors current revenue; Lending Solutions are expanding most quickly.
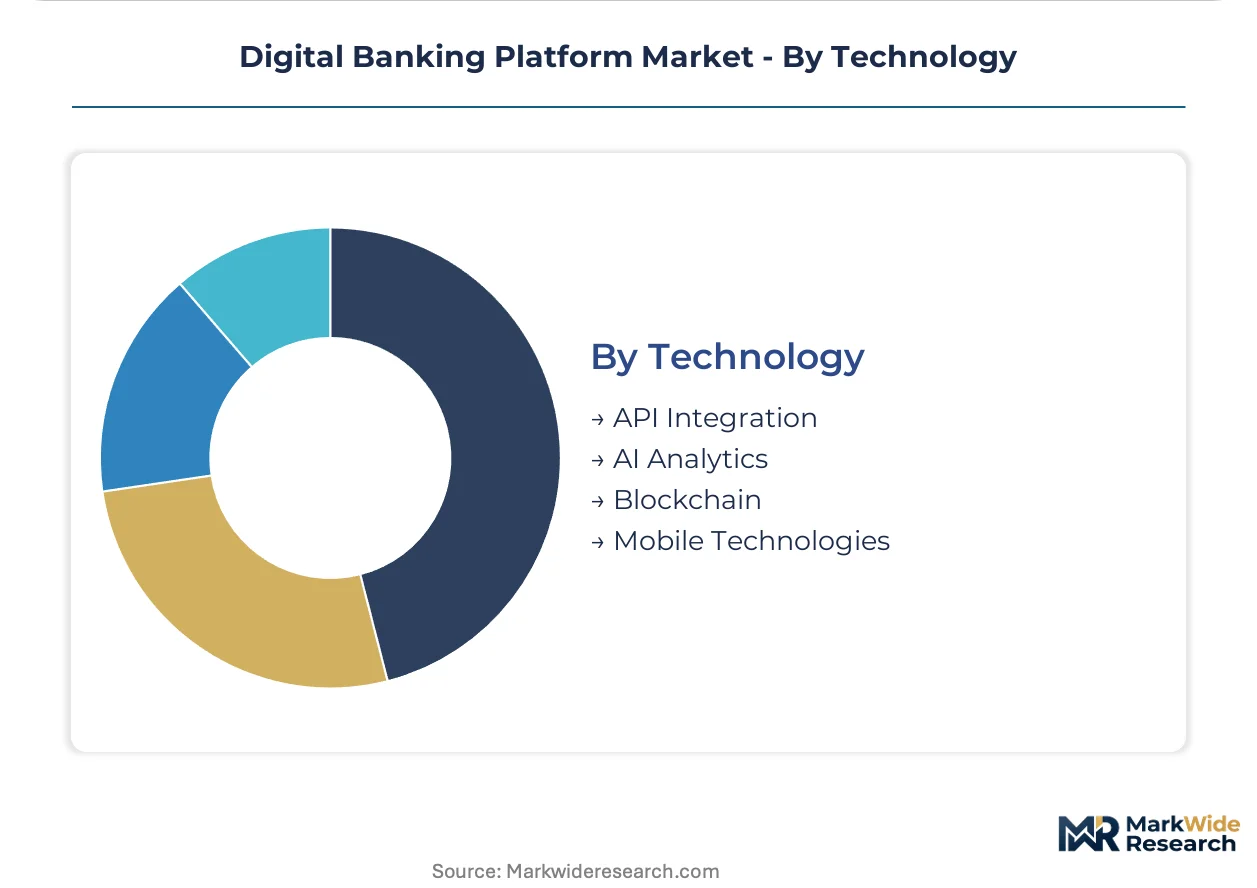
Technology:
Stack modernization cycles determine competitive durability. API and AI layers now separate viable platforms from legacy replacements.
- API Integration:Open banking compliance in Europe and Australia mandates standardized consent and data sharing protocols. PSD2 and CDR frameworks directly stimulate middleware procurement.
- AI Analytics:Real-time fraud detection and dynamic pricing engines generate premium service tiers. Singaporean regulators are publishing guidance on model risk management for these deployments.
- Blockchain:Cross-border settlement and programmable money pilots concentrate in UAE and Hong Kong financial centers.
- Mobile Technologies:Super-app integration and biometric authentication dominate customer-facing layer development in African and South Asian markets.
API Integration underpins current infrastructure; AI Analytics offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The PSD2 directive and FedNow infrastructure deployment are accelerating platform procurement across mature banking markets, while embedded finance partnerships expand adoption in emerging economies.
United States
Legacy core modernization cycles at money center banks and credit unions drive replacement demand. The OCC and Federal Reserve impose operational resilience standards that shape vendor selection criteria. New York and Charlotte financial centers concentrate procurement decisions for tier-one institutions replacing COBOL infrastructure.
United Kingdom
Open banking API mandates and neobank competition force incumbent institutions to rearchitect customer-facing layers. The Financial Conduct Authority enforces PSD2 compliance timelines that accelerate middleware procurement. London's fintech cluster hosts vendor development centers serving European expansion strategies.
Germany
SME banking digitization and treasury management requirements sustain demand for configurable platforms. BaFin data localization preferences sustain private cloud deployment models. Frankfurt's banking quarter anchors procurement for corporate banking modules serving multinational treasuries.
Singapore
Wealth management digitization and cross-border payment corridors drive platform adoption among private banks. The Monetary Authority of Singapore publishes guidance on AI model risk management for real-time analytics deployments. The Marina Bay financial district concentrates vendor partnerships for Southeast Asian market entry.
Brazil
Embedded finance partnerships between retailers and SaaS platforms expand addressable market beyond traditional banks. The Central Bank of Brazil's Pix instant payment infrastructure mandates sub-second processing capabilities. São Paulo's fintech corridor anchors white-label banking service deployments across Latin America.
Digital Banking Platform Market Key Industry Players
On the supply side, the industry is consolidating around vendors with balance-sheet depth to sustain multi-tenant cloud architectures and compliance certification investments. Three strategic archetypes dominate: established core banking vendors rearchitecting legacy stacks, cloud-native challengers offering composable microservices, and vertical specialists embedding deeply into CRM or payment workflows. Competitive intensity centers on geographic expansion partnerships and AI analytics service tier differentiation.
Within the cloud-native challenger tier, Mambu and Thought Machine exemplify the composable banking engine archetype that compresses implementation timelines for digital-first lenders. Temenos anchors the established vendor category with multi-tenant deployments across tier-one institutions. nCino occupies a specialized position through deep Salesforce integration in commercial lending workflows.
| Leading Market Players |
|---|
| Thought Machine |
| nCino |
| Temenos |
| Finacle |
| Oracle |
| Mambu |
| SDK.finance |
| Fiserv |
| Finastra |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoint exposure around FedNow and SEPA Instant compliance mandates determines both pricing tier spreads and supply chain shape, as tier-one institutions pay premiums for sub-second latency certification while mid-market buyers accept standard-tier performance.
Pricing Analysis
Certification level for real-time payment authorization creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers bundling SOC 2 Type II attestation and PCI DSS Level 1 validation. Cost compression in the economy tier is intensifying because hyperscaler infrastructure commoditizes basic processing capabilities. Community banks and credit unions under $10 billion in assets exhibit highest price sensitivity; tier-one institutions prioritize compliance assurance over unit cost.
Supply Chain Analysis
Tariff exposure between United States and China in semiconductor components for cloud infrastructure dominates vendor risk assessments. Supply concentrates in Ireland, Singapore, and Germany for data center operations serving financial services workloads. Raw material dependencies span specialized server hardware, encryption modules, and low-latency networking equipment. Single-source vulnerability in API gateway middleware creates procurement contingency planning. Distribution runs through direct enterprise sales teams with embedded implementation specialists rather than channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around open banking API interoperability, with PSD2 and forthcoming PSD3 frameworks creating winner-take-most dynamics for vendors achieving cross-border certification portability.
For Market Incumbents: Harden multi-tenant architecture resilience against neobank challengers by accelerating FedNow certification timelines and deepening vertical integration into AI analytics layers. Incumbents must consolidate channel control through exclusive partnerships with Salesforce and major hyperscalers before composable alternatives achieve functional parity.
For New Entrants and Emerging Players: SME banking digitization in Mexico, Nigeria, and Vietnam offers whitespace with limited incumbent presence. Purpose-built lending engines for embedded finance partnerships represent the most penetrable segment. Go-to-market execution should prioritize white-label deployments through retailer and SaaS platform channels rather than direct bank sales.
For Investors and Strategic Acquirers: PSD3 implementation timelines reshape the acquisition landscape by privileging vendors with pre-built consent management and liability protocol modules. Long-term viability favors platforms with demonstrated multi-jurisdiction deployment capability. Target acquisition archetypes include vertical specialists in commercial lending workflows and AI-native risk analytics engines. The signal to watch is central bank procurement announcements for instant payment infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep Salesforce or hyperscaler embedding creates switching costs for commercial lending clients. |
| Regulatory Certification Pathway | FedNow and SEPA Instant authorization separates viable vendors from legacy replacement candidates. |
| Geographic Expansion | Local data center presence satisfies Russia, China, and Indonesia residency mandates for market entry. |
| Acquisition of Specialist Firm | AI analytics or blockchain settlement capabilities fill functional gaps in core banking stacks. |
| Strategic Partnership | Embedded finance alliances with retailers and SaaS platforms expand addressable market beyond traditional banks. |
Research Approach
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings. CTOs, platform engineers, IT procurement officers at tier-one banks, and integration specialists at neobanks provided operational perspective. Secondary sources encompassed OCC and Federal Reserve guidance documents, ECB payment infrastructure reports, and hyperscaler financial services vertical disclosures. Bottom-up vendor revenue analysis and top-down banking IT spend estimates were reconciled through iterative calibration.
Calibration against historical core banking replacement cycles and open banking adoption curves shaped the projection framework. Segmentation dimensions spanned deployment model, customer tier, service type, and jurisdictional regulatory cluster. CAGRs were derived from slope-consistent growth rate analysis across the projection horizon. Forecast inputs incorporated real-time payment infrastructure deployment schedules and embedded finance partnership formation velocity.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native challenger expansion or accelerated PSD3 enforcement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
AI Finance Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
Fintech Crisis Management Market
FinTech
Hand Account Software Market
FinTech
Europe Financial Analytics Market
FinTech
China AI in Fintech Market
FinTech
Middle East AI in Fintech Market
FinTech
Russia AI in Fintech Market
FinTech
Smart Advisors Market
FinTech
Global Saas Spend Management Software Market
FinTech
Canada AI in Fintech Market
FinTech
North America Fintech Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Saudi Arabia Fintech Market
FinTech
Financial App Market
FinTech
Automotive Fintech Market