
 Automotive Fintech Market | 2026-2036
Automotive Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fintech Market Analysis
The split between premium white-label platforms and commodity API aggregators is realigning how capital reaches vehicle buyers. Ally Financial leverages its captive bank charter to sustain below-market funding costs across prime and near-prime segments. AutoFi Inc. competes by anchoring its embedded checkout technology directly into dealer management systems, bypassing traditional indirect lending infrastructure.
Automotive fintech encompasses digital financial services, credit infrastructure, and payment systems purpose-built for vehicle acquisition, ownership, and monetization, typically integrating with dealership point-of-sale terminals and OEM configurators via API protocols. Its primary commercial purpose is to reduce friction in loan origination, insurance binding, and recurring payment collection across the vehicle lifecycle. Credit Services within the Service Type dimension dominates transaction value as margin pools concentrate in interest income and loan servicing fees. AI & Machine Learning under the Technology segment leads origination speed as lenders deploy alternative data models to underwrite thin-file borrowers previously excluded from prime rates.
The Consumer Financial Protection Bureau shapes disclosure requirements and fair lending enforcement across automotive credit products in the United States. The Federal Trade Commission's Credit Practices Rule and state usury ceilings constrain pricing flexibility, pushing platforms toward fee-based revenue architectures. Stakeholders must monitor how open banking regulations and evolving AI governance standards reshape data access rights and algorithmic underwriting accountability.
Market Dynamics
Open banking API proliferation is dismantling the indirect lending infrastructure that dealerships have controlled for decades, forcing capital providers to rebuild origination around direct consumer relationships and real-time data pipes.
Growth Catalysts
- Real-time credit scoring:Alternative data models now underwrite thin-file borrowers previously excluded from prime auto rates, expanding the addressable borrower base beyond traditional FICO thresholds.
- CFPB disclosure modernization:Streamlined digital disclosure requirements reduce origination friction while maintaining fair lending enforcement, accelerating platform onboarding velocity.
- Embedded finance penetration:Point-of-sale financing integration into OEM configurators and dealer management systems collapses the time between vehicle selection and funding approval.
Market Restraints
- State usury ceilings:Interest rate caps in jurisdictions such as New York and California constrain pricing flexibility on subprime auto loans, compressing margin pools in high-yield segments.
- Legacy core banking systems:Mainstream lenders operate on decades-old loan origination software that cannot ingest alternative data streams without expensive middleware layers.
- Credit bureau concentration:Three national repositories dominate traditional scoring data, creating single-point-of-failure risk for platforms dependent on conventional underwriting inputs.
Strategic Opportunities
- Electric vehicle financing:Battery-as-a-service subscription models and residual value uncertainty create demand for specialized loan products with mileage-indexed repayment structures.
- FTC Credit Practices Rule evolution:Anticipated regulatory clarity on digital advertising disclosures opens pathways for social media-native origination channels previously restricted by compliance uncertainty.
- Usage-based insurance bundling:Telematics data convergence with loan servicing enables dynamic pricing that rewards low-mileage borrowers with rate reductions at renewal.
Industry Challenges
- AI governance accountability:Algorithmic underwriting models face escalating scrutiny from the CFPB on disparate impact, requiring explainable AI architectures that slow deployment timelines.
- ISO 20022 migration:Payment messaging standardization demands substantial core system upgrades for auto lenders still operating on legacy SWIFT MT formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fintech Market |
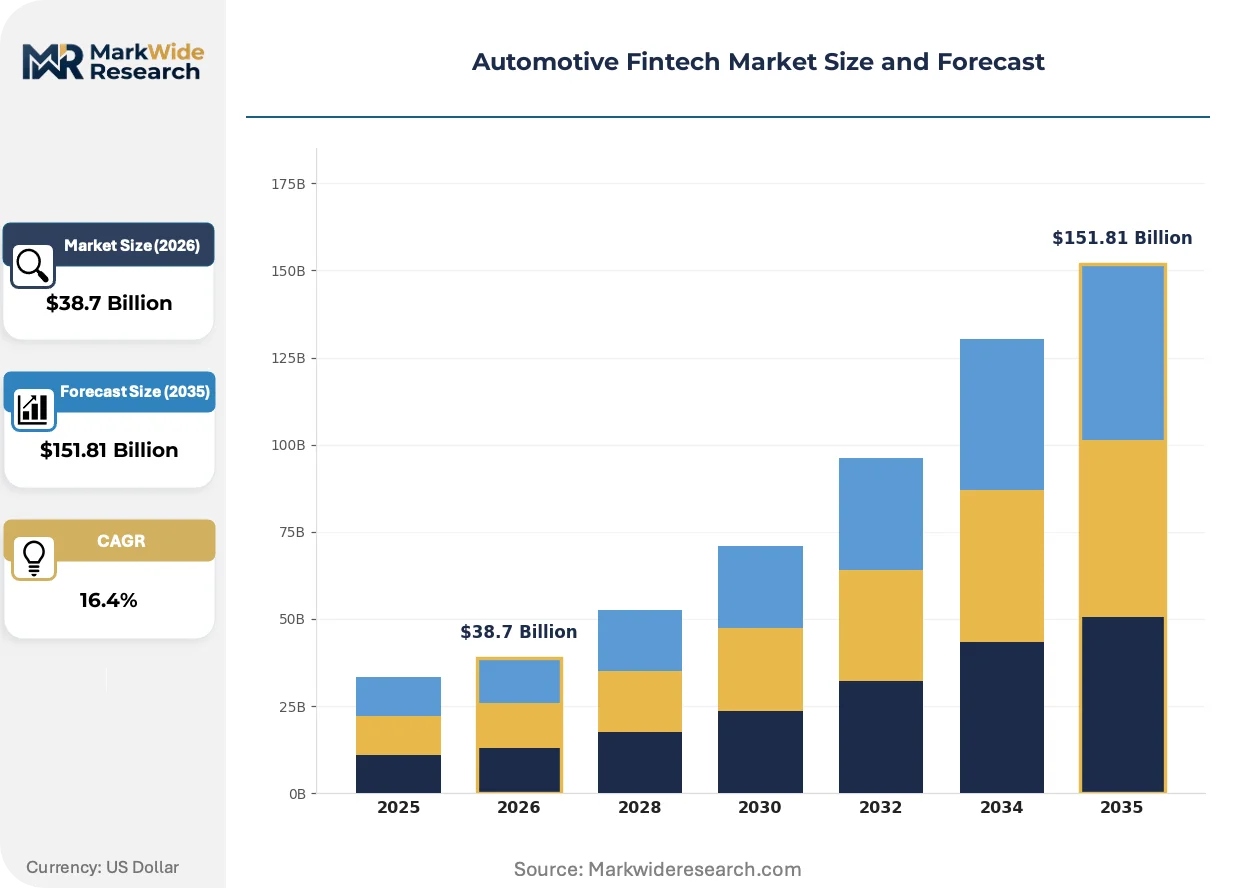
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Solutions, Insurance Products, Credit Services, Financing Options Customer Type: Dealerships, OEMs, Fleet Managers, Individual Consumers Technology: Blockchain, AI & Machine Learning, Mobile Apps, Cloud Computing Offering: Software Platforms, Digital Wallets, E-commerce Solutions, Analytics Tools |
| Companies Covered | Ally Financial, Toyota Financial Services, Ford Motor Credit Company, GM Financial Inc., Volkswagen Financial Services, AutoFi Inc., The Savings Group, Inc. (Autopay), Blinker Inc., Creditas Soluções Financeiras, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fintech Market Emerging Trajectories
Automotive fintech is converging around instant decisioning infrastructure that collapses the gap between credit inquiry and fund disbursement, redefining consumer expectations for vehicle purchase velocity.
Machine learning-powered income verification is electrifying the verification layer of loan origination. Subprime-focused digital lenders deploy bank account aggregation and payroll API connections to validate employment in seconds rather than days. Thin-file borrowers in Texas and Florida now access near-prime rates previously reserved for established credit histories.
The FTC's emerging guidance on digital dark patterns is reshaping disclosure presentation requirements. Lenders must redesign checkout flows to eliminate pre-checked boxes and forced navigation sequences that obscure loan terms. Buy-here-pay-here dealers operating online marketplaces face the steepest compliance retrofit costs as they migrate from in-person to remote origination.
Fleet procurement departments are unbundling vehicle acquisition from captive financing arrangements. Large commercial operators now issue RFPs to fintech platforms for white-label fleet management solutions that consolidate financing, telematics, and maintenance spend into single-dashboard visibility. This pattern concentrates most visibly among last-mile delivery contractors in California and Illinois seeking to optimize total cost of ownership across mixed ICE and electric vehicle portfolios.
Automotive Fintech Market Segmentation
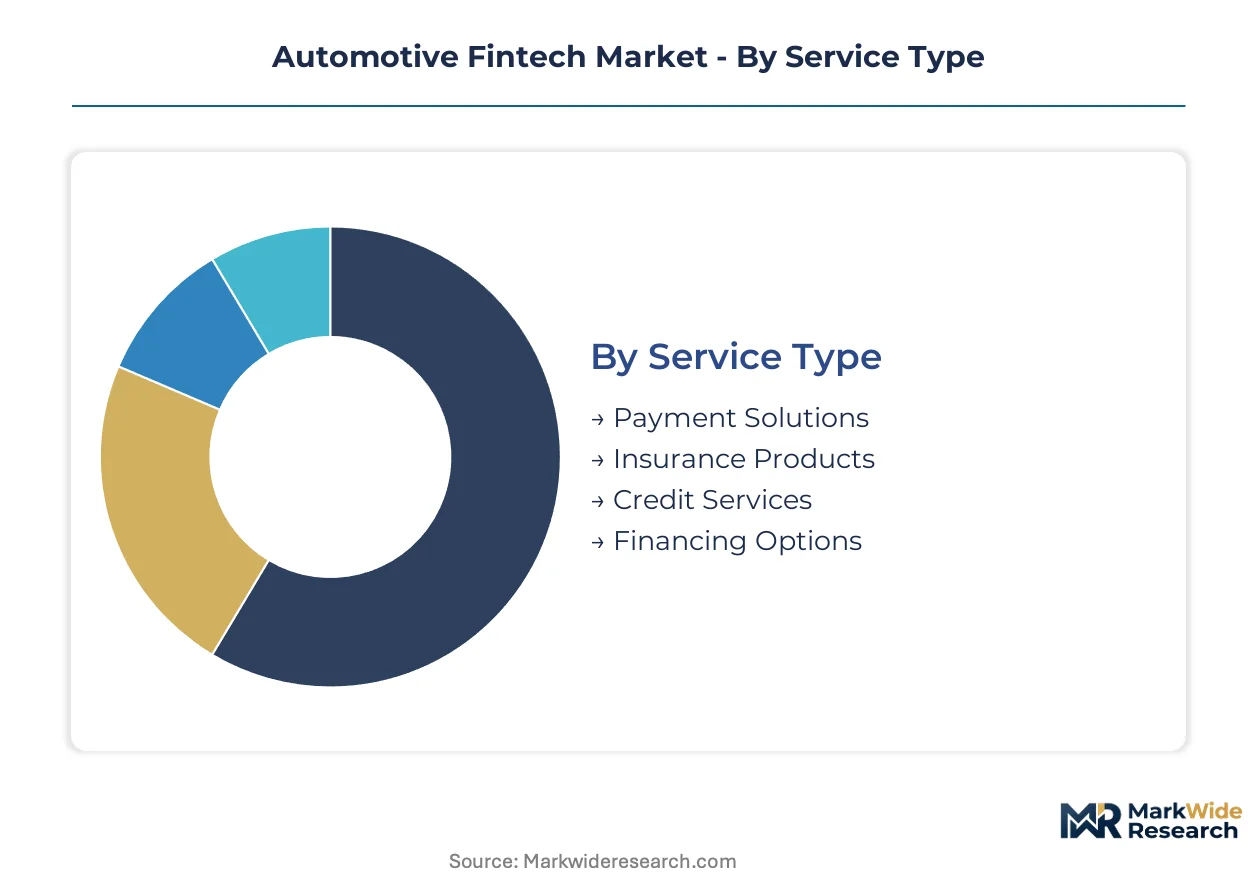
Automotive fintech segmentation reveals how capital flows, risk is priced, and technology layers stack across vehicle acquisition channels. Each category captures distinct buyer economics and infrastructure requirements that shape platform architecture and partnership priorities.
Service Type:
Dealerships, OEMs, and fleet operators select service types based on margin capture position and regulatory exposure in their origination channels.
- Credit Services:Loan origination and servicing infrastructure generates recurring fee income through interest spreads and administrative charges. Prime and near-prime auto lending concentrates in captive finance arms of major OEMs, while subprime digital platforms expand in Texas and Florida where state usury thresholds permit wider pricing bands.
- Insurance Products:Embedded auto insurance binding at point-of-sale collapses coverage activation from days to minutes. Telematics-integrated policies are gaining traction fastest among last-mile delivery fleets in California seeking usage-based premium adjustments tied to actual mileage exposure.
- Payment Solutions:Recurring payment orchestration for leases and subscriptions.
- Financing Options:Lease structuring, balloon payments, and residual value products.
Volume sits with Credit Services; growth tilts toward Insurance Products.
Customer Type:
Customer scale and decision velocity separate enterprise procurement from individual origination patterns.
- Dealerships:Independent and franchise dealers demand white-label embedded finance tools that preserve their customer relationship while outsourcing credit decisioning. The FTC's Credit Practices Rule compliance burden drives consolidation toward platforms with pre-built disclosure workflows.
- Fleet Managers:Commercial vehicle operators unbundle captive financing to optimize total cost of ownership across mixed powertrain portfolios. Large last-mile contractors in Illinois now issue RFPs for consolidated financing-telemetrics-maintenance dashboards.
- OEMs:Vehicle manufacturers deploying captive finance or partner-integrated checkout.
- Individual Consumers:Direct-to-borrower digital channels bypassing dealer intermediation.
Transaction volume concentrates with Dealerships; Fleet Managers are expanding most quickly.
Technology:
Technology selection determines underwriting speed, fraud exposure, and data sovereignty compliance.
- AI & Machine Learning:Alternative data models ingest bank transaction flows, employment verification APIs, and behavioral signals to score thin-file borrowers outside traditional FICO ranges. Real-time decisioning infrastructure now approves subprime auto loans in under sixty seconds.
- Cloud Computing:Elastic infrastructure enables lenders to burst capacity during promotional sales events without core system overbuild. Multi-tenant architectures reduce per-loan IT cost curves for mid-market platforms competing against Ally Financial's captive bank scale.
- Blockchain:Distributed ledger applications for title verification and smart contract automation.
- Mobile Apps:Native origination interfaces for dealer sales consultants and direct consumers.
Deployment scale favors Cloud Computing; AI & Machine Learning claims the steepest expansion trajectory.
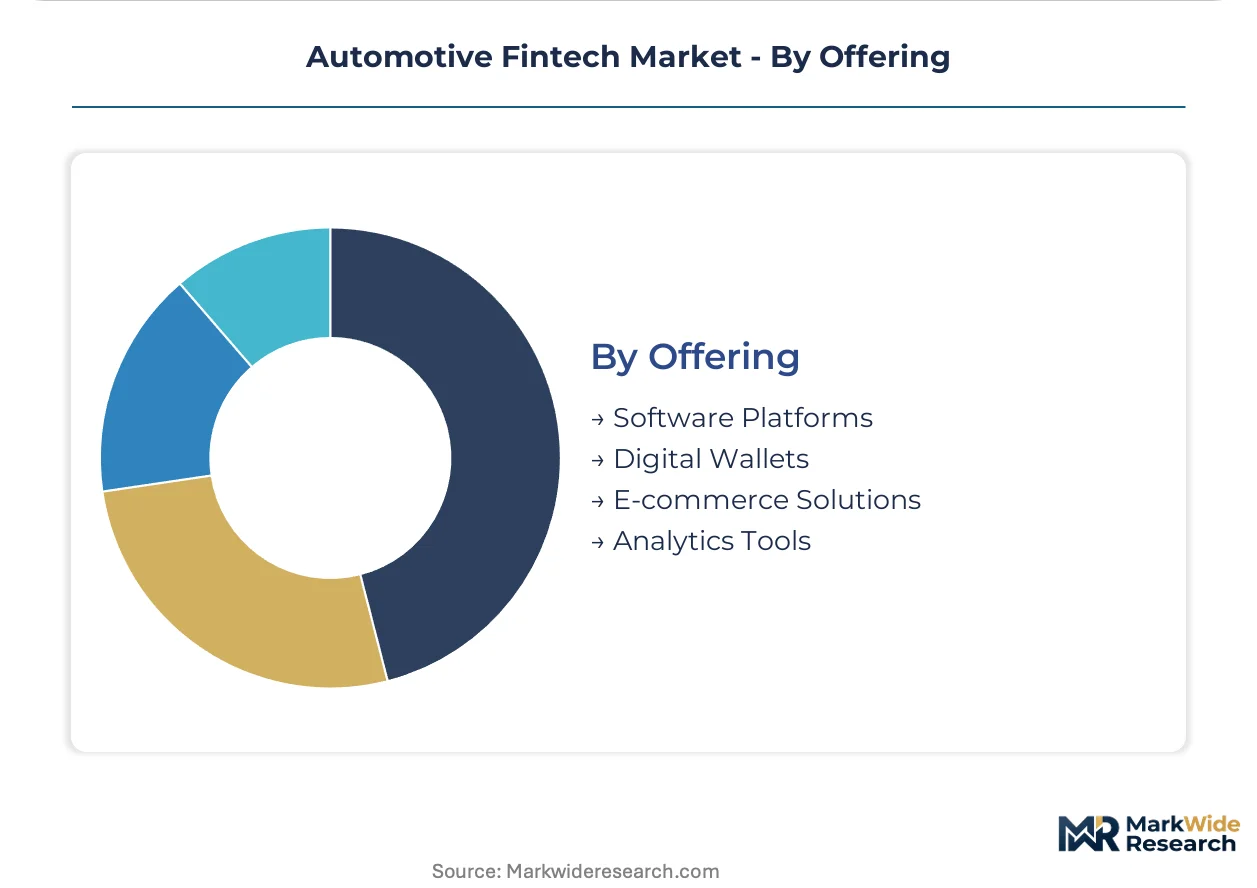
Offering:
Offering format shapes integration depth and revenue recognition timing for platform providers.
- Software Platforms:API-first loan origination systems embed directly into dealer management systems and OEM configurators. White-label deployments preserve dealer branding while centralizing compliance architecture.
- Digital Wallets:Closed-loop payment instruments for service plans, charging networks, and subscription renewals.
- E-commerce Solutions:End-to-end vehicle purchase completion with integrated financing.
- Analytics Tools:Portfolio monitoring and residual value forecasting for lenders.
Revenue concentration rests with Software Platforms; Digital Wallets are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors automotive fintech innovation as venture capital concentrates in San Francisco Bay Area startups building embedded finance infrastructure for vehicle purchases. The region's density of API developers and open banking specialists accelerates deployment timelines for real-time credit scoring platforms. This geographic clustering shapes how capital flows reach vehicle buyers across multiple national markets.
United States
Subprime digital lending platforms expand fastest in Texas and Florida where state usury thresholds permit wider pricing bands on auto loans. The Consumer Financial Protection Bureau enforces fair lending standards and disclosure modernization across all automotive credit products. Detroit's traditional automotive finance arms compete with Silicon Valley fintechs for control of loan origination technology stacks.
Germany
OEM captive finance arms dominate vehicle acquisition as Volkswagen Financial Services and similar entities leverage manufacturing relationships for prime-rate distribution. The EU AI Act imposes algorithmic accountability requirements on automated underwriting systems deployed across member states. Stuttgart's automotive engineering corridor incubates telematics-integrated insurance products for fleet operators.
China
Digital wallet penetration enables seamless vehicle purchase completion through super-app ecosystems integrating financing with e-commerce marketplaces. The National Financial Regulatory Administration supervises online lending platforms and embedded finance products offered through automotive sales channels. Shanghai's fintech district hosts developers building battery-as-a-service subscription billing infrastructure for electric vehicle manufacturers.
Brazil
Thin-file borrower expansion drives demand for alternative data underwriting models using bank transaction flows and employment verification APIs. ANVISA and the central bank coordinate on consumer protection frameworks for digitally distributed automotive credit products. São Paulo's technology corridor concentrates fintech platforms serving independent dealerships in Latin America's largest vehicle market.
United Kingdom
Open banking API adoption accelerates direct-to-consumer auto loan origination outside traditional dealership channels. The Financial Conduct Authority regulates embedded finance disclosures and algorithmic decision-making transparency in vehicle finance agreements. London's financial technology cluster develops white-label loan origination systems for European dealership networks.
Automotive Fintech Market Vendor Landscape
Premium-margin players sit above commodity-margin players across data infrastructure depth and regulatory compliance automation. Captive finance arms of major OEMs leverage manufacturing relationships and below-market funding costs to dominate prime and near-prime segments. Independent fintech platforms compete on embedded checkout speed and alternative data underwriting for subprime borrowers. Strategic consolidation centers on API-first loan origination acquisitions and dealership management system integration partnerships.
Within the captive finance tier, Ally Financial, Toyota Financial Services, and Ford Motor Credit Company exemplify established archetypes leveraging bank charters and OEM relationships for origination scale. These entities occupy positions where manufacturing integration and balance sheet capacity create defensive moats against digital-native entrants. AutoFi Inc. represents the embedded finance specialist archetype, anchoring a competitive position through direct dealer management system integration rather than indirect lending infrastructure.
| Leading Market Players |
|---|
| Ally Financial |
| Toyota Financial Services |
| Ford Motor Credit Company |
| GM Financial Inc. |
| Volkswagen Financial Services |
| AutoFi Inc. |
| The Savings Group, Inc. (Autopay) |
| Blinker Inc. |
| Creditas Soluções Financeiras |
| Others |
Supply Flow & Price Mechanics
API developer concentration in the San Francisco Bay Area anchors labor-cost differentials that widen pricing spreads between premium white-label platforms and commodity API aggregators. Talent scarcity for open banking specialists and real-time credit scoring engineers concentrates in Silicon Valley, forcing platforms to tier service pricing around embedded integration depth.
Pricing Analysis
Outcome-based pricing tied to loan origination throughput anchors revenue models across automotive fintech platforms. Three-tier pricing structure across premium, standard, and economy levels separates full-stack white-label deployments from modular API access and basic credit decisioning services. Cost compression in the commodity API tier is intensifying because venture-backed entrants subsidize customer acquisition with below-cost pricing. Subprime-focused digital lenders exhibit highest price sensitivity as thin margins on high-risk borrowers constrain platform fee budgets.
Supply Chain Analysis
Domestic-content mandates for financial data processing in Germany and Brazil reshape sourcing patterns for cloud infrastructure and compliance automation tools. Core technology supply concentrates in the United States, Ireland, and Singapore where hyperscaler data centers and API gateway providers cluster. Raw material dependencies center on semiconductor chips for point-of-sale terminals, encryption modules for data security, and fiber optic capacity for real-time credit pipes. Single-source vulnerability runs through concentrated cloud provider ecosystems. Distribution runs through direct API integrations with dealer management systems and OEM configurators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
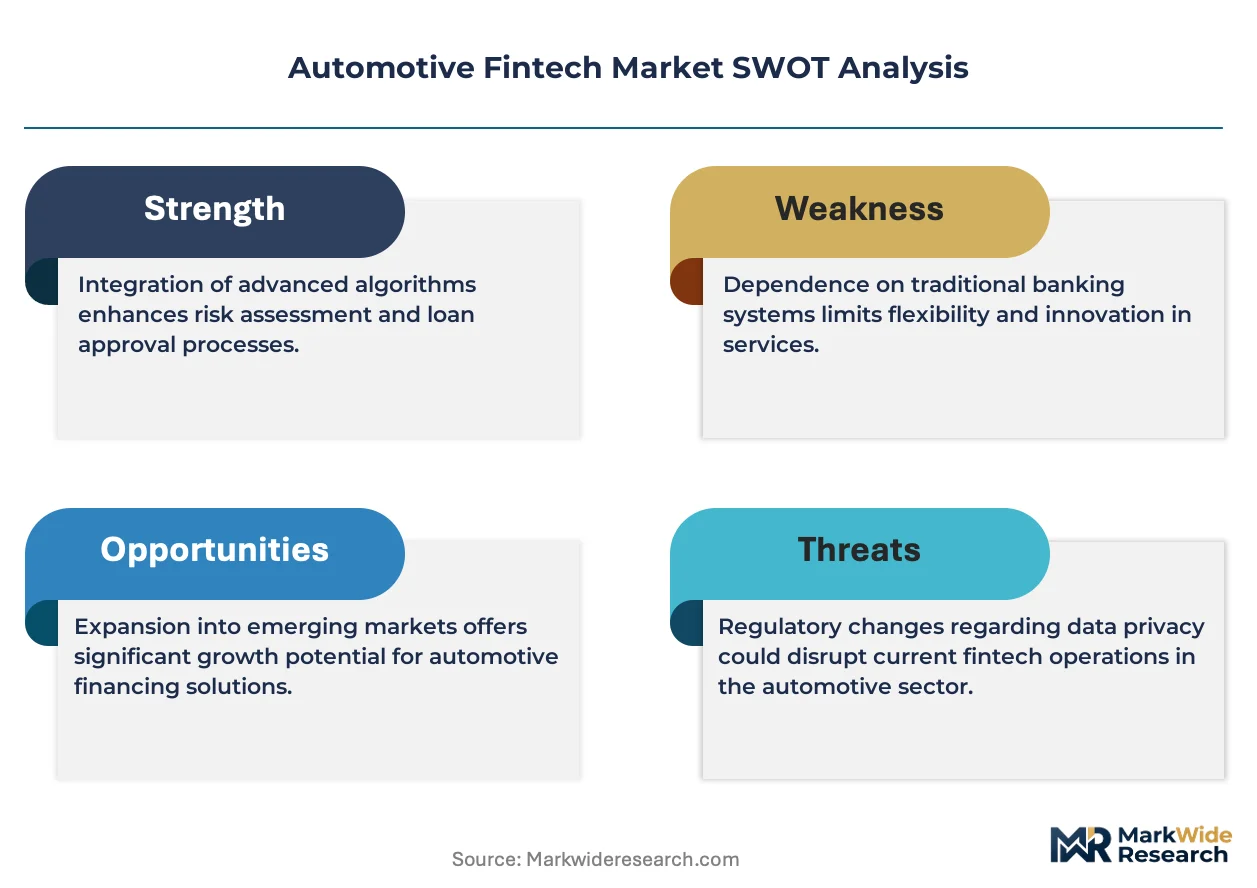
The automotive fintech market reads as a cost-of-compliance story where the CFPB's fair lending enforcement and disclosure modernization requirements erect barrier-to-entry moats for platforms with pre-built regulatory architectures.
For Market Incumbents: Hedge against embedded finance disruption by acquiring API-first loan origination specialists before dealership management system integration slots consolidate. Ally Financial and Toyota Financial Services should accelerate captive bank charter leverage into near-prime digital channels before subprime platforms scale alternative data underwriting. Vertical integration into real-time credit scoring infrastructure preserves margin capture as commodity API pricing erodes.
For New Entrants and Emerging Players: Thin-file borrowers in Texas and Florida represent the most penetrable buyer archetype as state usury thresholds permit wider pricing bands than California or New York. Last-mile delivery fleet operators in Illinois and California offer white-space expansion for consolidated financing-telemetrics-maintenance dashboards unbundled from captive arrangements. A telematics-embedded insurance bundling go-to-market angle bypasses entrenched credit services competition.
For Investors and Strategic Acquirers: The window for entry favors platforms with explainable AI architectures and pre-built CFPB disclosure workflows over growth-stage lenders with opaque algorithmic models. Long-term viability hinges on regulatory compliance automation as the EU AI Act and evolving FTC guidance escalate governance costs. Watch for CFPB enforcement actions on disparate impact as the inflection signal separating compliant platforms from retrofit liabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Management System Integration | Direct API embedding into CDK Global and Reynolds systems captures origination flow before indirect lending intermediation. |
| Alternative Data Underwriting Investment | Bank account aggregation and payroll API connections expand thin-file borrower access beyond traditional FICO thresholds. |
| Explainable AI Architecture Development | Transparent algorithmic decisioning satisfies CFPB disparate impact scrutiny while maintaining subprime approval velocity. |
| Telematics-Insurance Bundling Launch | Usage-based premium integration with loan servicing enables dynamic pricing tied to actual mileage exposure. |
| Captive Bank Charter Leverage | Below-market funding costs sustain prime and near-prime margin pools against venture-subsidized digital entrants. |
Methodological Framework
Independent corroboration across primary interviews with digital lending executives, dealership operations managers, regulatory compliance officers, and API platform engineers underwrites the qualitative findings in this study. Secondary validation draws from CFPB enforcement actions, FTC guidance documents, SEC 10-K filings from captive finance arms, and open banking regulatory frameworks. Bottom-up segmentation modeling triangulates against top-down market sizing from vehicle registration flows and loan origination volume estimates.
Rate-of-change decomposition separates volume growth from pricing evolution across the projection horizon. Segmentation dimensions modeled include service type, customer archetype, technology layer, and offering format alongside regional regulatory cluster variations. CAGRs derive from fitted growth curves anchored to disclosed origination volumes and platform revenue trajectories. Forecast inputs incorporate embedded finance penetration rates and alternative data underwriting adoption curves.
Revisions become necessary when CFPB enforcement priorities shift, open banking data access regulations tighten, or AI governance standards impose unanticipated compliance costs on algorithmic underwriting systems. Forecasts reflect documented assumptions about regulatory stability and technology deployment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Lendtech Market
FinTech
Japan AI in Fintech Market
FinTech
Financial Analytics Market
FinTech
UAE Fintech Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Robo-Advisory Software Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
Asia-Pacific Fintech Market
FinTech
Digital Banking Platform Market
FinTech
Russia AI in Fintech Market
FinTech
Germany AI in Fintech Market
FinTech
Cloud AI in Fintech Market
FinTech
Fintech-As-A-Service Platform Market
FinTech
Financial Cloud Market
FinTech
North America Fintech Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market