
 Japan Payment Gateway Market | 2026-2036
Japan Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Payment Gateway Market Insights
Subscription-based fraud detection is hardening into a standalone revenue layer for gateway providers. GMO Payment Gateway anchors its position through deep API integration with regional banks. Rakuten Pay leverages its super-app ecosystem to control merchant onboarding velocity. SP. LINKS specializes in hospitality-sector tokenization, occupying a niche where recurring billing complexity outstrips generic platform capabilities.
A payment gateway is a technology layer that encrypts, routes, and settles transaction data between merchants, acquirers, and card networks using tokenization and API protocols. Its commercial purpose is to reduce fraud exposure while enabling real-time authorization across fragmented banking infrastructure. Mobile payments and digital wallet segments lead transaction volume growth as QR-code interoperability expands beyond Tokyo's transit corridors. API integration technology captures expanding margin pools as mid-market merchants demand white-label checkout customization without proprietary development costs. E-commerce solutions remain structurally mature, with competition intensifying around checkout conversion optimization rather than basic payment acceptance.
METI's cashless rebate programs and the Payments Services Act administered by Japan's Financial Services Agency shape product standards by mandating consumer protection protocols and fund segregation requirements. JIS standards for data security and PCI-DSS compliance frameworks govern technical certification thresholds for market access. Stakeholders must monitor whether Bank of Japan digital currency pilots will force gateway providers to rebuild settlement architectures around central bank liabilities rather than commercial bank money.
Market Dynamics
QR-code interoperability standards are forcing gateway providers to rebuild settlement architectures around real-time authorization protocols, compressing transaction latency windows from seconds to milliseconds across Japan's fragmented banking infrastructure.
Growth Catalysts
- METI Cashless Rebate Programs:Government subsidies for merchant terminal upgrades accelerate SME adoption of integrated payment systems in Osaka's retail corridors.
- Tokenization Technology:Hospitality-sector merchants deploy recurring billing tokenization to reduce PCI-DSS compliance scope and fraud exposure.
- Super-App Ecosystems:Digital wallet consolidation drives checkout API demand as consumers abandon single-purpose payment apps.
Market Restraints
- Banking Infrastructure Fragmentation:Regional bank API inconsistency forces gateway providers to maintain multiple integration stacks.
- Interchange Cost Compression:Acquirer margin pressure limits gateway pricing flexibility for mid-market merchant segments.
- Legacy Terminal Base:Magnetic stripe hardware persistence in rural prefectures delays NFC and QR-code terminal refresh cycles.
Strategic Opportunities
- Bank of Japan Digital Currency Pilots:Central bank liability settlement architectures create first-mover advantage for gateway infrastructure rebuilds.
- Hokkaido and Tohoku SME Belt:Underpenetrated regional merchant acquiring offers whitespace for embedded checkout service expansion.
- API-First White Label Platforms:Mid-market demand for customizable checkout experiences without proprietary development investment accelerates.
Industry Challenges
- PCI-DSS Certification Timelines:Annual compliance audits and penetration testing requirements strain engineering resources.
- Embedded Finance Talent Scarcity:Shortage of engineers with dual expertise in payment protocols and cloud-native architecture limits platform development velocity.
- Multi-Acquirer Routing Complexity:Intelligent transaction routing across competing acquirer relationships demands sophisticated machine-learning infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Payment Gateway Market |
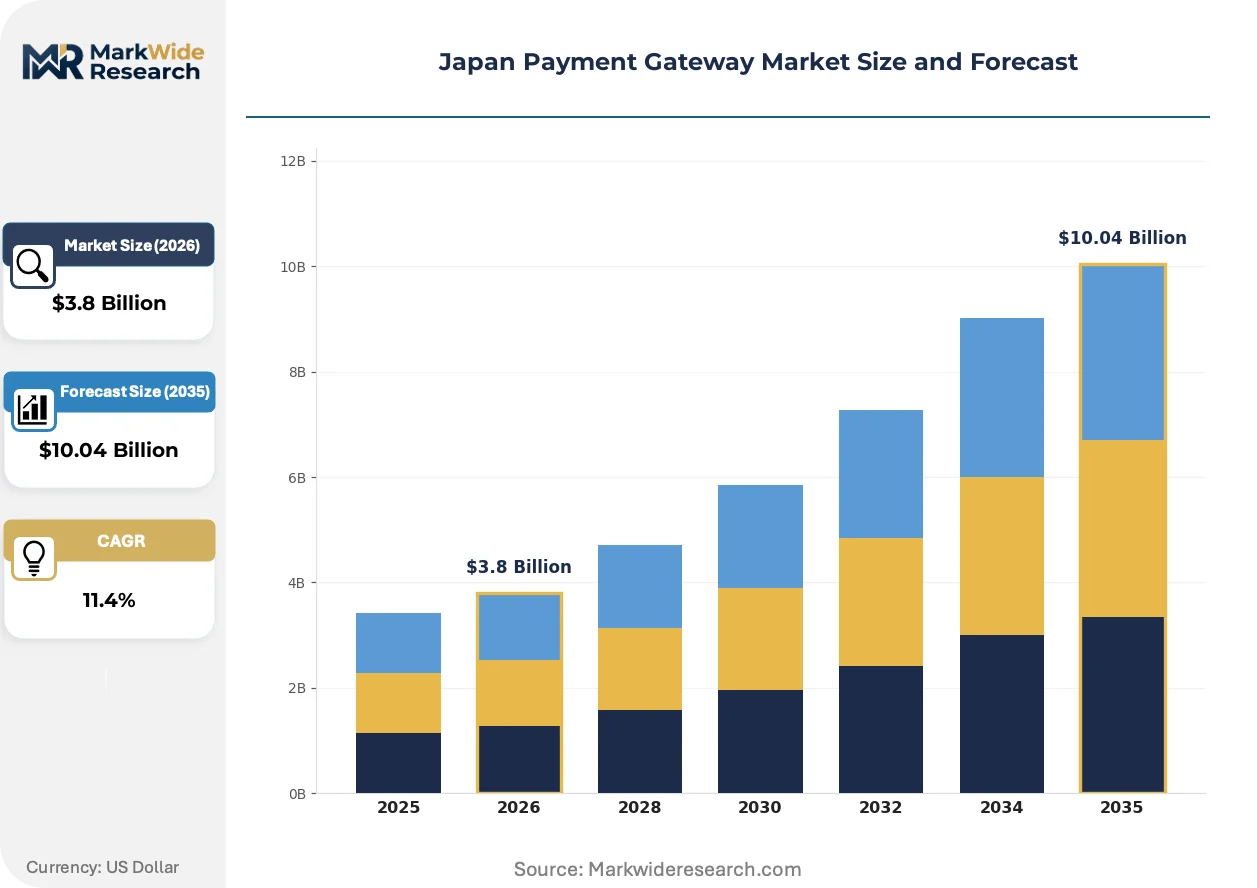
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Payments, E-commerce Solutions, Invoice Processing, Fraud Detection Technology: Tokenization, API Integration, NFC, Blockchain Industry Vertical: Retail, Hospitality, Healthcare, Education Payment Method: Credit Card, Digital Wallet, Bank Transfer, Cryptocurrency |
| Companies Covered | NTT DATA, SP. LINKS, GMO Payment Gateway, PayPay, Rakuten Pay, SB Payment Service, PAYGENT, LINE Pay, DG Financial Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Payment Gateway Market Trends and Innovations
Japan's payment gateway sector is experiencing architectural compression as real-time settlement requirements collide with legacy batch-processing infrastructure, forcing providers to rebuild core systems around event-driven microservices.
Tokenization infrastructure is consolidating transaction security layers by replacing primary account numbers with cryptographically inert tokens at the point of capture. Hospitality and subscription-commerce merchants are adopting this technology fastest, driven by recurring billing complexity and PCI scope reduction mandates. This consolidation is compressing fraud liability pools and enabling gateway providers to offer standalone security modules as revenue-bearing products.
METI's Payments Services Act amendments administered by Japan's Financial Services Agency are mandating enhanced consumer protection protocols and fund segregation requirements for non-bank payment service providers. Gateway operators must now maintain segregated trust accounts and real-time reconciliation systems. Small and mid-sized gateway providers in Tokyo's merchant-acquiring corridor face the steepest compliance cost adjustments.
Merchant procurement of checkout technology is fragmenting as vertical-specific demands outstrip generic platform capabilities. Retailers in Tokyo's transit corridors prioritize sub-second authorization latency, while hospitality operators in Kyoto and Osaka demand integrated loyalty and reservation system connectivity. This bifurcation is most visible in the Kansai region, where sector-specific gateway specialists are capturing share from horizontal platform providers.
Japan Payment Gateway Market Segmentation
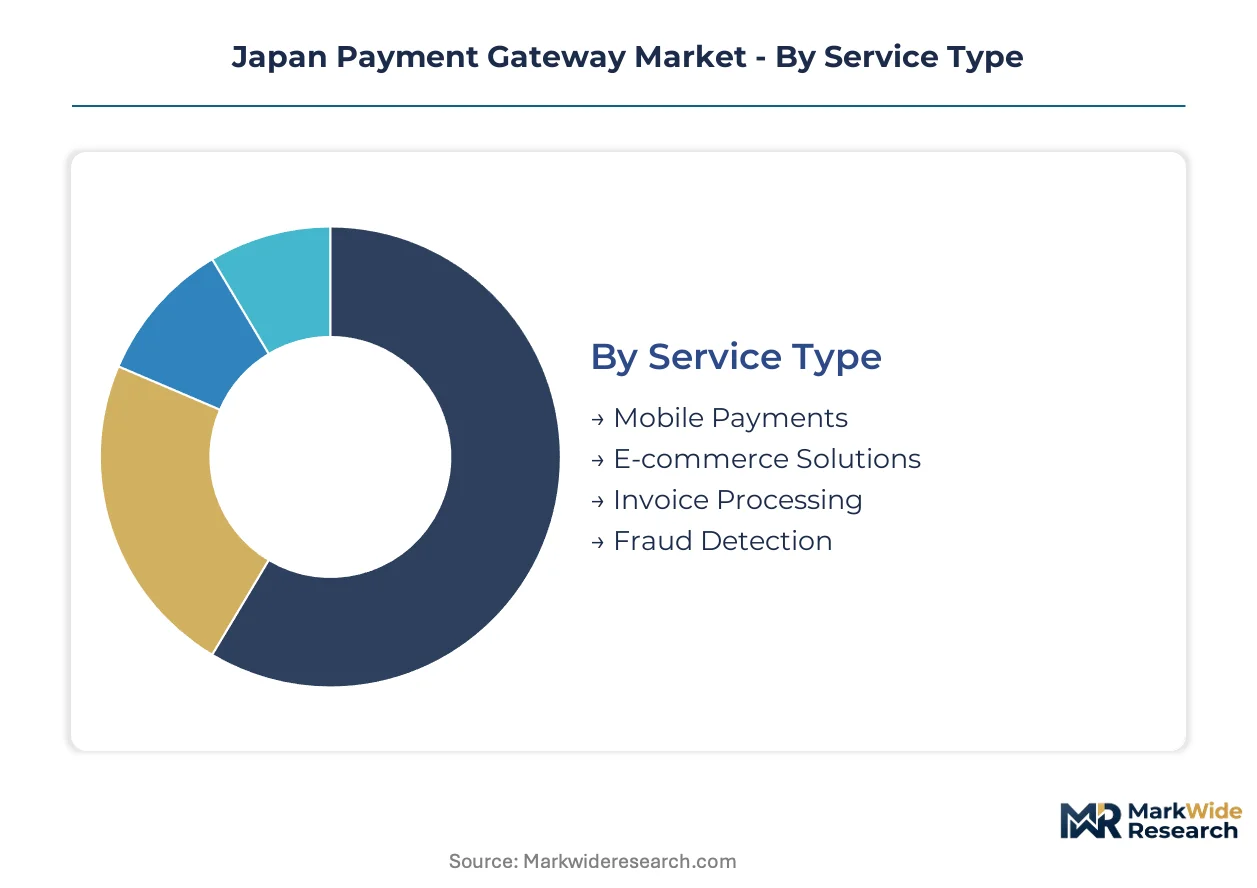
Payment gateway segmentation in Japan reveals how technical architecture and regulatory compliance reshape vendor selection across merchant tiers. Distinct service models, integration protocols, and sector-specific requirements fragment procurement patterns between Tokyo's enterprise corridor and Osaka's SME belt.
Service Type:
Standardization dominates mobile payment infrastructure while customization intensity rises through fraud detection layers.
- Mobile Payments:QR-code interoperability standards and transit corridor integration drive volume concentration. Tokyo's railway operators and convenience chains anchor demand as METI cashless rebates accelerate terminal deployment.
- E-commerce Solutions:Checkout conversion optimization and white-label API demand separate mid-market procurement from basic acceptance. Osaka's retail corridors prioritize embedded checkout customization over proprietary development investment.
- Invoice Processing:B2B automation for recurring billing workflows.
- Fraud Detection:Subscription-based security modules hardening into standalone revenue layers for gateway providers.
Most installed capacity flows through Mobile Payments. Expansion is steepest in Fraud Detection.
Technology:
Cost tier stratification separates commodity API infrastructure from premium tokenization deployments requiring PCI-DSS certification investment.
- Tokenization:Cryptographic replacement of primary account numbers reduces PCI scope and fraud liability. Hospitality merchants in Kyoto and Osaka adopt fastest for recurring billing complexity.
- API Integration:Real-time routing protocols connecting fragmented regional bank infrastructure. Mid-market merchants demand white-label customization without proprietary engineering costs.
- NFC:Contactless terminal infrastructure for transit and retail proximity payments.
- Blockchain:Experimental settlement architectures for cross-border remittance corridors.
API Integration carries the heaviest deployment volume. Tokenization gains share fastest among compliance-sensitive verticals.
Industry Vertical:
Application complexity fragments procurement between high-velocity retail authorization and hospitality's loyalty-integration demands.
- Retail:Sub-second authorization latency requirements dominate Tokyo transit corridor deployments. Checkout conversion optimization separates winning platforms from commodity acceptance providers.
- Hospitality:Integrated reservation and loyalty system connectivity demands exceed generic platform capabilities. Kyoto and Osaka operators prioritize sector-specific gateway specialists.
- Healthcare:Patient billing compliance and recurring payment scheduling for clinics.
- Education:Tuition installment processing and campus wallet ecosystems.
Retail absorbs the largest transaction volume. Hospitality climbs the fastest as sector-specific specialists capture share from horizontal providers.
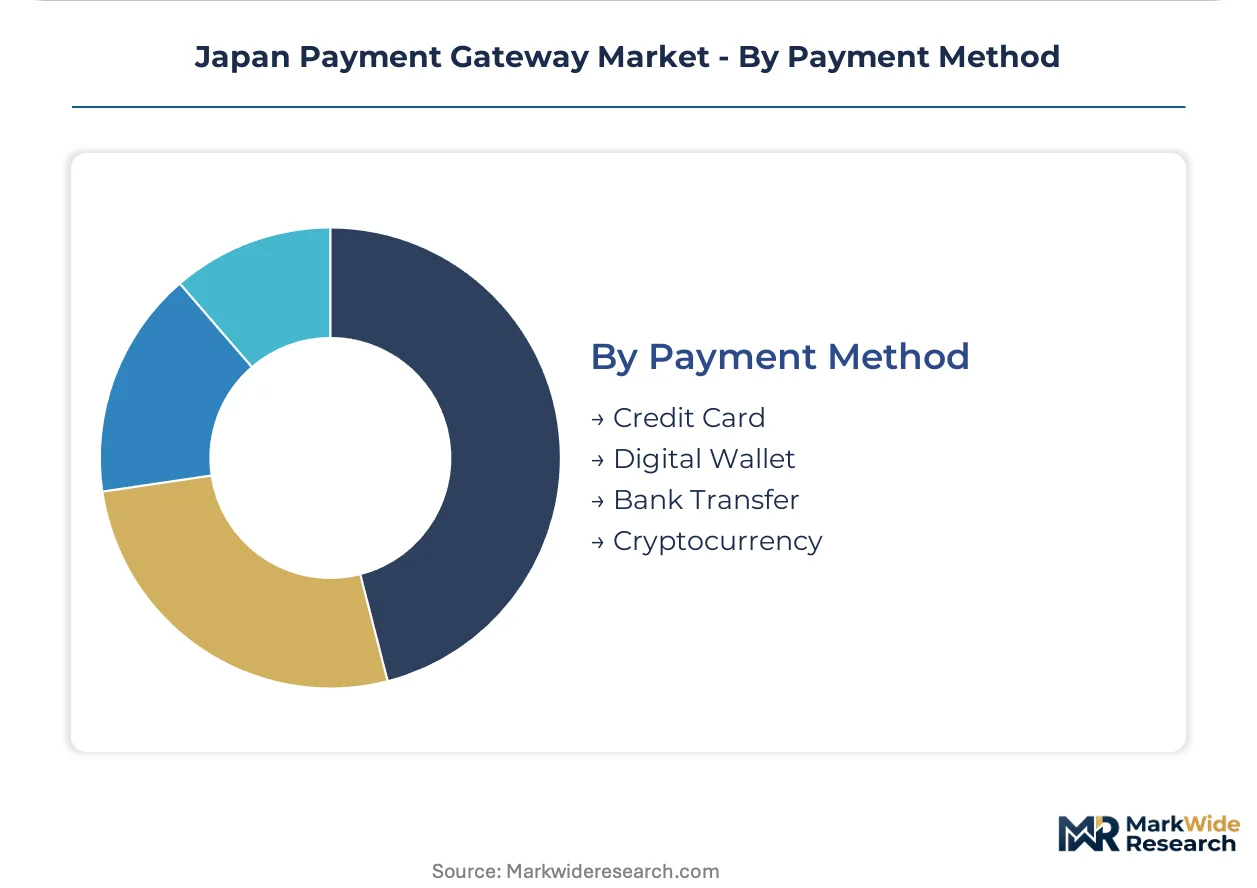
Payment Method:
Customer type bifurcation separates consumer-facing digital wallet consolidation from B2B bank transfer automation.
- Credit Card:Dominant authorization protocol with interchange cost compression limiting gateway pricing flexibility. Magnetic stripe persistence in rural prefectures delays terminal refresh cycles.
- Digital Wallet:Super-app ecosystem consolidation drives checkout API demand as consumers abandon single-purpose payment applications. Rakuten Pay and PayPay anchor Tokyo-Osaka adoption.
- Bank Transfer:Real-time settlement infrastructure for B2B invoice automation.
- Cryptocurrency:Limited merchant acceptance under Financial Services Agency fund segregation requirements.
Credit Card retains the deepest installed base. Digital Wallet expands most quickly as super-app ecosystems consolidate consumer preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's payment gateway infrastructure outpaces Australia's merchant density while trailing South Korea's real-time settlement maturity. METI cashless rebate programs and JIS standards compliance create distinct procurement patterns across Asia-Pacific corridors.
United States
Merchant acquiring consolidation and embedded finance API demand reshape gateway procurement. The Federal Reserve's FedNow instant payment rails force settlement architecture rebuilds. Silicon Valley fintech clusters and New York financial corridors anchor enterprise gateway deployment velocity.
China
Super-app ecosystem dominance and QR-code interoperability standards compress standalone gateway margins. The People's Bank of China's digital yuan pilots mandate central bank liability settlement infrastructure. Shenzhen and Hangzhou technology corridors concentrate merchant-acquiring platform development.
South Korea
Real-time bank transfer infrastructure and digital wallet consolidation accelerate gateway API demand. The Financial Services Commission's open banking mandates force multi-acquirer routing complexity. Seoul Capital Area merchants prioritize sub-second authorization latency specifications.
Singapore
Cross-border remittance corridors and ASEAN payment connectivity initiatives expand gateway addressable markets. The Monetary Authority of Singapore's digital banking licenses inject non-bank payment service competition. Raffles Place financial district anchors B2B invoice automation platform procurement.
Australia
Tap-and-go terminal saturation and buy-now-pay-later integration reshape checkout conversion optimization priorities. The Reserve Bank of Australia's least-cost routing mandates compress interchange-dependent gateway pricing. Sydney and Melbourne merchant corridors concentrate hospitality-sector tokenization adoption.
Japan Payment Gateway Market Competitive Landscape
Top-tier vendors anchor Tokyo-Osaka enterprise corridors, while regional specialists occupy prefecture-level SME belts. The vendor base stratifies across three tiers: super-app ecosystem operators, bank-integrated infrastructure providers, and vertical-specific tokenization specialists. Strategic archetypes include API-first platform builders, hospitality-sector recurring billing experts, and acquirer-agnostic routing optimizers. Competitive moves concentrate on white-label checkout customization capabilities and multi-acquirer machine-learning infrastructure.
Within the bank-integrated infrastructure tier, GMO Payment Gateway and NTT DATA exemplify deep API protocol penetration with regional financial institutions. SP. LINKS occupies a position among hospitality-sector specialists where recurring billing complexity exceeds generic platform capabilities. PayPay and Rakuten Pay represent super-app ecosystem consolidation vectors that control merchant onboarding velocity through captive consumer bases. These archetypes illustrate how technical architecture specialization and regulatory compliance depth separate winning platforms from commodity acceptance providers.
| Leading Market Players |
|---|
| NTT DATA |
| SP. LINKS |
| GMO Payment Gateway |
| PayPay |
| Rakuten Pay |
| SB Payment Service |
| PAYGENT |
| LINE Pay |
| DG Financial Technology |
| Others |
Pricing and Supply Chain Analysis
API engineering labor costs in Tokyo and Osaka cascade through three-tier pricing structures across premium, standard, and economy levels, with white-label customization premiums reflecting the scarcity of engineers fluent in both payment protocols and cloud-native architecture.
Pricing Analysis
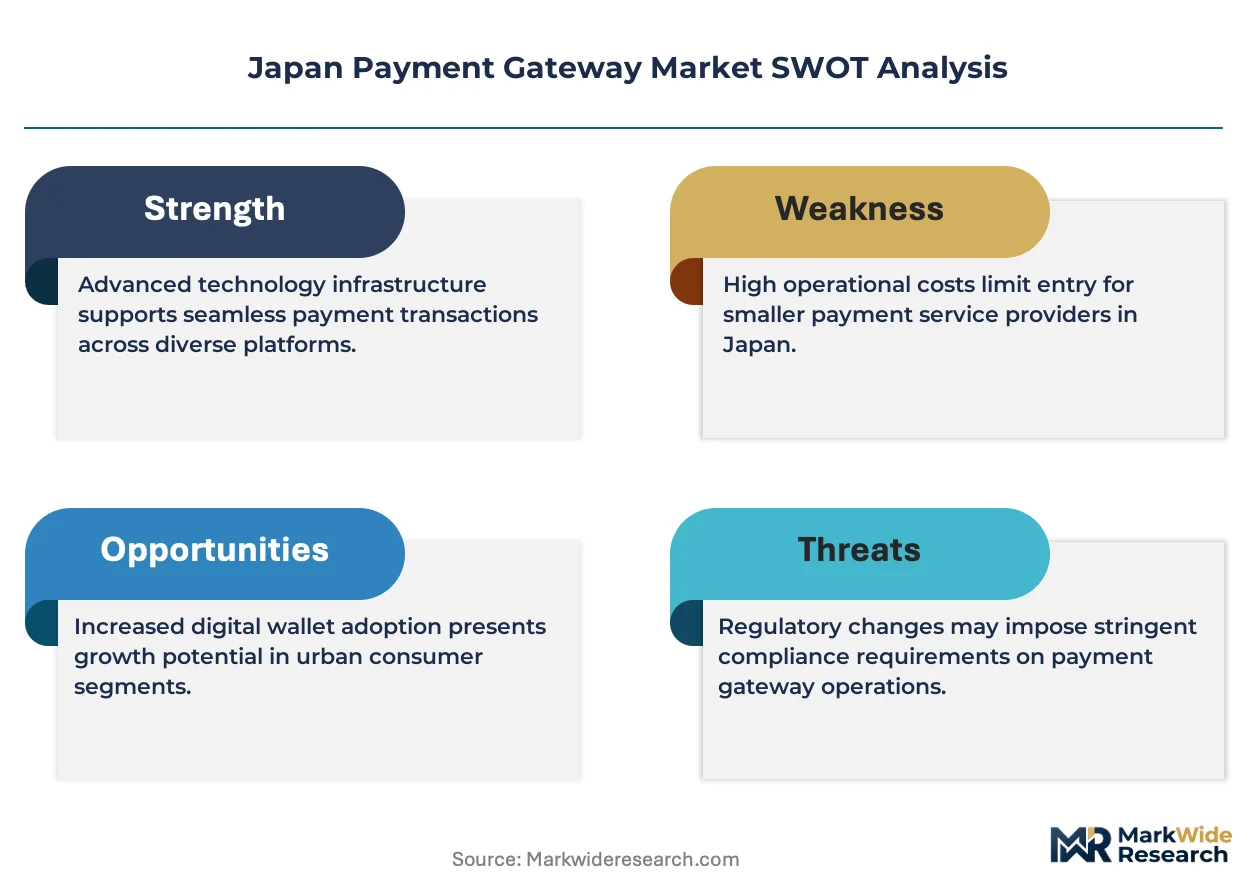
Capacity additions in Hokkaido and Tohoku are reshaping price floors for embedded checkout services as regional SME demand outstrips qualified gateway provider presence. Subscription-based fraud detection modules command premium tiers against per-transaction commodity routing, with PCI-DSS certification depth separating pricing bands. Cost compression in mid-market segments intensifies because acquirer margin pressure limits gateway flexibility. Regional bank-integrated providers exhibit lowest price sensitivity; standalone SaaS entrants face highest procurement scrutiny.
Supply Chain Analysis
Dual-sourcing requirements from METI fund segregation mandates force gateway operators to maintain redundant trust account infrastructure across multiple financial institutions. Engineering talent concentrates in Japan, Singapore, and South Korea, with cloud infrastructure dependencies drawing from AWS Tokyo, Azure Japan East, and Google Cloud Osaka regions. Single-source vulnerability rests on concentrated PCI-DSS auditor capacity. Distribution runs through direct enterprise sales for Tokyo corridor merchants and channel partners for Osaka SME belt penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's payment gateway sector offers margin expansion through tokenization premium tiers and API standardization cost-down, with METI cashless rebates accelerating addressable market growth.
For Market Incumbents: Acquire hospitality-sector tokenization specialists to fortify against SP. LINKS-style vertical specialists capturing recurring billing complexity premiums. Deepen regional bank API integration stacks to defend against PayPay and Rakuten Pay super-app ecosystem consolidation. Priority lever: multi-acquirer machine-learning routing infrastructure. For New Entrants and Emerging Players: Capture Hokkaido and Tohoku SME belt whitespace where embedded checkout penetration lags Tokyo-Osaka corridors by several years. Target hospitality operators in Kyoto seeking integrated reservation-loyalty system connectivity exceeding generic platform capabilities. Go-to-market angle: white-label API platforms eliminating proprietary engineering investment for mid-market merchants. For Investors and Strategic Acquirers: Consolidation pressure builds where regional bank API inconsistency forces subscale providers to maintain uneconomic multi-stack engineering. Long-term viability favors acquirer-agnostic routing optimizers with machine-learning infrastructure and vertical-specific tokenization depth. Acquisition target archetype: hospitality-sector specialists with recurring billing complexity moats. Signal to watch: Bank of Japan digital currency pilot architecture specifications forcing settlement rebuilds.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | White-label checkout customization captures mid-market merchants without proprietary engineering costs. |
| Multi-Acquirer Routing Infrastructure | Machine-learning optimization reduces transaction latency across Japan's fragmented regional banking network. |
| Hospitality Sector Specialization | Recurring billing tokenization addresses PCI-DSS scope reduction demands exceeding generic platform capabilities. |
| Regional Bank Partnership Expansion | Deep API protocol penetration with Osaka and Hokkaido institutions captures underpenetrated SME belt demand. |
| Digital Currency Settlement Readiness | Central bank liability architecture positioning creates first-mover advantage for gateway infrastructure rebuilds. |
Research Methodology
Coverage spans Japan's prefecture-level corridors, with primary inputs from each major merchant-acquiring cluster, combining interviews with payment gateway engineering directors, regional bank digital transformation leads, hospitality sector CIOs, and METI policy officers with secondary validation from Financial Services Agency regulatory filings, JIS standards documentation, and Bank of Japan payment system reports. Bottom-up transaction volume modeling triangulates against top-down addressable merchant density estimates.
Granularity-level framing segments the market by service type, technology protocol, industry vertical, and payment method, with regional adoption patterns modeled at prefecture level. CAGRs derive from trajectory analysis of installed terminal base, API integration velocity, and super-app ecosystem consolidation rates. Forecast inputs include METI cashless rebate program enrollment curves and QR-code interoperability standard deployment timelines across the projection horizon.
Bank of Japan digital currency pilot scope changes, regional bank API standardization delays, and super-app ecosystem consolidation acceleration are the dominant revision risks. Deviation in central bank settlement architecture specifications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Convergent Billing Market
Payments
Canada POS Terminal Market
Payments
Italy Gift Cards Market
Payments
Italy POS Terminals Market
Payments
Mexico Digital Wallet Market
Payments
Global Gift Card Market
Payments
Consumer Mobile Payment Market
Payments
B2B Payments Market
Payments
Canada Gift Card and Incentive Card Market
Payments
China Payment Gateway Market
Payments
South Korea POS Terminals Market
Payments
Payment Processing Solutions Market
Payments
Spain Payments Market
Payments
Romania POS Terminals Market
Payments
China Real Time Payments Market
Payments
China POS Terminals Market