
 Middle East AI in Fintech Market | 2026-2036
Middle East AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East AI in Fintech Market Analytics
Gulf-based cloud infrastructure providers is recalibrating service availability for financial workloads across Abu Dhabi, Riyadh, and Dubai data centers. IBM leverages its Watson platform to anchor AI governance tooling for regional banks navigating compliance complexity. Microsoft sustains Azure AI deployments through dedicated UAE and Qatar cloud regions, competing directly with Google Cloud's specialized financial services compute instances. Emirates NBD differentiates by operating an in-house AI lab focused on Arabic-language natural language processing for customer-facing applications.
Middle East AI in Fintech encompasses machine learning algorithms, natural language processing engines, and predictive analytics platforms engineered to automate credit decisions, detect anomalous transactions, and personalize financial recommendations across banking and insurance workflows. These systems typically process structured and unstructured data at sub-second latency thresholds to satisfy real-time payment clearing requirements. Fraud detection and risk assessment services dominate current revenue pools as banks prioritize regulatory compliance and loss prevention over customer experience automation. Cloud-based deployment is expanding fastest among neobanks and payment processors lacking legacy mainframe infrastructure, while hybrid architectures persist among established lenders managing sensitive core banking data on-premises.
SAMR in Saudi Arabia and the UAE central bank enforce sandbox licensing frameworks that shape which AI vendors gain market access, with data residency mandates forcing localization of model training infrastructure. Saudi Arabia's Personal Data Protection Law and the UAE's forthcoming federal data governance standards impose strict cross-border transfer restrictions on fintech AI systems processing customer financial records. Stakeholders must monitor evolving central bank digital currency integrations and open banking API mandates that will determine which AI feature sets become table stakes for competitive positioning.
Market Dynamics
Data residency mandates from SAMR and the UAE central bank are forcing AI vendors to localize model training infrastructure, compressing vendor onboarding timelines while fragmenting cloud architecture decisions across Saudi Arabia and the Emirates.
Growth Catalysts
- Central bank sandbox licensing:SAMR and the UAE central bank frameworks accelerate vendor qualification for digital banking licenses, reducing time-to-market for AI-native payment processors.
- Neobank cloud-native architecture:Payment processors and digital banks lacking legacy mainframe infrastructure deploy AI fraud detection at sub-second latency without hybrid complexity.
- Dubai DIFC fintech clustering:Concentration of payment processors and wealth management platforms in the DIFC creates demand density for Arabic-language NLP engines.
Market Restraints
- Cross-border data transfer restrictions:Saudi Arabia's Personal Data Protection Law and pending UAE federal data governance standards block model training on pooled regional datasets.
- GPU compute supply concentration:Specialized financial services AI training hardware concentrates through limited cloud region availability in Abu Dhabi, Riyadh, and Dubai data centers.
- Legacy core banking integration friction:Established lenders maintain sensitive customer records on-premises, forcing expensive hybrid AI architectures that neobanks avoid.
Strategic Opportunities
- Central bank digital currency integration:SAMR and UAE central bank CBDC pilots will mandate real-time AI transaction monitoring, creating mandatory demand for predictive analytics platforms.
- Open banking API mandates:Regulatory requirements for standardized financial data sharing enable AI-powered personalized wealth management tools to aggregate cross-institutional customer profiles.
- Arabic NLP specialization:Emirates NBD's in-house AI lab demonstrates technical feasibility for customer-facing applications, opening white space for vendor-provided dialect-aware language models.
Industry Challenges
- Compliance timeline compression:Rapidly evolving sandbox licensing requirements force vendors to revalidate AI governance tooling against shifting SAMR and UAE central bank standards mid-deployment.
- Model explainability for regulatory audits:Credit decision automation using machine learning faces scrutiny under emerging AI accountability frameworks, requiring interpretable algorithm architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East AI in Fintech Market |
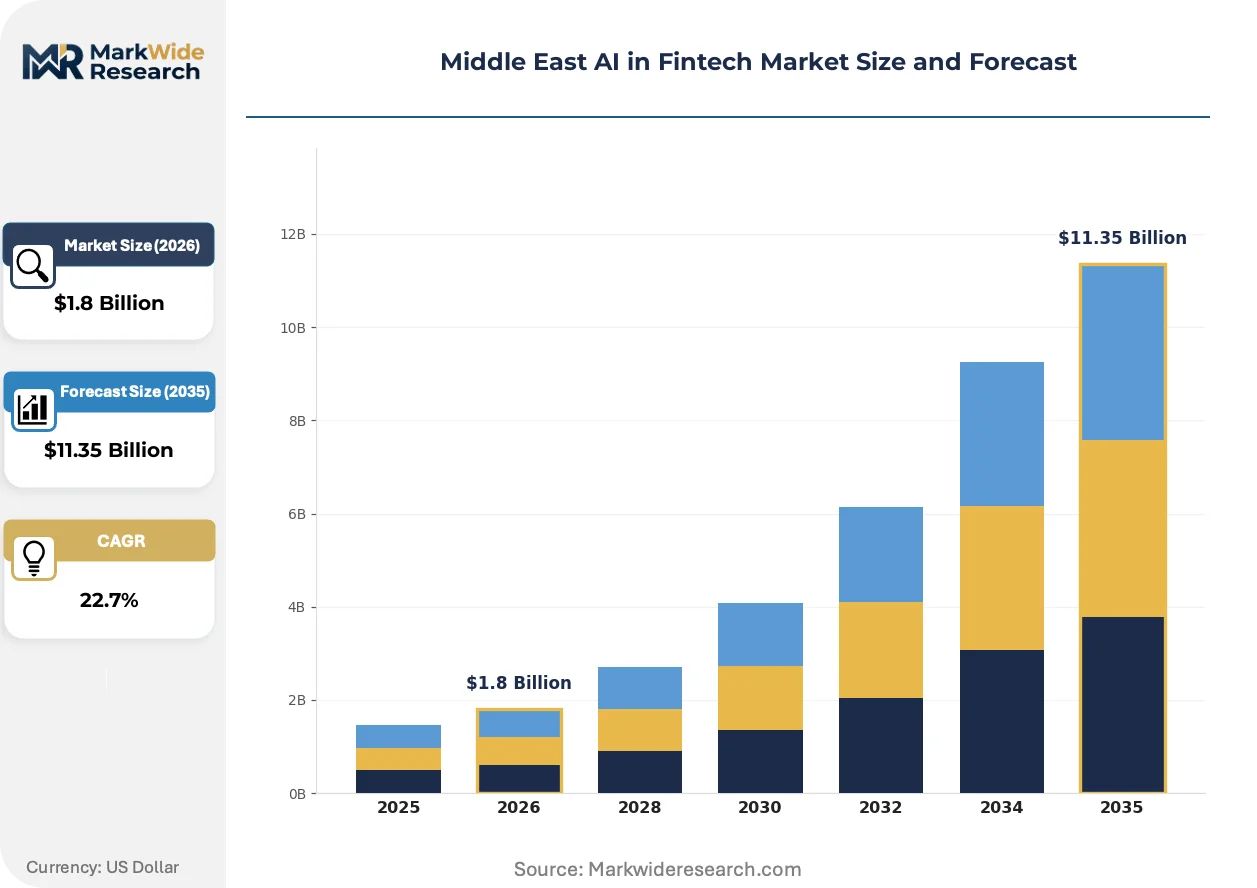
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fraud Detection, Risk Assessment, Customer Service, Personal Finance Management Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Banks, Insurance Companies, Investment Firms, Payment Processors Feature: Chatbots, Predictive Analytics, Algorithmic Trading, Credit Scoring |
| Companies Covered | IBM, Microsoft, Google, SAS Institute, Emirates NBD, Mashreq Bank, Personetics, Tabby, FICO, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East AI in Fintech Market Evolving Landscape
Machine learning deployment patterns across Middle East banking are pivoting from batch-processed risk scoring to real-time inference at the transaction edge, compressing the window between data ingestion and automated decision execution.
Natural language processing engines optimized for Arabic dialects are expanding into customer service automation, replacing rule-based chatbots in retail banking. Emirates NBD and regional competitors deploy these systems for voice-based authentication and wealth management advisory. This capability compression is reducing human agent handling time while raising the technical bar for vendor qualification.
SAMR's sandbox licensing framework and the UAE central bank's digital banking regulations are mandating pre-deployment AI model validation for fraud detection systems. Banks must demonstrate sub-second anomaly identification with documented false-positive rates before production approval. Neobanks gain advantage through greenfield cloud architectures that established lenders retrofit at higher compliance cost.
Buyer procurement for AI infrastructure is consolidating toward outcome-based performance contracts rather than perpetual software licenses. Payment processors in Dubai's DIFC negotiate vendor agreements tied to measured fraud reduction percentages, shifting risk to solution providers. Saudi Arabia's SAMR-authorized institutions show strongest appetite for this model, pressuring legacy pricing structures.
Middle East AI in Fintech Market Segmentation
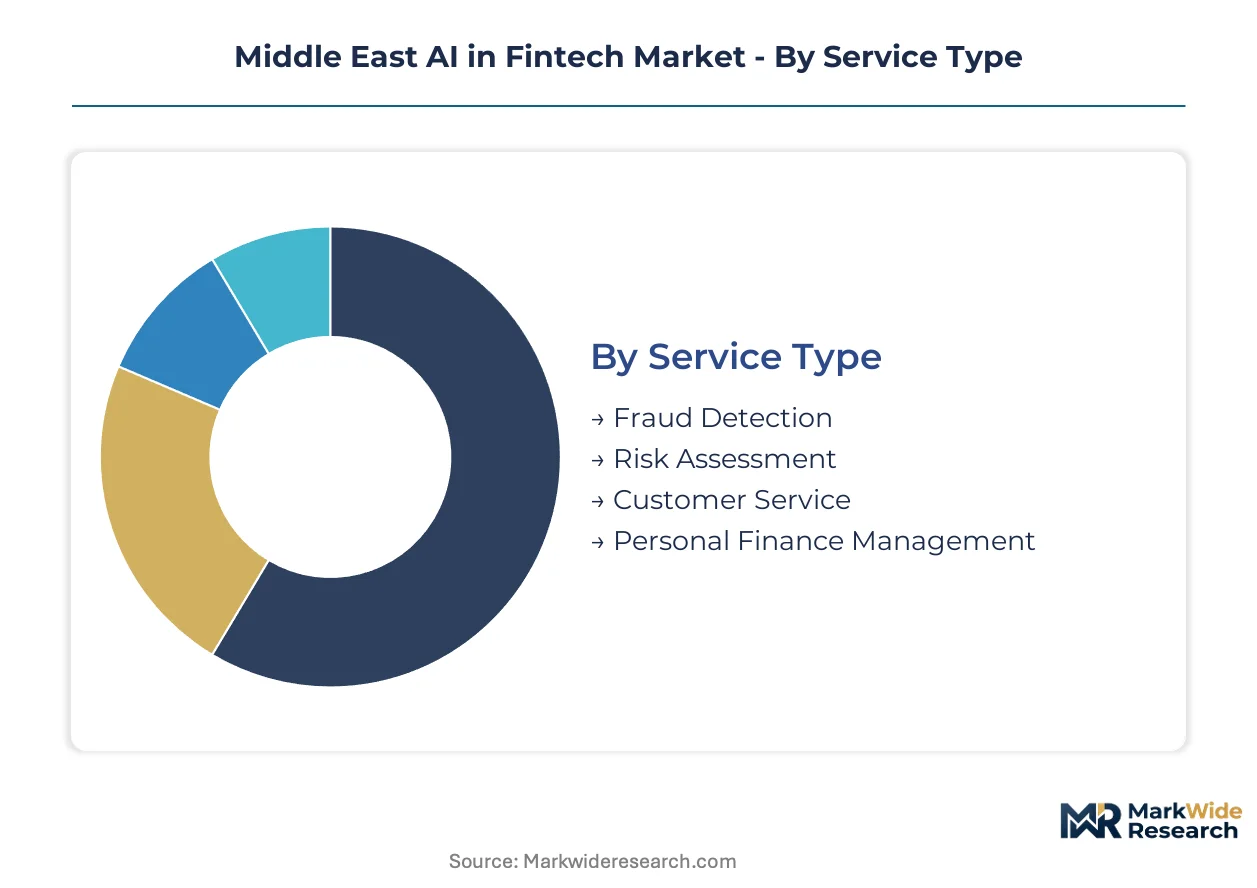
Middle East AI in Fintech Market segmentation reveals distinct integration patterns across service architectures. Deployment mode and end-user infrastructure maturity determine whether AI functions as embedded capability or standalone system.
Service Type:
Standalone fraud detection platforms operate independently from core banking systems, while customer service AI embeds directly into existing digital channels.
- Fraud Detection:Real-time transaction monitoring systems process structured payment data through anomaly detection algorithms. SAMR-authorized Saudi banks and UAE central bank licensees concentrate procurement here, driven by mandatory sub-second latency requirements for production approval.
- Risk Assessment:Machine learning models evaluate creditworthiness using alternative data streams including behavioral biometrics and mobile wallet patterns. Demand clusters among Dubai DIFC payment processors seeking to automate underwriting without legacy mainframe dependencies.
- Customer Service:Arabic-language NLP engines power voice authentication and wealth management advisory workflows.
- Personal Finance Management:Predictive budgeting tools aggregate cross-institutional spending patterns through open banking APIs.
Volume placements concentrate in Fraud Detection; the faster expansion belongs to Risk Assessment.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from operational-expense cloud models favored by neobanks.
- Cloud-Based:GPU compute instances from Microsoft Azure UAE and Google Cloud Qatar regions host model training for payment processors lacking legacy infrastructure. Neobanks bypass hybrid complexity entirely, deploying sub-second inference without on-premises hardware.
- Hybrid:Established lenders maintain sensitive core banking records locally while pushing non-critical workloads to cloud regions. Saudi Arabia's data residency mandates force this architecture despite higher compliance costs.
- On-Premises:Full-stack local deployment satisfies strictest cross-border transfer restrictions under the kingdom's Personal Data Protection Law.
- Edge Computing:Transaction-level inference at payment terminals reduces round-trip latency for real-time authorization decisions.
Procurement volumes favor Hybrid architectures; Cloud-Based deployment climbs the fastest among greenfield entrants.
End User:
Customer type determines whether AI procurement targets regulatory compliance or revenue-generating personalization.
- Banks:Emirates NBD and regional competitors operate in-house AI labs for Arabic NLP development, while smaller institutions purchase vendor-managed fraud detection services.
- Payment Processors:Dubai DIFC clustering creates demand density for real-time transaction monitoring without legacy integration friction.
- Insurance Companies:Claims automation and actuarial risk modeling drive adoption of predictive analytics platforms.
- Investment Firms:Algorithmic trading systems and portfolio optimization tools constitute primary AI investment.
Banking institutions anchor current procurement; payment processors are gaining share fastest through outcome-based performance contracts.
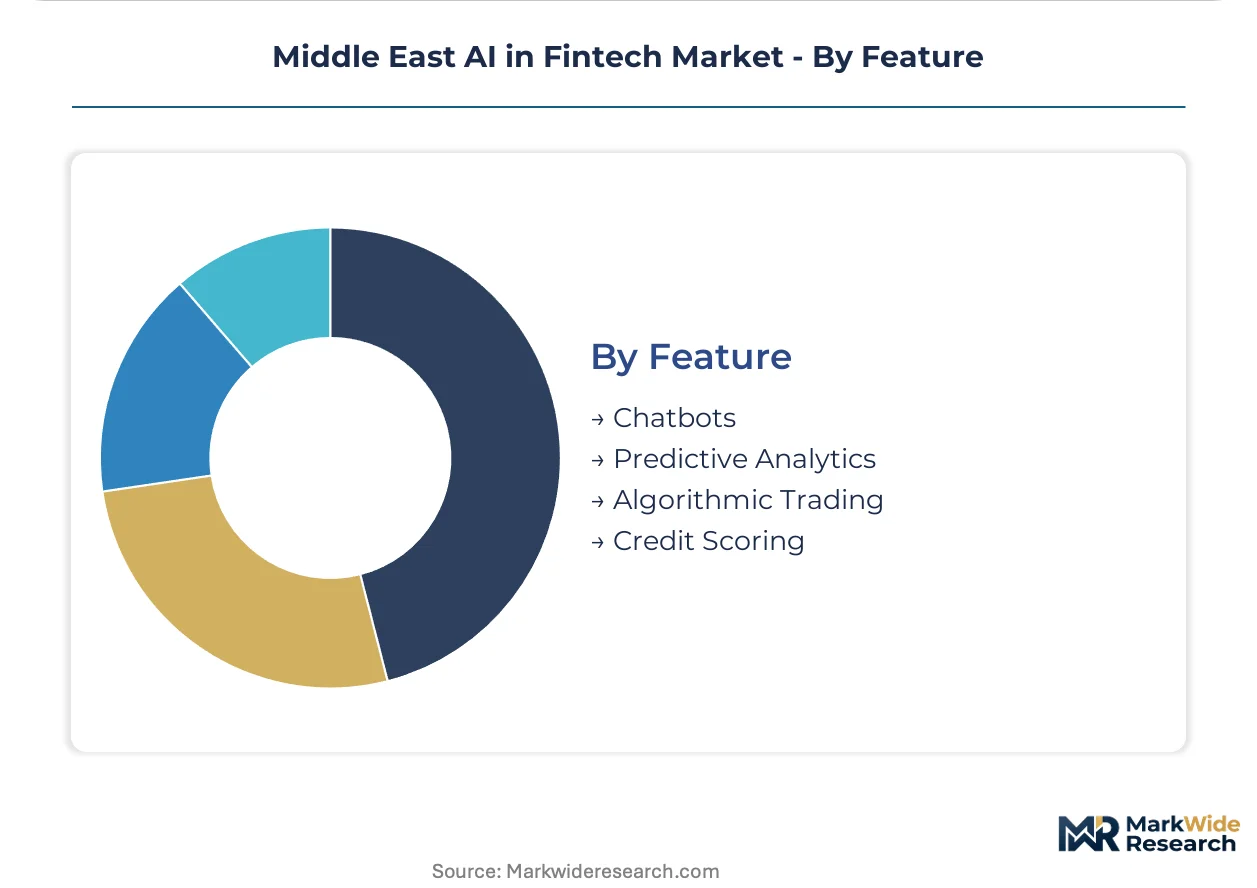
Feature:
Technology maturity separates production-grade capabilities from experimental deployments.
- Predictive Analytics:Time-series forecasting engines power credit scoring and liquidity management across Saudi and UAE financial institutions. Central bank sandbox licensing mandates pre-deployment validation, compressing vendor onboarding timelines.
- Chatbots:Rule-based systems yield to dialect-aware Arabic NLP for voice-based authentication and wealth advisory. Emirates NBD's technical demonstration raises qualification barriers for vendor entry.
- Credit Scoring:Alternative data models expand financial inclusion beyond traditional bureau dependencies.
- Algorithmic Trading:Quantitative execution systems remain concentrated among investment firms in Dubai's DIFC.
Chatbot deployments dominate current volumes; predictive analytics carries the steepest expansion trajectory as CBDC pilots mandate real-time monitoring infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU compute clusters in Abu Dhabi, Riyadh, and Dubai anchor regional AI training capacity for financial workloads. SAMR and UAE central bank data residency mandates force localization of model infrastructure. Cloud region availability concentrates vendor deployment decisions across these three metropolitan hubs.
United Arab Emirates
Dubai's DIFC fintech cluster generates concentrated demand for Arabic-language NLP engines and real-time fraud detection. The UAE central bank's digital banking licensing framework compresses vendor onboarding timelines for AI-native payment processors. Abu Dhabi data centers host Microsoft Azure and Google Cloud financial services compute instances serving Emirates NBD's in-house AI lab developments.
Saudi Arabia
Riyadh-based SAMR-authorized institutions drive procurement of predictive analytics platforms for credit decision automation. The kingdom's Personal Data Protection Law imposes strict cross-border transfer restrictions on customer financial records. NEOM and the Eastern Province are emerging as secondary data center locations for localized model training infrastructure.
Qatar
Doha's financial sector generates demand for cloud-based AI deployments among neobanks lacking legacy mainframe dependencies. The Qatar Central Bank's regulatory sandbox creates pathways for vendor qualification in transaction monitoring systems. Lusail's smart city infrastructure incorporates edge computing for real-time payment authorization at retail terminals.
Israel
Tel Aviv's cybersecurity expertise feeds specialized fraud detection algorithm development for regional banking clients. The Bank of Israel's fintech licensing framework accommodates AI-powered risk assessment tools. Jerusalem-based research institutions contribute machine learning talent to Arabic dialect processing challenges.
Kuwait
Kuwait City banking institutions prioritize hybrid AI architectures managing sensitive core records on-premises. The Central Bank of Kuwait's pending open banking regulations will mandate API-standardized data sharing for personalized wealth management tools. Al-Shaheed Park's technology district hosts emerging fintech incubators exploring CBDC integration pilots.
Middle East AI in Fintech Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and specialized financial AI services. The market structures around three tiers: hyperscale cloud providers with dedicated regional data centers, global enterprise software vendors with governance tooling expertise, and Gulf-based financial institutions operating captive AI development labs. Strategic moves concentrate on outcome-based performance contracting and Arabic-language NLP capability acquisition.
Within the hyperscale infrastructure tier, Microsoft and Google occupy positions as primary compute providers through UAE and Qatar cloud regions. IBM exemplifies the enterprise governance archetype with Watson-platform regulatory tooling for SAMR compliance navigation. Emirates NBD anchors the captive development model, demonstrating technical feasibility for in-house Arabic NLP applications that raise qualification barriers for external vendors.
| Leading Market Players |
|---|
| IBM |
| Microsoft |
| SAS Institute |
| Emirates NBD |
| Mashreq Bank |
| Personetics |
| Tabby |
| FICO |
| Others |
Value Network & Pricing Analysis
Machine learning engineer concentration across Tel Aviv, Dubai, and Riyadh generates labor-cost differentials that widen pricing-tier spreads between premium Arabic NLP implementations and standardized fraud detection modules. SAMR compliance validation requirements in Saudi Arabia compress margins for vendors lacking localized model training infrastructure, forcing price stratification based on regulatory certification depth rather than feature sophistication alone.
Pricing Analysis
Service bundling separates compliance-validated AI governance tooling from unbundled inference-only API access, with SAMR-authorized Saudi banks paying premium rates for pre-validated fraud detection systems that include documented false-positive rate guarantees. Price differentiation rests on two factors: regulatory sandbox certification tier and Arabic dialect coverage breadth. Pricing pressure stems from outcome-based performance contracts gaining traction among Dubai DIFC payment processors, who negotiate vendor fees tied to measured fraud reduction percentages rather than fixed licensing. Neobanks exhibit highest price sensitivity due to capital constraints, while established lenders with captive AI labs demonstrate lowest sensitivity as they benchmark against in-house development costs.
Supply Chain Analysis
GPU compute specialist availability concentrates in Abu Dhabi, Riyadh, and Dubai data center clusters, constraining model training capacity expansion for vendors seeking SAMR or UAE central bank authorization. Raw material dependencies center on NVIDIA A100/H100 accelerators, high-bandwidth memory modules, and specialized cooling infrastructure for financial services workloads. Supply chain risk manifests as single-source vulnerability to NVIDIA's foundry allocation decisions, compounded by US export control uncertainty affecting Middle East cloud region provisioning. Distribution runs through hyperscale cloud providers—Microsoft Azure UAE and Google Cloud Qatar—who control access to localized financial services compute instances, with neobanks and payment processors purchasing through outcome-based channel partnerships rather than direct hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with localized model training infrastructure, as SAMR and UAE central bank data residency mandates force smaller players without Gulf data center presence into unprofitable compliance investments or exit.
For Market Incumbents: Anchor defensive positioning through exclusive partnerships with Abu Dhabi and Riyadh data center operators to lock in GPU compute allocation priority, while acquiring Arabic NLP specialist teams to neutralize Emirates NBD's technical differentiation. The threat of outcome-based pricing commoditization from Dubai DIFC payment processors demands vertical integration into model validation services, converting compliance cost centers into revenue-generating audit capabilities that smaller vendors cannot replicate. For New Entrants and Emerging Players: Capture white space in Qatar's neobank segment and Kuwait's pending open banking API infrastructure, where regulatory frameworks are less mature and incumbent presence remains thin. The most penetrable entry point lies in dialect-aware voice authentication systems for Saudi Arabia's underserved Eastern Province banking networks, leveraging Tel Aviv cybersecurity algorithm expertise through technical licensing rather than capital-intensive cloud buildout. For Investors and Strategic Acquirers: The window for entry favors vendors with validated SAMR sandbox credentials and existing UAE central bank relationships, as regulatory friction accelerates consolidation toward pre-qualified players. Acquisition targets should demonstrate proven sub-second latency architecture and documented false-positive rate performance under live transaction loads. The signal to watch is central bank digital currency pilot expansion, which will mandate real-time AI monitoring infrastructure and eliminate vendors lacking proven production-scale deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Pre-Qualification | SAMR and UAE central bank validation compresses vendor onboarding timelines for AI-native payment processors. |
| Arabic NLP Capability Acquisition | Specialized dialect processing teams neutralize Emirates NBD's in-house technical differentiation. |
| Outcome-Based Contract Structuring | Fraud reduction percentage guarantees shift performance risk from Dubai DIFC buyers to solution providers. |
| GPU Compute Partnership Lock-in | Exclusive Abu Dhabi and Riyadh data center agreements secure training capacity against supply constraints. |
| CBDC Integration Readiness | Real-time transaction monitoring architecture positions vendors for mandatory SAMR pilot participation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with SAMR compliance officers, UAE central bank digital banking leads, hyperscale cloud procurement managers, and neobank CTOs across Dubai DIFC and Riyadh. SEC 10-K disclosures from IBM and Microsoft, SAMR sandbox authorization lists, and UAE central bank licensed fintech registries provided vendor market presence validation. Bottom-up triangulation across service type deployment volumes and top-down reconciliation against aggregate cloud capex disclosures in UAE and Qatar regions ensured figure consistency.
Granularity-level modeling operated at service type, deployment mode, and end-user dimensions, with additional segmentation by regulatory jurisdiction cluster reflecting SAMR versus UAE central bank compliance pathways. CAGRs were derived from fitted growth curves applied to base-year vendor revenue estimates, cross-checked against hyperscaler regional cloud revenue disclosures and fintech licensing velocity trends. Forecast inputs incorporated CBDC pilot expansion scenarios and open banking API mandate timing assumptions across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to SAMR and UAE central bank regulatory evolution, GPU compute supply availability, and cross-border data transfer restriction enforcement. Forecasts reflect documented assumptions regarding sandbox licensing velocity and neobank formation rates. Material deviation in central bank digital currency pilot scope or export control regime changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Transaction Monitoring Software Market
FinTech
Embedded Finance Market
FinTech
AI Finance Market
FinTech
Financial Management Software Market
FinTech
Finance Cloud Market
FinTech
France AI in Fintech Market
FinTech
Netherlands AI in Fintech Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Digital Banking Platform Market
FinTech
Vietnam Fintech Market
FinTech
Japan AI in Fintech Market
FinTech
Global Fundraising Software Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
Indonesia Financial Technology Services Market