
 Corporate Banking Market | 2026-2036
Corporate Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Corporate Banking Market Analysis
Investment-grade credit tiering is reorganizing how corporate banks price risk and allocate balance sheet capacity. JPMorgan Chase anchors its dominance through scale advantages in syndicated lending and global treasury infrastructure. Goldman Sachs differentiates via its specialization in leveraged finance and capital markets advisory for complex corporate restructurings. Citigroup competes through geographic breadth, sustaining cross-border trade finance corridors that link North American multinationals to emerging market operations.
Corporate banking encompasses the provision of credit, treasury, and advisory services to non-financial enterprises, operating through relationship-managed credit facilities with tenor structures ranging from revolving commitments to term loans of five to ten years. Its primary purpose centers on financing working capital cycles, funding capital expenditures, and optimizing liquidity across multi-entity corporate structures. Corporate loans represent the mature revenue pool where net interest margins face compression from competitive pricing, while treasury management services generate sticky fee income with lower capital intensity. Cash management offerings are expanding fastest as real-time payment infrastructure and API-based connectivity reshape how SMEs and large corporations interact with banking platforms.
The Federal Reserve's stress testing framework and the SEC's disclosure requirements for public debt issuers shape how banks model credit risk and report exposure concentrations. Basel Committee standards filter into domestic rulemaking through the Federal Reserve and OCC, tightening capital buffers for corporate loan portfolios and tilting origination toward investment-grade borrowers. Stakeholders must monitor how artificial intelligence-driven credit decisioning interfaces with fair lending oversight from the CFPB and prudential expectations for model risk management.
Market Dynamics
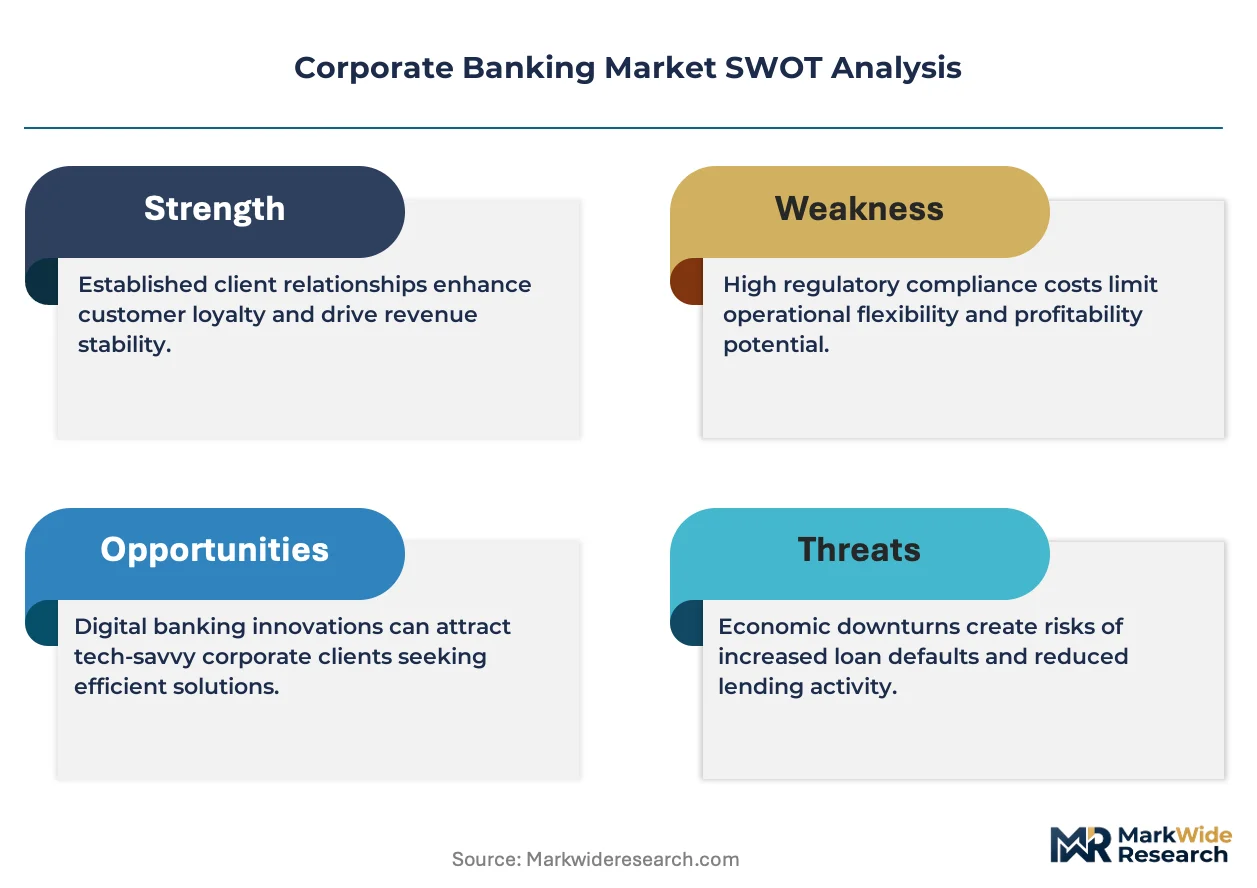
Basel III endgame capital requirements are compressing risk-weighted asset efficiency and forcing banks to restructure syndicated lending commitments toward shorter tenors and investment-grade borrowers.
Growth Catalysts
- API-based treasury connectivity:Real-time payment infrastructure enables mid-market corporates to consolidate multi-bank relationships onto single platforms, expanding addressable client bases for cash management services.
- Technology sector credit demand:Specialized facilities for cloud infrastructure and AI compute clusters draw new origination volumes from capital-intensive borrowers with non-traditional collateral profiles.
- US treasury consolidation:Multinational corporations are centralizing liquidity operations with top-tier domestic institutions, concentrating fee income and deposit balances in American money-center banks.
Market Restraints
- Basel III capital absorption:Higher risk-weighted asset charges on corporate loan portfolios compress net interest margins and reduce returns on committed capital.
- Deposit beta volatility:Rising funding costs outpace asset repricing in rising rate environments, squeezing core banking profitability.
- Non-bank lender substitution:Private credit funds and direct lending platforms capture leveraged finance opportunities with lighter regulatory constraints.
Strategic Opportunities
- SME embedded finance:Banking-as-a-Service partnerships with enterprise software platforms unlock previously uneconomical small-business relationships at scale.
- EU sustainable finance taxonomy:Green loan frameworks and transition financing incentives create differentiated product positioning for ESG-linked credit facilities.
- AI-driven credit decisioning:Machine learning models applied to alternative data sources accelerate underwriting velocity and expand addressable borrower segments.
Industry Challenges
- Model risk management:Prudential regulators demand explainable AI frameworks and bias testing for automated credit scoring systems, extending implementation timelines.
- Legacy core modernization:Decades-old payment and lending infrastructure requires costly replacement to support real-time data and API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corporate Banking Market |
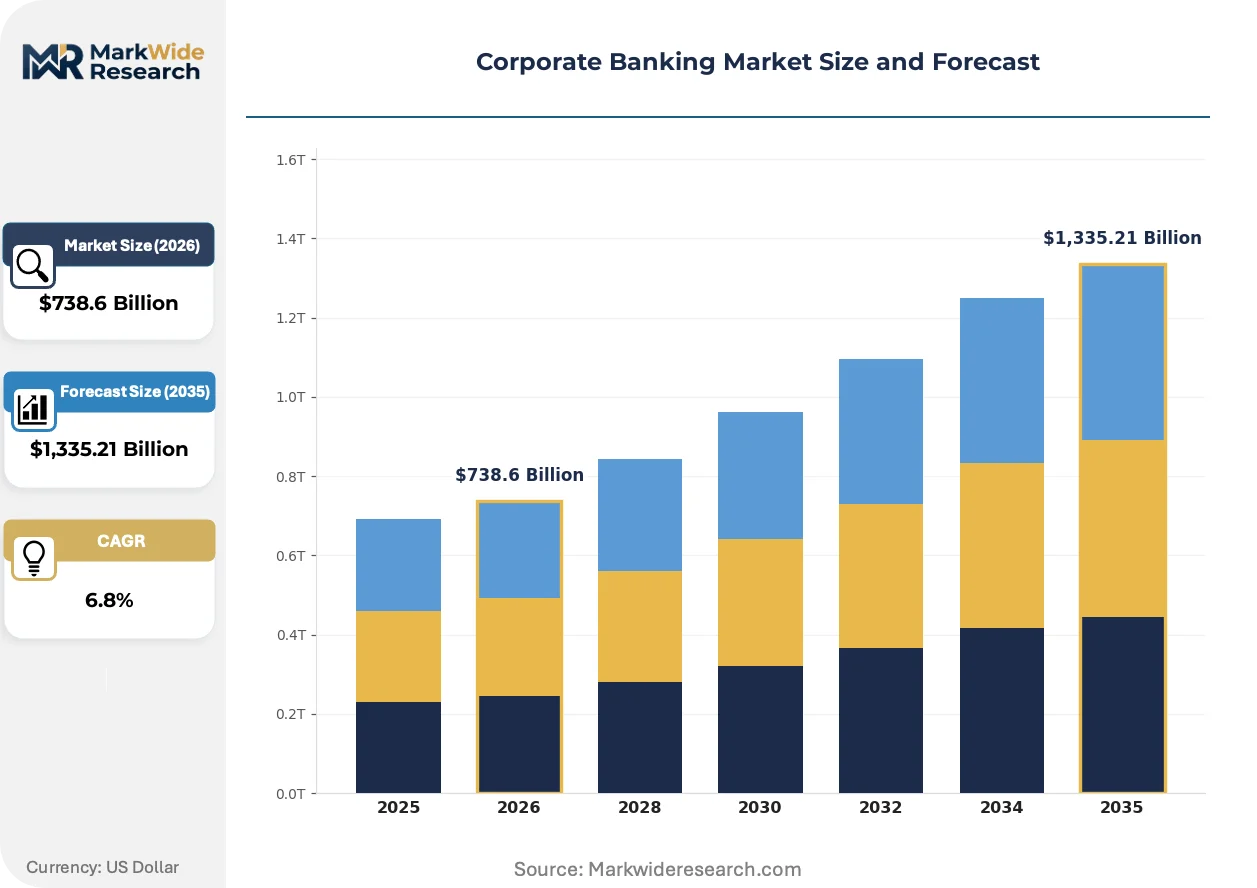
| Market Size in 2026 | $738.6 Billion |
| Market Size in 2035 | $1,335.21 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
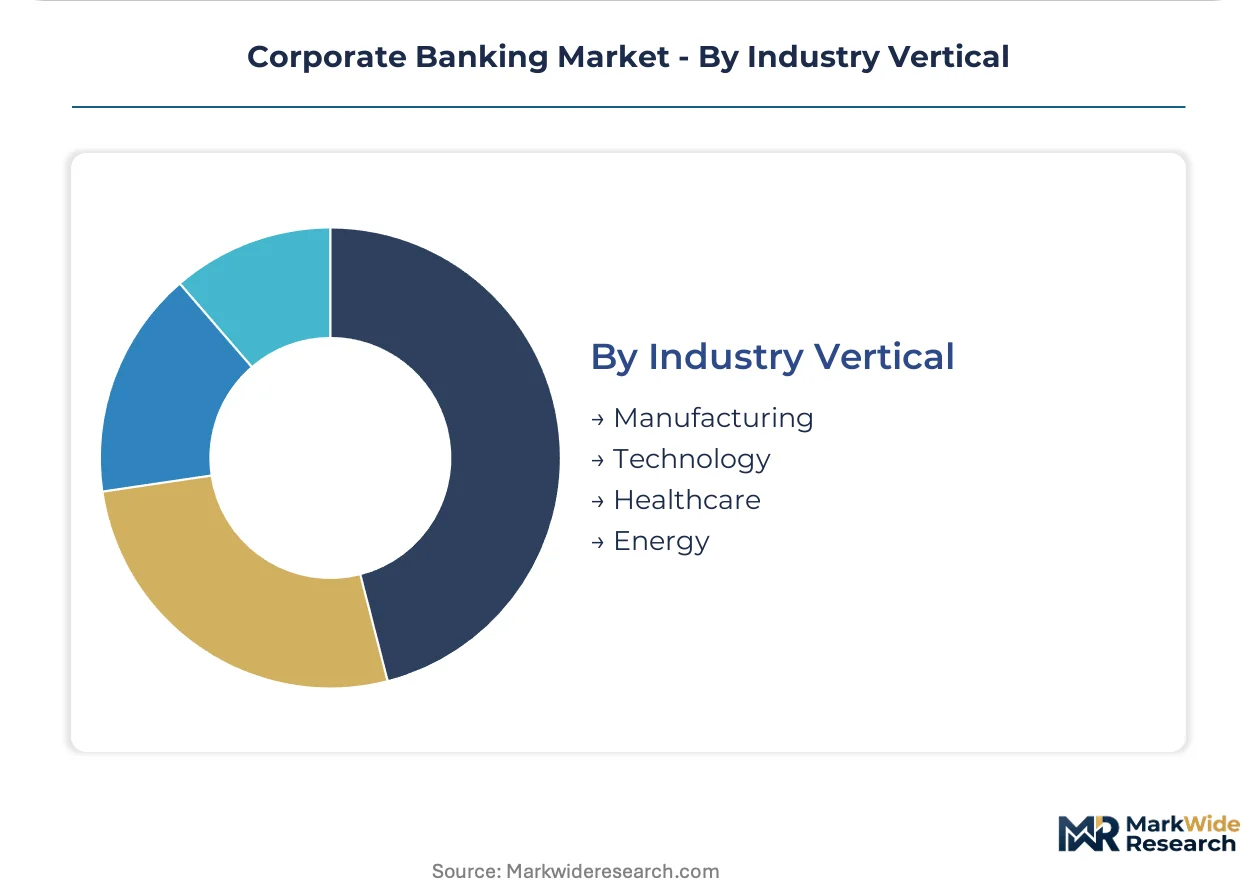
| Segmentation | Service Type: Corporate Loans, Treasury Management, Investment Banking, Cash Management Client Type: Large Corporations, SMEs, Multinational Companies, Startups Product Type: Trade Finance, Commercial Mortgages, Capital Markets, Deposit Products Industry Vertical: Manufacturing, Technology, Healthcare, Energy |
| Companies Covered | Wells Fargo, Morgan Stanley, JPMorgan Chase, PNC Financial Services, U.S. Bancorp, Bank of America, Goldman Sachs, Charles Schwab, Citigroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corporate Banking Market Emerging Trajectories
Artificial intelligence and embedded finance architectures are fragmenting traditional relationship-banking models and compressing the value chain between capital providers and corporate borrowers.
Machine learning credit engines are decomposing conventional underwriting workflows by ingesting real-time cash flow data from accounting software and ERP systems. Mid-market borrowers with thin credit histories gain access to facilities previously reserved for investment-grade issuers. This capability is collapsing the information advantage that relationship managers historically held through proprietary client knowledge.
The Federal Reserve's stress testing framework and SEC climate disclosure mandates are tightening capital planning and exposure reporting requirements for corporate loan portfolios. Banks must model forward-looking credit losses under adverse scenarios and quantify transition risk in carbon-intensive sectors. Energy and materials borrowers face heightened scrutiny and pricing adjustments as lenders incorporate climate scenarios into risk-weighted asset calculations.
Corporate treasury functions are unbundling traditional banking relationships and selecting providers à la carte for credit, payments, and foreign exchange. Large multinationals maintain revolving commitments with multiple institutions while centralizing operational cash management with technology-forward platforms. This pattern concentrates transaction banking revenue with API-enabled providers while fragmenting lending relationships across competing banks.
Corporate Banking Market Segmentation

Corporate banking revenue flows through distinct service architectures that determine capital intensity, fee generation potential, and relationship stickiness. Segment boundaries are blurring as API-based platforms enable modular service assembly across traditional product lines.
Service Type:
Channel mix varies sharply by service architecture—relationship managers anchor loan origination while digital platforms capture cash management and treasury execution.
- Corporate Loans:Revolving credit facilities and term loans with five-to-ten-year tenors absorb the majority of balance sheet capacity. Large corporations in the United States concentrate demand here as Basel III endgame requirements push banks toward investment-grade borrowers with shorter commitment structures.
- Treasury Management:Working capital optimization, liquidity pooling, and multi-entity cash concentration generate sticky fee income with minimal capital absorption. Real-time payment infrastructure and API connectivity are expanding addressable markets to mid-market corporates previously served through fragmented multi-bank relationships.
- Investment Banking:M&A advisory, debt and equity underwriting, and corporate restructuring services operate through specialized coverage teams.
- Cash Management:Payment processing, collections, and disbursement services integrate with ERP systems through embedded finance architectures.
Corporate loans dominate installed base. Treasury management is where expansion concentrates.
Client Type:
Cost-to-serve economics stratify sharply across client scale, determining branch density requirements and relationship manager allocation.
- Large Corporations:Investment-grade issuers with centralized treasury functions command dedicated coverage teams and bespoke facility structuring. These relationships concentrate in top-tier domestic institutions as multinationals consolidate liquidity operations.
- SMEs:Small and medium enterprises with fragmented banking relationships and thinner credit histories present higher acquisition costs. Banking-as-a-Service partnerships with enterprise software platforms are unlocking scalable origination channels previously uneconomical through traditional branch networks.
- Multinational Companies:Cross-border entities requiring multi-currency liquidity management and trade finance corridors spanning multiple jurisdictions.
- Startups:Venture-backed companies with non-traditional collateral profiles and concentrated counterparty risk.
Large corporations anchor fee generation. SMEs are climbing the fastest as embedded finance reduces acquisition friction.
Product Type:
Application-specific risk profiles determine regulatory capital treatment and pricing granularity across product lines.
- Trade Finance:Letters of credit, documentary collections, and supply chain financing instruments facilitate cross-border commerce. Citigroup and comparable institutions sustain geographic breadth in these corridors linking North American multinationals to emerging market operations.
- Commercial Mortgages:Income-producing real estate term loans with property-specific collateral and lease-based underwriting. Office and retail segments face heightened scrutiny as remote work patterns and e-commerce displacement reshape occupancy assumptions.
- Capital Markets:Debt issuance, equity underwriting, and structured products executed through trading desks and syndication platforms.
- Deposit Products:Non-interest-bearing demand deposits and interest-bearing time deposits providing stable funding bases.
Trade finance maintains cross-border dominance. Commercial mortgages face selective compression.
Industry Vertical:
Vertical-specific cash flow patterns and collateral profiles drive specialized underwriting frameworks and sector concentration limits.
- Technology:Cloud infrastructure and AI compute clusters require specialized credit facilities with non-traditional collateral profiles. Capital-intensive borrowers in this vertical are drawing new origination volumes as banks develop expertise in intangible asset-based lending.
- Energy:Oil and gas, utilities, and renewable power developers face heightened climate risk scrutiny under SEC disclosure mandates and Federal Reserve stress testing frameworks. Transition financing incentives are creating differentiated product positioning for green loan frameworks.
- Manufacturing:Working capital-intensive production operations with inventory and receivables-based financing needs.
- Healthcare:Hospital systems, pharmaceutical distributors, and medical device manufacturers with reimbursement-dependent revenue cycles.
Technology commands premium pricing. Energy is where ESG-linked differentiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows from United States-based multinational corporations into European treasury operations and Asian manufacturing supply chains define the dominant trade corridors reshaping corporate banking demand. These cross-border liquidity movements concentrate fee generation in money-center institutions with multi-jurisdictional infrastructure.
United States
Technology sector borrowers and healthcare systems drive specialized credit facility demand across cloud infrastructure and hospital network consolidation. The Federal Reserve's stress testing framework and Basel III endgame implementation tighten capital buffers for corporate loan portfolios. New York and San Francisco anchor syndicated lending and venture debt origination as multinational corporations centralize liquidity operations with domestic top-tier institutions.
Germany
Automotive supply chain financing and industrial machinery exporters sustain working capital-intensive borrowing needs across Mittelstand manufacturers. The EU Green Deal taxonomy and ECB climate risk guidance shape transition lending frameworks for carbon-intensive sectors. Frankfurt and Munich concentrate relationship-managed credit facilities as Bundesbank regulations filter Basel standards into domestic capital requirements.
China
State-owned enterprises and private technology conglomerates draw revolving credit commitments for domestic infrastructure and overseas expansion financing. The People's Bank of China dual carbon goals and MIIT industrial policy directives influence green loan origination priorities. Shanghai and Shenzhen anchor cross-border trade finance corridors linking manufacturing exporters to Belt and Road project lending.
United Kingdom
Multinational headquarters and asset management firms generate treasury management demand across multi-currency liquidity pooling structures. The Prudential Regulation Authority's implementation of Basel standards and FCA conduct rules reshape syndicated lending documentation. London's Square Mile concentrates investment-grade credit origination as post-Brexit regulatory divergence creates structuring complexity for EU-facing borrowers.
Japan
Trading houses and automotive assemblers sustain committed credit facilities for commodity procurement and overseas production networks. METI industrial policy and Bank of Japan negative rate legacy compress net interest margins on corporate loan portfolios. Tokyo and Osaka anchor relationship banking as regional banks face consolidation pressure from demographic deposit base shrinkage.
Corporate Banking Market Vendor Landscape
Listed money-center banks compete with private credit funds and direct lending platforms across balance sheet deployment and regulatory arbitrage dimensions. The vendor base stratifies into three tiers: global universal banks with integrated investment banking capabilities, regional commercial lenders with relationship depth in specific geographies, and non-bank specialists capturing leveraged finance with lighter capital constraints. Dominant competitive moves include M&A-driven scale accumulation in treasury management infrastructure and strategic partnerships with enterprise software platforms for embedded finance distribution.
Within the universal banking tier, JPMorgan Chase, Goldman Sachs, and Citigroup exemplify divergent specialization vectors. JPMorgan Chase occupies a position anchored in syndicated lending scale and global treasury infrastructure. Goldman Sachs sits within the capital markets advisory and leveraged finance specialization archetype. Citigroup represents geographic breadth in cross-border trade finance corridors. These institutions illustrate how relationship-managed credit facilities, investment banking advisory, and cash management services bundle into competing platform configurations.
| Leading Market Players |
|---|
| Wells Fargo |
| Morgan Stanley |
| JPMorgan Chase |
| PNC Financial Services |
| U.S. Bancorp |
| Bank of America |
| Goldman Sachs |
| Charles Schwab |
| Citigroup |
| Others |
Supply Flow & Price Mechanics
Federal Reserve stress testing standards gate both balance sheet deployment capacity and risk-adjusted pricing tiers simultaneously, compressing net interest margins for non-investment-grade facilities while concentrating fee generation in relationship-managed structures with embedded treasury services.
Pricing Analysis
Large corporations anchor pricing structures around relationship-intensity tiers, with investment-grade borrowers commanding tighter spreads through revolving credit facilities and syndicated term loans. Price differentiation hinges on Basel III risk-weighted asset charges and real-time payment infrastructure integration levels. Cost compression in leveraged finance is intensifying because private credit funds capture middle-market opportunities with lighter regulatory constraints. SMEs exhibit highest price sensitivity, while multinational treasury consolidations demonstrate lowest sensitivity due to bundled service economics.
Supply Chain Analysis
Port congestion across Asia-Pacific trade lanes elevates inbound logistics costs for documentary collections and supply chain financing instruments. Manufacturing inputs concentrate in China, Germany, and the United States for industrial machinery and automotive components. Raw material dependencies span semiconductor chips, rare earth minerals, and petroleum-based derivatives. Single-source vulnerability in cloud infrastructure hardware creates concentration risk for technology sector credit facilities. Distribution runs through correspondent banking networks with SWIFT messaging infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in AI-driven credit decisioning expertise and real-time treasury infrastructure engineering constrains competitive differentiation, favoring institutions with captive technology development capabilities over relationship-dependent traditional lenders.
For Market Incumbents: Secure API connectivity partnerships with enterprise software platforms to defend cash management market share against fintech disintermediation. Deepen vertical integration into embedded finance architectures through Banking-as-a-Service offerings that reduce SME acquisition costs. Prioritize investment-grade borrower concentration to optimize Basel III capital efficiency. For New Entrants and Emerging Players: Lead with specialized facilities for cloud infrastructure and AI compute clusters where collateral expertise gaps create white-space opportunities. Target mid-market technology borrowers with thin credit histories underserved by conventional underwriting workflows. Deploy machine learning credit engines with ERP system integrations as primary go-to-market mechanism. For Investors and Strategic Acquirers: Carve-out targets emerge from regional commercial lenders with deep relationship networks but legacy core infrastructure limitations. Long-term viability centers on institutions capable of modernizing payment rails while preserving sticky treasury deposit bases. Watch for inflection signals in real-time payment adoption rates among mid-market corporates.| Strategic Initiative | Industry Significance |
|---|---|
| API Platform Integration | Consolidates multi-bank relationships onto single treasury interfaces, expanding addressable SME bases. |
| AI Credit Decisioning Investment | Accelerates underwriting velocity for technology borrowers with non-traditional collateral profiles. |
| Green Loan Framework Development | Captures EU sustainable finance taxonomy incentives for transition financing in carbon-intensive sectors. |
| Embedded Finance Partnership | Unlocks scalable origination channels through enterprise software platform integrations. |
| Core Infrastructure Modernization | Replaces legacy payment systems to support real-time data and treasury connectivity demands. |
Methodological Framework
Cross-validation between primary interviews with corporate treasury officers, relationship managers, and regulatory compliance leads anchors the qualitative findings against secondary sources including Federal Reserve stress testing disclosures, SEC corporate debt filings, and Basel Committee regulatory guidance. Bottom-up triangulation with top-down macroeconomic scenario modeling ensures segmentation integrity across service types and client categories.
Sensitivity analysis frameworks test forecast robustness across alternative capital requirement implementations and interest rate trajectory scenarios. Segmentation dimensions span service architecture, client scale tier, product risk profile, and industry vertical cash flow pattern. CAGRs derive from historical balance sheet growth rates adjusted for regulatory capital absorption effects and technology sector credit demand elasticity.
Underlying assumptions cover stable implementation of Basel III endgame standards, with deviation risk concentrated in accelerated private credit substitution and faster-than-expected real-time payment infrastructure adoption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Banking
Commercial Banking Market
Banking
ATM Market
Banking
Africa Data Analytics in Banking Market
Banking
AI and Automation in Banking Market
Banking
Contactless Smart Cards in Banking Sales Market
Banking
Italy Data Analytics in Banking Market
Banking
Global Certificate of Deposit Market
Banking
Australia Data Analytics in Banking Market
Banking
E-Banking Market
Banking
Smart ATM Market
Banking
Spain Data Analytics in Banking Market
Banking
Japan Data Analytics in Banking Market
Banking
Merchant Banking Services Market
Banking
Europe Data Analytics in Banking Market
Banking
Investment Banking Market
Banking
US Data Analytics in Banking Market