
 China AI in Fintech Market | 2026-2036
China AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
China AI in Fintech Market Insights
Mobile payment infrastructure is reshaping how AI fintech solutions reach Chinese consumers. Ant Group leverages its super-app ecosystem to embed credit scoring algorithms directly into transaction workflows. Tencent anchors its competitive position through WeChat's social-commerce data streams that feed risk models. Baidu competes by applying its natural language processing heritage to intelligent customer service bots for regional banks.
China AI in Fintech denotes the application of artificial intelligence technologies—including machine learning models, natural language processing engines, and computer vision systems—to automate, augment, or transform financial services delivery within China's regulated banking and payments ecosystem. These systems process structured and unstructured data at scale to execute functions such as real-time fraud detection, dynamic credit assessment, and algorithmic portfolio rebalancing for commercial and retail financial institutions. Machine Learning dominates current deployment volumes across the service stack, while Robotic Process Automation captures expanding margin pools as insurers and payment processors seek back-office cost reduction. Natural Language Processing shows the fastest structural growth trajectory as conversational banking interfaces proliferate through super-apps and proprietary bank channels.
SAMR enforces algorithmic transparency and data governance standards that constrain black-box model deployment in consumer lending. The People's Bank of China operates the fintech regulatory sandbox, which gates market access for novel AI-driven payment and wealth management products. NMPA-aligned data security protocols extend to health-finance convergence products from players such as Ping An Good Doctor. Stakeholders must monitor how PBOC sandbox expansion criteria evolve to determine which AI service categories gain controlled release permissions.
Market Dynamics
Super-app ecosystems are compressing distribution layers for AI fintech services, forcing standalone providers to embed within Ant Group or Tencent infrastructure or face marginalization. This platform consolidation is redrawing competitive boundaries around data access rather than algorithmic superiority alone.
Growth Catalysts
- Regulatory Sandbox Expansion:The People's Bank of China's fintech regulatory sandbox accelerates controlled deployment of novel AI credit models and wealth algorithms through staged market access permissions.
- Computer Vision Integration:Facial recognition payment systems are penetrating rural banking channels, extending AI fintech reach beyond urban digital-native populations into previously underserved county-level markets.
- Dual Carbon Policy Alignment:Green finance mandates from MEE are channeling institutional capital toward AI-powered ESG scoring platforms that automate carbon footprint tracking across loan portfolios.
Market Restraints
- Algorithmic Opacity Constraints:SAMR enforcement of explainable AI standards limits black-box model deployment in consumer lending, forcing architecture redesigns that increase development cycles.
- Data Localization Requirements:NMPA-aligned data security protocols mandate domestic server infrastructure, raising compliance capital expenditure for foreign-partnered fintech ventures.
- GPU Supply Concentration:Training infrastructure for large language models depends on concentrated advanced semiconductor supply chains subject to export control friction.
Strategic Opportunities
- Greater Bay Area Convergence:Cross-border wealth management connect schemes are creating demand for AI systems that harmonize risk scoring across Hong Kong, Macau, and mainland regulatory regimes.
- Health-Finance Fusion:NMPA data protocols extending to Ping An Good Doctor-type platforms enable AI underwriting models that integrate medical records with credit assessment for specialized insurance products.
- Edge Computing Deployment:MIIT industrial internet standards are accelerating on-device inference for payment authentication, reducing latency in high-throughput transaction environments.
Industry Challenges
- Multimodal Talent Scarcity:The intersection of quantitative finance and MLOps engineering remains undersupplied, inflating compensation costs for hybrid skill profiles.
- Legacy Core Integration:Provincial rural commercial banks face extended API harmonization timelines when connecting AI front-ends to decades-old core banking systems.
- Model Drift Monitoring:Continuous validation requirements under SAMR guidelines demand dedicated operational teams that smaller fintech subsidiaries struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China AI in Fintech Market |
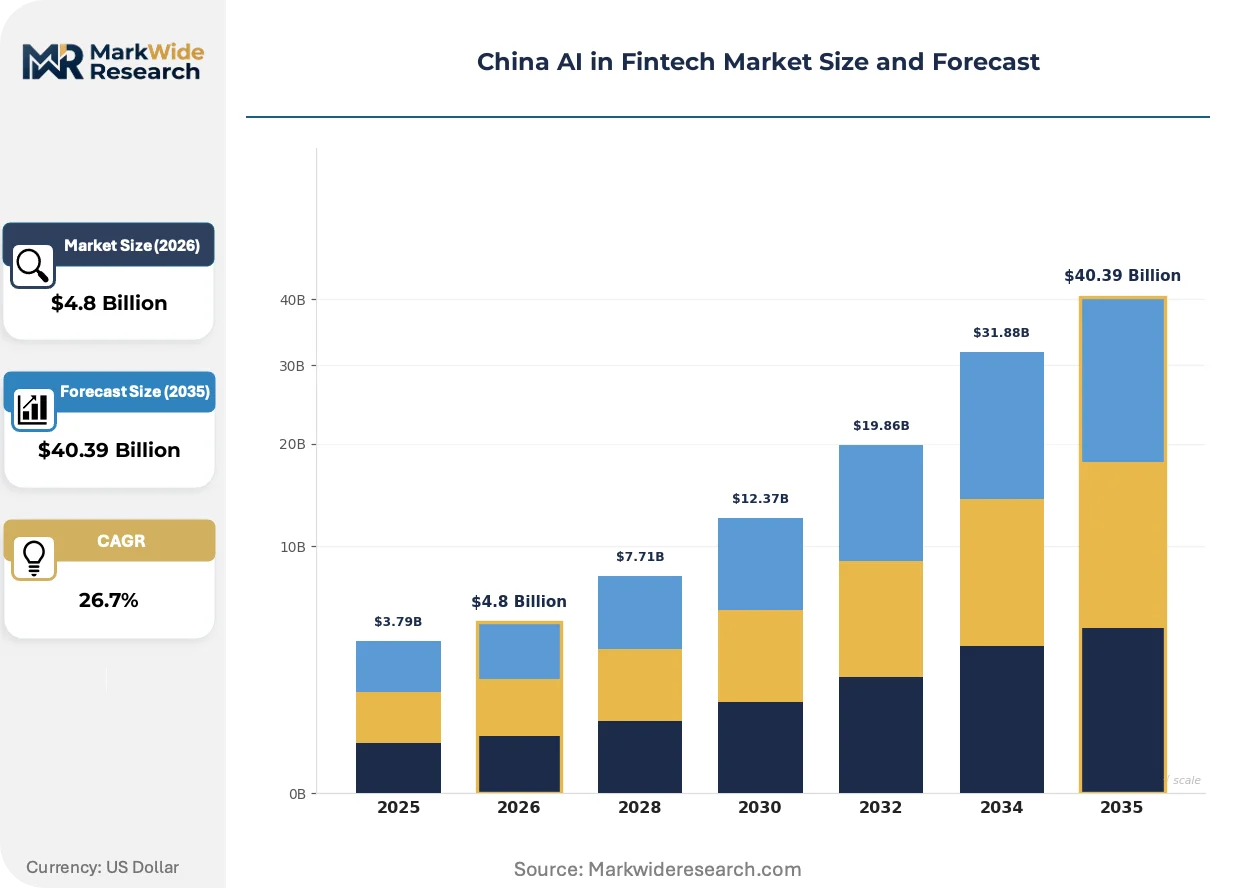
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotic Process Automation Service Type: Fraud Detection, Credit Scoring, Portfolio Management, Personalized Banking Customer Type: Retail Investors, Institutional Investors, Financial Advisors, Wealth Management End User: Banks, Insurance Companies, Investment Firms, Payment Processors |
| Companies Covered | Alibaba Group, 4Paradigm, Ant Group, Ping An Good Doctor, JD.com, Tencent, Baidu, Megvii Technology, JD Finance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China AI in Fintech Market Trends and Innovations
Federated learning architectures are reshaping how financial institutions collaborate on AI model training without centralizing sensitive customer data. This technical shift is redrawing competitive moats around privacy-preserving computation capabilities.
Large language model deployment is hybridizing rule-based compliance checks with generative document analysis. Regional banks in Jiangsu and Zhejiang are piloting these systems for automated loan document review, compressing underwriting timelines from days to hours while maintaining SAMR audit trail requirements.
The People's Bank of China is tightening algorithmic filing requirements for credit scoring models, mandating pre-deployment bias testing and ongoing performance reporting. Consumer lending platforms are responding by establishing dedicated model risk management functions, with Shanghai-based institutions setting the compliance benchmark for national rollout.
Wealth management clients are migrating toward embedded advisory experiences within super-app payment workflows rather than standalone robo-advisor platforms. This behavioral pivot is most pronounced among users under 35 in tier-one cities, where Ant Fortune and Tencent Wealth Management are capturing advisory engagement through transaction-triggered micro-investing prompts.
China AI in Fintech Market Segmentation
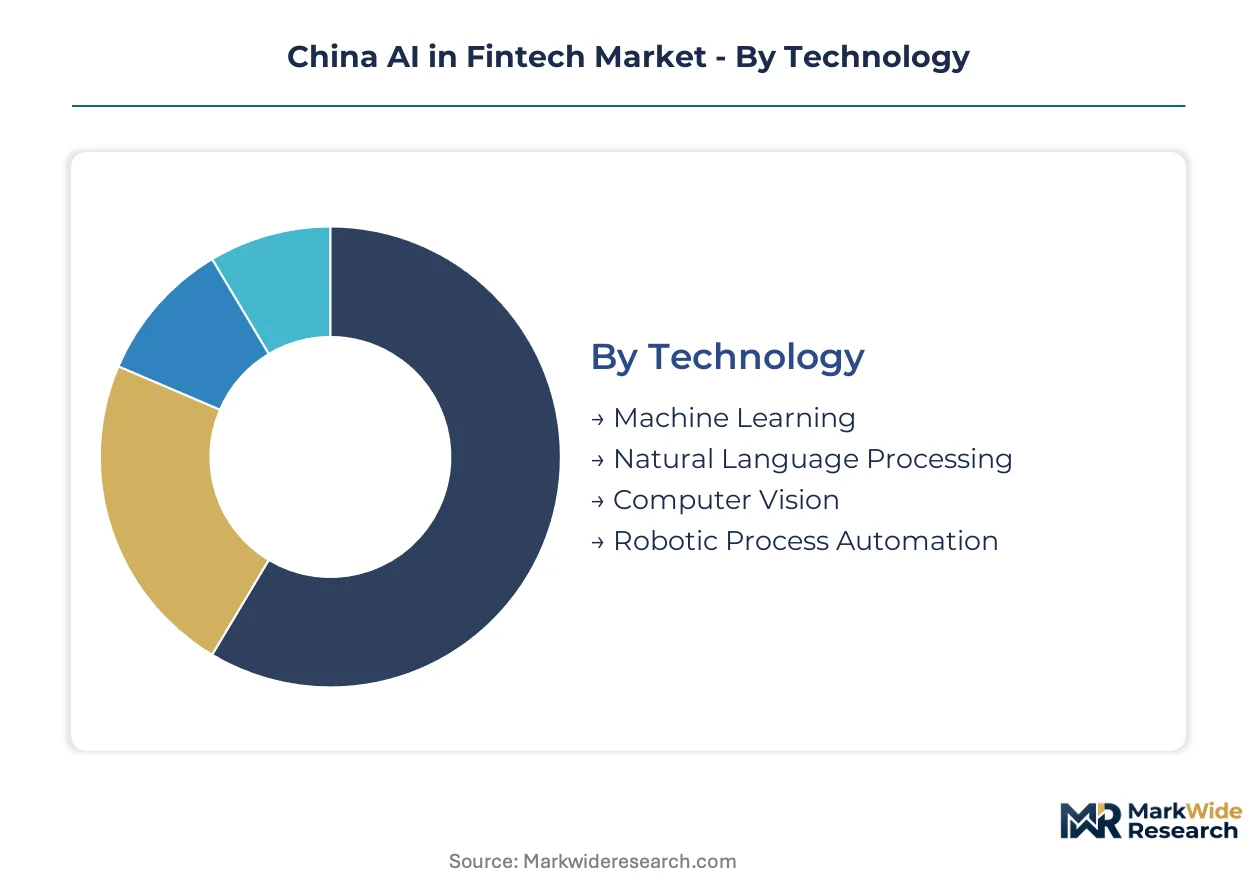
Technology heterogeneity across China's AI fintech stack demands granular segmentation to map deployment velocity, regulatory exposure, and margin capture potential. Each category reveals distinct competitive dynamics between algorithmic sophistication and operational scale.
Technology:
Machine Learning systems refresh model weights quarterly, while Robotic Process Automation deployments operate on multi-year refresh cycles. Natural Language Processing engines iterate fastest as conversational interfaces evolve.
- Machine Learning:Supervised and unsupervised learning architectures power real-time transaction monitoring and dynamic pricing engines. Demand concentrates in Shanghai's Lujiazui district where major banks operate model development centers, constrained by SAMR explainability mandates that extend validation timelines.
- Natural Language Processing:Transformer-based models process Mandarin financial documents and power conversational banking interfaces across super-app ecosystems. Jiangsu and Zhejiang regional banks pilot automated loan document review, compressing underwriting cycles while maintaining audit trail compliance.
- Computer Vision:Facial recognition authentication systems extend payment infrastructure into rural county-level markets previously excluded from digital finance.
- Robotic Process Automation:Rule-based workflow automation targets back-office cost reduction at provincial insurers and payment processors with legacy core systems.
Machine Learning dominates installed base. Natural Language Processing is where expansion concentrates.
Service Type:
Fraud detection solutions require continuous retraining against evolving attack vectors, while portfolio management algorithms shift on quarterly rebalancing schedules. Credit scoring models face the stiffest regulatory filing requirements.
- Fraud Detection:Real-time anomaly detection networks monitor transaction streams across payment rails, flagging synthetic identity fraud and merchant collusion. Ant Group and Tencent deploy these systems at billion-transaction scale, with PBOC sandbox protocols governing model updates.
- Credit Scoring:Alternative data algorithms incorporate mobile payment history and social-commerce behavior into underwriting decisions. SAMR pre-deployment bias testing and ongoing performance reporting requirements force architecture redesigns that favor established platform operators over standalone providers.
- Portfolio Management:Algorithmic rebalancing engines serve mass-affluent clients through embedded super-app experiences rather than standalone robo-advisors.
- Personalized Banking:Recommendation engines trigger micro-investing prompts based on transaction context, capturing advisory engagement among users under 35 in tier-one cities.
Fraud Detection anchors current revenue. Credit Scoring faces the steepest regulatory compliance gradient.
Customer Type:
Retail investor onboarding cycles run days, while institutional client acquisition extends across quarters. Financial advisor tools refresh annually as product shelves evolve.
- Retail Investors:Mass-market clients access AI-driven wealth management through transaction-triggered prompts within payment workflows. Ant Fortune and Tencent Wealth Management capture advisory engagement by embedding micro-investing nudges at point-of-sale moments.
- Institutional Investors:Asset managers deploy natural language processing for regulatory filing analysis and ESG sentiment scoring aligned with MEE dual carbon policy mandates.
- Financial Advisors:AI-assisted client segmentation tools prioritize outreach based on predicted life-event probability.
- Wealth Management:Family office platforms integrate cross-border portfolio tracking for Greater Bay Area clients navigating Hong Kong-mainland regulatory harmonization.
Retail Investors represent the deepest addressable pool. Institutional Investors command premium pricing for compliance-integrated solutions.
End User:
Payment processors iterate authentication systems fastest, while insurance companies maintain decade-long policy system horizons. Investment firms occupy the middle velocity tier.
- Banks:State-owned commercial banks and joint-stock institutions deploy machine learning for credit decisioning and computer vision for rural branch authentication. Legacy core integration timelines at provincial rural commercial banks delay AI front-end deployment.
- Insurance Companies:Ping An and peers apply AI to health-finance convergence products, integrating medical records from Ping An Good Doctor platforms into specialized underwriting models under NMPA data protocols.
- Investment Firms:Brokerages deploy algorithmic execution and sentiment analysis for retail-facing research distribution.
- Payment Processors:Facial recognition payment systems penetrate county-level markets, extending AI fintech reach beyond urban digital-native populations.
Banks absorb the largest absolute technology spend. Payment Processors are gaining share fastest in transaction-volume terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai commands premium pricing for AI fintech talent and infrastructure, while provincial markets in western China absorb cost-adjusted deployments. This asymmetry concentrates model development in coastal financial centers and operational scaling in interior provinces.
Yangtze River Delta
Shanghai's Lujiazui financial district hosts the densest concentration of bank AI development centers and regulatory sandbox participants. SAMR algorithmic transparency mandates originate here and propagate nationally as compliance benchmarks. Ant Group anchors super-app ecosystem innovation in Hangzhou, feeding transaction data streams into credit scoring models deployed across the delta.
Pearl River Delta
Shenzhen's hardware manufacturing base supplies edge computing infrastructure for facial recognition payment terminals penetrating county-level markets. Tencent's WeChat ecosystem generates social-commerce data streams that power risk assessment algorithms for embedded wealth management products. Guangzhou's provincial banks pilot federated learning architectures for cross-institutional model training without centralizing customer data.
Beijing-Tianjin-Hebei
Capital-region regulators including SAMR and PBOC draft national AI fintech standards that constrain black-box model deployment in consumer lending. Baidu leverages natural language processing heritage to supply intelligent customer service bots for regional banks undergoing digital transformation. Zhongguancun technology corridor concentrates venture funding for AI infrastructure startups serving financial institutions.
Sichuan-Chongqing
Western China's largest metropolitan economy supports AI fintech deployment for rural commercial banks serving agricultural supply chain finance. Chongqing's municipal government operates localized regulatory sandbox iterations for wealth management products targeting mass-affluent households. Chengdu's software parks host delivery centers for back-office robotic process automation serving insurers nationwide.
Shandong Peninsula
Qingdao's port finance ecosystem generates trade finance data streams for AI-powered supply chain risk monitoring. Provincial rural commercial banks in Jinan face extended legacy core integration timelines when connecting AI front-ends to decades-old systems. Local government guidance funds channel investment toward computer vision authentication systems for branch network modernization.
China AI in Fintech Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying algorithms and infrastructure. Super-app ecosystems compress distribution layers, forcing standalone providers to embed within dominant platforms or face marginalization. Three archetypes prevail: ecosystem orchestrators with data network effects, algorithm specialists licensing models to institutions, and infrastructure vendors supplying training compute. Competitive moves concentrate on strategic partnerships for data access and vertical integration into edge computing hardware.
Among ecosystem orchestrators, Ant Group and Tencent exemplify platform consolidation dynamics that redraw competitive boundaries around data access rather than algorithmic superiority alone. Baidu occupies a position within the specialist tier, leveraging heritage capabilities in natural language processing to serve regional banks.
| Leading Market Players |
|---|
| Alibaba Group |
| 4Paradigm |
| Ant Group |
| Ping An Good Doctor |
| JD.com |
| Tencent |
| Baidu |
| Megvii Technology |
| JD Finance |
| Others |
Pricing and Supply Chain Analysis
Shanghai's Lujiazui AI development cluster concentrates model training infrastructure and specialized engineering talent, creating asymmetric pricing power for algorithmic solutions deployed downstream to provincial banks and payment processors. This geographic concentration of compute capacity and regulatory sandbox access allows tier-one institutions to capture premium pricing while interior markets absorb cost-adjusted deployments.
Pricing Analysis
The customization-premium spread in China AI fintech separates configured-to-order credit scoring models from standardized fraud detection APIs. Three-tier pricing structure across premium, standard, and economy levels reflects SAMR certification depth and explainability audit trail completeness. Cost compression in the standard tier is intensifying because Ant Group and Tencent bundle algorithmic services into super-app transaction fees. Tier-two regional banks exhibit highest price sensitivity; state-owned commercial banks prioritize compliance integration over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for AI training hardware rests on Taiwan Semiconductor Manufacturing and domestic foundries in Shanghai and Beijing. Advanced GPU supply draws from concentrated semiconductor fabrication in Taiwan, South Korea, and the United States. Single-source vulnerability around NVIDIA export-controlled chips creates procurement bottlenecks for large language model training. Distribution runs through cloud service provider marketplaces and direct enterprise licensing to financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China AI in fintech operates as a service-attach opportunity where recurring model retraining and compliance audit subscriptions expand faster than initial algorithm deployment fees. The shift from perpetual licensing to consumption-based pricing for inference workloads deepens revenue durability.
For Market Incumbents: Insulate core data network effects by embedding federated learning capabilities that prevent customer defection to standalone algorithm vendors. Ant Group and Tencent should deepen upstream control over edge computing hardware for facial recognition terminals. SAMR algorithmic filing requirements favor established players with dedicated model risk management functions. For New Entrants and Emerging Players: Western China's county-level rural commercial banks present the most penetrable geography for computer vision authentication systems. These institutions face extended legacy core integration timelines that create appetite for modular AI front-ends. Target agricultural supply chain finance in Sichuan-Chongqing with lightweight credit scoring APIs that bypass super-app dependency. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory capture play because PBOC sandbox expansion criteria determine which AI service categories gain controlled release permissions. Acquisition targets should exhibit dual capabilities in MLOps engineering and quantitative finance talent pools. Monitor SAMR pre-deployment bias testing enforcement intensity as the inflection signal for compliance-integrated solution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Platform Launch | Enables Ping An and regional banks to train models without centralizing NMPA-regulated customer data. |
| Edge Computing Hardware Partnership | Shenzhen manufacturers supply MIIT-compliant facial recognition terminals for rural county-level banking channels. |
| Regulatory Sandbox Expansion | PBOC controlled release permissions gate market access for novel AI wealth management algorithms. |
| Natural Language Processing Acquisition | Baidu heritage capabilities in Mandarin document analysis address Jiangsu-Zhejiang bank automation demand. |
| Health-Finance Data Integration | Ping An Good Doctor medical records feed NMPA-aligned underwriting models for specialized insurance products. |
Research Methodology
A spread of perspectives from chief technology officers at state-owned banks, PBOC regulatory sandbox administrators, MLOps engineering directors, and super-app platform architects converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SAMR algorithmic filing databases, MIIT industrial internet standards documentation, and PBOC fintech sandbox participant disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Demand-supply-balance framing anchored the quantitative approach, with deployment velocity modeled by technology segment, service type, and customer tier throughout the forecast period. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory inflection points. Key inputs included GPU supply chain constraints, SAMR explainability mandate compliance costs, and super-app ecosystem penetration rates by provincial market.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud hyperscalers or semiconductor nationalization initiatives would shift outcomes beyond projected ranges. Quarterly review of PBOC sandbox expansion criteria, SAMR enforcement intensity, and edge computing hardware deployment metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Spain AI in Fintech Market
FinTech
North America AI in Fintech Market
FinTech
Indonesia Financial Technology Services Market
FinTech
Decentralized Finance Technology Market
FinTech
Spend Management Platform Market
FinTech
Smart Lending Platform Market
FinTech
Global Fundraising Software Market
FinTech
Germany AI in Fintech Market
FinTech
IoT for Finance Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Transaction Monitoring Software Market
FinTech
Singapore AI in Fintech Market
FinTech
Generative AI in Fintech Market
FinTech
Latin America Fintech Market