
 Fintech Crisis Management Market | 2026-2036
Fintech Crisis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Fintech Crisis Management Market Analysis
Asset-light subscription pricing for crisis simulation platforms is tilting competitive dynamics toward firms that can scale without heavy infrastructure commitments. Ant Financial Services Group leverages its cloud-native architecture to deliver resilience tools across payment networks. PayPal anchors its position through embedded fraud-recovery workflows within existing merchant relationships. TransUnion LLC differentiates via proprietary credit-risk signals that feed real-time crisis dashboards.
Fintech crisis management encompasses the frameworks, software systems, and operational protocols that financial technology firms deploy to detect, contain, and recover from operational disruptions, cyber incidents, or liquidity shocks, typically integrating automated alerting with pre-configured response playbooks and cross-functional communication channels. Its primary commercial purpose is to minimize downtime, preserve customer trust, and satisfy prudential supervisors who now mandate demonstrable recovery capabilities. Technology integration services command premium pricing as banks seek to stitch disparate vendor tools into coherent response architectures. Cloud-based deployment is expanding fastest among mid-tier fintechs that lack capital for on-premises infrastructure. Regulatory compliance solutions within the solution layer attract sustained investment as supervisory expectations harden.
The EU Digital Operational Resilience Act and the UK Financial Conduct Authority's operational resilience framework are tightening minimum standards for incident response, recovery testing, and third-party risk management across European fintechs. The US Federal Reserve and OCC guidance on operational risk governance similarly shapes product roadmaps for domestic vendors serving federally chartered institutions. Stakeholders must weigh whether to build proprietary crisis management stacks or embed third-party platforms that carry their own concentration risk.
Market Dynamics
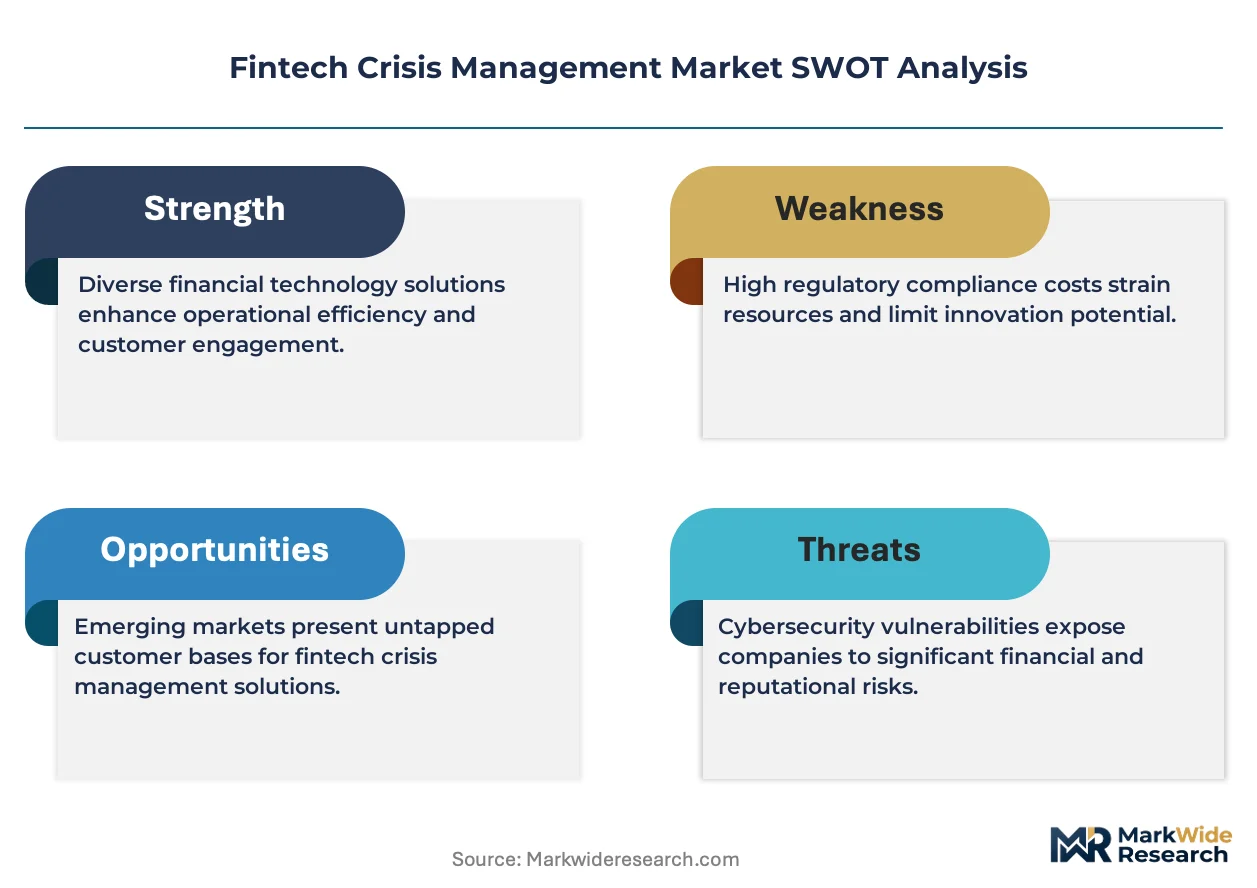
Cloud-native architecture is collapsing the traditional infrastructure barrier that once separated tier-one banks from agile fintech challengers, forcing incumbent vendors to reprice their crisis simulation platforms or lose mid-market share entirely.
Growth Catalysts
- EU Digital Operational Resilience Act:The regulation mandates recovery testing and third-party risk management, compelling European fintechs to procure certified crisis management stacks or face supervisory penalties.
- Payment network complexity:Real-time gross settlement systems and instant payment rails multiply failure points, driving demand for automated containment protocols that isolate cascading disruptions.
- London regulatory cluster:UK Financial Conduct Authority scrutiny on operational continuity concentrates procurement decisions among Square Mile institutions seeking demonstrable resilience capabilities.
Market Restraints
- Specialized talent scarcity:Crisis management engineering requires hybrid skills spanning cybersecurity, financial operations, and regulatory compliance, with compensation inflation exceeding 15% annually in key hubs.
- Vendor concentration risk:Cloud infrastructure dependence on three hyperscalers creates systemic vulnerability that supervisors now flag as a material concentration requiring mitigation.
- Integration legacy drag:Core banking systems built on COBOL and mainframe architectures resist API-based crisis response orchestration, extending deployment timelines by 18-24 months.
Strategic Opportunities
- Southeast Asia digital banking licenses:Singapore, Indonesia, and Philippines regulators are greenlighting neobanks without physical branches, creating first-mover advantage for cloud-native crisis platform vendors.
- Embedded resilience APIs:Banking-as-a-Service providers can white-label crisis detection modules, extending reach into embedded finance ecosystems without direct enterprise sales cycles.
- Climate stress testing convergence:ECB and Bank of England mandates for physical risk scenario modeling create cross-sell opportunity for vendors with catastrophe modeling capabilities.
Industry Challenges
- Cross-border data sovereignty:Fragmented cloud localization requirements across EU member states, India, and China complicate unified crisis response architectures for multinational fintechs.
- Tabletop fatigue:Regulatory-mandated simulation frequency is producing checkbox compliance behavior rather than genuine operational preparedness, degrading platform engagement metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fintech Crisis Management Market |
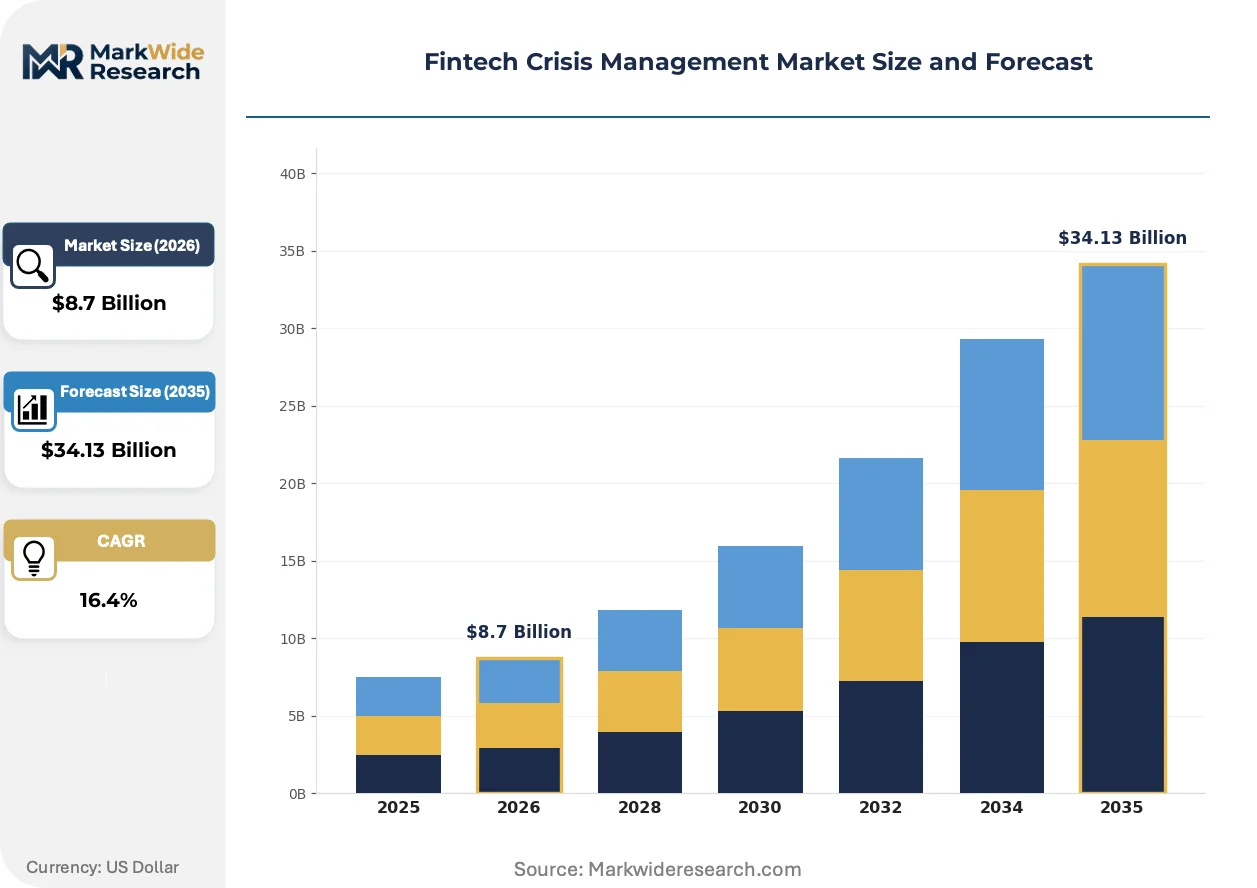
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Risk Assessment, Technology Integration, Training Solution: Fraud Detection, Cybersecurity, Regulatory Compliance, Data Analytics Customer Type: SMEs, Large Enterprises, Startups, Government Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Gravity Payments, Ant Financial Services Group, PayPal, Carta Inc., Klarna Bank AB, Braintree, TransUnion LLC, Avant LLC, Verifi Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fintech Crisis Management Market Emerging Trajectories
Generative AI is rewriting incident response playbooks by compressing decision cycles from hours to minutes, while supervisory technology mandates harden minimum viable capabilities across jurisdictions.
Immutable audit logging on distributed ledger infrastructure is collapsing the evidentiary gap between incident occurrence and regulatory notification. Tier-two banks and payment processors are adopting these architectures fastest, bypassing traditional forensic reconstruction delays. The structural consequence is collapsing remediation timelines that previously justified premium consulting retainers.
UK Financial Conduct Authority's operational resilience framework now mandates maximum tolerable downtime thresholds for critical business services, with enforcement commencing for the largest firms. The industrial consequence is forcing vendors to engineer automatic failover capabilities rather than manual escalation protocols. Asset managers and pension administrators face the steepest compliance curves, driving consolidation toward platforms with pre-certified control libraries.
Subscription pricing for crisis simulation is displacing perpetual license models, compressing customer acquisition costs while extending revenue visibility. Mid-tier fintechs in Germany and France are leading this transition, preferring consumption-based access to dedicated infrastructure. The Netherlands and Nordic markets show similar momentum, with procurement committees prioritizing opex flexibility over balance-sheet asset ownership.
Fintech Crisis Management Market Segmentation
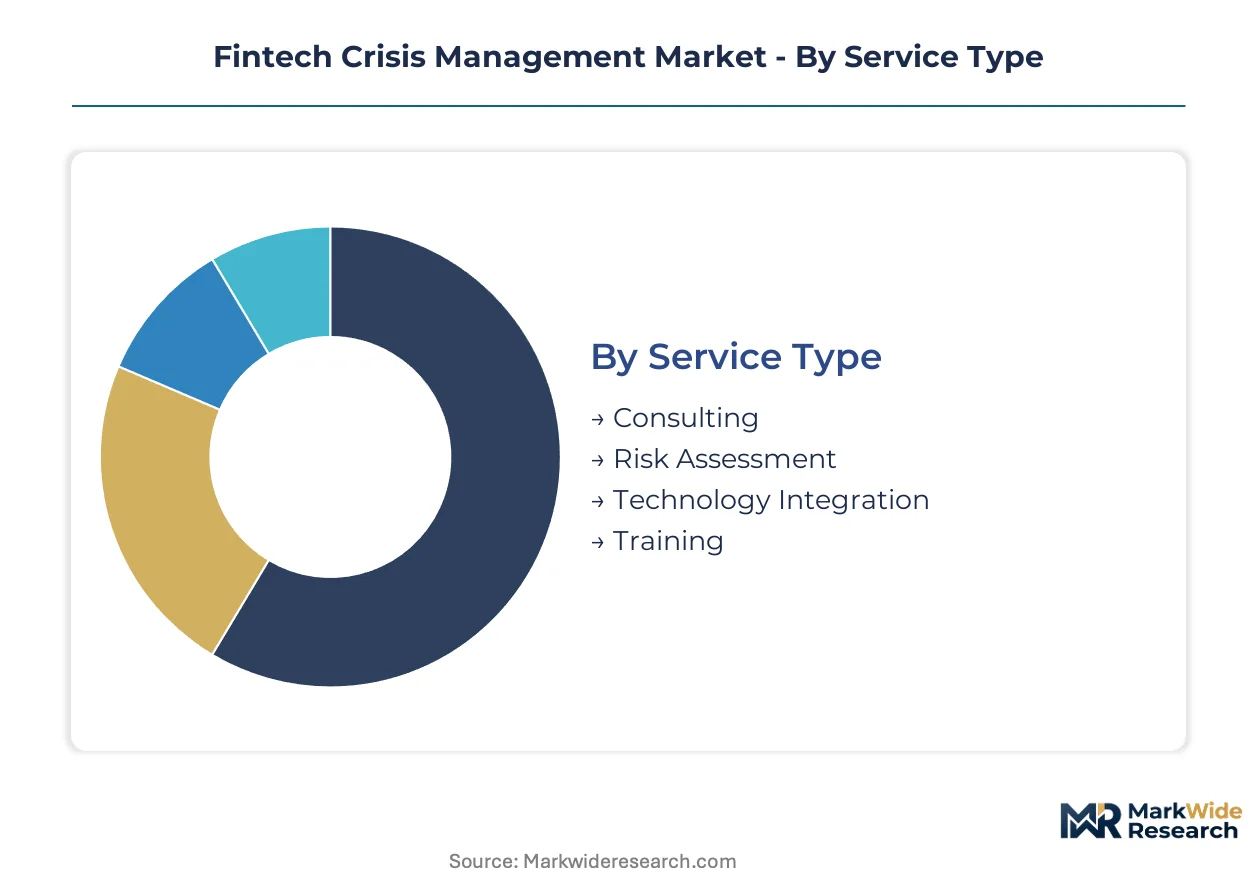
Crisis management procurement cycles vary dramatically across fintech segments, with deployment infrastructure refreshing every 18-24 months while consulting engagements stretch across multi-year regulatory windows. Understanding these velocity differences shapes vendor resource allocation and partnership structuring.
Service Type:
Technology Integration contracts turn over fastest as cloud-native platforms displace legacy stitching projects, while Training engagements exhibit the longest renewal cycles tied to supervisory examination calendars.
- Consulting:Strategic advisory spanning business continuity planning, regulatory gap remediation, and merger integration for distressed fintechs. UK and German banking supervisors now mandate external consultant attestation for operational resilience self-assessments, concentrating demand among Square Mile and Frankfurt institutions facing compliance deadlines.
- Risk Assessment:Quantitative stress testing and scenario modeling services that map cascading failure points across payment networks and lending platforms. Singapore and Indonesia digital banking licensees are procuring these services fastest as they build resilience frameworks from greenfield operations.
- Technology Integration:Vendor-agnostic architecture design linking disparate crisis detection, communication, and recovery tools into unified response stacks.
- Training:Immersive simulation programs and tabletop exercises that validate response playbooks against regulatory benchmarks.
Consulting dominates installed base. Technology Integration is where expansion concentrates.
Solution:
Margin structures diverge sharply across this category, with Fraud Detection commanding premium pricing for real-time transaction monitoring while Data Analytics competes on volume-driven subscription tiers.
- Fraud Detection:Real-time transaction scoring and behavioral biometrics that isolate account takeover and synthetic identity attacks before funds move. European instant payment rails and India's UPI network are driving procurement as settlement finality eliminates recall options.
- Cybersecurity:Endpoint detection, threat intelligence, and automated containment protocols for ransomware and supply chain compromises. US federally chartered institutions under OCC supervision are consolidating spending here following updated operational risk guidance.
- Regulatory Compliance:Automated control mapping, evidence collection, and supervisory reporting aligned to jurisdiction-specific mandates.
- Data Analytics:Predictive models that correlate operational signals with liquidity stress indicators and customer churn risk.
Cybersecurity captures the largest share of current spending. Fraud Detection is climbing the fastest as real-time payment volumes accelerate.
Customer Type:
Application intensity varies by institutional complexity, with Large Enterprises demanding end-to-end platform orchestration while Startups prioritize modular, API-first components.
- SMEs:Mid-tier payment processors and regional lenders procuring standardized crisis response templates with limited customization. France and Netherlands procurement committees are driving subscription model adoption, favoring opex flexibility over capital deployment.
- Large Enterprises:Global banks and payment networks requiring bespoke resilience architectures spanning multiple jurisdictions and regulatory regimes. UK Financial Conduct Authority maximum tolerable downtime mandates are forcing automatic failover investments among the largest Square Mile institutions.
- Startups:Neobanks and embedded finance providers seeking cloud-native, plug-and-play resilience modules.
- Government Agencies:Central banks and financial market infrastructures procuring systemic risk monitoring and cross-firm coordination platforms.
Large Enterprises dominate installed base. SMEs are gaining share fastest as subscription pricing democratizes access.
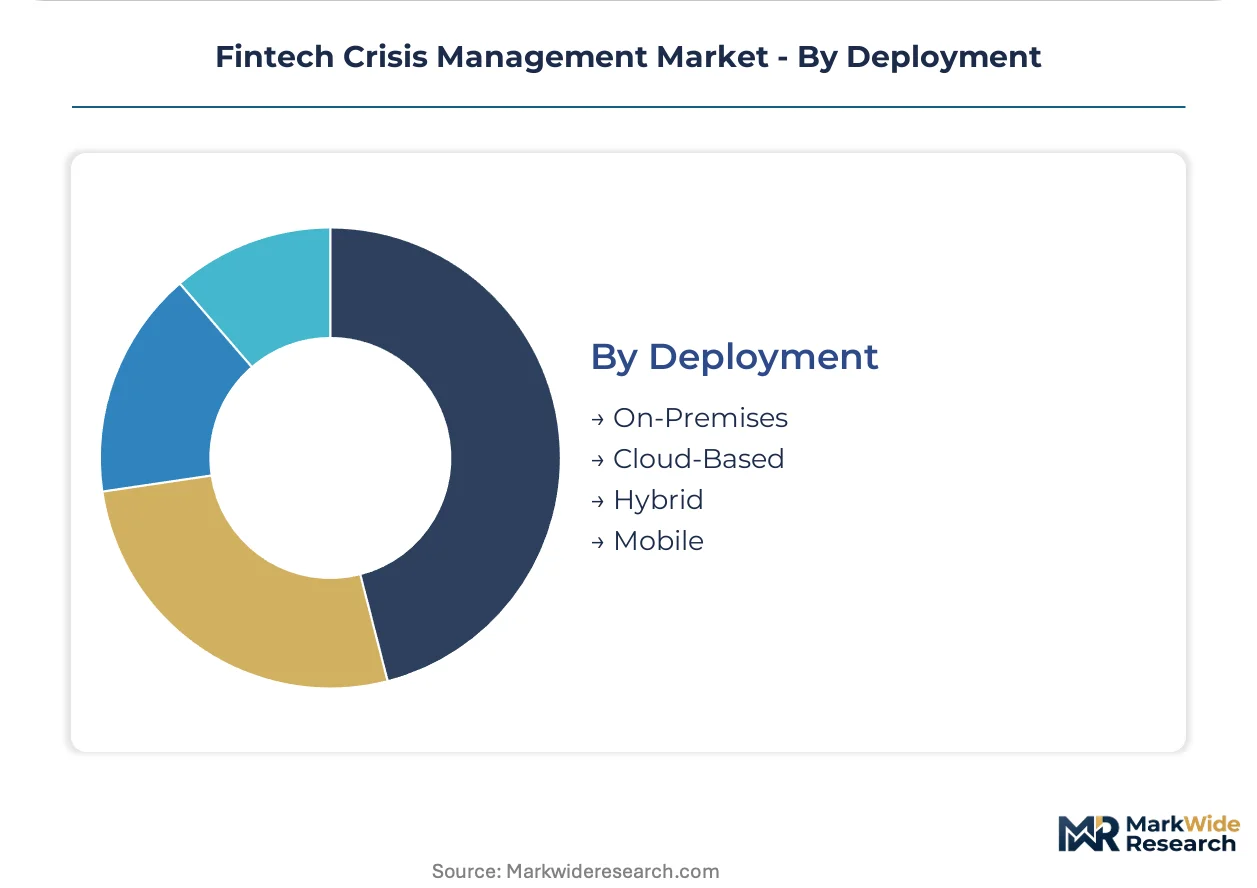
Deployment:
Supply concentration favors hyperscaler infrastructure, though data sovereignty requirements are fragmenting architecture decisions across national boundaries.
- On-Premises:Dedicated hardware installations within client data centers, typically reserved for core banking systems with latency-sensitive transaction processing. COBOL and mainframe legacy systems in US and European tier-one banks resist API-based orchestration, extending deployment timelines substantially.
- Cloud-Based:Fully managed SaaS platforms leveraging distributed compute for elastic crisis simulation capacity and global redundancy. Mid-tier German and French fintechs are leading this transition, bypassing capital constraints that previously favored perpetual license models.
- Hybrid:Split architectures retaining sensitive control functions on-premises while pushing analytics and simulation workloads to cloud environments.
- Mobile:Executive-facing incident response applications enabling remote decision-making and stakeholder communication.
On-Premises retains the deepest installed base. Cloud-Based is expanding most quickly among capital-constrained challengers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Banking supervisors in London, Frankfurt, and Singapore are driving procurement concentration among fintechs facing mandatory operational resilience deadlines. Cloud-native platform vendors prioritize these regulatory clusters over dispersed geographic expansion.
United Kingdom
Square Mile institutions dominate European crisis management spending as the UK Financial Conduct Authority enforces maximum tolerable downtime mandates. The operational resilience framework requires automatic failover capabilities for critical payment services by March 2025. London-based neobanks and legacy clearing houses are consolidating vendor relationships toward pre-certified control libraries.
Germany
Frankfurt's banking density creates concentrated demand for EU Digital Operational Resilience Act compliance solutions. BaFin supervision of instant payment rails drives procurement of real-time containment protocols. Mid-tier fintechs in Berlin and Munich favor subscription-priced simulation platforms over capital-intensive perpetual licenses.
United States
Federally chartered institutions under OCC and Federal Reserve guidance anchor North American demand for cyber incident response automation. New York and San Francisco payment processors face updated operational risk governance requirements. Community banks across the Midwest resist API-based orchestration due to core system legacy constraints.
Singapore
Digital banking licensees without physical branches create greenfield demand for cloud-native resilience architectures. The Monetary Authority of Singapore mandates recovery testing for newly authorized neobanks before operational launch. Fintech clusters in the Central Business District prioritize embedded resilience APIs over bespoke enterprise deployments.
India
UPI network expansion and real-time retail payment growth multiply failure points requiring automated containment. The Reserve Bank of India's operational risk guidelines shape vendor product roadmaps for domestic payment processors. Mumbai and Bangalore fintechs lead cloud adoption among capital-constrained challengers seeking opex flexibility.
Fintech Crisis Management Market Vendor Landscape
Channel-controlling players compete with product-specialist players for crisis management procurement decisions across tier-one banks and mid-market fintechs. The vendor base organizes around three strategic archetypes: cloud-native platform providers, embedded finance infrastructure specialists, and credit-risk data aggregators. Consolidation pressure intensifies as hyperscaler partnerships become table stakes for enterprise credibility. M&A activity targets boutique consulting firms with regulatory attestation credentials.
Within the cloud-native platform tier, Ant Financial Services Group and PayPal occupy positions exemplifying divergent strategic bets on infrastructure ownership versus merchant relationship embedding. TransUnion LLC anchors the data-centric archetype, leveraging proprietary signals for real-time crisis dashboarding. Gravity Payments represents the specialist end, serving payment processors with tailored resilience modules rather than horizontal platform expansion.
| Leading Market Players |
|---|
| Gravity Payments |
| Ant Financial Services Group |
| PayPal |
| Carta Inc. |
| Klarna Bank AB |
| Braintree |
| TransUnion LLC |
| Avant LLC |
| Verifi Inc. |
| Others |
Supply Flow & Price Mechanics
London's Square Mile fintech cluster concentrates cloud-native platform capacity, translating infrastructure density into pricing leverage over mid-tier challengers seeking EU Digital Operational Resilience Act compliance without capital-intensive perpetual licenses.
Pricing Analysis
Cost-plus contracts with inflation indexation to cloud infrastructure spot rates dominate enterprise procurement, though subscription SaaS tiers are displacing perpetual licenses fastest among German and French mid-tier fintechs. Price differentiation hinges on certification grade against UK Financial Conduct Authority mandates and customization depth for legacy core banking integration. Cost compression in the mid-market intensifies as hyperscaler partnerships become table stakes, eroding vendor margins. Startups exhibit highest price sensitivity, while tier-one banks absorbing regulatory penalties prioritize control library completeness over unit cost.
Supply Chain Analysis
Upstream compute capacity feeds from Ireland, Netherlands, and Singapore data center clusters, with crisis simulation workloads drawing from GPU-intensive training pipelines and distributed ledger infrastructure nodes. Raw material dependencies span semiconductor substrates for edge detection hardware, optical fiber for low-latency failover networks, and specialized cybersecurity talent pools concentrated in London, Frankfurt, and Bangalore. Single-source vulnerability in cloud infrastructure on three hyperscalers creates systemic concentration flagged by EU supervisors. Distribution runs through direct enterprise sales for large banks and white-label API embedding for Banking-as-a-Service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid crisis engineering talent spanning cybersecurity, financial operations, and regulatory compliance remains acutely scarce, with compensation inflation exceeding annual benchmarks and constraining vendor scale velocity.
For Market Incumbents: Entrench position through backward integration into proprietary control libraries pre-certified against UK Financial Conduct Authority maximum tolerable downtime mandates, while acquiring boutique consulting firms with regulatory attestation credentials to defend against cloud-native challengers eroding mid-market share via subscription pricing. For New Entrants and Emerging Players: Build out embedded resilience API offerings targeting Southeast Asian digital banking licensees in Singapore, Indonesia, and Philippines, where greenfield operations lack legacy drag and procurement committees prioritize opex flexibility over enterprise sales cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from tier-one banks spinning off internal crisis management stacks into standalone SaaS entities; long-term viability rests on recurring revenue depth from regulatory compliance mandates rather than discretionary consulting engagements. Watch for supervisory technology hardening minimum viable capabilities as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies disparate crisis detection and recovery tools into coherent response architectures for tier-one banks. |
| Acquisition of Specialist Firm | Boutique consultants with UK Financial Conduct Authority attestation credentials command premium valuations. |
| Geographic Expansion | Southeast Asian digital banking licenses create first-mover advantage for cloud-native resilience vendors. |
| Strategic Partnership | Hyperscaler alliances become table stakes for enterprise credibility in crisis simulation procurement. |
| Product Launch | Automatic failover capabilities displace manual escalation protocols under EU Digital Operational Resilience Act deadlines. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with chief risk officers, operational resilience directors, regulatory compliance leads, and cloud infrastructure procurement officers at tier-one banks and mid-tier fintechs; and secondary validation against SEC 10-K filings, UK Financial Conduct Authority supervisory disclosures, EU regulatory impact assessments, and hyperscaler capex announcements. Bottom-up deployment sizing triangulated against top-down market aggregation.
Forecast inputs considered service type, solution layer, customer tier, and deployment model segmentation across the analysis window, with CAGRs derived from regression against historical procurement velocity and regulatory deadline clustering. Industry-specific inputs included EU Digital Operational Resilience Act implementation timelines and instant payment rail expansion curves.
Stress conditions across cloud infrastructure pricing volatility, talent compensation inflation, and cross-border data sovereignty fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding supervisory enforcement consistency and legacy system API accessibility. Cross-checking against central bank operational risk survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
United States Fintech Market
FinTech
Finance Cloud Market
FinTech
Netherlands AI in Fintech Market
FinTech
Europe AI in Fintech Market
FinTech
France AI in Fintech Market
FinTech
Fintech Credit Management Blockchain Market
FinTech
North America Fintech Market
FinTech
China AI in Fintech Market
FinTech
France BNPL Market
FinTech
Germany Fintech Market
FinTech
North America Fintech Cloud Market
FinTech
Cyber Security in Fintech Market
FinTech
Singapore Fintech Market
FinTech
Financial Forecasting Software Market
FinTech
Russia AI in Fintech Market
FinTech
Financial Management Software Market