
 Asia-Pacific Fintech Cloud Market | 2026-2036
Asia-Pacific Fintech Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Fintech Cloud Market Analytics
The EU AI Act is restructuring cross-border data governance expectations for financial institutions operating cloud infrastructure, compelling providers to demonstrate algorithmic transparency and data residency compliance. Alibaba Cloud leverages sovereign cloud architectures to anchor its position across mainland China and ASEAN markets. Tencent sustains competitive density through embedded finance integrations that tie cloud services to super-app ecosystems. Huawei Cloud differentiates via dedicated financial industry zones that satisfy localized processing mandates.
Asia-Pacific fintech cloud denotes the delivery of computing, storage, and analytical resources through distributed server networks to financial technology operators, typically featuring sub-50 millisecond latency thresholds and multi-availability-zone redundancy for payment clearing workloads. Its commercial purpose centers on enabling real-time transaction processing, elastic scaling during peak settlement windows, and API-driven interoperability between legacy core banking systems and digital-native platforms. Public cloud deployment captures the dominant revenue share as tier-1 banks migrate non-core workloads off-premises, while hybrid cloud architectures are expanding fastest among mid-market payment processors seeking burst capacity without full infrastructure surrender. Software as a Service margins concentrate in regulatory reporting and anti-money-laundering tooling where recurring compliance obligations lock in subscription durability.
India's RBI operationalizes fintech cloud governance through data localization directives and digital lending guidelines that mandate on-shore storage of customer financial records. China's SAMR and MEE enforce dual carbon accountability on hyperscale data centers, redirecting facility investment toward renewable-powered western provinces. Australia's TGA and prudential standards from the country's financial regulator impose operational resilience testing that shapes cloud service level agreements. Stakeholders must monitor evolving sovereign AI regulations and carbon disclosure thresholds as these will determine which infrastructure configurations retain market access across the region.
Market Dynamics
Regulatory fragmentation across Asia-Pacific jurisdictions is forcing cloud providers to architect multi-sovereign data residency frameworks, while India's UPI scale and China's carbon mandates simultaneously pull infrastructure investment in divergent directions.
Growth Catalysts
- India's UPI infrastructure:Real-time payment volumes exceeding 10 billion monthly transactions are compressing latency requirements and driving demand for edge-deployed cloud nodes across Mumbai, Hyderabad, and Bengaluru.
- China's dual carbon goals:SAMR and MEE enforcement on hyperscale data centers is redirecting facility construction toward renewable-powered western provinces, creating compliant capacity for fintech workloads.
- RBI sandbox frameworks:Experimental licensing for neobanks and digital lenders is accelerating cloud-native core banking migrations without full regulatory burden.
Market Restraints
- Cross-border data friction:Australia's TGA and prudential standards impose operational resilience testing that extends procurement cycles for foreign cloud providers.
- Power supply concentration:Indonesia's grid instability in secondary cities limits data center expansion beyond Jakarta and Surabaya corridors.
- Legacy core entrenchment:Southeast Asian tier-2 banks maintain COBOL-dependent systems that resist API-driven interoperability without multimillion-dollar transformation budgets.
Strategic Opportunities
- Vietnam's underpenetrated neobank sector:State Bank of Vietnam's 2023 digital banking licensing framework opens greenfield cloud deployment for payment processors targeting 70% unbanked populations.
- Embedded finance convergence:Super-app ecosystems in Thailand and the Philippines are creating demand for modular, API-first cloud stacks that unify lending, insurance, and wealth management.
- Philippines' renewable energy transition:DOE-mandated green power procurement for data centers is attracting investment in Luzon-based solar-powered facilities.
Industry Challenges
- Cloud-native talent scarcity:Kubernetes and Terraform expertise concentrates in Singapore and Bangalore, leaving Jakarta and Manila operations dependent on expensive contract engineering.
- Multi-jurisdiction compliance orchestration:Simultaneous adherence to India's data localization, China's cybersecurity review, and Australia's CPS 234 standards fragments security architecture design.
- Interoperability debt:ISO 20022 migration timelines vary across ASEAN central banks, forcing payment processors to maintain parallel message formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Fintech Cloud Market |
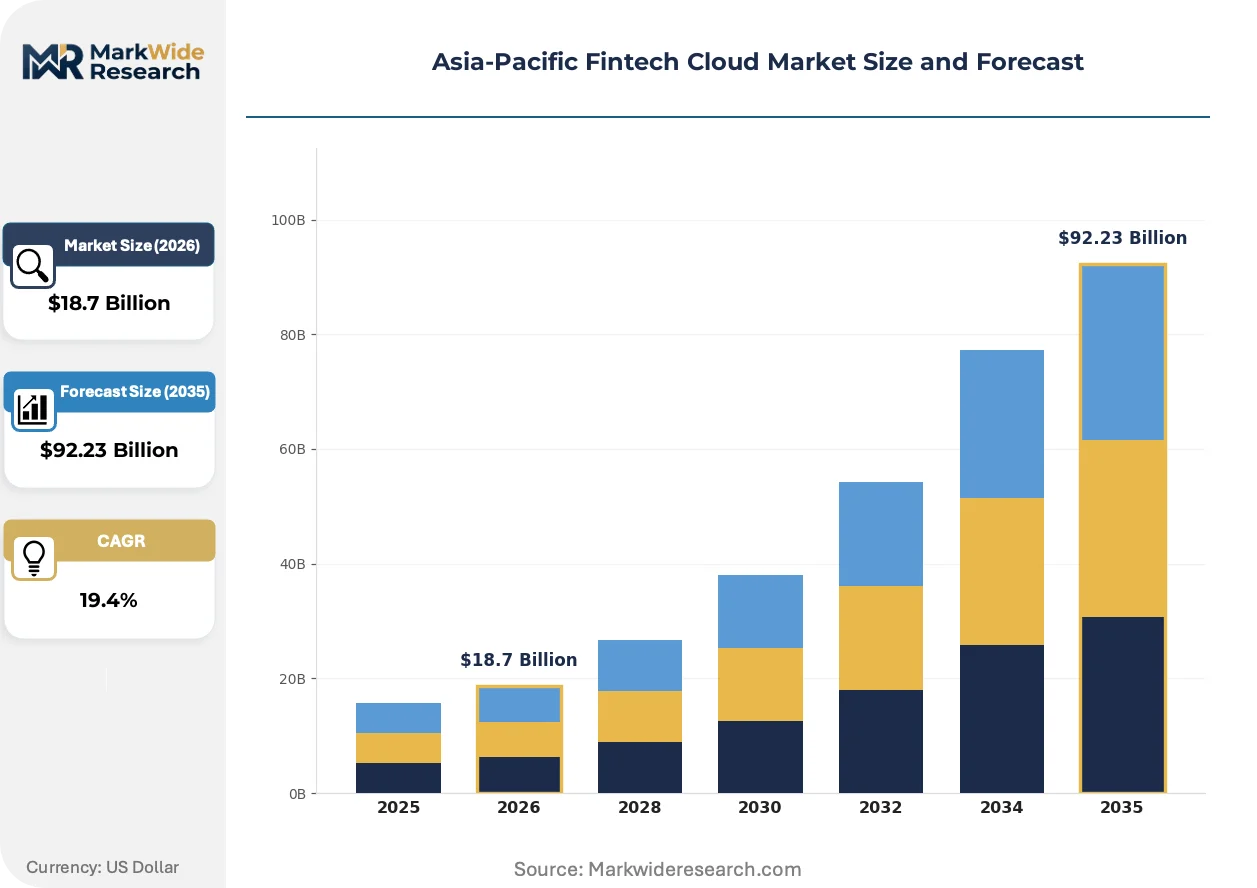
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Managed Services End User: Banks, Payment Processors, Investment Firms, Insurance Companies Solution: Digital Banking, Payment Solutions, Wealth Management, Risk Management |
| Companies Covered | Ant Group, Tencent, Alibaba Cloud, Paytm, Grab Financial Group, Huawei Cloud, AWS, Microsoft, Google, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Fintech Cloud Market Evolving Landscape
Serverless container orchestration is compressing infrastructure provisioning from weeks to hours, while sovereign AI regulations and embedded finance architectures are rewriting procurement criteria across the region.
Distributed ledger-based settlement rails are overtaking traditional correspondent banking for cross-border remittances. Philippine and Indonesian payment processors are deploying these systems to bypass SWIFT latency and fees. This compression is enabling real-time wage disbursement for gig economy platforms.
China's SAMR cybersecurity review framework for fintech data centers is mandating hardware-level attestation and source code inspection. Domestic cloud providers are pre-certifying entire technology stacks to accelerate customer onboarding. Foreign operators face 12-18 month approval windows that disadvantage their market entry.
Subscription-based infrastructure pricing is displacing reserved-instance commitments among mid-market payment processors. Singapore-based aggregators now offer consumption-aligned contracts with burst capacity guarantees. This shift is most visible in Malaysia's digital lending sector, where seasonal disbursement cycles demand elastic compute without annual lock-in.
Asia-Pacific Fintech Cloud Market Segmentation
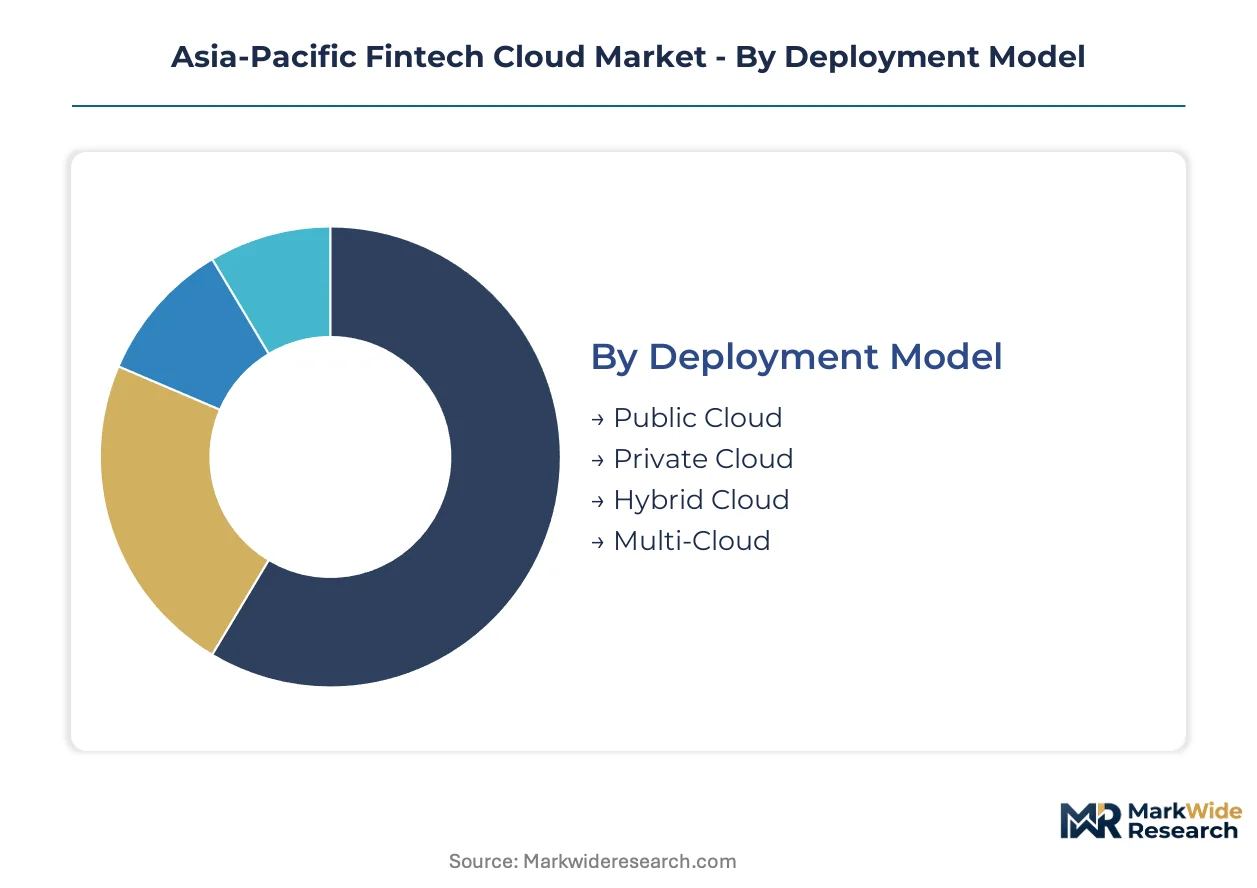
Cloud infrastructure procurement across Asia-Pacific fintech operators fragments across deployment architectures, service layers, and regulatory exposure profiles. Each segmentation axis reveals distinct margin structures, compliance burdens, and vendor concentration patterns that shape competitive positioning.
Deployment Model:
Supply concentration in hyperscale facilities across Singapore, Mumbai, and Shanghai determines which deployment architectures can satisfy sub-50 millisecond latency mandates for real-time payment clearing.
- Public Cloud:Shared infrastructure pools deliver elastic compute and storage through distributed availability zones. Tier-1 banks across India and Australia are migrating non-core workloads—customer analytics, marketing automation, and development environments—to public environments to shed capital intensity.
- Hybrid Cloud:Architectures split sensitive transaction processing across on-premises private nodes and burst capacity in public pools. Mid-market payment processors in Indonesia and Thailand favor this model to contain core banking data on-shore while accessing elastic settlement capacity during peak windows.
- Private Cloud:Dedicated infrastructure stacks serve institutions with strict data residency mandates. China's SAMR cybersecurity review framework and India's RBI localization directives sustain demand for sovereign private deployments.
- Multi-Cloud:Orchestration layers distribute workloads across competing hyperscalers to mitigate vendor lock-in and regulatory concentration risk. ASEAN neobanks are adopting multi-cloud strategies to satisfy divergent national data sovereignty requirements.
Today's leader: Public Cloud. Tomorrow's challenger: Hybrid Cloud.
Service Type:
Margin capture varies sharply across the infrastructure stack, with recurring compliance obligations anchoring subscription durability in upper-layer services.
- Infrastructure as a Service:Bare-metal compute, storage, and networking resources delivered through API-driven provisioning. IaaS volumes concentrate in India where UPI transaction growth demands rapid infrastructure scaling across Mumbai, Hyderabad, and Bengaluru nodes.
- Software as a Service:Pre-configured applications for regulatory reporting, anti-money-laundering screening, and fraud detection. SaaS margins expand fastest among mid-market payment processors seeking to externalize compliance engineering without building captive expertise.
- Platform as a Service:Managed runtime environments and middleware that accelerate cloud-native application deployment. PaaS adoption lags in Southeast Asia where Kubernetes and Terraform expertise concentrates in Singapore and Bangalore.
- Managed Services:Outsourced infrastructure operations including security monitoring, patch management, and disaster recovery. Australian prudential standards from the financial regulator and TGA operational resilience testing drive demand for managed service wrappers around cloud deployments.
SaaS commands premium pricing through compliance lock-in. IaaS faces margin compression from hyperscale competition.
End User:
Procurement sophistication and regulatory scrutiny intensity diverge markedly across financial institution types, fragmenting vendor engagement models.
- Payment Processors:Real-time transaction clearing operators with extreme latency sensitivity and burst scaling requirements. India's UPI infrastructure exceeding 10 billion monthly transactions compresses infrastructure procurement cycles and drives edge node deployment.
- Banks:Regulated deposit-taking institutions with legacy core banking entrenchment. Tier-2 banks across Southeast Asia maintain COBOL-dependent systems that resist API-driven interoperability without multimillion-dollar transformation budgets.
- Insurance Companies:Risk carriers with actuarial compute demands and long-dated liability management. Insurers in Japan and South Korea are migrating actuarial modeling to cloud environments to access elastic high-performance compute.
- Investment Firms:Asset managers and broker-dealers with algorithmic trading and portfolio analytics workloads. Quantitative funds in Singapore and Hong Kong drive demand for low-latency co-location adjacent to exchange matching engines.
Payment processors anchor volume growth. Banks represent the longest sales cycles but largest contract values.
Solution:
Functional application areas map to distinct technology stacks, integration complexity, and recurring revenue profiles.
- Payment Solutions:Real-time clearing, cross-border remittance, and merchant acquiring infrastructure. Distributed ledger-based settlement rails in the Philippines and Indonesia are displacing traditional correspondent banking for gig economy wage disbursement.
- Digital Banking:Cloud-native core banking, mobile-first customer interfaces, and embedded finance orchestration. Vietnam's State Bank digital banking licensing framework opens greenfield deployment for neobanks targeting 70% unbanked populations.
- Risk Management:Credit scoring, fraud detection, and regulatory capital calculation engines. RBI digital lending guidelines and sandbox frameworks are accelerating cloud-native risk system deployment among experimental licensees.
- Wealth Management:Robo-advisory, portfolio construction, and client reporting platforms. Super-app ecosystems in Thailand and the Philippines are creating demand for modular API-first stacks unifying lending, insurance, and wealth management.
Payment Solutions capture the steepest expansion trajectory. Wealth Management remains underpenetrated outside Singapore and Australia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud engineering talent concentrates in Singapore and Bangalore, leaving secondary ASEAN markets dependent on distributed delivery models and regional hub architectures for fintech infrastructure deployment.
India
UPI transaction volumes exceeding 10 billion monthly payments compress latency requirements for cloud nodes across Mumbai, Hyderabad, and Bengaluru. RBI data localization directives and digital lending guidelines mandate on-shore storage of customer financial records. Mumbai anchors hyperscale facility investment as payment processors deploy edge infrastructure to meet sub-50 millisecond clearing thresholds.
China
Domestic fintech operators drive demand for sovereign cloud architectures that satisfy SAMR cybersecurity review frameworks and MEE carbon accountability mandates. Dual carbon goals redirect hyperscale data center construction toward renewable-powered western provinces. Sichuan and Guizhou host compliant capacity expansion as domestic providers pre-certify technology stacks to accelerate customer onboarding.
Singapore
Quantitative funds and regional headquarters operations sustain demand for low-latency co-location adjacent to exchange matching engines. MAS regulatory frameworks shape cross-border data governance expectations for institutions operating cloud infrastructure across ASEAN. Marina Bay and Changi North clusters concentrate managed service providers delivering security monitoring and disaster recovery wrappers.
Indonesia
Digital lending platforms and payment processors seek burst capacity without full infrastructure surrender amid grid instability constraints. State Bank of Indonesia licensing frameworks for neobanks accelerate cloud-native core banking migrations. Jakarta and Surabaya corridors limit viable data center expansion as secondary cities face power supply concentration risks.
Vietnam
State Bank of Vietnam's 2023 digital banking licensing framework opens greenfield cloud deployment for payment processors targeting 70% unbanked populations. DOE-mandated green power procurement redirects facility investment toward solar-powered Luzon-based capacity. Ho Chi Minh City anchors initial hyperscale presence as operators test modular API-first stacks for embedded finance convergence.
Asia-Pacific Fintech Cloud Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform orchestrators across the Asia-Pacific fintech cloud sector. Hyperscale facility owners dominate volume capture through distributed availability zone networks. Tier-2 managed service providers and sovereign cloud specialists occupy intermediate positions. Competitive moves concentrate on multi-sovereign data residency framework construction and renewable-powered capacity expansion.
Within the domestic Chinese tier, Ant Group, Tencent, and Alibaba Cloud exemplify vertically integrated platform ecosystems that embed cloud services within super-app financial architectures. These operators anchor sovereign cloud positioning through pre-certified technology stacks satisfying SAMR hardware-level attestation requirements. AWS and Microsoft occupy the foreign hyperscale archetype, facing extended approval windows that disadvantage market entry against domestic compliance velocity.
| Leading Market Players |
|---|
| Ant Group |
| Tencent |
| Alibaba Cloud |
| Paytm |
| Grab Financial Group |
| Huawei Cloud |
| AWS |
| Microsoft |
| Others |
Value Network & Pricing Analysis
India's UPI transaction volumes exceeding 10 billion monthly payments compress infrastructure procurement cycles and force hyperscale providers to deploy edge nodes across Mumbai, Hyderabad, and Bengaluru. This demand concentration enables tier-1 cloud operators to command subscription premiums for sub-50 millisecond latency guarantees while mid-market payment processors face margin pressure from burst capacity requirements.
Pricing Analysis
Bundled managed service wrappers around core infrastructure are displacing unbundled compute-and-storage procurement across ASEAN markets. Three-tier pricing structure across premium sovereign-compliant, standard multi-availability-zone, and economy shared-tenant levels differentiates offerings, with certification against India's RBI data localization and China's SAMR cybersecurity review anchoring premium tiers. Cost compression in standard-tier IaaS is intensifying because hyperscale facility investment in renewable-powered western Chinese provinces and Luzon-based solar facilities expands compliant capacity. Mid-market payment processors in Indonesia and Vietnam exhibit highest price sensitivity due to seasonal disbursement volatility, while quantitative funds in Singapore demonstrate lowest sensitivity for co-location adjacent to exchange matching engines.
Supply Chain Analysis
Hardware refresh cycles and technology stack pre-certification flows are shortening as domestic Chinese providers accelerate customer onboarding through SAMR-compliant attestation processes. Server and networking equipment concentrates in China, Taiwan, and South Korea, with specialized financial industry zone configurations drawing from these manufacturing hubs. Supply chain vulnerability rests on single-source dependency for advanced semiconductor components subject to export control review. Distribution runs through direct hyperscale sales teams for tier-1 banks alongside Singapore-based managed service aggregators serving mid-market ASEAN payment processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's RBI sandbox frameworks and China's SAMR cybersecurity reviews continuously elevate compliance thresholds that lock in subscription durability for certified providers.
For Market Incumbents: Acquire edge computing infrastructure assets in secondary Indian cities beyond Mumbai and Bengaluru to preempt latency compression from UPI volume growth. Build captive renewable energy procurement capabilities in western Chinese provinces to satisfy MEE carbon accountability mandates without third-party dependency. Defend against domestic Chinese providers' pre-certification velocity by embedding managed security monitoring wrappers that extend switching costs. For New Entrants and Emerging Players: Capture Vietnam's greenfield neobank sector under State Bank of Vietnam's 2023 digital banking licensing framework, where 70% unbanked populations and nascent hyperscale presence create first-mover terrain. Target Philippine payment processors deploying distributed ledger settlement rails for gig economy wage disbursement, as these operators seek modular API-first stacks bypassing traditional correspondent banking infrastructure. Lead with consumption-aligned contracts featuring burst capacity guarantees rather than reserved-instance commitments. For Investors and Strategic Acquirers: Asymmetric upside sits with sovereign cloud specialists possessing pre-certified technology stacks across multiple Asia-Pacific jurisdictions. Long-term viability centers on providers capable of orchestrating simultaneous compliance with India's data localization, China's cybersecurity review, and Australia's CPS 234 operational resilience standards. Monitor ISO 20022 migration timeline convergence across ASEAN central banks as inflection indicator for payment processor infrastructure refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Deployment | Compresses latency for India's UPI clearing thresholds across Mumbai, Hyderabad, and Bengaluru corridors. |
| Renewable-Powered Facility Buildout | Satisfies China's SAMR and MEE dual carbon mandates while anchoring compliant capacity in Sichuan and Guizhou. |
| Multi-Sovereign Certification Investment | Enables simultaneous RBI, SAMR, and TGA compliance that fragments competitor security architectures. |
| Embedded Finance Platform Integration | Unifies lending, insurance, and wealth management APIs within Thailand and Philippines super-app ecosystems. |
| Managed Service Wrapper Development | Externalizes Australian prudential standard compliance for tier-2 banks without captive expertise investment. |
Research Methodology
Coverage spans India, China, Singapore, Indonesia, and Vietnam, with primary inputs from each market's cloud infrastructure decision-makers. Interviews with hyperscale facility operators, neobank CTOs, payment processor platform engineers, and regulatory compliance officers combined with secondary validation from RBI circulars, SAMR cybersecurity review frameworks, MAS guidance notices, and ASEAN central bank ISO 20022 migration announcements. Bottom-up triangulation across deployment model adoption rates and top-down reconciliation against hyperscale capex disclosures anchored market sizing.
Rate-of-change decomposition across the projection horizon separated volume growth from price evolution and mix shift effects. Segmentation dimensions modeled include deployment architecture, service layer, end-user institution type, and regulatory exposure profile, with sovereign compliance tier and latency sensitivity as cross-cutting modifiers. CAGRs derived from infrastructure investment run-rates, UPI transaction growth trajectories, and renewable-powered facility commissioning schedules across the analysis window.
Regulatory timeline acceleration, grid stability failures in Indonesian secondary cities, and talent concentration bottlenecks in Kubernetes and Terraform expertise are the dominant revision risks to modeled outcomes. Practitioners should monitor central bank sandbox licensing velocity, hyperscale renewable energy procurement announcements, and ISO 20022 migration deadline harmonization across ASEAN for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Vietnam Fintech Market
FinTech
MENA Fintech Market
FinTech
China Fintech Market
FinTech
Business Analytics in Fintech Market
FinTech
Blockchain in Fintech Market
FinTech
France AI in Fintech Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Spend Management Platform Market
FinTech
Australia Fintech Market
FinTech
AI in Fintech Market
FinTech
United Kingdom Fintech Market
FinTech
Transaction Monitoring Software Market
FinTech
Latin America Fintech Market
FinTech
Multichannel Digital Banking Integration Software Market
FinTech
Fintech Crisis Management Market
FinTech
Robotic Process Automation (RPA) in Financial Services Market