
 Parenteral Drugs Market | 2026-2036
Parenteral Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Parenteral Drugs Market Outlook
Single-use closed-system transfer devices and robotic aseptic filling is reshaping parenteral manufacturing economics, cutting contamination risk while boosting batch throughput. Fresenius anchors European capacity through its Kabi infusion therapy division and verticalized compounding operations. Baxter competes on premixed medication delivery systems that reduce pharmacy labor and dosing errors at the point of care. Teva Pharmaceutical Industries specializes in generic injectables, leveraging complex formulation capabilities to occupy niche sterile segments with limited competition.
Parenteral drugs are sterile pharmaceutical preparations administered directly into body tissues or the circulatory system, bypassing gastrointestinal absorption through formulations meeting USP <797> and <800> sterility and handling standards. Biologics command premium positioning within the product type split, as monoclonal antibodies and cell therapies require parenteral delivery due to protein degradation in the digestive tract. Intravenous infusion dominates the delivery mode landscape for hospital-administered oncology and critical care, while subcutaneous formulations are gaining fastest in home healthcare as self-injection devices improve patient compliance. Vials retain volume leadership among container types, though prefilled syringes are capturing share in chronic disease management where dosing precision and reduced needlestick risk matter.
FDA enforcement of Current Good Manufacturing Practice for finished pharmaceuticals and the EU's Annex 1 revision on sterile medicinal products are elevating barrier isolation and continuous monitoring requirements across production facilities. The EPA regulates pharmaceutical wastewater discharge from active ingredient synthesis, adding environmental compliance costs to parenteral API manufacturing. Stakeholders must weigh capital deployment between isolator-based aseptic lines and emerging continuous manufacturing platforms as regulatory expectations and competitive intensity converge on quality assurance and supply resilience.
Market Dynamics
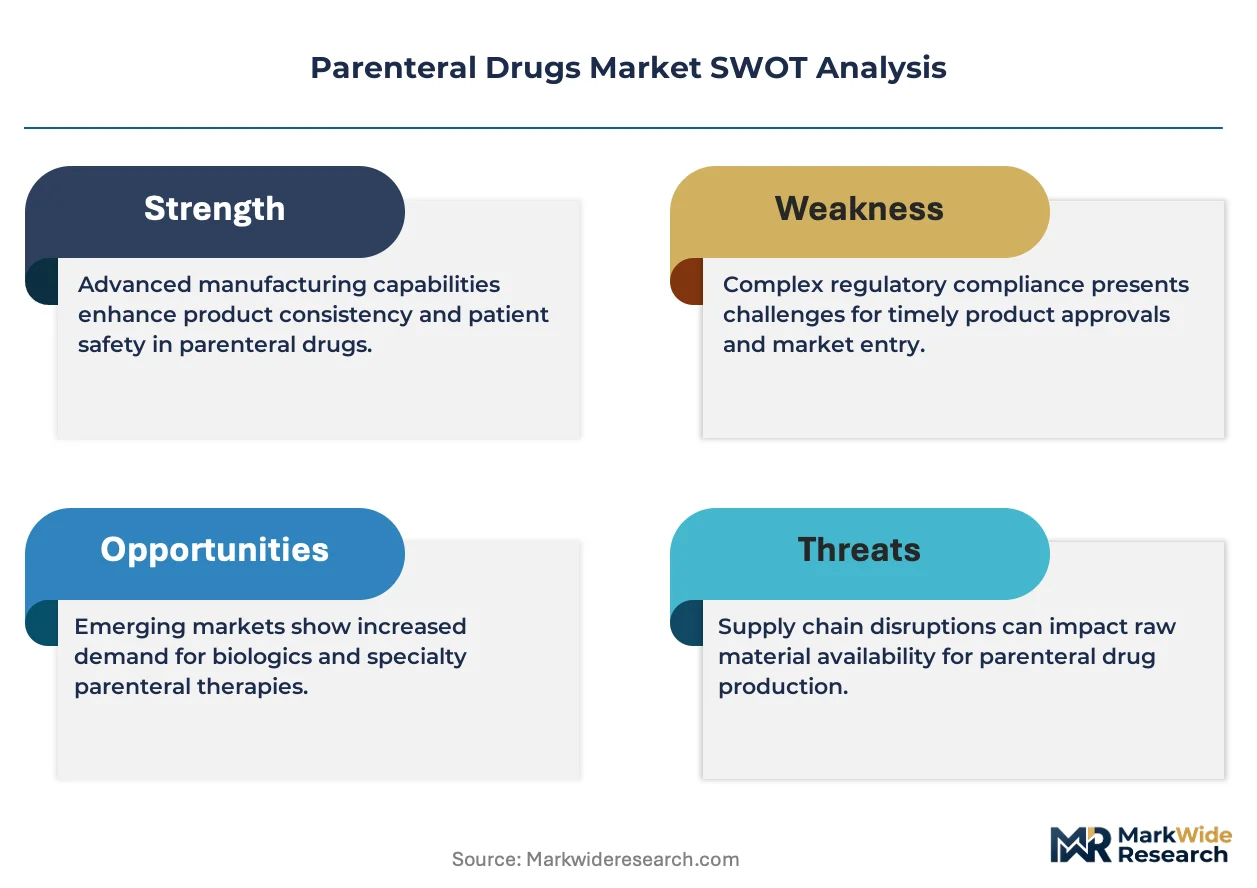
The FDA's updated sterile manufacturing guidance and the EU's Annex 1 revision are compressing legacy aseptic processing economics, forcing capital redeployment toward isolator-based filling infrastructure.
Growth Catalysts
- Specialty pharmacy networks:Ambulatory infusion centers in the United States are capturing patient volume from traditional inpatient settings, expanding parenteral drug administration capacity.
- Biologic protocol standardization:Oncology and immunology treatment pathways now mandate parenteral administration for monoclonal antibodies and cell therapies.
- REACH and RoHS alignment:European environmental compliance frameworks are accelerating adoption of closed-system transfer devices that reduce hazardous exposure.
Market Restraints
- API synthesis wastewater costs:EPA pharmaceutical discharge regulations add environmental compliance burdens to active ingredient manufacturing.
- Barrier isolation capex intensity:Continuous monitoring and isolator-based line upgrades require substantial capital deployment with extended payback periods.
- Glass supply concentration:Borosilicate vial production clusters in limited geographic zones create container shortage vulnerability during demand spikes.
Strategic Opportunities
- Home healthcare subcutaneous shift:Self-injection device improvements open chronic disease management to outpatient settings previously requiring intravenous infusion.
- Japan's PMDA accelerated review:Regulatory pathways for innovative parenteral formulations compress time-to-market for complex generics.
- Continuous manufacturing convergence:Integration of process analytical technology with isolator-based filling enables real-time release testing.
Industry Challenges
- Aseptic processing technician scarcity:FDA cGMP enforcement elevates qualification requirements for sterile operators, constraining workforce expansion.
- Legacy line decommissioning timelines:Facility shutdowns for isolator retrofitting disrupt batch schedules and contract manufacturing commitments.
- USP <800> hazardous drug handling:Compounding pharmacy infrastructure upgrades for cytotoxic agents strain operational budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parenteral Drugs Market |
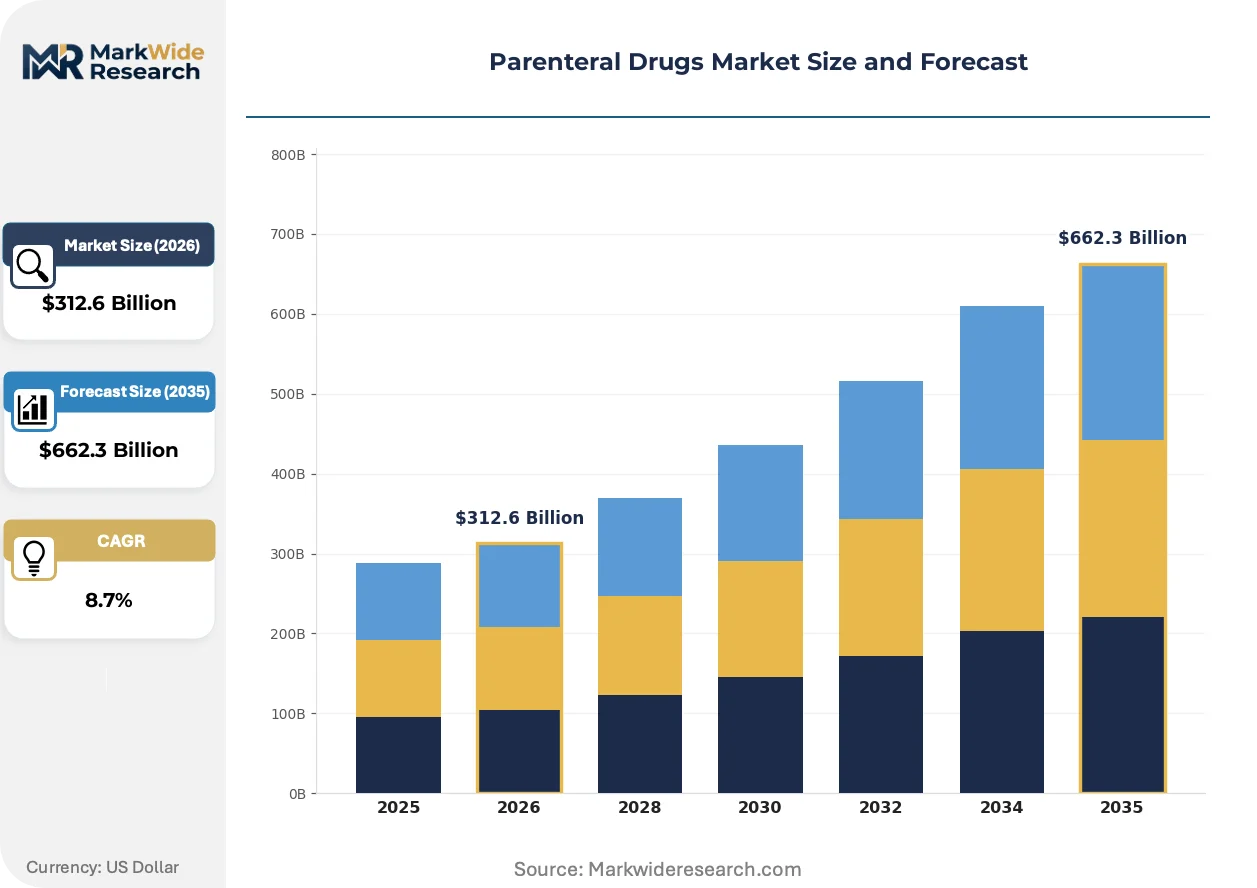
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Vaccines, Insulin Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Intraarterial End User: Hospitals, Clinics, Home Healthcare, Research Laboratories Container Type: Syringes, Vials, Ampoules, Infusion Bags |
| Companies Covered | Fresenius, ICU Medical, Baxter, Teva Pharmaceutical Industries, Grifols, B. Braun, Otsuka Pharmaceutical Co., Kelun Pharma, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parenteral Drugs Market Strategic Shifts
Robotic aseptic filling and single-use closed-system technologies are compressing contamination risk while expanding batch throughput economics. Three developments are restructuring competitive positioning.
Robotic aseptic filling systems integrate machine vision with gloveless isolator interfaces to eliminate human intervention during critical fill-finish operations. Contract manufacturers in the United States and Germany are deploying these systems to meet FDA and EMA sterility assurance expectations. Traditional cleanroom-based filling with manual intervention is rendering obsolete for high-value biologic batches.
The EU's Annex 1 revision on sterile medicinal products mandates barrier isolation and continuous viable/non-viable monitoring across all aseptic processing zones. European manufacturers face facility retrofit deadlines that compress legacy asset utilization windows. Parenteral drug facilities in Ireland, Switzerland, and the Netherlands are prioritizing isolator line investments to maintain EMA GMP certification.
Hospital procurement departments are consolidating supplier relationships around premixed medication delivery systems that reduce pharmacy labor and dosing errors. Specialty pharmacy networks are displacing traditional wholesale distribution for oncology and immunology infusions. This concentration is most visible in United States metropolitan markets where integrated delivery networks negotiate direct manufacturer contracts.
Parenteral Drugs Market Segmentation
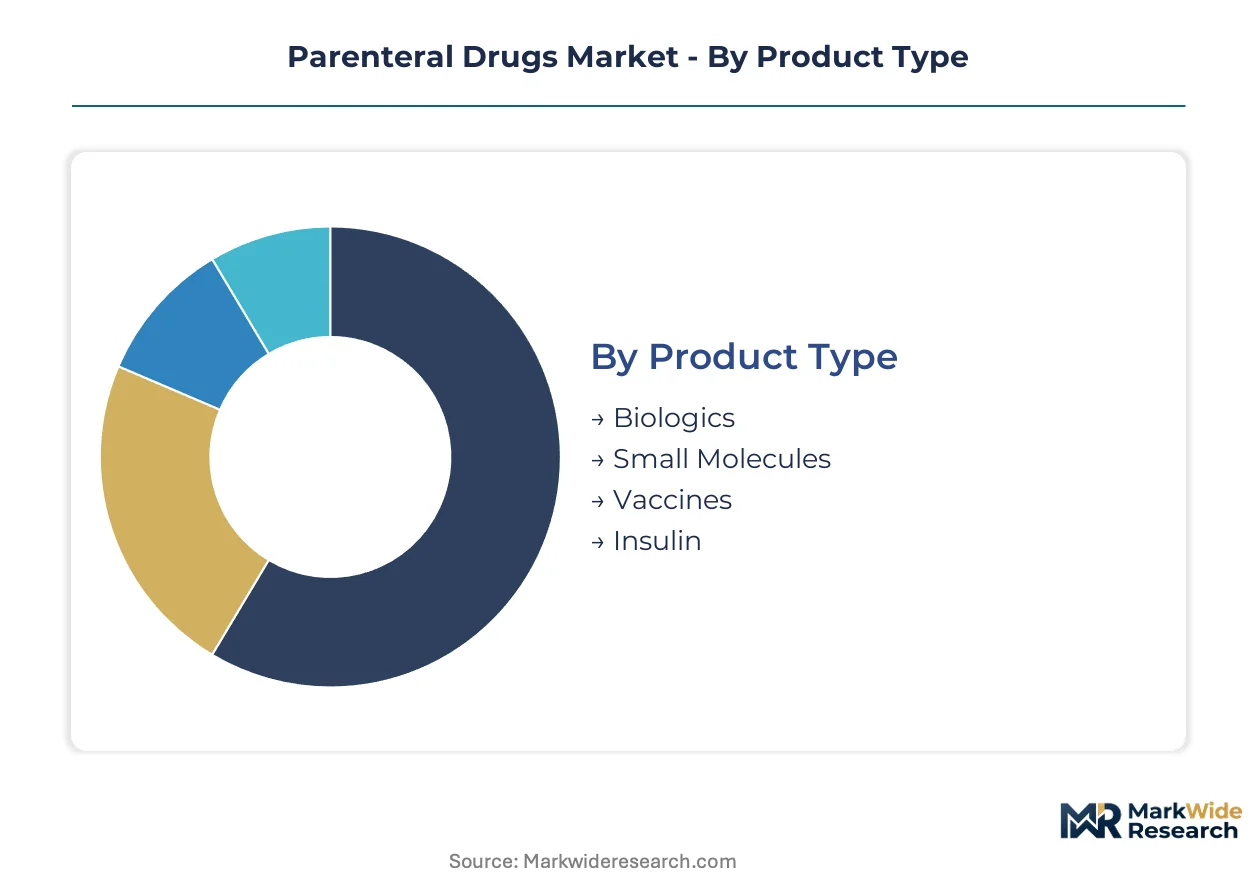
Parenteral drug segmentation reveals how formulation complexity, administration setting, and container engineering interact to determine procurement economics. Each dimension carries distinct regulatory burdens and capital intensity profiles that reshape competitive positioning across therapeutic categories.
Product Type:
Cost tier stratification separates protein-based therapies from commodity small molecules, with manufacturing complexity driving margin dispersion across therapeutic classes.
- Biologics:Monoclonal antibodies and cell therapies require cold-chain distribution and isolator-based aseptic processing due to protein structural sensitivity. Hospital oncology departments in the United States concentrate procurement volume as immunology protocols standardize on infusion-based administration.
- Small Molecules:Generic injectable antibiotics and analgesics compete on manufacturing scale and API sourcing efficiency. Teva Pharmaceutical Industries and Fresenius Kabi dominate capacity for hospital-critical sterile generics where formulation complexity creates limited-competition niches.
- Vaccines:Adjuvanted formulations and mRNA lipid nanoparticles demand specialized fill-finish infrastructure with enhanced cold-chain integrity.
- Insulin:Biosimilar and analog formulations for diabetes management shift toward prefilled pen systems and pump-compatible cartridges.
Small molecules command the established base. The steepest expansion runs through biologics.
Delivery Mode:
Application setting determines device engineering requirements, with acute care infusion systems diverging sharply from ambulatory self-administration platforms.
- Intravenous:Direct circulatory access enables rapid bioavailability for critical care and oncology protocols. United States specialty pharmacy networks and ambulatory infusion centers are capturing patient volume from traditional inpatient settings, expanding IV administration capacity outside hospital walls.
- Subcutaneous:Self-injection devices and wearable pump systems enable chronic disease management in home healthcare settings. Prefilled syringes and auto-injectors reduce needlestick risk while improving dosing precision for immunology and endocrine therapies.
- Intramuscular:Deep tissue deposition supports vaccine delivery and depot formulations requiring sustained release kinetics.
- Intraarterial:Regional chemotherapy perfusion and interventional radiology procedures demand catheter-based delivery with real-time imaging guidance.
Intravenous administration commands the established base. The steepest expansion runs through subcutaneous delivery.
End User:
Customer type concentration reflects care migration patterns, with integrated delivery networks restructuring procurement relationships around site-of-service economics.
- Hospitals:Inpatient oncology and critical care units drive bulk purchasing of premixed medication delivery systems. Baxter competes on integrated infusion pumps and medication management software that reduce pharmacy labor and dosing errors at the point of care.
- Home Healthcare:Subcutaneous biologics and insulin therapies shift administration to outpatient settings as self-injection device engineering improves patient compliance. United States metropolitan markets see fastest penetration of specialty pharmacy direct-to-patient distribution.
- Clinics:Ambulatory surgical centers and infusion suites concentrate same-day procedures requiring rapid-turn parenteral administration.
- Research Laboratories:Clinical trial supply chains demand small-batch sterile manufacturing with adaptive protocol flexibility and investigational drug labeling compliance.
Hospitals command the established base. The steepest expansion runs through home healthcare.
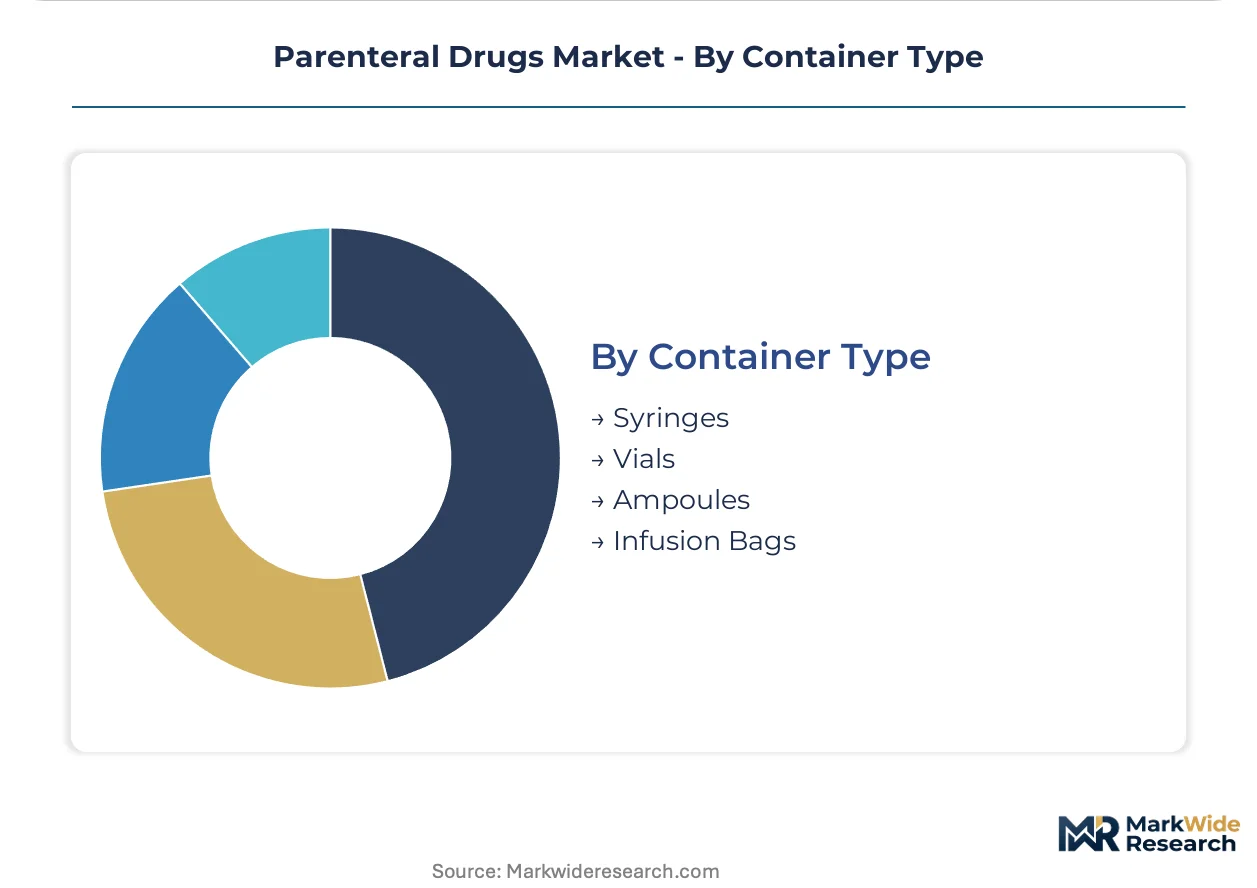
Container Type:
Volume and margin profiles diverge across primary packaging formats, with glass integrity and extractables testing determining regulatory qualification timelines.
- Vials:Borosilicate glass containers retain leadership for multi-dose biologics and hospital pharmacy compounding operations. Production clusters in limited geographic zones create shortage vulnerability during demand spikes, constraining supply resilience.
- Syringes:Prefilled glass or polymer barrels capture chronic disease management share where dosing precision and reduced needlestick risk matter. Self-injection device integration with safety-engineered needle systems accelerates adoption in immunology and diabetes.
- Ampoules:Single-dose glass containers serve emergency medicine and anesthesiology applications requiring immediate access without reconstitution steps.
- Infusion Bags:Flexible polymer containers for large-volume parenteral solutions and premixed drug delivery reduce pharmacy admixture labor.
Vials command the established base. The steepest expansion runs through syringes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports parenteral drug manufacturing equipment and fill-finish technologies to United States biopharma facilities, establishing a transatlantic trade corridor in sterile processing infrastructure.
United States
Specialty pharmacy networks and ambulatory infusion centers capture patient volume from traditional inpatient settings. FDA enforcement of Current Good Manufacturing Practice elevates barrier isolation requirements across production facilities. Boston-Cambridge biopharma clusters prioritize isolator-based aseptic lines to maintain compliance with sterility assurance standards.
Germany
Hospital procurement of biologic infusions expands as oncology protocols standardize on parenteral administration. EMA Annex 1 revision mandates continuous viable and non-viable monitoring across aseptic processing zones. Frankfurt-Rhine-Main pharmaceutical corridors retrofit legacy facilities with robotic filling systems to preserve GMP certification.
Switzerland
Complex formulation capabilities concentrate in sterile generics manufacturing for limited-competition niche segments. Swissmedic maintains stringent sterility assurance expectations for parenteral medicinal products. Basel pharmaceutical clusters deploy isolator-based infrastructure to serve contract manufacturing demand from European biotech sponsors.
Japan
PMDA accelerated review pathways compress time-to-market for innovative parenteral formulations. METI industrial policy supports domestic fill-finish capacity expansion for biologic therapies. Osaka-Kobe pharmaceutical manufacturing zones integrate process analytical technology with isolator systems to enable real-time release testing.
India
CDSCO regulatory harmonization aligns domestic sterile manufacturing standards with ICH guidelines for export market access. API synthesis wastewater discharge regulations add environmental compliance costs to active ingredient manufacturing. Hyderabad-Visakhapatnam pharmaceutical corridors expand isolator-based filling capacity to supply United States and European generic injectable markets.
Parenteral Drugs Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: diversified healthcare conglomerates with verticalized infusion therapy divisions, generic injectable specialists leveraging complex formulation capabilities, and premixed medication delivery system providers. Dominant competitive moves include isolator-based line retrofits for regulatory compliance and specialty pharmacy network partnerships for site-of-service capture.
Among diversified healthcare conglomerates, Fresenius anchors European capacity through verticalized compounding operations. Baxter occupies a position in premixed medication delivery systems that reduce pharmacy labor at the point of care. Teva Pharmaceutical Industries exemplifies the generic injectable specialist archetype, leveraging formulation complexity to serve limited-competition sterile segments.
| Leading Market Players |
|---|
| Fresenius |
| ICU Medical |
| Baxter |
| Teva Pharmaceutical Industries |
| Grifols |
| B. Braun |
| Otsuka Pharmaceutical Co. |
| Kelun Pharma |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
Isolator-based filling line undercapacity across European manufacturing hubs is compressing contract manufacturing margins while elevating pricing power for qualified sterile processors. Utilization rates above threshold levels in Germany and Switzerland are forcing buyers into longer-term offtake commitments with penalty clauses for volume flexibility.
Pricing Analysis
Legacy cleanroom-based filling versus isolator-based robotic systems versus continuous manufacturing platforms creates a three-generation pricing structure across premium, standard, and economy tiers. Contract manufacturers with EMA Annex 1 compliant isolator lines command 40-60% premiums over legacy cleanroom operators due to sterility assurance differentiation. Cost compression in standard-tier vial filling is intensifying because Indian and Chinese generic injectable specialists are expanding isolator capacity for export markets. Hospital procurement departments exhibit highest price sensitivity for commodity small-molecule injectables, while biotech sponsors show lowest sensitivity for clinical trial material where batch failure risk dominates total cost.
Supply Chain Analysis
Tariff exposure between United States and China in pharmaceutical glassware and stainless steel processing equipment dominates supply chain risk planning for sterile manufacturing infrastructure. Borosilicate vial production concentrates in Germany, China, and India, with specialty tubing glass drawing from Schott AG's European furnaces and Corning's North American facilities. Active pharmaceutical ingredient synthesis for parenteral drugs rests on Chinese intermediate suppliers and Indian finished-API manufacturers, creating single-source vulnerability for oncology cytotoxics. Distribution runs through specialty pharmacy networks in United States metropolitan markets and hospital procurement consortiums in European integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty pharmacy platform economics are reconfiguring parenteral drug value capture around site-of-service arbitrage and reimbursement pathway control. Interoperability between infusion pump systems and electronic health record networks is becoming the decisive ecosystem battleground.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA and EMA isolator line qualification to lock in biotech sponsor relationships. Fresenius and Baxter should accelerate backward integration into borosilicate glass tubing supply through long-term offtake agreements with Schott. Capacity addition in Switzerland and Ireland preserves GMP certification proximity to European biotech clusters while generic injectable specialists in India threaten standard-tier pricing. For New Entrants and Emerging Players: Home healthcare subcutaneous delivery in Japan and South Korea offers the most penetrable geographic expansion vector for self-injection device manufacturers. Ambulatory infusion center partnerships in United States secondary metropolitan markets provide white-space access outside dominant specialty pharmacy networks. Go-to-market positioning should emphasize USP <800> hazardous drug handling compliance as a differentiated service layer for oncology compounding. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across isolator-based fill-finish infrastructure as EMA Annex 1 retrofit deadlines compress legacy asset values. Five-to-ten year viability favors contract manufacturers with qualified sterile capacity in both United States and European regulatory jurisdictions. Acquisition targets should display robotic aseptic filling deployment and specialty pharmacy network contracts. The signal to watch is FDA warning letter frequency for legacy cleanroom operators as decommissioning timelines accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Line Retrofit and Qualification | EMA Annex 1 compliance preserves European market access for sterile medicinal products. |
| Specialty Pharmacy Network Partnership | Site-of-service capture redirects patient volume from hospital inpatient settings. |
| Robotic Aseptic Filling Deployment | FDA sterility assurance expectations render manual cleanroom operations obsolete. |
| Subcutaneous Formulation Development | Self-injection device integration opens home healthcare reimbursement pathways. |
| Backward Integration into Glass Supply | Borosilicate vial shortage vulnerability demands captive supply arrangements. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital pharmacy directors, sterile manufacturing executives, regulatory affairs leads, and specialty pharmacy network operators. Secondary validation drew from FDA warning letter databases, EMA GMP inspection records, USP <797> and <800> revision documents, and hospital procurement database extracts. Bottom-up capacity modeling across isolator-based filling lines was triangulated against top-down therapeutic category demand projections.
Calibration against historical capacity utilization and regulatory enforcement patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type complexity tier, delivery mode setting, container engineering format, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions. Forecast inputs incorporated biologic pipeline submission rates and specialty pharmacy network expansion trajectories.
Practitioners should monitor FDA isolator guidance revisions and EMA Annex 1 inspection deficiency trends for early signals of compliance cost inflection. Forecasts reflect assumptions about regulatory harmonization timelines and sterile manufacturing workforce availability that could shift with immigration policy or training program expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Global Cold and Flu Drugs Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Egypt Diabetes Drugs Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market