
 Collagenase Clostridium Histolyticum Market | 2026-2036
Collagenase Clostridium Histolyticum Market Size, Share, and Industry Trends Forecast 2026-2036
Collagenase Clostridium Histolyticum Market Analysis
Hospital and specialty clinic procurement channels are tilting toward integrated wound-care bundles that pair collagenase with debridement protocols. Horizon Therapeutics sustains dominance in North American hospital formularies through its established orphan-drug infrastructure. Merz Pharmaceuticals anchors European distribution with concentrated strength in German urology and hand-surgery centers. BioSpecifics Technologies leverages its manufacturing scale to supply active pharmaceutical ingredient to multiple finished-dose partners globally.
Collagenase Clostridium Histolyticum is a purified mixture of two collagen-degrading enzymes, class I and class II collagenases, derived from Clostridium histolyticum fermentation, typically formulated at standardized activity units for enzymatic lysis of collagen-rich connective tissue. Its primary commercial purpose is localized pharmacological disruption of pathological collagen deposits in conditions such as Dupuytren's contracture, Peyronie's disease, and selected wound debridement protocols. Among product types, lyophilized formulations command premium positioning due to extended stability and cold-chain flexibility, while injections generate the highest procedure volume across outpatient settings. The application landscape shows fasciitis treatment as the mature revenue base, with chronic wound care representing the fastest-expanding margin pool as hospital outpatient departments adopt enzymatic debridement.
FDA orphan drug designation and EMA advanced therapy pathways shape competitive timelines, while ISO 13485 quality management standards govern contract manufacturing organization selection for biological enzyme production. The EU Medical Device Regulation and FDA 510(k) clearance requirements for combination delivery systems create layered compliance costs that favor sponsors with established regulatory affairs capacity. Stakeholders must monitor evolving CMS reimbursement decisions for wound-care biologics and the trajectory of biosimilar collagenase development programs.
Market Dynamics
Hospital outpatient departments in the United States, Germany, and Japan are consolidating enzymatic debridement protocols into bundled wound-care contracts, compressing procurement cycles and favoring suppliers with integrated cold-chain logistics.
Growth Catalysts
- FDA orphan drug exclusivity:The framework grants seven-year market exclusivity for rare disease indications, incentivizing developers to pursue Dupuytren's contracture and Peyronie's disease pathways.
- Chronic wound care expansion:Hospital outpatient departments in the United States are adopting collagenase-based debridement as standard protocol for diabetic foot ulcers and pressure injuries.
- Cellulite treatment protocols:Dermatology practices in Brazil and South Korea are driving off-label demand for subcision-combination therapies targeting fibrotic septae.
Market Restraints
- Fermentation capacity concentration:Active pharmaceutical ingredient production clusters in North American contract manufacturing organizations, creating single-source vulnerability for finished-dose partners.
- Cold-chain cost structure:Lyophilized formulations require continuous temperature monitoring from fermentation through final mile, elevating logistics expenditure versus small-molecule alternatives.
- Biosimilar development timelines:Complex enzyme characterization requirements under ICH Q5C guidelines extend preclinical validation periods beyond typical biologic comparability studies.
Strategic Opportunities
- Japanese urology centers:Peyronie's disease diagnosis rates lag Western benchmarks by 40%, presenting expansion potential as PMDA reimbursement pathways mature.
- Combination delivery systems:Integration with hyaluronidase co-formulations is enabling deeper tissue penetration for retracted cord presentations in hand surgery.
- EMA advanced therapy medicinal products:The pathway accelerates scientific advice and centralized marketing authorization for novel fibrotic indications beyond current orphan designations.
Industry Challenges
- Enzymatic assay standardization:Variability in collagenase activity unit measurement between pharmacopeial methods complicates batch release and cross-supplier substitution.
- ISO 13485 certification timelines:Contract manufacturing organization qualification for biological enzyme production averages 18-24 months, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collagenase Clostridium Histolyticum Market |
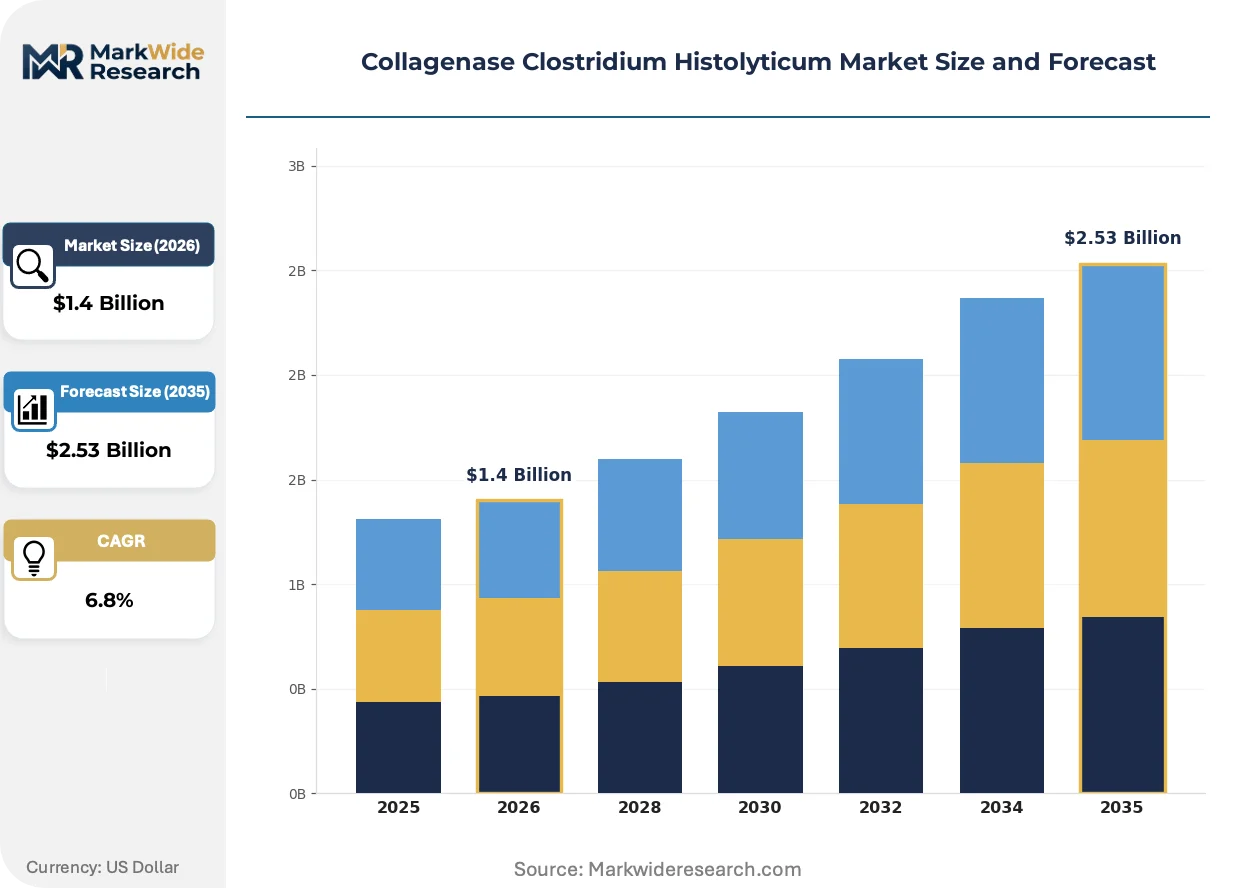
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injections, Gel, Powder, Lyophilized End User: Hospitals, Clinics, Outpatient Facilities, Research Laboratories Application: Fasciitis Treatment, Surgery Preparation, Chronic Wound Care, Tissue Repair Delivery Mode: Intravenous, Subcutaneous, Topical, Intra-articular |
| Companies Covered | Horizon Therapeutics plc, Merz Pharmaceuticals GmbH, BioSpecifics Technologies Corp. (Endo International plc), Sanofi S.A., Novartis AG, Pfizer Inc., Revance Therapeutics Inc., MediWound Ltd., Swedish Orphan Biovitrum AB (Sobi), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collagenase Clostridium Histolyticum Market Emerging Trajectories
Enzymatic manufacturing and clinical deployment are converging around precision dosing, regulatory harmonization, and procurement centralization that favors integrated supply partners over fragmented vendor bases.
Lyophilized formulation technology is digitizing quality assurance through embedded temperature-logging sensors and blockchain-tracked chain-of-custody records. German hospital networks are mandating these smart packaging standards for high-value biologics. The technology is digitizing inventory management by enabling real-time cold-chain verification and automated reorder triggers based on stability data rather than fixed expiry assumptions.
EU Medical Device Regulation combination product requirements are forcing alignment between pharmaceutical and device quality management systems. Manufacturers of injection delivery systems must now maintain technical documentation under both MDR and pharmaceutical GMP standards. German and French notified bodies are experiencing 12-18 month backlog for conformity assessment, compressing launch timelines for next-generation applicators.
Hospital procurement departments are consolidating wound-care biologics into single-source framework agreements with integrated logistics providers. United States academic medical centers are displacing multi-vendor spot purchasing with three-year committed volume contracts. The shift concentrates supplier relationships among manufacturers with captive fermentation capacity and dedicated distribution infrastructure.
Collagenase Clostridium Histolyticum Market Segmentation
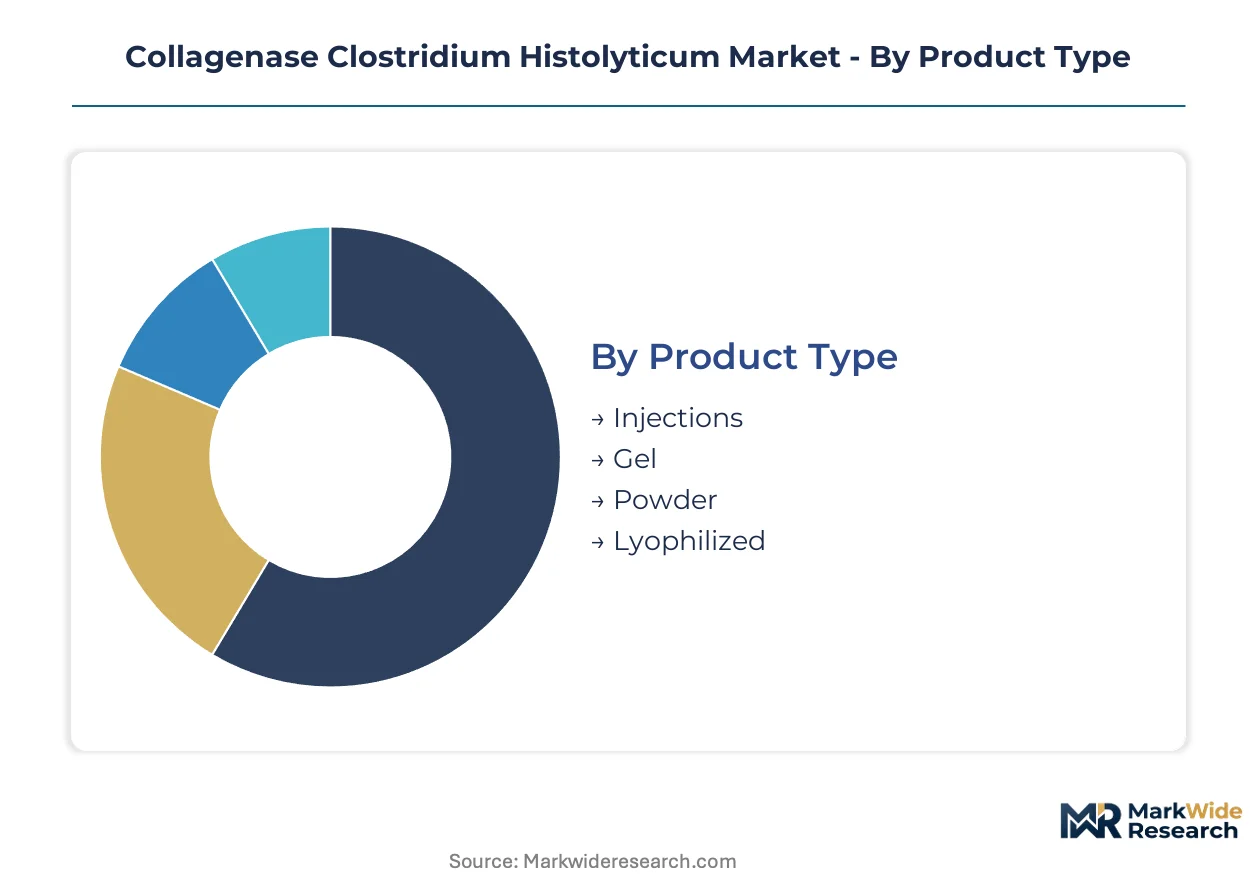
Segmentation in the Collagenase Clostridium Histolyticum market reveals divergent procurement rhythms across formulation types and care settings. Lyophilized products turn on 18-24 month manufacturing cycles while outpatient injections replenish on quarterly schedules. Understanding these velocity differences enables suppliers to align inventory positioning with channel-specific consumption patterns.
Product Type:
Cycle times stretch from days for ready-to-use gels to years for validated lyophilized batches, creating distinct working capital requirements across the portfolio.
- Lyophilized:Freeze-dried formulations at standardized activity units deliver extended stability beyond 36 months at controlled temperatures. German hospital networks mandate embedded temperature-logging sensors for these high-value biologics, compressing supplier qualification timelines.
- Injections:Liquid enzyme preparations in single-use vials dominate outpatient procedure volume across United States dermatology and urology practices. Quarterly procurement cycles align with insurance reimbursement windows for Dupuytren's contracture and Peyronie's disease interventions.
- Gel:Semisolid preparations enable topical debridement protocols in wound care centers with minimal preparation overhead.
- Powder:Bulk active enzyme material serves compounding pharmacies and research applications requiring custom formulation flexibility.
Lyophilized formulations anchor the volume base while injections gain share at the steepest rate as outpatient facilities expand enzymatic debridement protocols.
End User:
Procurement sophistication escalates from research laboratories with project-based purchasing to hospital systems with integrated supply chain demands.
- Hospitals:Academic medical centers in the United States are displacing multi-vendor spot purchasing with three-year committed volume contracts for wound-care biologics. These framework agreements bundle collagenase with debridement protocols and cold-chain logistics.
- Outpatient Facilities:Ambulatory surgery centers concentrate demand for Peyronie's disease and hand surgery applications where same-day discharge protocols favor rapid-acting enzymatic interventions over operative alternatives.
- Clinics:Dermatology and urology practices in Brazil and South Korea drive off-label demand for cellulite and fibrotic condition treatments.
- Research Laboratories:Preclinical and clinical trial supply chains require small-batch, high-characterization enzyme lots with extensive documentation packages.
Hospitals command the procurement leverage while outpatient facilities expand most quickly as surgical migration accelerates.
Application:
Margin profiles diverge between mature indications with established reimbursement and emerging protocols navigating coverage uncertainty.
- Fasciitis Treatment:Dupuytren's contracture interventions represent the commercial foundation with well-defined FDA orphan drug exclusivity and established CMS reimbursement codes. Hand surgery centers in Germany and Japan generate predictable recurring demand.
- Chronic Wound Care:Diabetic foot ulcer and pressure injury debridement protocols are expanding fastest as United States hospital outpatient departments adopt enzymatic alternatives to surgical sharp debridement.
- Surgery Preparation:Pre-operative tissue softening applications in orthopedic and plastic surgery settings require precise dosing coordination with operative schedules.
- Tissue Repair:Emerging applications in scar revision and fibrotic adhesion lysis remain investigational with variable payer coverage.
Fasciitis treatment anchors the volume base while chronic wound care gains share at the steepest rate.
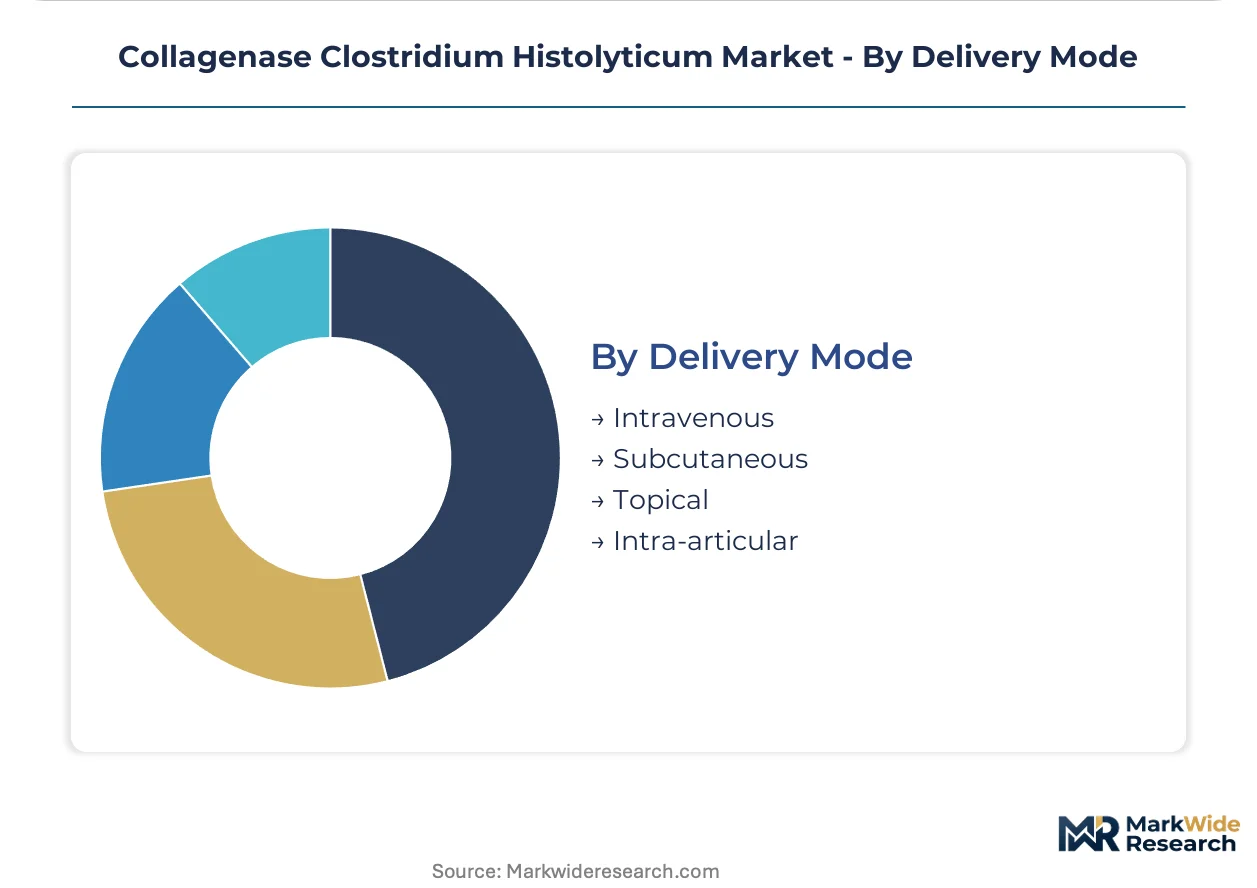
Delivery Mode:
Regulatory complexity scales with invasiveness, from topical applications under cosmetic oversight to intra-articular injections requiring combination product clearance.
- Subcutaneous:Direct injection into palpable cord or plaque tissue enables precise localized enzymatic action with minimal systemic exposure. This route dominates Dupuytren's and Peyronie's protocols across United States and European markets.
- Topical:Surface application for wound debridement avoids injection-related adverse events and expands addressable settings to nursing facilities and home care with appropriate training.
- Intravenous:Systemic enzyme administration remains investigational with limited commercial application due to immunogenicity concerns and narrow therapeutic indices.
- Intra-articular:Joint space injection for adhesive capsulitis and related fibrotic conditions requires combination product classification under EU Medical Device Regulation, extending development timelines.
Subcutaneous delivery anchors the volume base while topical administration gains share at the steepest rate as wound care decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites European distribution reliability for temperature-sensitive biologics. This logistics backbone connects fermentation facilities to hospital networks across the continent.
United States
FDA orphan drug exclusivity for Dupuytren's contracture and Peyronie's disease anchors manufacturer commitment. CMS reimbursement codes for outpatient enzymatic debridement sustain hospital procurement volumes. The Boston-Cambridge corridor concentrates clinical trial infrastructure and specialty hand surgery centers driving adoption protocols.
Germany
EMA centralized marketing authorization accelerates market access for novel fibrotic indications. ISO 13485 certification requirements for biological enzyme production govern contract manufacturing organization selection. The Rhine-Main cluster around Frankfurt anchors distribution networks serving urology and hand surgery centers across Baden-Württemberg and Bavaria.
Japan
PMDA reimbursement pathway maturation for Peyronie's disease interventions is closing the diagnosis gap with Western benchmarks. METI industrial policy supports domestic fermentation capacity expansion for biologic active pharmaceutical ingredients. Tokyo and Osaka metropolitan areas concentrate urology specialty practices adopting collagenase-based protocols.
Brazil
ANVISA regulatory harmonization with ICH guidelines streamlines import authorization for reference biologics. Off-label dermatology demand for cellulite treatment protocols drives private clinic procurement outside public reimbursement frameworks. São Paulo's private healthcare networks anchor consumption concentration in Southeast Brazil.
South Korea
MFDS fast-track designation for advanced therapy medicinal products accelerates scientific advice timelines for fibrotic indication expansions. Subcision-combination therapies for aesthetic applications concentrate demand in Seoul's Gangnam district dermatology practices. Domestic contract manufacturing organizations are qualifying for biological enzyme production under K-GMP standards.
Collagenase Clostridium Histolyticum Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying active pharmaceutical ingredient to finished-dose partners. The market structure concentrates around sponsors with captive orphan-drug infrastructure and established hospital formulary relationships. Three archetypes dominate: fermentation-scale API suppliers, integrated specialty pharmaceutical companies with regulatory affairs capacity, and regional distributors with cold-chain logistics networks. Competitive moves center on backward integration into fermentation capacity and strategic partnerships for combination delivery system development.
Among North American integrated sponsors, Horizon Therapeutics plc and BioSpecifics Technologies Corp. exemplify the platform archetype through orphan-drug infrastructure and API supply relationships respectively. Merz Pharmaceuticals GmbH anchors the European distribution tier with concentrated strength in German urology and hand surgery centers. These three entities represent distinct competitive positions: captive regulatory capacity, upstream manufacturing scale, and regional channel control.
| Leading Market Players |
|---|
| Horizon Therapeutics plc |
| Merz Pharmaceuticals GmbH |
| BioSpecifics Technologies Corp. (Endo International plc) |
| Sanofi S.A. |
| Novartis AG |
| Pfizer Inc. |
| Revance Therapeutics Inc. |
| MediWound Ltd. |
| Swedish Orphan Biovitrum AB (Sobi) |
| Others |
Supply Flow & Price Mechanics
The Port of Rotterdam's pharmaceutical cold-chain corridors govern cost dynamics across European distribution, compressing margins for suppliers without integrated temperature-controlled logistics while enabling premium capture by sponsors with captive fermentation infrastructure and direct hospital formulary relationships.
Pricing Analysis
Volume-discount tiering structures separate orphan-drug premium positioning from standard wound-care procurement, with three-tier pricing stratification across lyophilized biologics, ready-to-use injections, and bulk powder compounding grades. ISO 13485 certification tier and captive API production anchor price differentiation between integrated sponsors and finished-dose partners. Pricing pressure stems from hospital procurement consolidation into bundled wound-care contracts with committed volume obligations. Academic medical centers exhibit lowest price sensitivity due to formulary stickiness, while ambulatory surgery centers face acute cost compression from quarterly reimbursement windows.
Supply Chain Analysis
Extended payment terms from United States academic medical centers and supply-chain finance facilities through German hospital networks are reshaping working capital requirements for contract manufacturing organizations. Fermentation capacity clusters in the United States, Germany, and Japan, with active pharmaceutical ingredient production drawing from Clostridium histolyticum culture media, specialized bioreactor systems, and cold-chain packaging materials. Single-source vulnerability concentrates risk around North American CMO qualification timelines. Distribution runs through integrated logistics providers with dedicated temperature-monitoring infrastructure serving hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens across wound-care biologics as hospital procurement departments displace multi-vendor spot purchasing with framework agreements, creating niches for suppliers with differentiated cold-chain capabilities or captive fermentation scale.
For Market Incumbents: Pre-empt biosimilar entry by securing backward integration into fermentation capacity and deepening ISO 13485 certification moats. Lock in three-year committed volume contracts with United States academic medical centers before CMS reimbursement decisions shift procurement leverage. Channel control through dedicated distribution infrastructure represents the critical defensive lever against finished-dose partners seeking direct hospital relationships.
For New Entrants and Emerging Players: Pursue white-space expansion in Japanese urology centers where Peyronie's disease diagnosis rates trail Western benchmarks, and Brazilian dermatology clinics driving off-label cellulite demand outside public reimbursement frameworks. The most penetrable segment lies in topical gel formulations for nursing facility wound care with minimal preparation overhead. Go-to-market execution should anchor on partnerships with regional cold-chain logistics specialists rather than captive infrastructure buildout.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap pharmaceutical parents with orphan-drug infrastructure but subscale wound-care commercialization. Long-term viability across the analysis window hinges on regulatory affairs capacity and hospital formulary positioning rather than manufacturing scale alone. The signal to monitor is PMDA reimbursement pathway maturation for Peyronie's disease interventions in Japan, which would validate expansion economics for platform sponsors.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Orphan Drug Designation Pursuit | Seven-year exclusivity for Dupuytren's contracture anchors manufacturer commitment and pricing power. |
| EMA Advanced Therapy Pathway Engagement | Centralized marketing authorization accelerates scientific advice timelines for novel fibrotic indications. |
| Integrated Cold-Chain Logistics Partnership | Embedded temperature-logging sensors and blockchain custody records satisfy German hospital network mandates. |
| Combination Delivery System Development | Hyaluronidase co-formulations enable deeper tissue penetration for retracted cord presentations in hand surgery. |
| ISO 13485 CMO Qualification Investment | Eighteen-to-twenty-four month certification timelines constrain competitor capacity expansion and protect incumbent position. |
Methodological Framework
A spread of perspectives from hospital procurement managers, formulary directors, regulatory affairs leads at orphan-drug sponsors, and contract manufacturing organization executives converged on the working assumptions. Secondary validation drew from FDA orphan drug designation filings, EMA centralized marketing authorization submissions, ClinicalTrials.gov protocol registries, and CMS reimbursement code databases. Bottom-up demand modeling across formulation types, end-user settings, and application areas triangulated against top-down market sizing from fermentation capacity and hospital procurement spend patterns.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning lyophilized versus liquid formulations, hospital versus outpatient facility procurement channels, and fasciitis treatment versus chronic wound care applications. CAGRs emerged from patient population epidemiology, procedure volume trajectories, and pricing evolution assumptions. Forecast inputs incorporated PMDA reimbursement pathway maturation timelines for Peyronie's disease in Japan and evolving CMS coverage determinations for enzymatic debridement protocols.
Sensitivities concentrate around biosimilar development program announcements, fermentation capacity expansion decisions by North American CMOs, and regulatory harmonization shifts affecting combination product classification. Forecasts reflect documented assumptions regarding orphan drug exclusivity duration and hospital procurement consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Mucosolvan (Ambroxol) Market
Pharmaceuticals
Global Antipyretic Drugs for Children Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Global Autoimmune Drugs Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
North America Analgesics Market